
 Sialendoscopes Market | 2026-2036
Sialendoscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Sialendoscopes Market Analytics
German precision instrument manufacturing is consolidating around advanced endoscopy supply chains. Olympus Corporation leverages its optical engineering heritage to sustain leadership in rigid sialendoscope design. KARL STORZ SE & Co. KG anchors its position through integrated visualization platforms for salivary duct navigation. Richard Wolf GmbH competes on specialized instrument portfolios targeting stone retrieval and ductal intervention workflows.
A sialendoscope is a miniature endoscopic instrument, typically 1.1–1.6 mm in outer diameter, designed for diagnostic and therapeutic cannulation of salivary ducts under direct visualization. Fiber optic bundles or digital sensor arrays transmit illumination and image data through semirigid or flexible shafts to enable stone extraction, stricture dilation, and biopsy collection. Flexible sialendoscopes command premium positioning due to superior navigation of tortuous ductal anatomy, while rigid variants dominate procedural throughput in high-volume hospital settings. Digital technology segments are displacing fiber optic platforms as CMOS sensor miniaturization improves image fidelity at sub-2mm diameters.
The FDA 510(k) pathway governs US market entry for sialendoscopes as Class II medical devices, while the EU MDR and CE marking framework impose strengthened clinical evidence requirements for reusable instruments. Japan's PMDA maintains distinct quality system expectations that shape export certification strategies for manufacturers targeting Asian markets. Stakeholders must monitor evolving sterilization validation standards and reimbursement code granularity for outpatient sialendoscopy procedures.
Market Dynamics
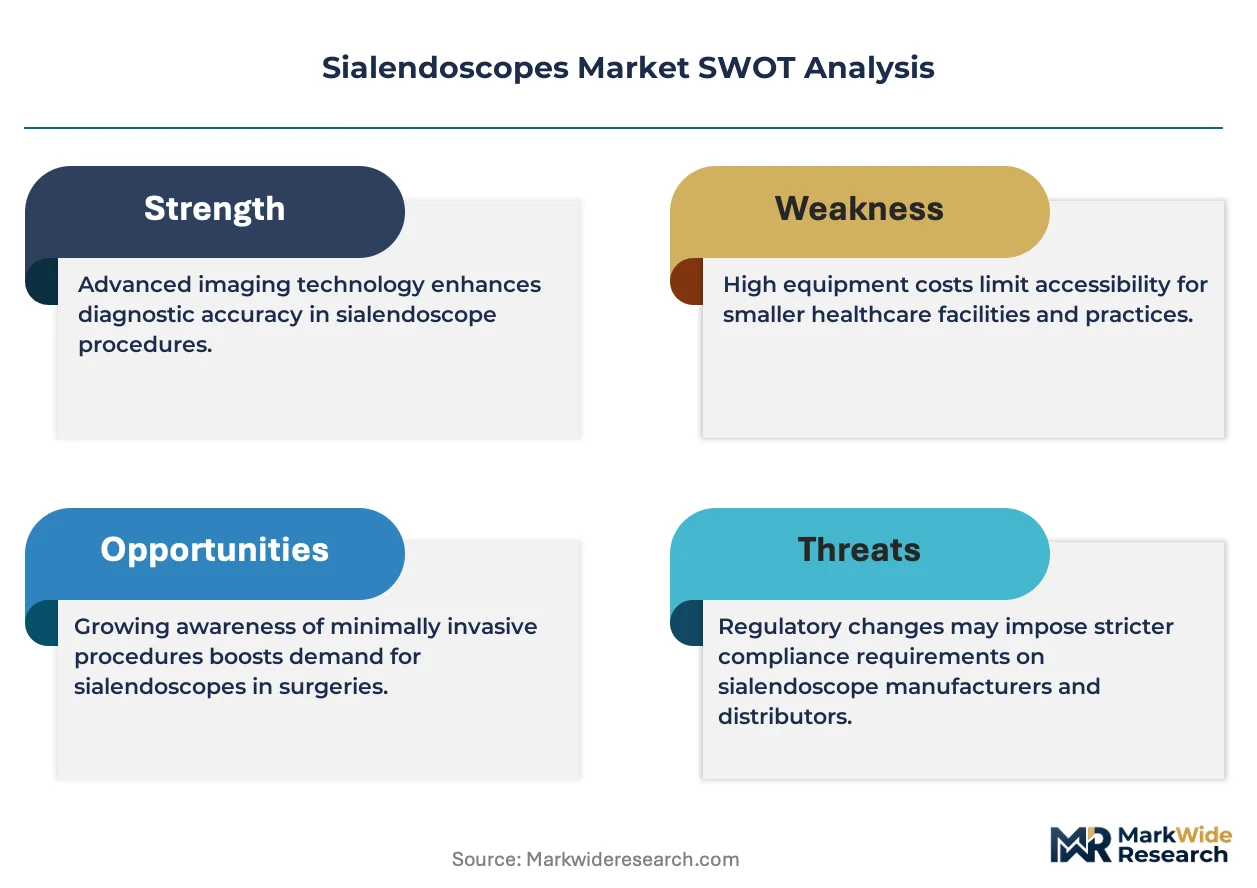
The EU Medical Device Regulation's tightened clinical evidence requirements for reusable endoscopic instruments is compressing product development timelines and forcing manufacturers to consolidate sterilization validation capabilities.
Growth Catalysts
- Ambulatory surgical centers:These facilities are expanding minimally invasive salivary procedures due to favorable reimbursement codes for outpatient sialendoscopy.
- CMOS sensor miniaturization:Digital imaging arrays now achieve sub-2mm diameters with superior fidelity, accelerating displacement of fiber optic bundles in new system deployments.
- German outpatient volumes:Rising procedural throughput in Germany's ambulatory settings concentrates demand for rigid sialendoscope configurations optimized for high-frequency use.
Market Restraints
- EU MDR compliance costs:Strengthened clinical evidence requirements for reusable instruments impose substantial documentation burdens on manufacturers with legacy product portfolios.
- Specialized technician scarcity:Salivary duct navigation requires trained endoscopists with otolaryngology subspecialization, limiting addressable procedure volumes in secondary care settings.
- Single-use alternatives:Disposable bronchoscopes and ureteroscopes from adjacent endoscopy markets threaten to capture price-sensitive buyers seeking simplified reprocessing workflows.
Strategic Opportunities
- Japan PMDA certification:Export-oriented manufacturers can access premium Asian markets by meeting distinct quality system expectations for visualization platforms.
- Flexible-digital convergence:Combining CMOS sensors with torque-stable flexible shafts enables navigation of tortuous submandibular anatomy previously requiring rigid instrumentation.
- Stone retrieval workflow integration:Bundled instrument portfolios combining sialendoscopes with lithotripters and retrieval baskets capture higher per-procedure revenue in hospital purchasing.
Industry Challenges
- Reprocessing validation timelines:Sterilization protocol documentation for complex luminal instruments delays EU MDR certification cycles by 12-18 months.
- Cross-platform visualization compatibility:Proprietary camera control units from dominant endoscopy manufacturers fragment interoperability standards for third-party sialendoscope attachments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sialendoscopes Market |
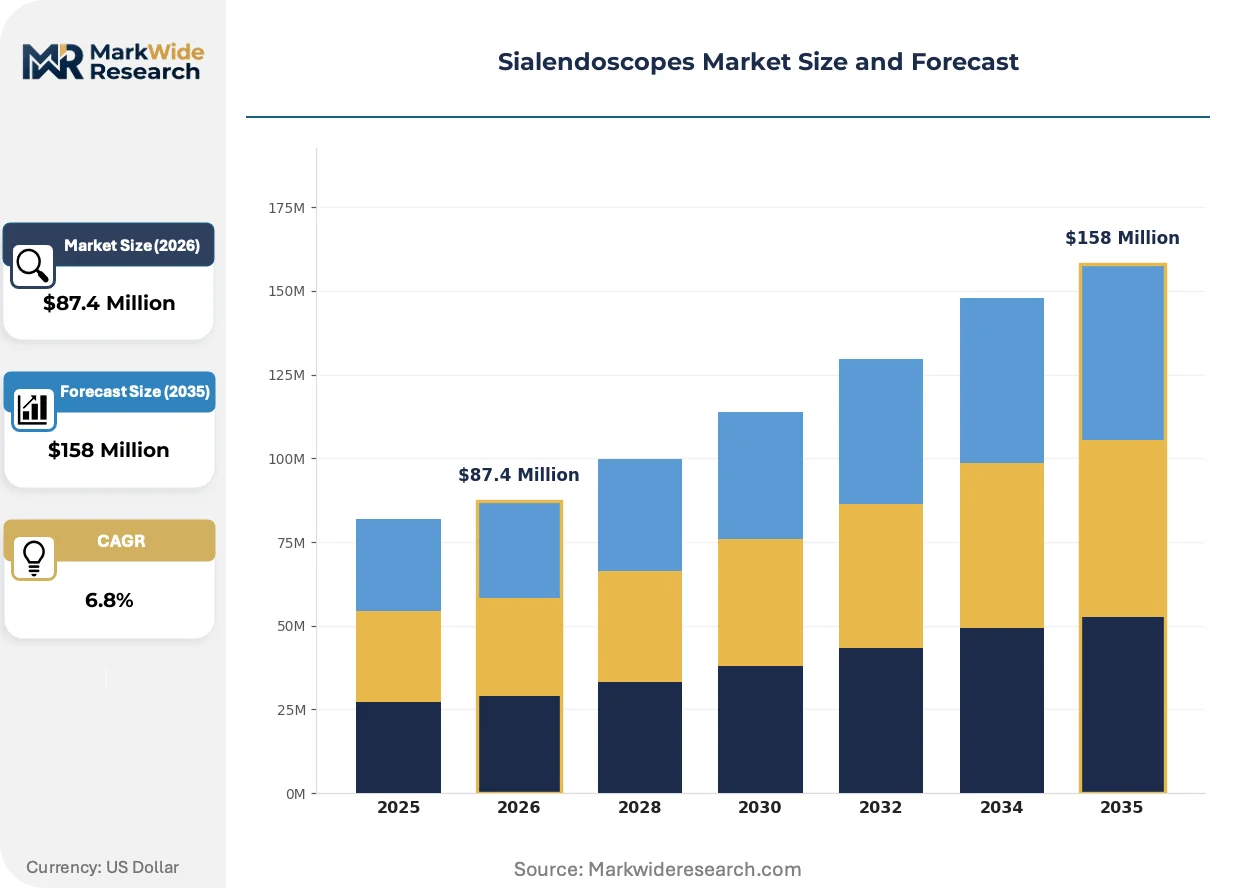
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Sialendoscopes, Flexible Sialendoscopes, Accessories, Consumables End User: Hospitals, Specialty Clinics, Ambulatory Surgical Centers, Research Institutions Application: Salivary Gland Disorders, Stone Removal, Biopsy, Ductal Strictures Technology: Fiber Optic, Digital, Wireless, Standard |
| Companies Covered | HOYA Corporation, Stryker Corporation, Olympus Corporation, Medtronic plc, Boston Scientific Corporation, Fujifilm Holdings Corporation, Richard Wolf GmbH, Smith & Nephew plc, KARL STORZ SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sialendoscopes Market Evolving Landscape
Digital sensor technology is restructuring competitive advantage around image processing capabilities rather than optical component craftsmanship. Three developments are compressing product lifecycles and reshaping procurement criteria.
CMOS-based digital sialendoscopes is overtaking fiber optic platforms in premium system configurations. Academic medical centers in Germany and the United States are prioritizing digital acquisition for their superior low-light performance and reduced maintenance requirements. This transition compresses residual value for installed fiber optic bases and accelerates capital replacement cycles.
EU MDR Article 10 post-market surveillance obligations now mandate systematic clinical follow-up for reusable instruments. Manufacturers must establish traceability systems linking specific device units to patient outcomes across multi-year horizons. German and French hospital procurement departments are prioritizing suppliers with demonstrated vigilance reporting capabilities.
Buying committees are consolidating vendor relationships around integrated visualization ecosystems rather than standalone instruments. Hospital systems in Bavaria and North Rhine-Westphalia now require sialendoscope compatibility with existing tower infrastructure as a mandatory tender condition. This specification pattern favors manufacturers with broad endoscopy portfolios over specialized instrument developers.
Sialendoscopes Market Segmentation
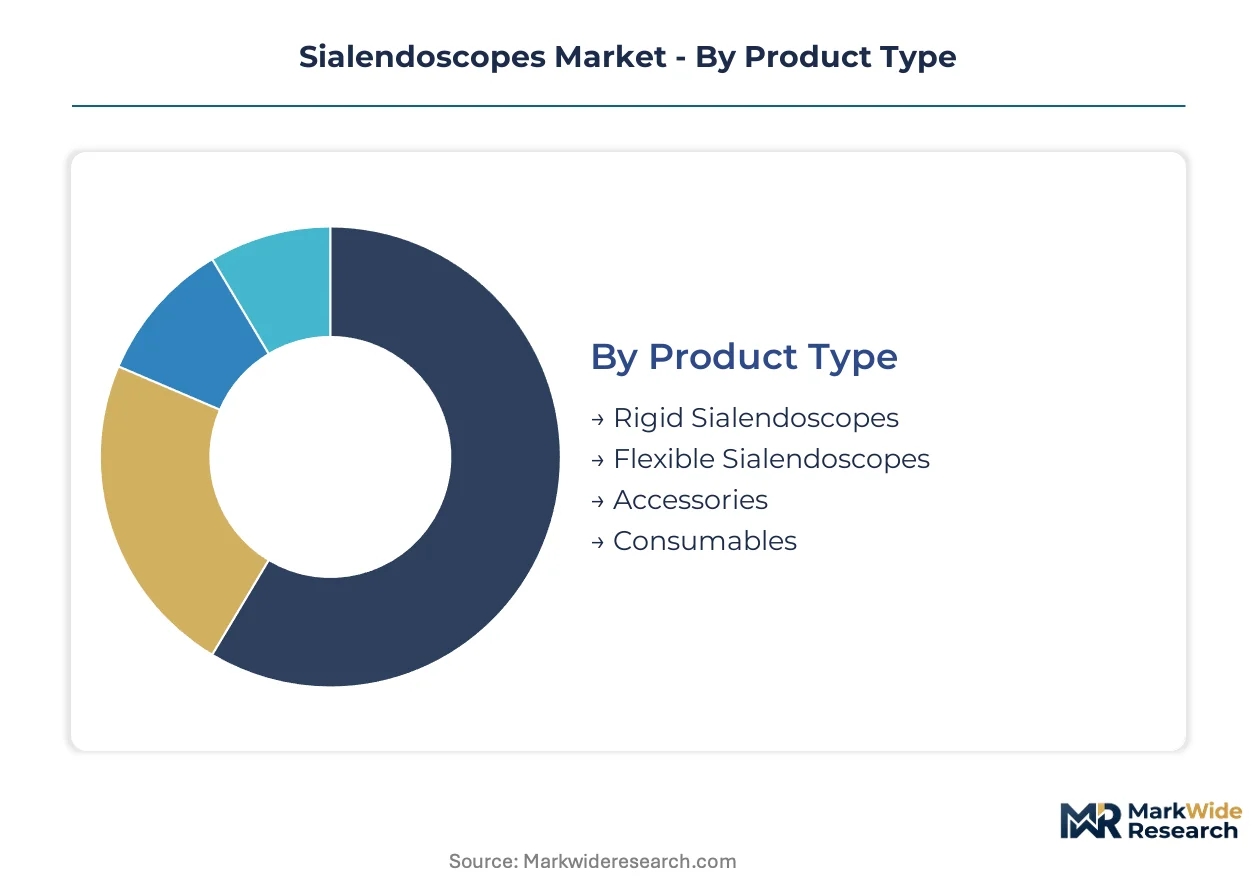
Sialendoscope procurement decisions hinge on procedural setting, anatomical complexity, and visualization technology maturity. Each segmentation dimension reveals distinct purchasing hierarchies between high-volume hospital systems and specialized ambulatory operators.
Product Type:
Rigid configurations dominate standalone procedural workflows, while flexible variants embed into integrated navigation platforms requiring tower compatibility.
- Rigid Sialendoscopes:Semirigid stainless steel shafts with fixed optics deliver superior durability for high-frequency stone extraction procedures. German outpatient centers in Bavaria and North Rhine-Westphalia concentrate procurement of these configurations for submandibular duct interventions where straight-line access predominates.
- Flexible Sialendoscopes:Torque-stable polymer shafts with active tip deflection navigate tortuous parotid anatomy unreachable by rigid instrumentation. Academic medical centers in the United States prioritize these for diagnostic sialendoscopy where ductal tortuosity demands steerable visualization.
- Accessories:Lithotripters, retrieval baskets, and dilation balloons complete therapeutic workflows.
- Consumables:Single-use sheaths and irrigation tubing reduce cross-contamination risks in high-throughput settings.
Rigid sialendoscopes lead volumes today; flexible variants are gaining share fastest.
End User:
Procurement authority concentrates differently across facility types, with reimbursement codes shaping capital allocation priorities.
- Hospitals:Integrated tower infrastructure and dedicated ENT departments support complex bilateral procedures. Tertiary centers in Germany maintain highest per-facility instrument counts due to subspecialist concentration and research mandates.
- Ambulatory Surgical Centers:Streamlined reprocessing protocols and favorable outpatient reimbursement accelerate adoption of disposable-compatible platforms. These facilities in the United States show steepest expansion trajectory for minimally invasive salivary procedures.
- Specialty Clinics:Otolaryngology-focused practices balance diagnostic throughput against capital constraints.
- Research Institutions:Academic medical centers drive early evaluation of CMOS-based digital platforms before commercial deployment.
Hospitals retain the largest installed base; ambulatory surgical centers are expanding most quickly.
Application:
Clinical indication determines instrument specification, with therapeutic interventions commanding premium configurations over diagnostic screening.
- Stone Removal:Therapeutic sialendoscopy for sialolithiasis requires integrated lithotripsy and retrieval capabilities. German procedural volumes concentrate here due to dietary prevalence patterns and established outpatient reimbursement pathways.
- Salivary Gland Disorders:Diagnostic evaluation of chronic sialadenitis and autoimmune conditions drives flexible platform demand. United States academic centers prioritize these workflows for resident training and research protocol enrollment.
- Biopsy:Tissue sampling mandates compatible forceps channels and histological handling protocols.
- Ductal Strictures:Balloon dilation procedures require graduated sizing and pressure monitoring integration.
Stone removal dominates current procedure mix; salivary gland disorder evaluation is climbing the fastest.
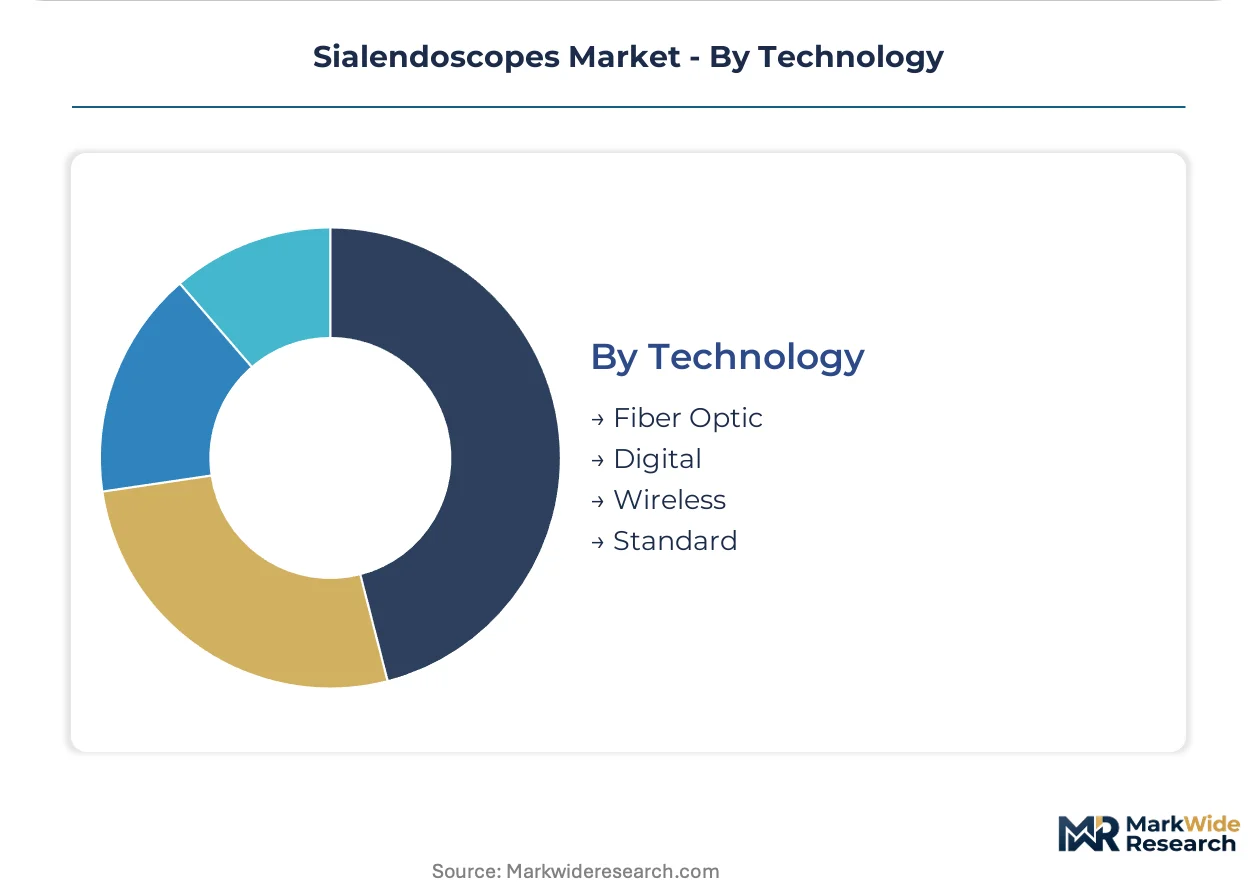
Technology:
Imaging modality selection reflects the transition from optical craftsmanship to digital signal processing capabilities.
- Digital:CMOS sensor arrays at sub-2mm diameters deliver superior low-light performance and eliminate fiber bundle degradation. German and United States hospital systems prioritize these for reduced maintenance and enhanced image fidelity in academic settings.
- Fiber Optic:Traditional quartz fiber bundles maintain residual presence in price-sensitive secondary markets and legacy system compatibility requirements.
- Wireless:Eliminated tethering between instrument head and camera control unit enables ergonomic improvements in compact procedure rooms.
- Standard:Unspecified or hybrid configurations serve transitional installations and budget-constrained procurement cycles.
Digital technology leads current installations; wireless platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are migrating sterilization validation and clinical documentation functions toward jurisdictions with established regulatory harmonization, compressing development timelines for reusable endoscopic instruments. The EU MDR's tightened evidence requirements have concentrated compliance expertise in Germany and Switzerland, while Asian regulators maintain distinct pathways that reward early quality system investments.
United States
Ambulatory surgical centers in Texas and Florida are expanding sialendoscopy volumes fastest, drawn by favorable CMS reimbursement codes for outpatient salivary procedures. The FDA's 510(k) pathway for Class II devices maintains predictable review timelines compared with EU counterparts. Academic medical clusters in Boston and the Research Triangle drive early adoption of CMOS-based digital platforms before commercial scale-up.
Germany
Bavarian outpatient centers concentrate procurement of rigid sialendoscope configurations optimized for high-frequency submandibular interventions. The EU MDR's post-market surveillance obligations under Article 10 mandate systematic clinical follow-up, favoring suppliers with established vigilance reporting systems. Precision instrument manufacturing clusters in Tuttlingen and Berlin-Brandenburg consolidate sterilization validation capabilities to compress certification cycles.
Japan
PMDA quality system expectations for visualization platforms shape export certification strategies for manufacturers targeting premium Asian markets. Tokyo and Osaka academic medical centers prioritize digital imaging arrays for resident training protocols. The Kanto region's endoscopy supply chains are integrating CMOS sensor miniaturization capabilities from adjacent consumer electronics industries.
United Kingdom
NHS procurement frameworks are consolidating vendor relationships around integrated visualization ecosystems rather than standalone instruments. London and Southeast hospital systems require sialendoscope compatibility with existing tower infrastructure as mandatory tender conditions. The Medicines and Healthcare products Regulatory Agency's alignment with EU MDR standards simplifies dual-market certification for manufacturers.
China
NMPA registration pathways for reusable endoscopic instruments are lengthening as domestic quality benchmarks converge with international standards. Yangtze River Delta medical device clusters in Shanghai and Suzhou are building sterilization validation capabilities to serve both domestic and export markets. Tertiary hospitals in Beijing and Guangzhou are piloting digital sialendoscope platforms through research protocol exemptions.
Sialendoscopes Market Competitive Landscape
German precision instrument fabricators anchor one tier through integrated visualization platforms; Japanese optical engineering specialists hold another through fiber optic heritage and CMOS sensor integration. Market structure concentrates around three to five dominant tower-system providers with broad endoscopy portfolios, while specialized instrument developers compete on stone retrieval workflow bundles. Two strategic archetypes predominate: diversified medtech conglomerates leveraging cross-selling infrastructure, and focused endoscopy pure-plays defending position through subspecialist relationships. Competitive moves center on sterilization validation capability consolidation and tower compatibility certification to capture hospital procurement committee specifications.
Among Germany-based fabricators, KARL STORZ SE & Co. KG and Richard Wolf GmbH exemplify the focused endoscopy archetype, occupying positions within salivary duct navigation and lithotripsy workflow integration respectively. Olympus Corporation represents the diversified optical engineering tier, leveraging heritage in rigid endoscope design across multiple anatomical applications. These three entities collectively illustrate how geographic concentration of precision manufacturing expertise translates into procurement specification influence within European hospital systems.
| Leading Market Players |
|---|
| HOYA Corporation |
| Stryker Corporation |
| Olympus Corporation |
| Medtronic plc |
| Boston Scientific Corporation |
| Fujifilm Holdings Corporation |
| Richard Wolf GmbH |
| Smith & Nephew plc |
| KARL STORZ SE & Co. KG |
| Others |
Value Network & Pricing Analysis
Stainless steel price indices cascade through sialendoscope manufacturing tiers, compressing margins on rigid instrument configurations while amplifying premiums for CMOS-integrated flexible platforms. German precision fabricators pass alloy cost volatility into three-tier pricing structures across premium, standard, and economy levels, with hospital procurement committees capturing volume discounts that ambulatory surgical centers cannot match.
Pricing Analysis
Distributor margins on tower-compatible sialendoscope systems absorb 15-25 percent of manufacturer list prices before hospital purchasing committees negotiate further reductions. Pricing stratifies across premium, standard, and economy tiers based on CMOS sensor resolution grades and EU MDR certification completeness, with fiber optic legacy platforms facing accelerated price erosion as academic medical centers prioritize digital acquisition. Cost compression in mid-tier configurations intensifies because single-use endoscope alternatives from adjacent markets capture price-sensitive buyers seeking simplified reprocessing workflows. Ambulatory surgical centers exhibit highest price sensitivity due to capital constraints, while German tertiary hospitals with research mandates demonstrate lowest sensitivity when bundled with lithotripsy workflow integration.
Supply Chain Analysis
Regional distribution centers in Tuttlingen, Berlin-Brandenburg, and Tokyo anchor hub-and-spoke patterns for precision instrument fulfillment into European and Asian hospital systems. Manufacturing concentration in Germany, Japan, and Switzerland draws from specialized optical glass, CMOS sensor arrays, and medical-grade stainless steel feedstocks. Single-source vulnerability in sub-2mm CMOS sensor supply creates exposure should semiconductor foundry capacity tighten. Distribution runs through manufacturer-direct hospital contracts in Germany, specialized medical device distributors in the United States, and layered importer networks across Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sialendoscope manufacturing hinges on CMOS sensor cost curves flattening faster than fiber optic bundle degradation, enabling premium-tier shifts without proportional bill-of-material increases.
For Market Incumbents: Hedge against single-use endoscope encroachment by consolidating sterilization validation capabilities in Tuttlingen and Berlin-Brandenburg to compress EU MDR certification cycles. Anchor hospital procurement relationships through tower compatibility certification, as Bavarian and North Rhine-Westphalia systems now mandate integrated visualization ecosystems as tender conditions. Backward integration into CMOS sensor sourcing reduces exposure to semiconductor foundry allocation constraints. For New Entrants and Emerging Players: Wireless sialendoscope platforms eliminating tethered camera control units offer the most penetrable wedge for compact ambulatory surgical center installations where ergonomic constraints dominate purchasing criteria. Target United States outpatient facilities in Texas and Florida where CMS reimbursement codes favor minimally invasive salivary procedures and incumbent tower compatibility requirements remain less entrenched than in German hospital systems. Pursue FDA 510(k) pathway entry before EU MDR clinical evidence burdens to establish revenue base for subsequent European expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where sterilization validation expertise concentrates in jurisdictions with established EU MDR compliance infrastructure. The sialendoscope segment offers 5-10 year viability framed by outpatient procedure migration and digital imaging displacement of fiber optic platforms. Acquisition target archetypes include specialized lithotripsy workflow developers with proven hospital purchasing committee relationships and demonstrated vigilance reporting capabilities under Article 10. Monitor PMDA quality system investment announcements as inflection indicator for premium Asian market access strategies.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Article 10 compliance compresses certification timelines for reusable instruments by 12-18 months. |
| Hospital System Partnership | Bavarian and North Rhine-Westphalia procurement committees mandate tower compatibility as tender condition. |
| Software Companion Development | Image processing algorithms for CMOS-based platforms differentiate premium configurations from fiber optic legacy systems. |
| Reimbursement Strategy | CMS outpatient codes in Texas and Florida accelerate ambulatory surgical center adoption of minimally invasive procedures. |
| FDA Submission Prioritization | 510(k) Class II pathway offers predictable review timelines compared with EU MDR clinical evidence requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ENT department heads, hospital purchasing committee members, biomedical engineers specializing in endoscope maintenance, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR vigilance databases, hospital procurement records, and CMS reimbursement code updates. Bottom-up instrumentation counts by facility type triangulated against top-down manufacturer shipment estimates.
Segment-weighting approaches applied product type, end user category, clinical application, and imaging technology dimensions across the analysis window. CAGRs derived from procedural volume trajectories in ambulatory versus hospital settings, technology displacement curves for CMOS versus fiber optic platforms, and reimbursement code expansion patterns. Forecast inputs incorporated EU MDR compliance cost pass-through assumptions and PMDA certification timeline differentials for Asian market entry.
The model holds under stable regulatory harmonization between EU MDR and notified body capacity; deviation in sterilization validation standard stringency or semiconductor foundry allocation constraints would shift replacement cycle assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pacemaker/Defibrillator Lead Extraction Kits Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
General Surgery Devices Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
Global Auto-Injectors Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Breast Localization System Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Global Medical Composite Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Global Gait Analysis System Market
Medical Devices
Endodontic Devices Market