
 Food and Grocery Retail Market | 2026-2036
Food and Grocery Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Grocery Retail Market Intelligence
Asset-light franchising and sale-leaseback programs is rewriting competitive entry barriers across food and grocery retail. ALDI leverages its hard-discount private-label model to sustain margin compression that rivals struggle to match. Walmart anchors North American grocery volume through backward integration into distribution and captive supply of perishables. Kroger differentiates via technology leadership in automated fulfillment centers that reduce last-mile costs.
Food and grocery retail encompasses the procurement, storage, display, and sale of consumable goods through physical and digital channels, with cold-chain maintenance for temperature-sensitive categories such as dairy and frozen foods serving as a critical operational parameter. Supermarkets dominate value capture in developed economies, while discount stores occupy the fastest-expanding format tier in price-sensitive markets. Online retail is reshaping fulfillment architecture, and fresh produce commands the highest margin pool per square foot due to spoilage risk and sourcing complexity.
The FDA enforces food safety standards under the Food Safety Modernization Act, while the USDA regulates organic labeling and agricultural supply integrity. The EU Green Deal's packaging mandates and REACH chemical restrictions shape cross-border product standards and market access conditions. Stakeholders must monitor how dual carbon goals in China and the EU AI Act's algorithmic transparency requirements will reshape automated pricing and inventory systems.
Market Dynamics
Food and grocery retail is restructuring around cold-chain digitization and last-mile fulfillment density, as spoilage economics and labor scarcity force capital reallocation from front-of-store experience to back-of-house automation.
Growth Catalysts
- EU Green Deal packaging mandates:Reusable and recyclable material requirements are accelerating supplier consolidation toward certified packaging providers capable of multi-retailer compliance.
- Home delivery integration:Urban Chinese consumers are consolidating weekly shopping into app-coordinated fresh produce delivery slots, raising basket values and reducing store traffic volatility.
- Automated fulfillment centers:Kroger and Walmart deployments of robotic picking systems for ambient and chilled goods are compressing order-to-door timelines below two hours in dense metropolitan zones.
Market Restraints
- Perishable input cost volatility:Fresh produce and protein prices swing with climate-driven harvest disruptions, compressing gross margins for retailers lacking backward integration into agricultural supply.
- Supply concentration in cold-chain logistics:Third-party refrigerated transport providers cluster in coastal China and the US Midwest, creating bottleneck risk during peak demand windows.
- Labor scarcity in last-mile delivery:Gig-economy driver availability limits same-day service expansion regardless of capital deployment.
Strategic Opportunities
- India's FSSAI modernization:Streamlined food safety certification timelines are opening organized retail penetration in tier-two cities previously served by fragmented kirana networks.
- Dark store micro-fulfillment:Abandoned urban retail spaces in Germany and France are converting to automated picking hubs serving 3-5 kilometer delivery radii.
- AI-driven dynamic pricing convergence:Machine learning inventory systems combined with real-time spoilage forecasting enable margin recovery on near-expiry fresh categories.
Industry Challenges
- Cold-chain technician scarcity:Refrigeration system maintenance and HVAC-R certification gaps delay automated warehouse commissioning in secondary US markets.
- Legacy POS integration friction:Real-time inventory visibility across e-commerce and physical shelves requires middleware development that strains IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Grocery Retail Market |
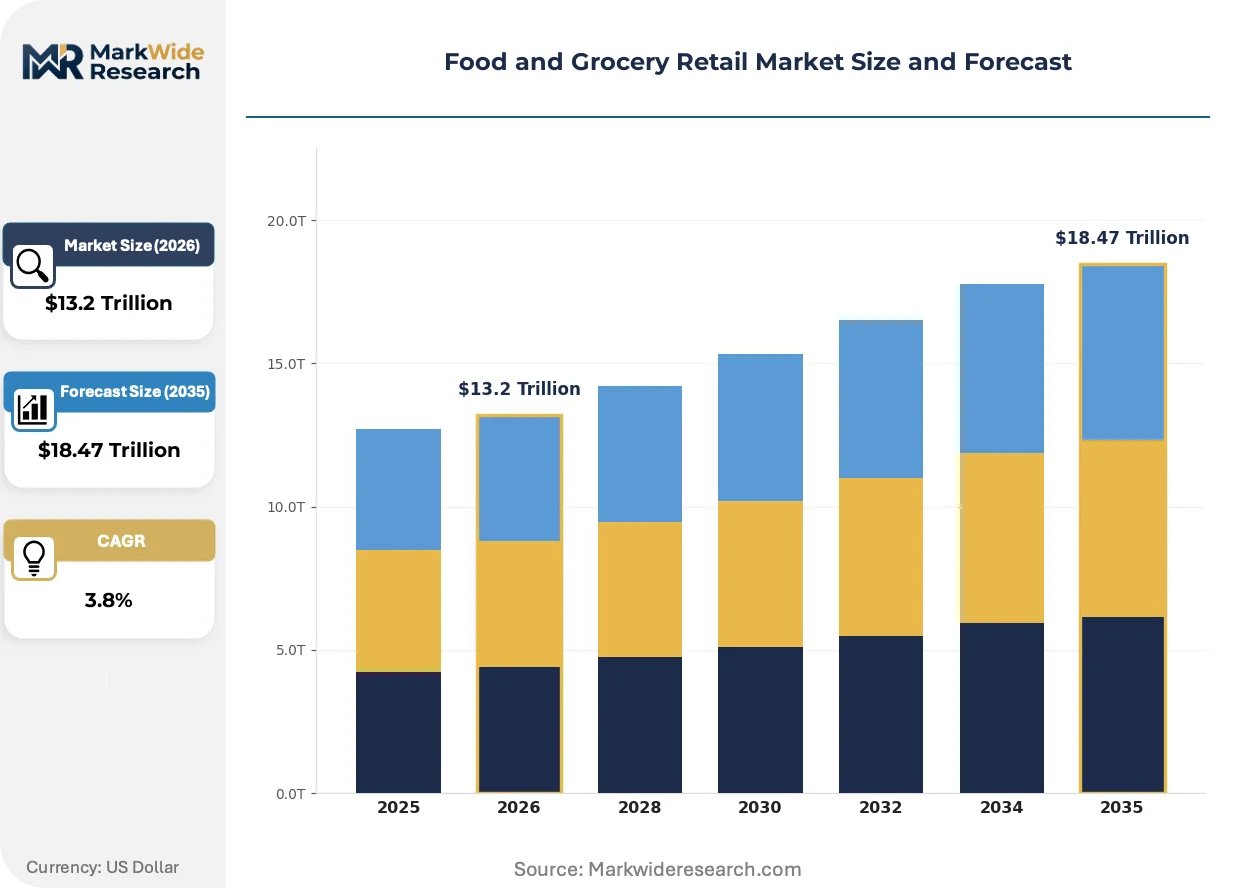
| Market Size in 2026 | $13.2 Trillion |
| Market Size in 2035 | $18.47 Trillion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Store Format: Supermarkets, Hypermarkets, Convenience Stores, Specialty Food Stores, Discount Stores Product Category: Fresh Produce, Packaged Foods, Beverages, Bakery, Dairy Products, Frozen Foods Sales Channel: In-Store, Online Retail, Mobile Commerce, Home Delivery, Click & Collect Customer Segment: Urban Consumers, Suburban Households, Rural Buyers, Students, Working Professionals |
| Companies Covered | Albertsons Companies, ALDI, Walmart, Target, Amazon, Kroger, Ahold Delhaize, Publix, Costco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Grocery Retail Market Strategic Shifts & Innovations
Retailers are rearchitecting store footprints around fulfillment rather than browsing, with capital flowing from merchandising displays to temperature-controlled backroom automation and localized inventory positioning.
Computer vision shelf-monitoring systems are migrating from pilot installations in Amazon Fresh and Carrefour locations to standard equipment in mid-tier European supermarkets. These systems reduce out-of-stock rates on high-velocity packaged goods by triggering automated replenishment orders before shelf depletion. Labor hours previously allocated to manual stock checks are redeploying to customer-facing fresh preparation counters.
The EU AI Act's algorithmic transparency requirements are forcing retailers to document decision logic in automated pricing and promotion engines. Compliance investments are concentrating in German and French headquarters where AI-driven loyalty programs originated. Operators must now maintain explainable audit trails for dynamic markdowns on perishable categories, raising system architecture costs.
Chinese urban households are fragmenting weekly grocery trips into multiple smaller orders coordinated through super-app interfaces. This pattern concentrates demand in morning and evening delivery windows, requiring retailers to overbuild chilled staging capacity relative to average hourly volume. Fresh produce sourcing is regionalizing to reduce transit time from farm to fulfillment center.
Food and Grocery Retail Market Segmentation
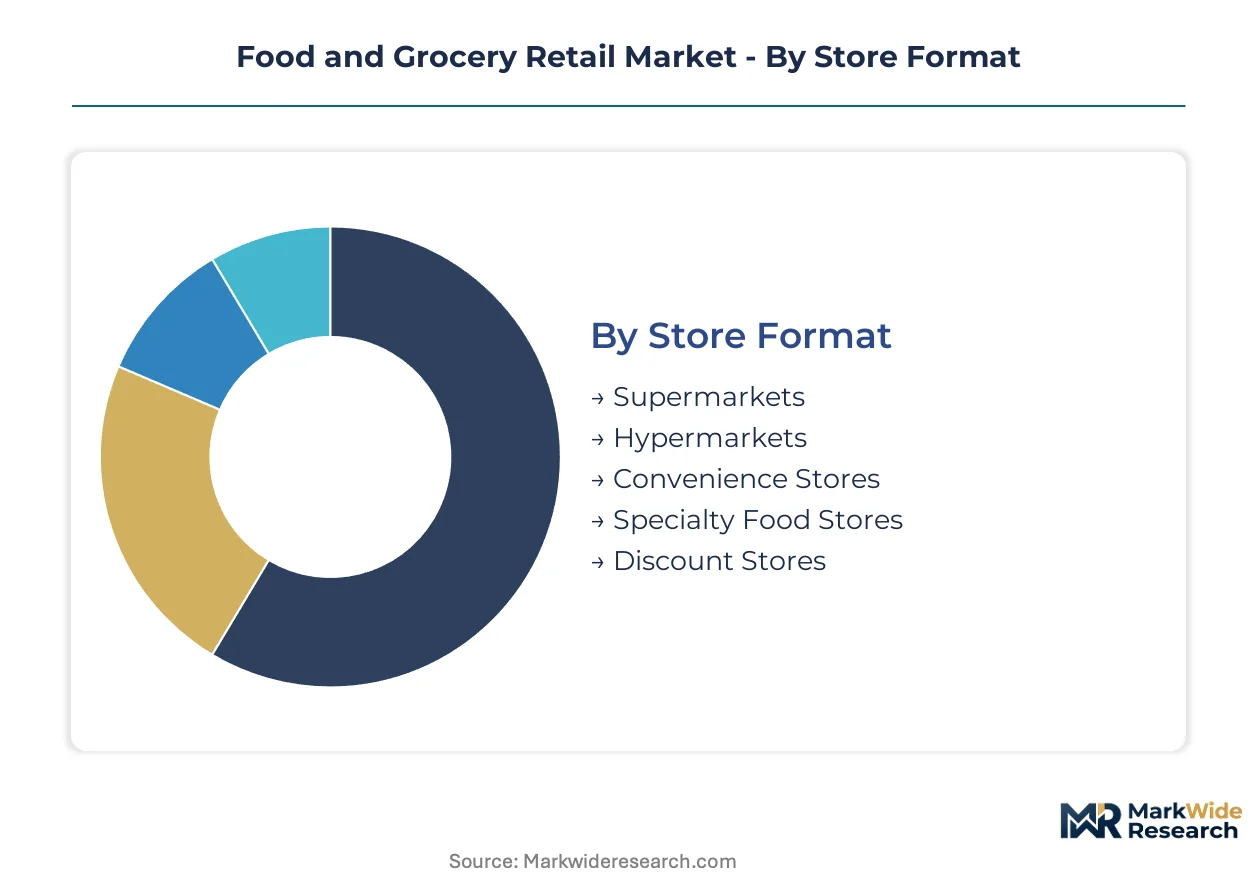
Food and grocery retail segmentation reveals how operational complexity and service intensity vary dramatically across format, product, and channel combinations. Each dimension carries distinct cold-chain requirements, margin profiles, and capital deployment patterns that shape competitive positioning.
Store Format:
After-sales service intensity escalates with format scale, as larger footprints demand more sophisticated refrigeration maintenance and loyalty program management.
- Supermarkets:Mid-size formats averaging 2,000-5,000 square meters balance SKU breadth with manageable cold-chain complexity. Urban Chinese consumers and North American suburban households drive demand for one-stop fresh produce and prepared meal sections.
- Hypermarkets:Massive retail complexes exceeding 10,000 square meters integrate general merchandise with grocery, requiring multi-zone temperature control and dedicated HVAC-R technician contracts. Labor scarcity in secondary US markets limits expansion beyond coastal corridors.
- Convenience Stores:Compact 100-300 square meter formats prioritize ambient packaged goods and limited chilled beverages. 24-hour operations in Japan and South Korea sustain premium pricing on emergency purchases.
- Specialty Food Stores:Curated assortments of organic, ethnic, or artisanal products with minimal cold-chain infrastructure. Certification requirements under USDA organic labeling and EU Green Deal packaging mandates elevate compliance costs.
- Discount Stores:Hard-discount models emphasizing private-label packaged goods with stripped-back service levels. ALDI's European footprint demonstrates margin sustainability through limited SKU counts and efficient inventory turns.
Supermarkets hold the largest share; momentum sits with discount stores as price-sensitive markets expand.
Product Category:
Margin structure varies inversely with spoilage risk, creating tiered investment requirements across temperature-controlled and ambient segments.
- Fresh Produce:Fruits and vegetables commanding the highest margin pool per square foot due to sourcing complexity and rapid deterioration. Regional farm networks in China and California's Central Valley concentrate supply.
- Packaged Foods:Shelf-stable goods with extended dating enable centralized distribution and reduced waste. Working professionals in dense metropolitan zones favor convenience-oriented ready meals and snack formats.
- Beverages:Ambient and chilled drinks spanning water, carbonated soft drinks, juices, and functional beverages. Deposit return schemes under EU Green Deal directives reshape packaging material selection.
- Bakery:In-store and central kitchen production of bread, pastries, and cakes with short shelf lives. German and French consumers sustain demand for artisanal preparation counters.
- Dairy Products:Milk, cheese, yogurt, and butter requiring continuous cold-chain maintenance from processor to display case. FDA Food Safety Modernization Act traceability rules elevate record-keeping burdens.
- Frozen Foods:Ice cream, prepared meals, and vegetables held at -18°C throughout distribution. Energy costs and F-Gas Regulation compliance in Europe constrain warehouse expansion economics.
Fresh produce generates the highest returns; frozen foods are gaining share fastest through meal-solution positioning.
Sales Channel:
Channel selection determines fulfillment architecture investment, with digital routes demanding entirely different cost structures than physical retail.
- In-Store:Traditional brick-and-mortar shopping with immediate product access and sensory evaluation. German and French supermarkets retain dominant volume despite digital encroachment.
- Online Retail:E-commerce platforms with home or pickup point delivery, requiring automated fulfillment centers. Kroger and Walmart deployments of robotic picking systems compress order-to-door timelines below two hours in dense US metropolitan zones.
- Mobile Commerce:Super-app interfaces integrating grocery with payment, entertainment, and social functions. Chinese urban households fragment weekly trips into multiple smaller orders coordinated through morning and evening delivery windows.
- Home Delivery:Scheduled or on-demand transport from fulfillment center to residence. Gig-economy driver availability limits same-day service expansion regardless of capital deployment.
- Click & Collect:Online ordering with physical pickup at designated locations, blending digital convenience with reduced last-mile costs. Abandoned urban retail spaces in Germany and France convert to automated picking hubs serving 3-5 kilometer radii.
In-Store retains volume leadership; mobile commerce climbs the fastest in Asia-Pacific urban corridors.
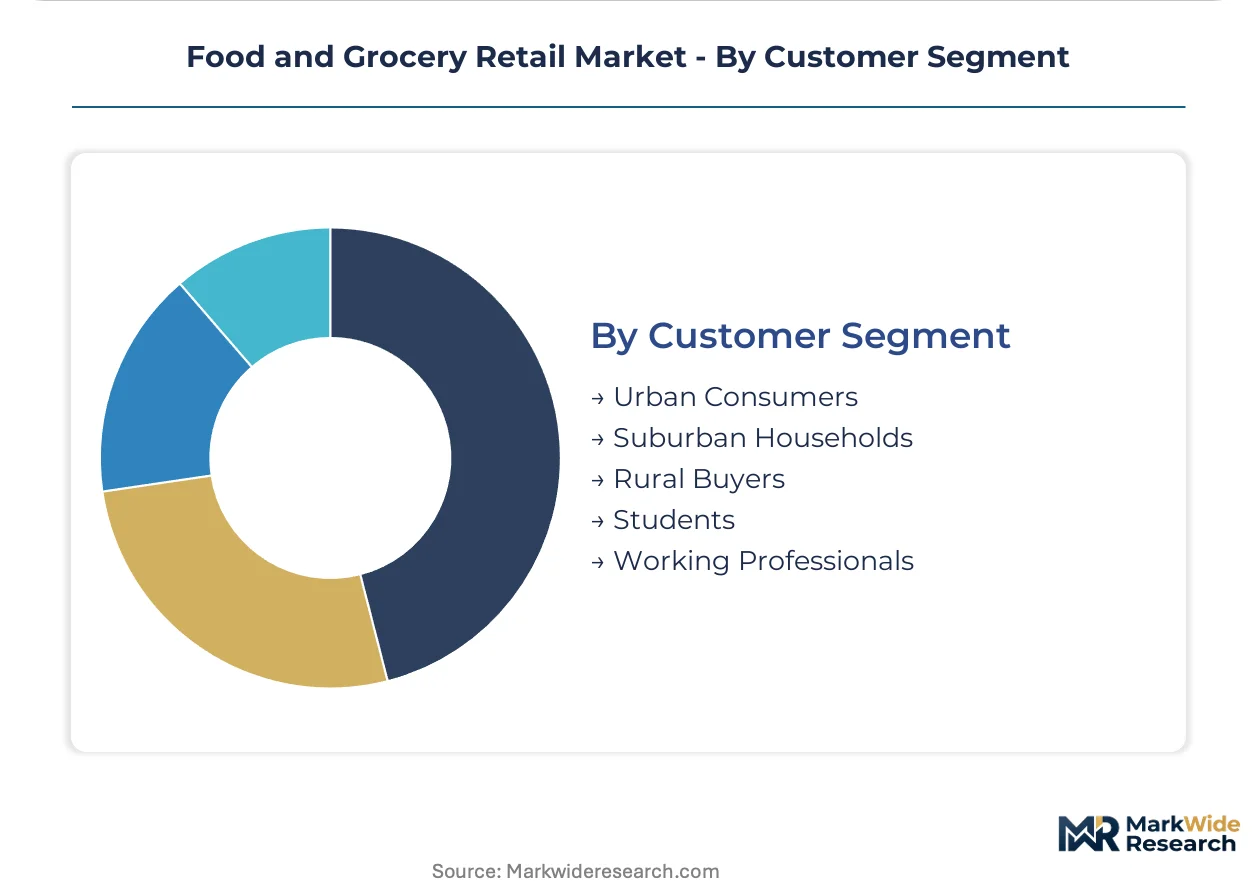
Customer Segment:
Purchasing frequency and basket composition diverge sharply across demographic and geographic customer types.
- Urban Consumers:Dense-city residents prioritizing convenience, premium fresh produce, and app-coordinated delivery slots. China's tier-one cities concentrate demand for integrated home delivery services.
- Suburban Households:Family units favoring weekly stock-up trips to supermarkets and hypermarkets with parking accessibility. US Midwest and Southeast corridors sustain large-format volume.
- Rural Buyers:Sparse-population zones served by limited-format stores with extended driving distances. India's tier-two cities present organized retail penetration opportunities as FSSAI modernization streamlines certification.
- Students:Price-sensitive younger consumers gravitating toward discount stores and convenience locations near educational institutions. Private-label acceptance runs higher in this cohort.
- Working Professionals:Time-constrained employees consolidating shopping into efficient digital channels and prepared meal solutions. EU AI Act algorithmic transparency requirements now shape automated pricing for this segment's loyalty programs.
Suburban households represent the largest customer base; working professionals drive steepest channel shift toward digital integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in German supermarkets exceeds that of Brazilian operators by a factor reflecting cold-chain infrastructure gaps and sourcing concentration differentials. This asymmetry shapes capital deployment patterns across major food and grocery retail markets.
United States
Suburban households in the Midwest and Southeast sustain large-format hypermarket volume through weekly stock-up behavior. The FDA enforces Food Safety Modernization Act traceability rules that elevate record-keeping burdens for dairy and produce suppliers. Dallas-Fort Worth anchors automated fulfillment center construction as Kroger and Walmart deploy robotic picking systems for sub-two-hour delivery windows.
China
Urban consumers in tier-one cities fragment weekly shopping into multiple smaller orders coordinated through super-app interfaces. Dual carbon goals under MEE oversight reshape cold-chain warehouse energy economics and F-gas compliance requirements. The Yangtze River Delta concentrates fresh produce regionalization efforts as retailers reduce farm-to-fulfillment-center transit times.
Germany
ALDI's hard-discount private-label model sustains margin compression that price-sensitive European consumers reward with loyalty. The EU AI Act's algorithmic transparency requirements force documentation of decision logic in automated pricing engines. Abandoned urban retail spaces in Berlin and Hamburg convert to dark store micro-fulfillment hubs serving three-to-five-kilometer delivery radii.
India
Organized retail penetration accelerates in tier-two cities as working professionals shift from fragmented kirana networks to integrated formats. FSSAI modernization streamlines food safety certification timelines and reduces compliance friction for national chains. Maharashtra and Gujarat host the densest concentration of new supermarket openings as cold-chain infrastructure extends beyond traditional metro corridors.
France
Carrefour deploys computer vision shelf-monitoring systems from pilot installations to standard mid-tier supermarket equipment. EU Green Deal packaging mandates accelerate supplier consolidation toward certified providers capable of multi-retailer compliance. The Île-de-France region dominates AI-driven loyalty program investment as headquarters compliance costs concentrate in Paris-based operations.
Food and Grocery Retail Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical positioning. The vendor base stratifies between scale-driven hard-discount operators and technology-heavy fulfillment innovators. Three archetypes dominate: backward-integrated volume leaders, asset-light franchising networks, and automated logistics specialists. Competitive moves concentrate on sale-leaseback real estate monetization and captive supply chain development.
Within the hard-discount archetype, ALDI exemplifies margin sustainability through limited SKU discipline and private-label concentration. Walmart anchors North American volume through distribution integration and perishable supply control. Kroger occupies a position within the automation tier, representing technology leadership in robotic fulfillment deployment.
| Leading Market Players |
|---|
| Albertsons Companies |
| ALDI |
| Walmart |
| Target |
| Amazon |
| Kroger |
| Ahold Delhaize |
| Publix |
| Costco |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta cold-chain corridor connects regional farm networks to urban fulfillment centers, with freight cost volatility compressing margins for retailers lacking backward integration into agricultural supply while enabling price differentiation between premium fresh produce and economy packaged goods tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures in the B2B protein and dairy supply tier, though consumer-facing segments favor per-unit transactional models. Price differentiation rests on certification level under FDA Food Safety Modernization Act traceability rules and geographic delivery cost from coastal cold-chain hubs to interior markets. Cost compression in the discount store tier is intensifying because ALDI's private-label concentration forces rivals to match margin structures they cannot replicate. Students represent the most price-sensitive segment, while urban consumers in China's tier-one cities exhibit lowest sensitivity due to convenience premium acceptance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates input cost planning for retailers sourcing packaged goods and frozen foods across Pacific routes. Geographic supply concentration centers on China for electronics-enabled shelf systems, the United States for refrigeration equipment, and Germany for automation components. Raw material dependencies draw from aluminum for HVAC-R systems, lithium for warehouse battery backup, and food-grade packaging polymers. Single-source vulnerability in third-party refrigerated transport creates bottleneck risk during peak demand windows. Distribution runs through regional distribution centers feeding last-mile micro-fulfillment hubs in dense metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food and grocery retail sits in early-cycle expansion as India's FSSAI modernization accelerates organized retail penetration in tier-two cities previously locked out by fragmented kirana networks.
For Market Incumbents: Harden cold-chain infrastructure control through captive supply development in California's Central Valley and the Yangtze River Delta, where climate-driven harvest disruptions threaten input cost stability. Consolidate supplier relationships toward certified packaging providers capable of multi-retailer EU Green Deal compliance. Defensive positioning requires technology investment in automated fulfillment centers that compress order-to-door timelines below competitor reach.
For New Entrants and Emerging Players: Tier-two Indian cities present the most penetrable geography as working professionals migrate from kirana networks to integrated supermarket formats. White-space targets include dark store micro-fulfillment in abandoned German and French urban retail spaces and AI-driven dynamic pricing systems for near-expiry fresh categories. A super-app integration strategy offers the strongest go-to-market angle in Chinese urban corridors where household shopping fragmentation concentrates demand in morning and evening delivery windows.
For Investors and Strategic Acquirers: Automated logistics specialists with robotic picking deployments represent the priority acquisition archetype, as Kroger and Walmart capital allocations signal technology leadership premiums. Long-term viability across the next decade hinges on backward integration depth and last-mile fulfillment density rather than front-of-store merchandising scale. The signal to watch is commissioning delays for automated warehouses in secondary US markets, where cold-chain technician scarcity constrains capacity expansion timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Supply | Walmart's distribution control over perishables anchors North American volume leadership against price volatility. |
| Automated Fulfillment Center Deployment | Kroger's robotic picking systems compress delivery timelines below two hours in Dallas-Fort Worth density corridors. |
| Dark Store Micro-Fulfillment Conversion | Berlin and Hamburg abandoned retail spaces transform into chilled staging hubs serving three-to-five-kilometer radii. |
| EU Green Deal Packaging Compliance | Supplier consolidation toward certified providers reshapes procurement relationships across German and French headquarters. |
| Super-App Mobile Commerce Integration | Chinese urban household shopping fragmentation concentrates demand in app-coordinated morning and evening delivery slots. |
Research Approach
Initial hypotheses were tested against primary input from supermarket operations directors, cold-chain logistics managers, retail procurement leads, and FSSAI compliance officers and refined through secondary validation against FDA Food Safety Modernization Act filings, EU Green Deal directive documentation, customs and trade data for refrigerated equipment imports, and SEC 10-K disclosures from listed retail operators. Bottom-up store-format modeling and top-down regional consumption pattern analysis were triangulated to anchor volume estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation dimensions spanning store format, product category temperature requirements, sales channel fulfillment architecture, and customer segment purchasing frequency. CAGRs were derived from trend extrapolation of cold-chain digitization adoption curves and last-mile automation deployment rates, incorporating urbanization patterns in China and India as industry-specific demand inputs.
Practitioners should monitor labor scarcity in last-mile delivery, gig-economy driver availability constraints, and EU AI Act algorithmic transparency compliance costs for early signals of forecast revision triggers. Forecasts reflect documented assumptions about cold-chain infrastructure extension timelines and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
India Foodservice Market
Food Service
China Inflight Catering Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
India Inflight Catering Market
Food Service
Chile Food Delivery Market
Food Service
United States Foodservice Market
Food Service
Bangladesh Food Service Market
Food Service
Clear Ice Maker Market
Food Service
Quick-Service Restaurants Market
Food Service
Kuwait Food Service Market
Food Service
Saudi Arabia Pizza Restaurants Market
Food Service
Philippines Foodservice Market
Food Service
Smart Food Logistics Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
Global Delivery Takeaway Food Market
Food Service
Food Contract Manufacturing Market