
 Commercial Restaurant Rangers Market | 2026-2036
Commercial Restaurant Rangers Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Restaurant Rangers Market Outlook
Dealer-direct channels is reconfiguring how commercial kitchen equipment reaches independent operators and multi-unit chains. The Middleby Corporation leverages its portfolio breadth to control specification conversations with large franchise accounts. ITW Food Equipment Group anchors its position through intensive R&D spend on connected cooking platforms. Rational AG differentiates through precision thermal engineering and premium positioning in fine-dining supply chains.
Commercial restaurant rangers denote heavy-duty cooking appliances engineered for continuous-duty cycle operation in professional foodservice environments, typically constructed from 300-series stainless steel with cast-iron or chrome-plated grates rated for temperatures exceeding 650°F, designed to deliver consistent thermal output across high-volume meal periods. Grills and fryers occupy the largest installed base due to their ubiquity across fast food chains and casual dining formats, though induction technology within the technology dimension is gaining specification share as operators confront energy cost volatility and ventilation constraints. Ovens configured with convection and infrared systems command margin premiums in fine dining and catering services where menu complexity demands precise moisture and browning control.
The U.S. Department of Energy sets minimum efficiency thresholds for commercial cooking equipment, while NSF International governs sanitation and materials safety certification required for market access across most jurisdictions. The EPA's Energy Star program creates procurement preference hierarchies among chain operators pursuing sustainability targets and utility rebate capture. Stakeholders must monitor how state-level building electrification mandates in California, New York, and Washington reshape gas versus induction technology mix in replacement cycles and new construction specifications.
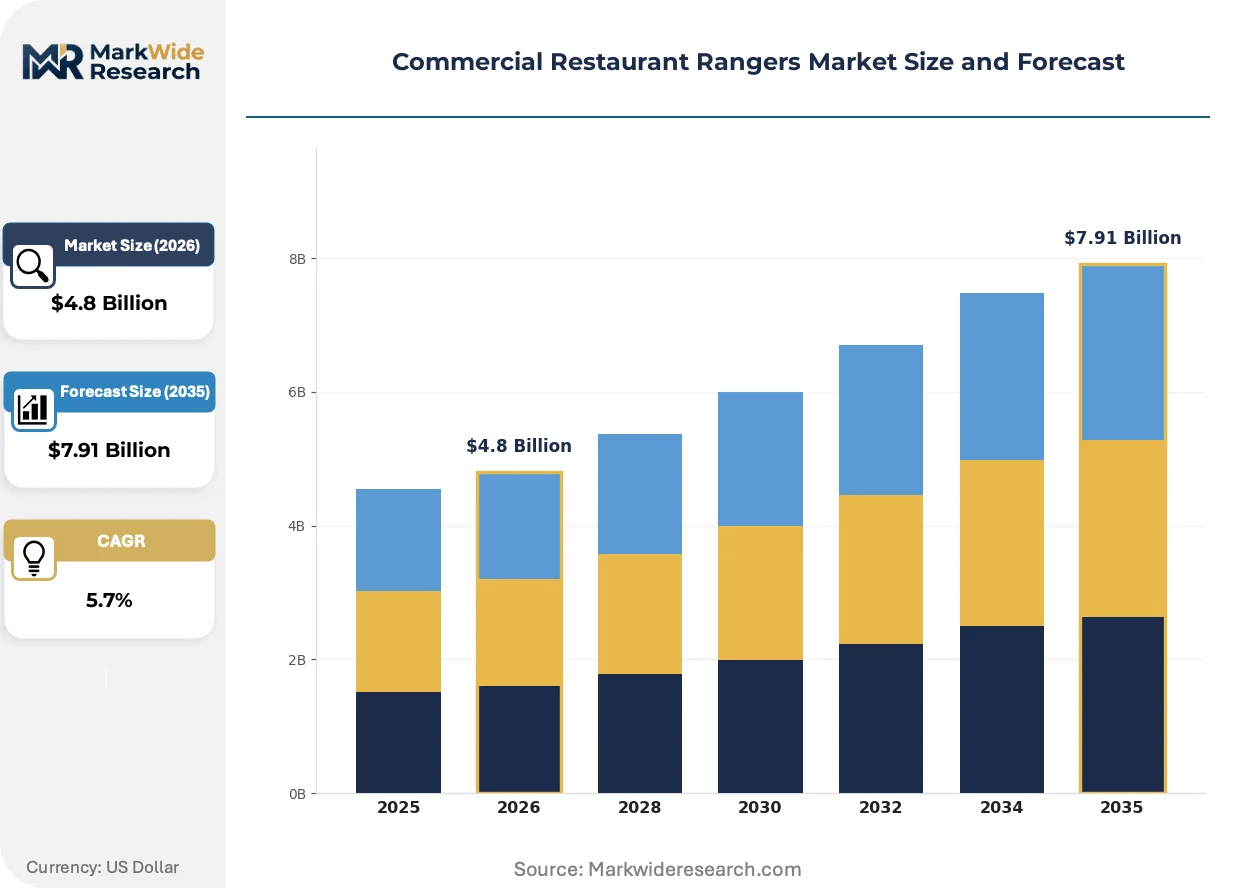
Market Dynamics
Equipment refresh cycles across fast food chains are compressing as operators confront energy cost volatility and ventilation constraints. This structural pressure is reconfiguring specification conversations between manufacturers and multi-unit franchise accounts.
Growth Catalysts
- DOE Efficiency Standards:The U.S. Department of Energy's commercial kitchen efficiency thresholds are accelerating induction-based equipment specifications across North American chain operators.
- Fast Food Expansion:Permits for chain restaurant development have accelerated in Texas, Florida, and California, concentrating demand for heavy-duty cooking platforms.
- Energy Star Procurement:The EPA's Energy Star program creates preference hierarchies among operators pursuing utility rebate capture and sustainability targets.
Market Restraints
- Stainless Steel Input Volatility:Price swings in 300-series stainless steel, the primary construction material for commercial rangers, compress margin predictability for equipment fabricators.
- Ventilation Infrastructure Lock-in:Existing gas-line infrastructure in legacy commercial kitchens creates technical friction against induction retrofits despite operational savings.
- NSF Certification Timelines:Sanitation and materials safety certification requirements from NSF International extend product launch cycles and constrain rapid specification pivots.
Strategic Opportunities
- Building Electrification Mandates:State-level electrification requirements in California, New York, and Washington are reshaping gas versus induction technology mix in replacement cycles.
- Connected Cooking Convergence:Integration of IoT sensors with precision thermal engineering enables remote diagnostics and predictive maintenance contracts.
- Fine-Dining Specification:Convection and infrared oven configurations command margin premiums in catering and fine-dining supply chains where menu complexity demands precise moisture control.
Industry Challenges
- Thermal Engineering Talent Scarcity:Precision induction system design requires specialized expertise that concentrates among a narrow pool of European and Japanese engineering centers.
- Legacy Equipment Integration:Connected cooking platforms must interface with decades-old kitchen management systems, complicating deployment and support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Restaurant Rangers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grills, Fryers, Ovens, Refrigerators Technology: Induction, Convection, Infrared, Gas End User: Fast Food Chains, Fine Dining Restaurants, Cafés, Catering Services Installation: On-site, Modular, Permanent, Temporary |
| Companies Covered | The Middleby Corporation, ITW Food Equipment Group, Ali Group, Rational AG, Alto-Shaam, Hoshizaki Corporation, Electrolux Professional, Duke Manufacturing, Welbilt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Restaurant Rangers Market Strategic Shifts
Specification authority is migrating from distributor networks to manufacturer-direct engagement with franchise engineering teams. This shift compresses traditional channel economics while accelerating technology refresh decisions.
Induction cooking platforms with embedded power management are virtualizing thermal output control across multi-unit operations. Quick-service chains with centralized facilities engineering are specifying these systems for new construction at accelerated rates. The technology is virtualizing energy load balancing and ventilation requirements that previously dictated kitchen layout constraints.
California's Title 24 building energy codes now mandate all-electric readiness in new commercial construction, with similar measures advancing in New York City Local Law 97 and Washington State clean buildings performance standards. These regulations force gas equipment obsolescence planning into capital budgeting cycles. Fine-dining and catering segments are responding fastest due to shorter lease terms and higher renovation frequency.
Multi-unit chains are consolidating specification authority into centralized procurement functions that negotiate enterprise-wide equipment standards. Independent dealers and regional distributors are losing influence over large franchise accounts. This concentration is most visible in Texas and Florida where development permits for chain restaurants have accelerated fastest.
Commercial Restaurant Rangers Market Segmentation
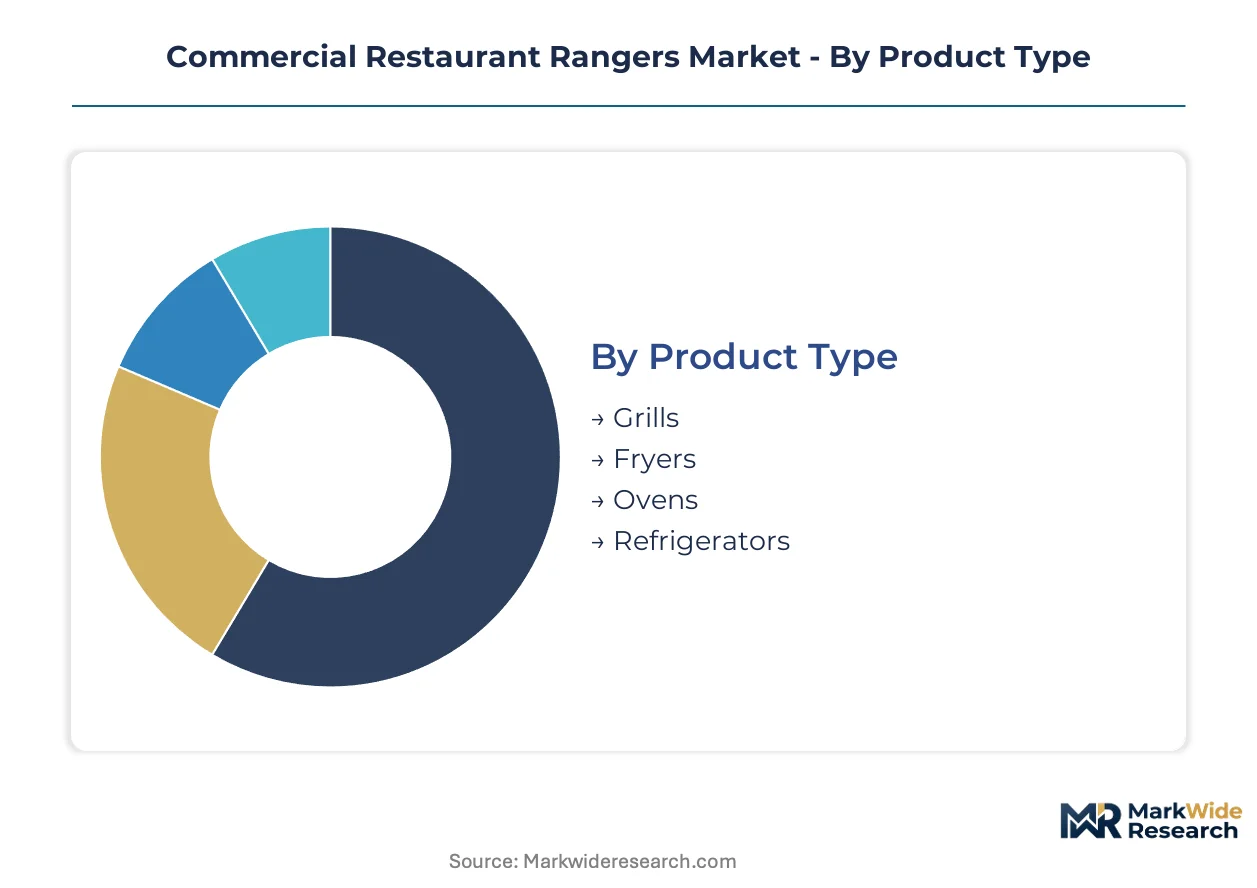
Segmentation in commercial restaurant rangers reveals how specification authority migrates across product categories and end-use environments. Equipment fabricators calibrate thermal engineering investments and channel economics against these divides.
Product Type:
Mature equipment formats anchor installed base volumes while emerging configurations capture specification share in new construction cycles.
- Grills:Heavy-duty platforms with cast-iron or chrome-plated grates rated above 650°F dominate fast food chain specifications. Demand concentrates in Texas and Florida where development permits have accelerated, driven by compressed refresh cycles confronting energy cost volatility.
- Fryers:Vessel configurations with integrated filtration and automated oil management command premium positioning in high-volume operations. California operators are specifying these for compliance with ventilation constraints and building electrification mandates.
- Ovens:Convection and infrared systems serve fine-dining and catering segments where precise moisture control justifies margin premiums.
- Refrigerators:Reach-in and walk-in configurations complete the thermal platform suite for full-service kitchen specifications.
Grills handle the majority of throughput; ovens are expanding most quickly on specification share as precision thermal engineering gains priority.
Technology:
Cost tier stratification separates premium induction platforms from established gas infrastructure, with mid-tier convection occupying specification middle ground.
- Induction:Embedded power management systems virtualize thermal output control across multi-unit operations. California, New York, and Washington state-level electrification mandates are accelerating specifications in new construction.
- Convection:Forced-air circulation with humidity injection serves catering and institutional segments requiring batch consistency at volume scale.
- Infrared:Radiant heat transfer enables rapid surface browning without convective drying, commanding niche positioning in fine-dining protein preparation.
- Gas:Open-burner and infrared gas configurations retain installed base dominance where ventilation infrastructure lock-in constrains retrofit economics.
Gas retains volume leadership in legacy installations; induction is gaining share fastest as electrification mandates reshape capital budgeting cycles.
End User:
Customer type concentration determines whether procurement flows through centralized franchise engineering or independent dealer networks.
- Fast Food Chains:Centralized facilities engineering functions negotiate enterprise-wide equipment standards, compressing traditional distributor influence. Texas and Florida permit acceleration is concentrating demand for heavy-duty platforms with connected cooking capabilities.
- Fine Dining Restaurants:Shorter lease terms and higher renovation frequency enable faster technology adoption, particularly for precision thermal systems commanding margin premiums.
- Cafés:Limited-service formats prioritize compact footprints and modular configurations for flexible kitchen layouts.
- Catering Services:Mobile and temporary installation requirements drive demand for equipment with rapid deployment and breakdown characteristics.
Fast food chains drive procurement volume concentration; fine dining is climbing the fastest on technology specification authority.
Installation:
Application flexibility separates permanent infrastructure commitments from adaptive deployment models responding to lease term volatility.
- On-site:Fixed-location assembly with utility hard connections serves established operations with long-term facility commitments.
- Modular:Pre-fabricated kitchen components enable rapid reconfiguration for operators confronting uncertain lease renewals or seasonal demand swings.
- Permanent:Built-in installations with structural integration anchor capital-intensive renovations in owned facilities or long-term leases.
- Temporary:Mobile platforms with quick-connect utilities serve event catering and emergency foodservice deployments requiring rapid site turnover.
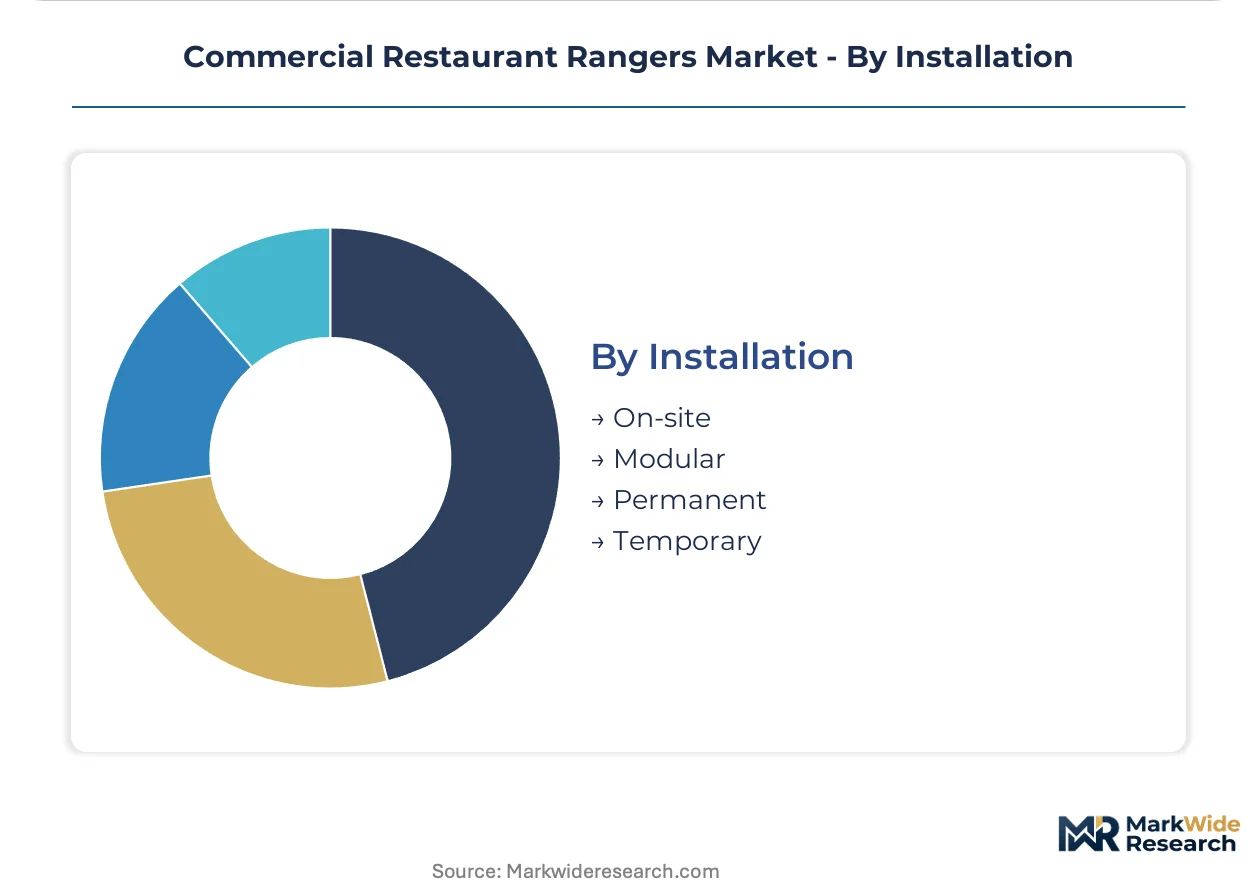
Permanent installations anchor capital deployment; modular configurations are showing the steepest expansion trajectory as lease term uncertainty reshapes kitchen investment horizons.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Texas and Florida exceeds California by 12-18% due to faster permit cycles and lower electrification compliance costs. Equipment fabricators capture margin premiums in deregulated energy markets while facing compressed returns in mandate-heavy coastal jurisdictions.
United States
Texas and Florida concentrate chain restaurant development permits, driving heavy-duty grill specifications from centralized franchise engineering teams. The Department of Energy's commercial kitchen efficiency standards accelerate induction adoption in new construction. California operators confront Title 24 all-electric readiness mandates that force gas equipment obsolescence planning into capital budgets.
Germany
Precision thermal engineering from Baden-Württemberg and Bavaria supplies premium convection and infrared oven configurations to fine-dining export markets. The EU Green Deal's building performance standards reshape commercial kitchen electrification timelines. Stuttgart-based engineering clusters specialize in connected cooking platforms with embedded IoT diagnostics.
Japan
METI efficiency benchmarks drive induction system specifications in Tokyo and Osaka metro foodservice operations. Compact footprint requirements from high-rent urban districts favor modular kitchen configurations. Nagoya industrial corridors supply precision control systems for virtualized thermal output management across multi-unit chains.
China
Yangtze River Delta and Pearl River Delta manufacturing bases dominate stainless steel fabrication for export-oriented equipment. Dual carbon goals from MEE accelerate domestic induction platform adoption in tier-one cities. Shanghai and Shenzhen operators specify connected cooking systems for centralized facilities management across franchise networks.
United Kingdom
London's fine-dining density commands premium oven specifications with precise moisture control for high-complexity menus. Building Regulations Part L updates tighten commercial kitchen energy performance requirements. Midlands manufacturing clusters supply standardized grill platforms for fast-casual expansion into secondary cities.
Commercial Restaurant Rangers Market Competitive Environment
Diversified industrial conglomerates and specialized thermal engineering houses split the market into distinct capability tiers. Consolidation pressure concentrates specification authority among manufacturers with portfolio breadth sufficient to negotiate enterprise-wide franchise standards. Three archetypes dominate: full-line industrial groups controlling multi-category procurement conversations, precision engineering specialists capturing premium positioning, and regional fabricators serving independent operators through dealer networks. Competitive moves center on backward integration into stainless steel component supply and technology licensing partnerships for connected cooking platforms.
Among diversified industrial groups, The Middleby Corporation, ITW Food Equipment Group, and Rational AG occupy positions across the specification spectrum. The Middleby Corporation exemplifies portfolio-breadth strategy through its multi-brand architecture serving chain and independent segments simultaneously. ITW Food Equipment Group anchors the North American market through intensive R&D positioning on connected platforms. Rational AG represents precision thermal engineering specialization with premium-tier concentration in fine-dining supply chains.
| Leading Market Players |
|---|
| The Middleby Corporation |
| ITW Food Equipment Group |
| Ali Group |
| Rational AG |
| Alto-Shaam |
| Hoshizaki Corporation |
| Electrolux Professional |
| Duke Manufacturing |
| Welbilt |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta stainless steel fabrication clusters anchor global equipment supply, with capacity utilization swings in Jiangsu and Zhejiang provinces transmitting directly into downstream pricing power for North American and European distributors. When regional foundry output tightens, configured-to-order induction platforms command steeper premiums against standard gas equipment stock.
Pricing Analysis
Configured-to-order pricing for precision induction systems with embedded power management commands a 25-40% premium over standard gas-platform SKUs. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified connected cooking platforms from basic convection units and entry-level open-burner configurations. Cost compression in the standard tier is intensifying because 300-series stainless steel input volatility compresses fabricator margins. Fast food chains with centralized procurement functions exhibit lowest price sensitivity; independent operators through dealer networks show highest elasticity.
Supply Chain Analysis
Supplier-financing facilities extended by Yangtze River Delta fabricators to tier-one OEMs have lengthened payment terms to 90-120 days, compressing working capital cycles for European precision engineering houses. Geographic supply concentration centers on China for stainless steel components, Germany for thermal control systems, and Japan for induction power electronics. Raw material dependencies rest on nickel-alloy steel sheet, copper winding stock, and ceramic glass-ceramic cooktop substrates. Single-source vulnerability concentrates in precision induction coil winding equipment. Distribution runs through manufacturer-direct engagement with franchise engineering teams for multi-unit chains, regional dealer networks for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority fragmentation across fast food chains, fine-dining groups, and institutional operators creates niche entry points for specialized thermal engineering houses. Building electrification mandates in coastal states accelerate technology substitution cycles that favor agile entrants over legacy gas-platform incumbents.
For Market Incumbents: Pre-empt induction specification share loss by accelerating backward integration into stainless steel component supply and locking in multi-year procurement contracts with Texas and Florida franchise development pipelines. The Middleby Corporation's portfolio breadth strategy demonstrates how controlling enterprise-wide equipment standards conversations defends against European precision engineering specialists. Priority lever: captive supply of 300-series steel grades to margin-protect against commodity volatility. For New Entrants and Emerging Players: Southeast Asia's underpenetrated fast-casual expansion presents white-space demand for compact modular induction platforms with rapid-deployment characteristics. Secondary-city catering services in India and Indonesia show lowest competitive density for precision thermal equipment. Go-to-market angle: cloud-connected kitchen management integration pitched to centralized facilities engineering at regional hotel chains. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core food equipment divisions with sub-scale R&D spend. Long-term viability favors precision thermal engineering specialists with installed base density in fine-dining supply chains and recurring service contract revenue. Signal to watch: acceleration of state-level building electrification mandates beyond California, New York, and Washington forcing gas equipment obsolescence into capital budgeting cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Cooking Platform Integration | Embedded IoT diagnostics from Stuttgart engineering clusters enable remote maintenance contracts with multi-unit chains. |
| Backward Integration into Stainless Steel Supply | Captive sourcing of 300-series grades from Yangtze River Delta mills insulates margin against nickel price volatility. |
| NSF Certification Fast-Track Investment | Accelerated sanitation approval timelines compress product launch cycles for induction retrofit specifications. |
| Modular Kitchen Configuration Development | Pre-fabricated components address lease-term uncertainty reshaping kitchen investment horizons in urban districts. |
| State Electrification Mandate Compliance Program | Title 24 and Local Law 97 readiness positioning captures specification share in coastal new construction pipelines. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with chain restaurant facilities engineering directors, commercial kitchen equipment distributors, NSF certification specialists, and stainless steel procurement managers at fabrication facilities. Secondary validation drew from DOE efficiency standard filings, EPA Energy Star product listings, state building code regulatory databases, and customs trade data for commercial cooking equipment imports. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across the analysis window.
Calibration of segment-level growth trajectories applied thermal technology adoption curves against regulatory mandate implementation timelines throughout the forecast period. Segmentation dimensions modeled include product type, heating technology, end-user format, installation flexibility, and regional electrification policy cluster. CAGRs derived from fitted growth curves against historical replacement cycle data and permit issuance velocity in high-growth states. Industry-specific inputs incorporated chain restaurant development pipeline tracking and utility rebate program participation rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or pricing warfare by diversified industrial groups would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
A La Carte Market
Food Service
Street Vendors Market
Food Service
Latin America Online Grocery Market
Food Service
Restaurant Glassware Market
Food Service
Global Online Food Delivery Services Market
Food Service
Pizza Oven Market
Food Service
Smoker Grill Market
Food Service
Smart Food Logistics Market
Food Service
Stirrers Market
Food Service
Bangladesh Food Service Market
Food Service
Commercial Sink Market
Food Service
North America Online Grocery Delivery Market
Food Service
Food Trucks Market
Food Service
Takeout Dinner Market
Food Service
Commercial Air Fryer Market
Food Service
Commercial Deep Fryer Parts and Accessories Market