
 India Food Emulsifiers Market | 2026-2036
India Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
India Food Emulsifiers Market Foresight
Asset-light contract manufacturing and third-party tolling arrangements are reshaping competitive entry in India's food emulsifier space. Mohini Organics Private Limited leverages its western India manufacturing base to sustain cost advantages across mono- and diglyceride output. Gujarat Ambuja Exports Ltd. anchors its position through backward integration into vegetable oil refining. Fine Organic Industries Limited differentiates via specialized ester chemistry for high-margin confectionery applications.
Food emulsifiers are surface-active agents containing hydrophilic and lipophilic moieties that reduce interfacial tension between immiscible phases, typically manufactured through glycerolysis of triglycerides or direct esterification of fatty acids with polyols. These compounds stabilize oil-water mixtures, control crystallization, and extend shelf stability in processed foods. Phospholipids and lecithin dominate value capture due to clean-label positioning and non-GMO sourcing premiums. Mono- and diglycerides represent the highest-volume category, though margin compression intensifies as unorganized suppliers expand capacity. Bakery and dairy applications concentrate growth, with beverage formulations emerging as a faster-advancing niche.
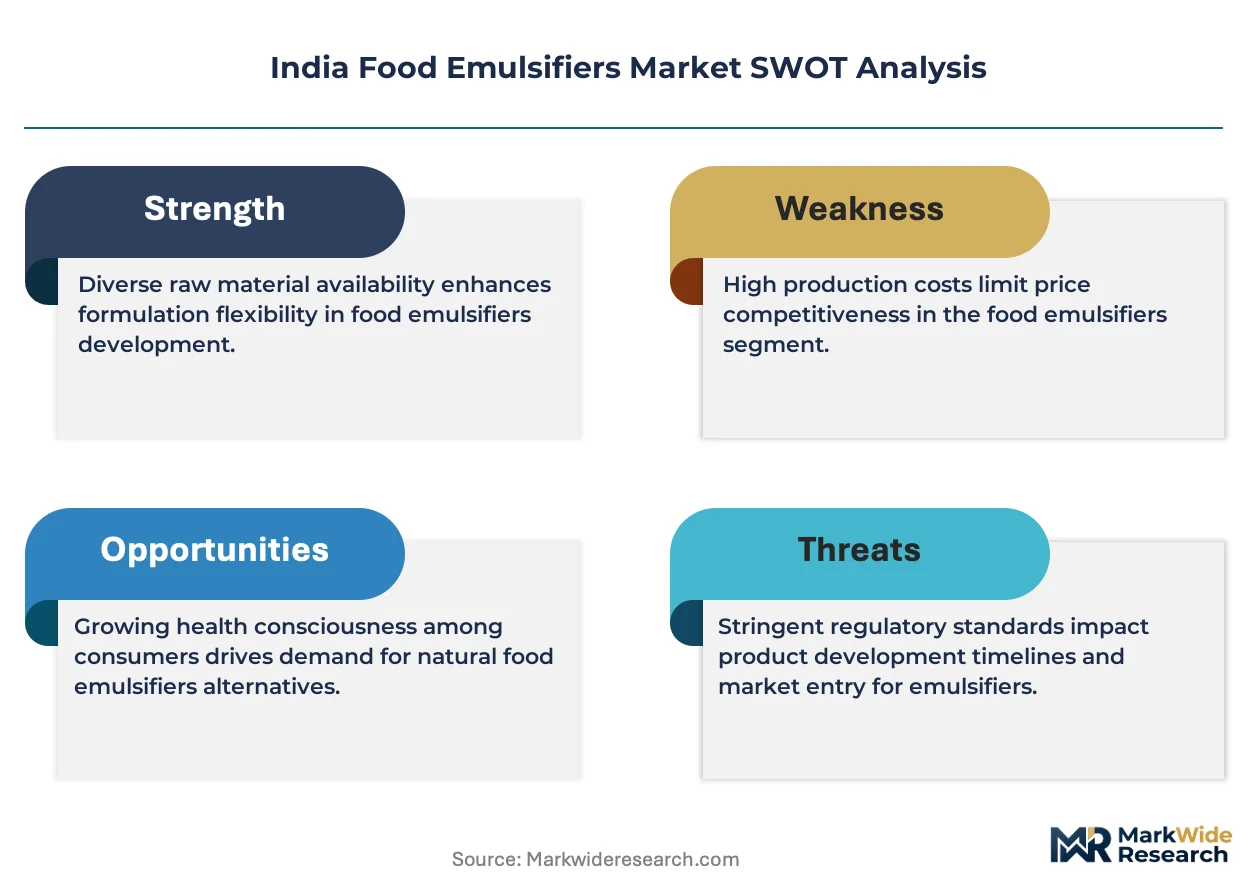
FSSAI additive approval protocols, BIS quality certification requirements, and state-level food safety commissionerates collectively determine market access and product registration timelines in India. Compliance costs favor larger formulators with dedicated regulatory affairs teams, squeezing regional traders. Stakeholders must monitor pending FSSAI notifications on emulsifier usage limits and invest in label-friendly formulations ahead of anticipated enforcement tightening.
Market Dynamics
FSSAI's tightening additive approval timelines are compressing formulation cycles across India's food emulsifier supply base. Clean-label migration is forcing simultaneous reformulation of legacy mono- and diglyceride portfolios.
Growth Catalysts
- Urban bakery expansion:Organized retail penetration in tier-2 and tier-3 cities is pulling emulsifier volumes into biscuit and bread manufacturing clusters.
- FSSAI notification streamlining:Proposed harmonization with Codex Alimentarius standards is reducing multi-state registration friction for national formulators.
- Enzymatic interesterification:This process technology is enabling cleaner-label mono- and diglyceride output without synthetic catalyst residues.
Market Restraints
- Palm oil price volatility:Feedstock concentration in Malaysian and Indonesian supply chains transmits cost shocks directly to Indian emulsifier margins.
- Import dependence for specialty esters:Sorbitan ester and polysorbate categories rely on Chinese and European intermediate supply, creating forex exposure.
- Clean-label substitution pressure:Lecithin and hydrocolloid blends are displacing synthetic emulsifiers in premium confectionery and infant nutrition segments.
Strategic Opportunities
- North-east India penetration:Processing infrastructure gaps in Assam and Manipur create first-mover advantage for tolling partnerships with local dairy cooperatives.
- Plant-based beverage emulsification:Oat and almond milk stabilization requires novel protein-lipid emulsifier systems absent from current portfolios.
- PLI scheme alignment:Food processing equipment incentives under India's production-linked incentive framework reduce capital barriers for integrated emulsifier-bakery operations.
Industry Challenges
- FSSAI state commissionerate coordination:Divergent enforcement interpretations across Maharashtra, Gujarat, and Karnataka create compliance patchwork costs for multi-locational manufacturers.
- Specialized ester chemistry talent:Formulation chemists with glycerolysis and direct esterification process expertise command premium compensation in Ahmedabad and Mumbai clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food Emulsifiers Market |
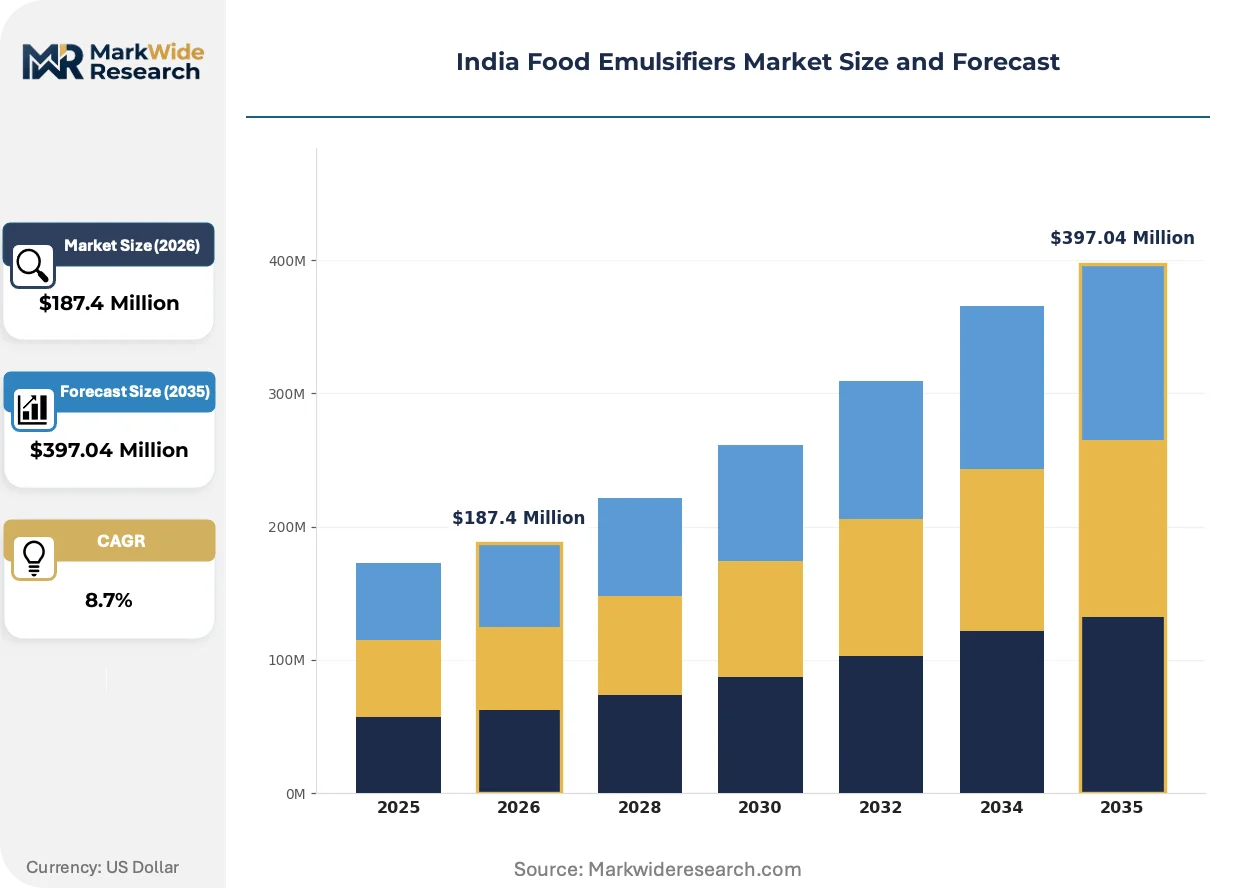
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono- and Diglycerides, Phospholipids, Sorbitan Esters, Lecithin Application: Beverages, Bakery, Dairy, Sauces Form: Liquid, Powder, Granular, Paste End User: Food Processing, Confectionery, Catering, Retail |
| Companies Covered | Mohini Organics Private Limited, Rikevita (India) Private Limited, Gujarat Ambuja Exports Ltd., Cargill Inc., Archer Daniels Midland Co., Fine Organic Industries Limited, Novasol Ingredients Private Limited, Ingredion Inc., Indian Emulsifiers Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food Emulsifiers Market Shifts & Advancements
Enzymatic process technologies and label-friendly positioning are restructuring competitive advantage in India's emulsifier landscape. Formulators are racing to patent-position around bio-catalyzed production routes.
Enzymatic glycerolysis using lipase biocatalysts is collapsing the traditional cost premium between synthetic and clean-label mono- and diglyceride grades. Mid-tier bakery manufacturers in Pune and Hyderabad are adopting these enzymatic grades at 15-20% formulation premiums. This technology diffusion is compressing margin pools for legacy acid-catalyzed production assets.
FSSAI's pending notification on emulsifier usage limits in infant foods and health supplements is forcing anticipatory reformulation across dairy and nutraceutical segments. Manufacturers are pre-emptively reducing polyglycerol ester loadings in whey protein applications. The regulatory uncertainty is accelerating third-party clean-label certification investments ahead of enforcement.
Direct procurement from emulsifier manufacturers is displacing layered distributor networks in Maharashtra's organized bakery sector. Large biscuit producers in Thane and Nashik are negotiating annual volume contracts with tolling specialists. This channel consolidation is most visible in the western India processed food corridor where logistics costs favor direct manufacturer relationships.
India Food Emulsifiers Market Segmentation
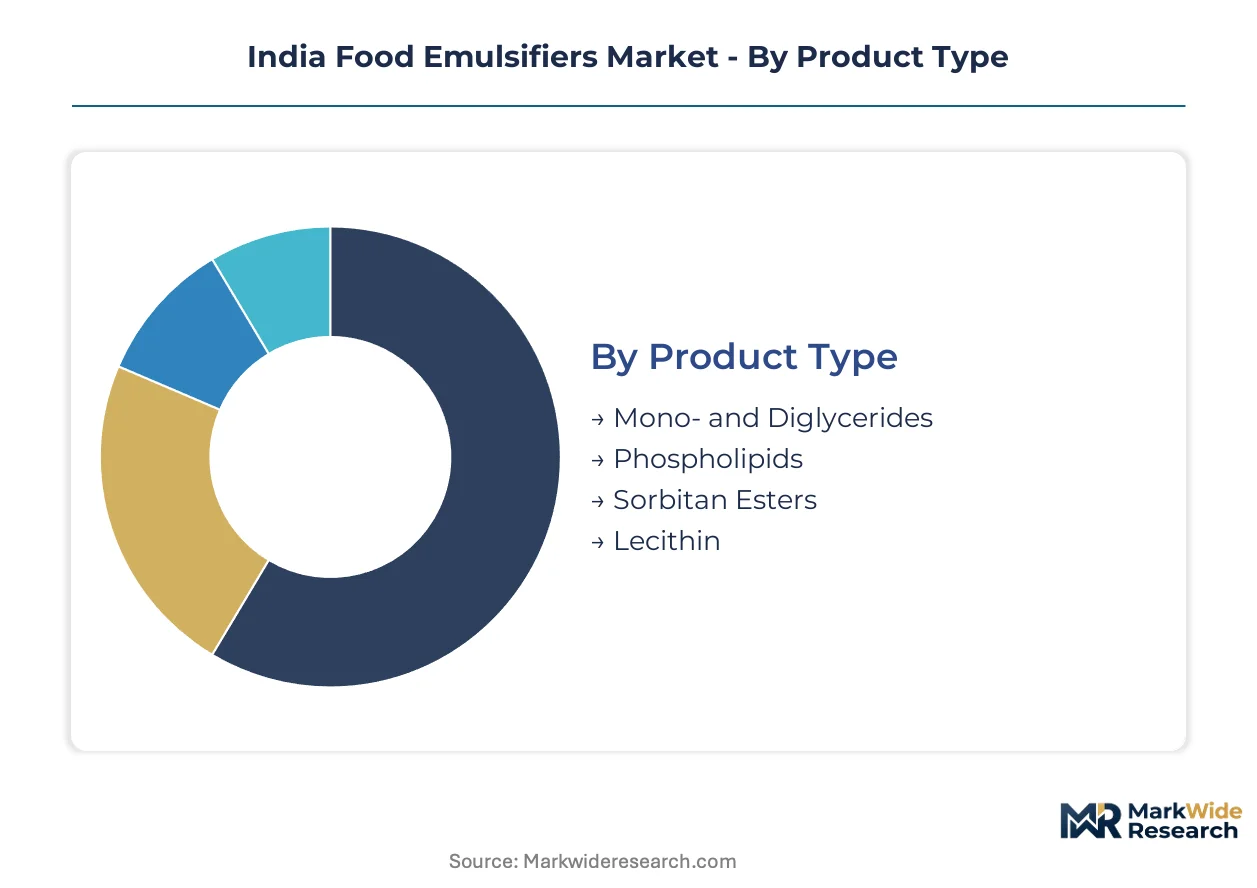
Segmentation in India's food emulsifier market reveals how formulation chemistry, application requirements, and supply chain logistics intersect to create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure, demanding targeted portfolio strategies from suppliers.
Product Type:
Mature glycerolysis-based emulsifiers anchor volume procurement, while enzymatic and clean-label variants command formulation premiums in emerging application niches.
- Mono- and Diglycerides:These partial glycerides manufactured through glycerolysis of triglycerides constitute the highest-volume emulsifier category in Indian processed foods. Maharashtra's biscuit manufacturing clusters in Thane and Nashik drive concentrated procurement of distilled monoglycerides for dough conditioning and shelf-life extension.
- Phospholipids:Naturally derived phosphatidylcholine and phosphatidylethanolamine fractions from soybean and sunflower sources carry clean-label positioning premiums. Gujarat's dairy processing cooperatives are expanding phospholipid procurement for infant formula emulsification ahead of anticipated FSSAI usage limit notifications.
- Sorbitan Esters:Synthetic sorbitan fatty acid esters serve specialized confectionery and cosmetic food applications requiring high HLB stability.
- Lecithin:De-oiled and fluid lecithin grades from non-GMO soybean and rapeseed sources capture growing share in premium bakery and chocolate segments.
Mono- and diglycerides retain volume leadership; phospholipids hold the steepest expansion curve.
Application:
Application-driven segmentation tracks how emulsifier functionality requirements vary across India's processed food manufacturing corridors, with western states anchoring procurement concentration.
- Beverages:Emulsifier systems for plant-based milk alternatives and flavored drinks require protein-lipid stabilization complexes absent from legacy portfolios. Hyderabad's beverage manufacturing base is pulling novel oat and almond milk emulsification chemistries into commercial scale.
- Bakery:Bread, biscuit, and cake applications consume the largest emulsifier volumes through dough strengtheners and crumb softeners. Pune's organized retail bakery expansion is accelerating enzymatic mono- and diglyceride adoption at 15-20% formulation premiums over acid-catalyzed grades.
- Dairy:Ice cream, cheese, and whey protein applications demand emulsifiers controlling fat crystallization and preventing whey-off. FSSAI's pending infant food notifications are forcing pre-emptive polyglycerol ester loading reductions across dairy processors.
- Sauces:Mayonnaise, dressings, and condiment emulsions require high-HLB systems for oil-in-water stability under variable storage conditions.
Bakery commands absolute procurement tonnage; beverages are climbing the fastest as plant-based alternatives reshape formulation requirements.
Form:
Physical form selection reflects logistics economics and manufacturing integration depth across India's fragmented processing infrastructure.
- Liquid:Fluid emulsifier deliveries suit high-volume continuous manufacturing with integrated dosing systems. Bulk liquid tanker supply dominates western India dairy and beverage corridors where direct manufacturer relationships displace distributor networks.
- Powder:Spray-dried and plated powder grades enable dry blending operations in tier-2 and tier-3 bakery clusters lacking liquid handling infrastructure.
- Granular:Free-flowing granular forms reduce dusting and improve dispersion in large-scale bread and biscuit manufacturing.
- Paste:High-viscosity paste emulsifiers serve specialized confectionery and margarine applications requiring precise plasticity control.
Liquid form retains volume leadership; powder holds the steepest expansion curve as semi-urban bakery clusters scale.
End User:
End-user segmentation captures divergent procurement sophistication, with organized food processing consolidating direct supplier relationships while fragmented channels sustain distributor relevance.
- Food Processing:Large-scale organized manufacturers of bakery, dairy, and beverage products negotiate annual volume contracts with emulsifier tolling specialists. Direct procurement is displacing layered distribution most visibly in Maharashtra's processed food corridor.
- Confectionery:Chocolate and sugar confectionery applications require specialized ester chemistry expertise concentrated in Ahmedabad and Mumbai formulation clusters.
- Catering:Institutional food service and hospitality channels procure emulsifiers through regional distributors with limited technical support.
- Retail:Consumer-facing emulsifier sales for home baking remain a marginal channel dominated by imported specialty brands.
Food processing retains volume leadership; confectionery holds the steepest expansion curve as premium chocolate manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's food emulsifier trade remains import-dependent for specialty esters while western states dominate domestic manufacturing. Export volumes concentrate in mono- and diglyceride shipments to South Asian neighbors. Regional procurement patterns track processed food corridor development across state boundaries.
Maharashtra
Thane and Nashik biscuit manufacturing clusters drive concentrated demand for distilled monoglycerides in dough conditioning applications. FSSAI state commissionerate enforcement variations create compliance coordination costs for multi-locational manufacturers operating across Maharashtra-Gujarat borders. Pune's organized retail bakery expansion accelerates enzymatic emulsifier adoption at formulation premiums over acid-catalyzed grades.
Gujarat
Ahmedabad anchors India's vegetable oil refining infrastructure, enabling backward-integrated emulsifier production with captive fatty acid supply. BIS quality certification requirements for food additives favor larger formulators with dedicated regulatory affairs teams based in the state. Dairy processing cooperatives across Gujarat expand phospholipid procurement for infant formula emulsification ahead of anticipated FSSAI usage limit notifications.
Karnataka
Bengaluru's beverage manufacturing base pulls novel plant-based milk emulsification chemistries into commercial scale. State-level food safety commissionerates enforce divergent interpretation of national FSSAI standards, creating patchwork compliance costs. The state's processed food sector concentrates procurement of high-HLB emulsifier systems for oil-in-water stability in dressing and condiment applications.
Tamil Nadu
Chennai's confectionery and chocolate manufacturing corridor demands specialized ester chemistry expertise concentrated in formulation clusters. PLI scheme incentives for food processing equipment reduce capital barriers for integrated emulsifier-manufacturing operations in the state. Regional dairy processors pre-emptively reduce polyglycerol ester loadings in whey protein applications ahead of regulatory enforcement tightening.
Telangana
Hyderabad's emerging beverage manufacturing base requires protein-lipid stabilization complexes absent from legacy emulsifier portfolios. State industrial policy supports tolling partnerships between national emulsifier suppliers and local dairy cooperatives. The region's bakery sector adopts powder-form emulsifiers to enable dry blending operations in semi-urban clusters lacking liquid handling infrastructure.
India Food Emulsifiers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower formulation scope. India's food emulsifier structure fragments across organized manufacturers, tolling specialists, and unorganized regional traders. Three archetypes dominate: backward-integrated oil refiners with captive fatty acid supply, enzymatic process technology licensors, and clean-label phospholipid purveyors. Capacity expansion and direct procurement channel consolidation represent the dominant competitive moves as large biscuit producers negotiate annual volume contracts displacing layered distribution networks.
Within the domestic specialist tier, Mohini Organics Private Limited and Fine Organic Industries Limited occupy positions exemplifying western India manufacturing concentration. Gujarat Ambuja Exports Ltd. anchors the backward-integrated archetype through its vegetable oil refining infrastructure. Among multinational participants, Cargill Inc. and Archer Daniels Midland Co. represent global platform integrators with broad ingredient portfolios extending beyond emulsifiers into complementary hydrocolloid and stabilizer systems.
| Leading Market Players |
|---|
| Mohini Organics Private Limited |
| Rikevita (India) Private Limited |
| Gujarat Ambuja Exports Ltd. |
| Cargill Inc. |
| Archer Daniels Midland Co. |
| Fine Organic Industries Limited |
| Novasol Ingredients Private Limited |
| Ingredion Inc. |
| Indian Emulsifiers Limited |
| Others |
Supply & Pricing Matrix
Palm oil price volatility originating in Malaysian and Indonesian supply chains determines both margin compression across enzymatic versus acid-catalyzed emulsifier tiers and the geographic clustering of backward-integrated manufacturers in Gujarat. This feedstock concentration forces Indian formulators to absorb cost shocks or pass them through annual volume contracts with Maharashtra biscuit producers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across India's food emulsifier procurement. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-certified enzymatic grades from legacy acid-catalyzed outputs and unorganized trader supplies. Cost compression in standard-grade mono- and diglycerides is intensifying because unorganized capacity expansion in Ahmedabad and Mumbai clusters erodes margin pools. Regional bakery cooperatives in tier-2 cities exhibit highest price sensitivity; infant formula manufacturers in Gujarat demonstrate lowest sensitivity due to clean-label certification requirements.
Supply Chain Analysis
Chinese and European export-control regimes on specialty ester intermediates constrain sorbitan ester and polysorbate flows into Indian formulation plants. Supply concentrates in Indonesia and Malaysia for palm oil feedstocks, China for synthetic ester intermediates, and western Indian states for finished emulsifier manufacturing. Raw material dependencies span crude palm oil, glycerol, and fatty acid fractions. Single-source vulnerability in Malaysian palm oil derivatives creates forex exposure during ringgit volatility. Distribution runs through direct manufacturer relationships displacing layered networks in Maharashtra's organized bakery corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's food emulsifier market sits at a platform-economics inflection where enzymatic process licensors and clean-label phospholipid purveyors compete to become the dominant formulation standard for FSSAI-compliant infant nutrition and bakery applications.
For Market Incumbents: Entrench backward integration into vegetable oil refining to defend against margin erosion from unorganized mono- and diglyceride suppliers expanding capacity in Ahmedabad clusters. Secure FSSAI pre-certification for enzymatic glycerolysis outputs ahead of pending infant food usage limit notifications. Capacity addition in tolling partnerships with Assam and Manipur dairy cooperatives anchors north-east India penetration before competitors establish local presence. For New Entrants and Emerging Players: Establish a beachhead in plant-based beverage emulsification systems for oat and almond milk stabilization, a white-space segment where legacy portfolios lack protein-lipid complexes. Target Hyderabad's emerging beverage manufacturing base through tolling arrangements with state-supported dairy cooperatives. License enzymatic process technology from European biocatalyst specialists to bypass capital-intensive acid-catalyzed asset requirements. For Investors and Strategic Acquirers: FSSAI's pending harmonization with Codex Alimentarius standards reshapes the acquisition landscape toward formulators with dedicated regulatory affairs teams and clean-label certification infrastructure. Long-term viability over the projection horizon favors enzymatic process technology licensors and phospholipid purveyors with non-GMO sourcing premiums over commodity mono- and diglyceride manufacturers facing margin compression. Watch for FSSAI enforcement tightening on polyglycerol ester loadings in infant formula as the signal indicating regulatory premium capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Process Technology Licensing | Enables clean-label mono- and diglyceride output without synthetic catalyst residues for FSSAI compliance. |
| Backward Integration into Palm Oil Refining | Captive fatty acid supply insulates Gujarat manufacturers from Indonesian and Malaysian price volatility. |
| Direct Procurement Channel Consolidation | Annual volume contracts with Thane and Nashik biscuit producers displace layered distributor networks. |
| North-East India Tolling Partnerships | First-mover advantage in Assam and Manipur dairy cooperatives fills processing infrastructure gaps. |
| Clean-Label Phospholipid Certification Investment | Non-GMO soybean and sunflower sourcing premiums capture infant formula reformulation demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bakery procurement managers, dairy processing technologists, FSSAI regulatory affairs specialists, and emulsifier formulation chemists in Ahmedabad and Mumbai clusters. Secondary validation drew from FSSAI notification archives, BIS quality certification records, customs trade data on palm oil derivatives, and SEC filings of global ingredient platform integrators. Bottom-up volume estimates from state-level processed food manufacturing clusters were triangulated against top-down market sizing from import-export trade flows.
Calibration against historical price elasticities in palm oil feedstock markets and enzymatic technology adoption curves in European bakery applications anchored the analytical framework. Segmentation dimensions modeled span product type chemistry, application functionality, physical form logistics, and end-user procurement sophistication across the projection horizon. CAGRs were derived from growth driver quantification and restraint impact assessment. Industry-specific forecast inputs include FSSAI notification timelines and PLI scheme equipment incentive uptake rates.
Stress conditions across palm oil price volatility bands, FSSAI enforcement intensity scenarios, and enzymatic technology diffusion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory harmonization progress and clean-label substitution velocity. Cross-checking against Indian processed food production indices and Malaysian palm oil derivatives pricing benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Granulated Tapioca Market
Food Additives and Ingredients
Japan Feed Additives Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
Nisin for Food Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Japan Anti-Caking Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
North America Feed Additives Market