
 Africa Food Additives Market | 2026-2036
Africa Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Additives Market Outlook
ISO 22000 certification is reorganizing competitive access across the Africa food additives landscape, filtering out smaller traders unable to document hazard-critical control points. Cargill Incorporated leverages its integrated supply chain from West African sourcing hubs to maintain cost discipline in sweetener and texturizer distribution. Tate & Lyle PLC anchors its position through specialized starch modification capabilities that serve dairy and bakery processors in Kenya and South Africa. Ingredion Incorporated differentiates via clean-label ingredient portfolios aligned with retailer procurement standards in Nigeria and Egypt.
Food additives comprise functional substances—emulsifiers, acidulants, antioxidants, and enzymatic preparations—incorporated at specified concentrations to enhance shelf stability, sensory profile, or nutritional value in processed foods. Industrial formulations typically specify inclusion rates between 0.01% and 2.0% by weight, depending on target functional effect and matrix compatibility. Preservatives currently command the largest volume share within product type segmentation, driven by ambient-distribution infrastructure gaps that demand extended shelf life in tropical climates. Sweeteners represent the fastest-expanding category, as beverage manufacturers reformulate to reduce sucrose content while maintaining palatability thresholds across price-sensitive consumer segments.
South Africa's Department of Health administers mandatory fortification standards for maize meal and wheat flour, directly shaping mineral premix demand specifications. Nigeria's National Agency for Food and Drug Administration and Control enforces additive maximum residue limits that determine which international suppliers qualify for import registration. Kenya's Bureau of Standards operates parallel compliance protocols for synthetic colorants in confectionery and snack categories. Stakeholders must monitor divergent national implementation timelines for Codex Alimentarius harmonization, as asynchronous adoption creates fragmented product registration burdens across the continent's major economies.
Market Dynamics
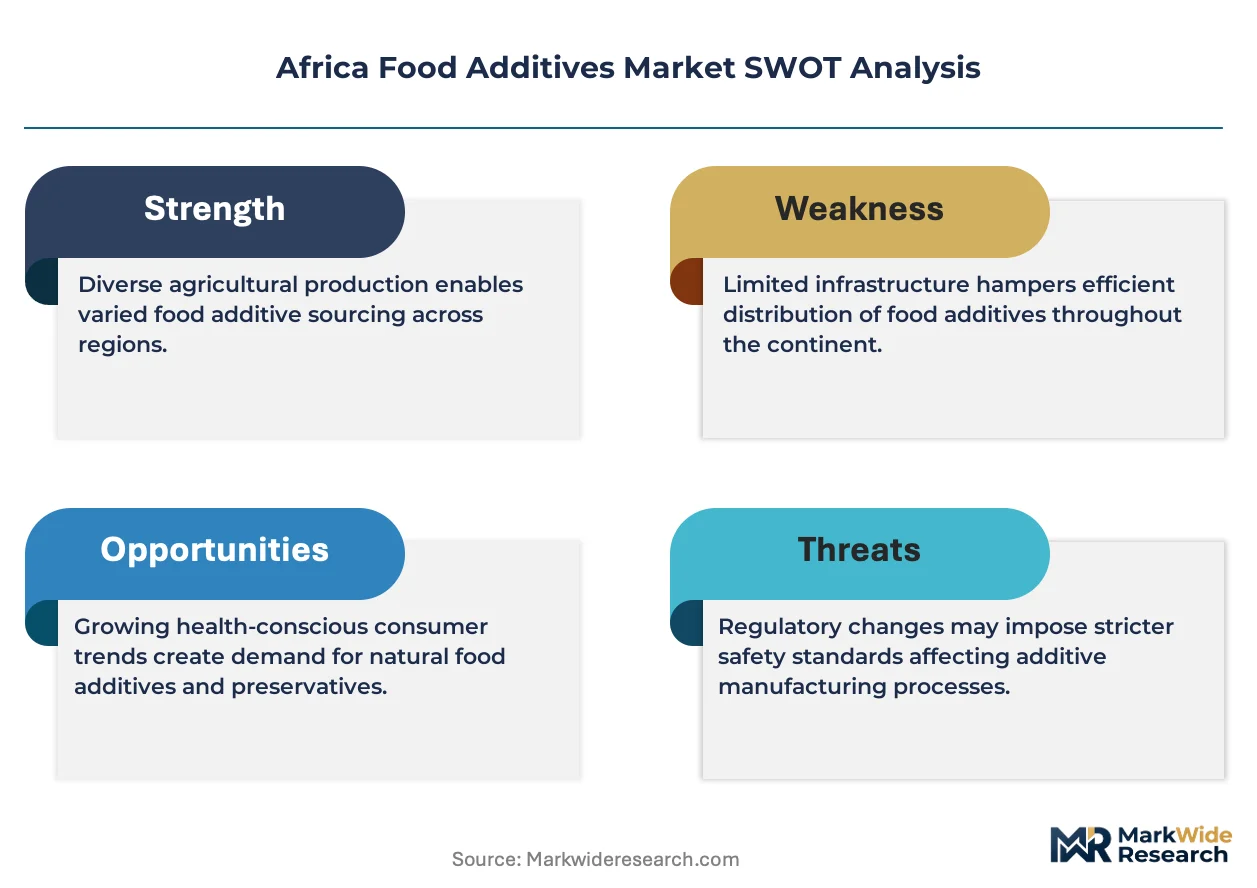
ISO 22000 certification requirements are filtering competitive access across Africa's food additives landscape, forcing smaller traders to document hazard-critical control points or exit procurement channels serving multinational food processors.
Growth Catalysts
- Nigeria's industrial cassava-to-sweetener investments:Domestic starch modification capacity is expanding, reducing import dependency for beverage manufacturers reformulating sucrose-reduced products.
- South Africa's mandatory maize meal fortification:The Department of Health's mineral premix specifications are creating sustained demand for vitamin-mineral blends in milling operations.
- Clean-label enzymatic preparations:Bakery and dairy processors in Kenya are adopting label-friendly alternatives to synthetic emulsifiers, opening formulation flexibility for export-oriented production.
Market Restraints
- Input cost volatility in natural colorants:Weather-dependent harvests of annatto and turmeric concentrates in East African sourcing zones create formulation cost instability for confectionery manufacturers.
- Supply concentration in synthetic antioxidant precursors:Three Asian chemical conglomerates control BHA and BHT intermediate supply, exposing African compounders to freight and currency shocks.
- Technical limitation in ambient-distribution compatibility:Natural preservative alternatives lack the thermal stability required for Nigeria's unchilled retail infrastructure, locking processors into synthetic benzoate systems.
Strategic Opportunities
- Egypt's underpenetrated clean-label segment:Retailer procurement standards in Cairo-Alexandria corridors are tightening, creating first-mover positioning for documented natural additive portfolios.
- Regulatory tailwind from Codex Alimentarius harmonization:Asynchronous national adoption timelines create temporary arbitrage windows for compliant suppliers to pre-register ahead of competitor qualification.
- Direct-to-processor digital distribution:B2B platforms connecting Lagos-Abuja manufacturers with certified additive suppliers are compressing traditional distributor margins and accelerating sample-to-contract cycles.
Industry Challenges
- ISO 22000 auditor scarcity:Certification bodies with Africa-specific food additive expertise are concentrated in Johannesburg and Nairobi, creating six-to-nine-month queue delays for facility accreditation.
- Legacy ERP integration complexity:Nigerian mid-scale processors running on-premise inventory systems face batch-traceability gaps when linking to supplier digital platforms mandated by multinational procurement contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Additives Market |
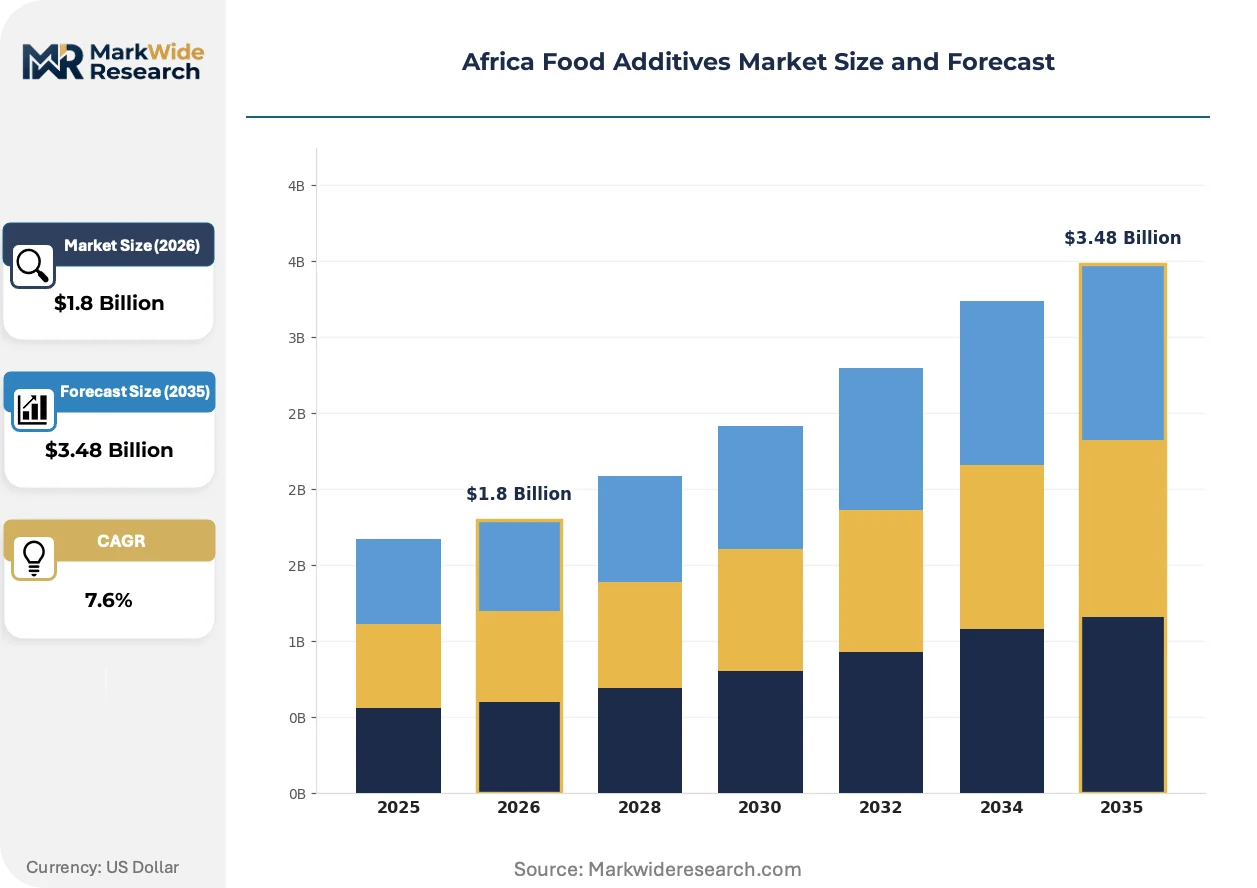
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavors, Preservatives, Colorants, Sweeteners Application: Beverages, Dairy Products, Bakery, Snacks End User: Food Processing, Catering Services, Retail, Households Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | Cargill Incorporated, Tate & Lyle PLC, Ingredion Incorporated, CP Kelco U S Inc, Chemsystems, The Dow Chemical Company, Afro-Ingredients Ltd, Nile Chemicals, PureFood Additives, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Additives Market Strategic Shifts
Clean-label ingredient portfolios are compressing synthetic additive demand across Africa's processed food sector, while digital traceability systems and regional regulatory convergence reshape supplier qualification protocols.
Enzymatic lipid modification technology is decomposing traditional emulsifier demand in bakery applications. Industrial bakeries in South Africa and Kenya are accelerating adoption of lipase and phospholipase systems at pilot-to-scale pace. This enzymatic shift is decomposing commodity lecithin volumes while forcing emulsifier suppliers to reposition around functional blends that enzymes cannot replicate.
Kenya's Bureau of Standards is tightening maximum residue limits for synthetic colorants in confectionery, mirroring trajectory in Nigeria's NAFDAC enforcement. The industrial consequence is a qualification bottleneck where international suppliers must submit extended toxicological dossiers for azo dye registrations. Confectionery exporters targeting COMESA markets are most affected, with formulation teams accelerating natural carotenoid and anthocyanin substitutions to preempt border rejection risks.
Buyer concentration among Lagos-Abuja multinational processors is compressing supplier negotiation leverage. Three beverage and dairy conglomerates now control additive procurement for Nigeria's Atlantic corridor, replacing fragmented distributor networks with direct supplier contracts and consolidated annual tenders. This consolidation is most visible in sweetener and acidulant categories, where volume commitments now determine pricing tier access and technical service allocation.
Africa Food Additives Market Segmentation
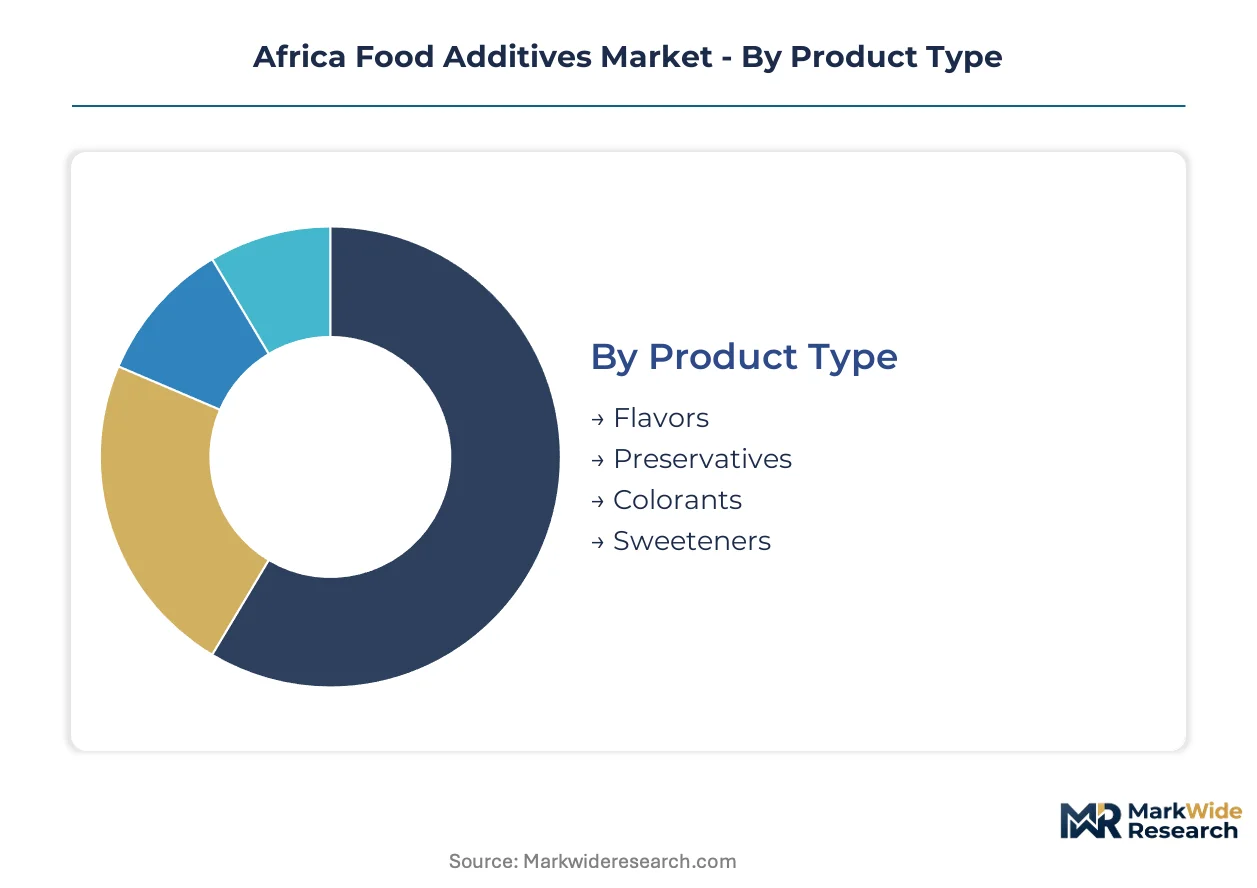
Food additive procurement patterns across Africa diverge sharply by functional category and channel structure. Regulatory fragmentation between national food safety authorities creates asymmetric qualification burdens that reshape competitive access within each segment.
Product Type:
South Africa's Department of Health fortification mandates and Nigeria's NAFDAC residue limits impose divergent compositional standards that filter supplier eligibility differently across functional categories.
- Preservatives:Sorbates, benzoates, and propionates dominate ambient-distribution formulations where tropical heat stress demands extended shelf stability. Nigeria's unchilled retail infrastructure locks processors into synthetic systems despite clean-label pressure elsewhere.
- Sweeteners:High-intensity compounds and bulk polyols are displacing sucrose in Lagos-Abuja beverage corridors. Industrial cassava-to-starch investments are redirecting procurement toward domestic maltodextrin and glucose syrup sources.
- Flavors:Natural extracts and nature-identical compounds serve bakery and dairy processors seeking taste differentiation in Kenya's export-oriented production.
- Colorants:Carotenoid and anthocyanin preparations face qualification bottlenecks under tightening Bureau of Standards limits in Kenya and NAFDAC enforcement in Nigeria.
Preservatives handle the majority of throughput; sweeteners are gaining share fastest as reformulation accelerates across price-sensitive consumer segments.
Application:
End-use concentration in multinational-owned processing clusters concentrates additive demand in specific functional combinations.
- Beverages:Acidulants, sweeteners, and stabilizers integrate in carbonated and juice formulations. Three Lagos-Abuja conglomerates now control procurement through direct supplier contracts rather than fragmented distributor networks.
- Dairy Products:Emulsifiers and enzymatic preparations serve UHT milk and yogurt processors in South Africa and Kenya. Lipase systems are decomposing traditional lecithin volumes at pilot-to-scale pace.
- Bakery:Oxidizing agents and enzymatic strengtheners address flour variability in industrial-scale operations. Clean-label pressures are accelerating phospholipase adoption.
- Snacks:Antioxidants and flavor enhancers protect lipid-rich formulations in extruded and fried categories. Synthetic BHA and BHT dependence exposes compounders to Asian precursor supply concentration.
Beverages absorb the largest additive volumes; dairy applications show the steepest expansion trajectory as UHT penetration deepens.
End User:
Customer scale determines certification requirements and technical service intensity.
- Food Processing:Industrial manufacturers in Nigeria's Atlantic corridor and South Africa's Gauteng belt demand ISO 22000-compliant suppliers with documented hazard-critical control points.
- Retail:Private-label packaged goods buyers in Egypt's Cairo-Alexandria corridors are tightening clean-label procurement standards.
- Catering Services:Institutional and hospitality channels prioritize cost-stable bulk formulations with extended ambient storage compatibility.
- Households:Small-scale artisanal producers access additives through repackaged specialty store channels with minimal technical support.
Food processing commands the dominant share; retail channels are expanding most quickly as supermarket private-label programs mature.
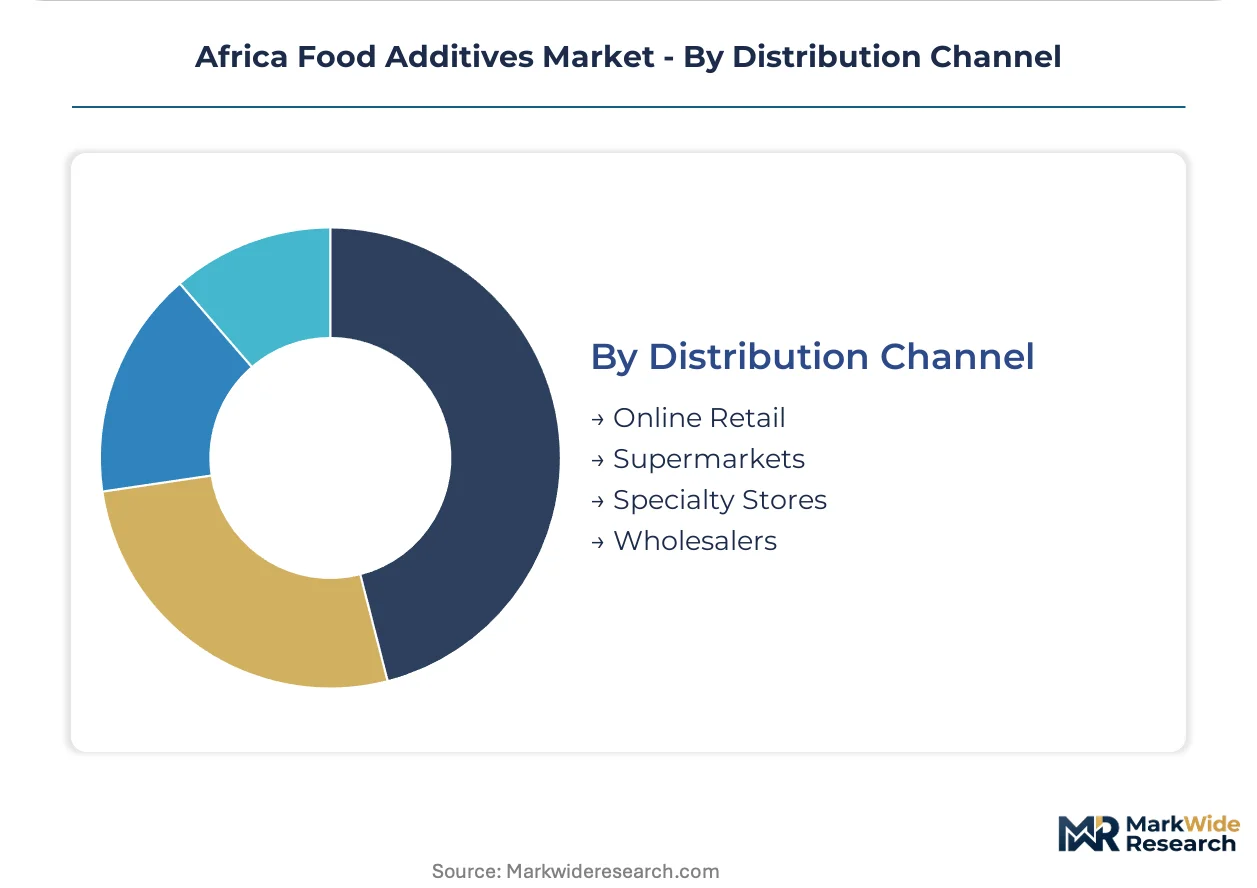
Distribution Channel:
Channel structure determines traceability depth and margin compression potential.
- Wholesalers:Traditional distributors serving mid-scale Nigerian processors face margin compression from direct-to-processor digital platforms.
- Supermarkets:Organized retail chains in South Africa and Kenya consolidate additive procurement for private-label manufacturing subsidiaries.
- Online Retail:B2B platforms connecting certified suppliers with Lagos-Abuja manufacturers are accelerating sample-to-contract cycles.
- Specialty Stores:Technical ingredient suppliers serve artisanal bakeries and small dairy processors with customized blends and formulation support.
Wholesalers retain the largest throughput share; online retail is climbing the fastest as digital traceability systems reshape supplier qualification protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational beverage and dairy processors in Lagos-Abuja, Johannesburg-Pretoria, and Nairobi corridors now dictate additive procurement volumes, replacing fragmented distributor networks with direct supplier contracts and consolidated tenders.
Nigeria
Industrial cassava-to-sweetener investments and sucrose-reduced beverage reformulation drive procurement shifts. The National Agency for Food and Drug Administration and Control enforces additive maximum residue limits that filter import registration eligibility. Lagos-Abuja manufacturers now source maltodextrin and glucose syrup from domestic starch modification facilities.
South Africa
Mandatory maize meal and wheat flour fortification sustains mineral premix demand from industrial millers. The Department of Health administers compositional standards that shape supplier qualification protocols. Gauteng-based dairy processors deploy enzymatic lipid modification systems that decompose traditional lecithin volumes.
Kenya
Export-oriented bakery and dairy production accelerates clean-label enzymatic adoption. The Bureau of Standards tightens synthetic colorant limits for confectionery, forcing extended toxicological dossiers. Nairobi industrial zones witness phospholipase and lipase preparation scaling from pilot to commercial volumes.
Egypt
Retailer procurement standards in packaged goods tighten clean-label requirements ahead of supply base compliance. The country's national food safety authority aligns gradual Codex Alimentarius adoption with domestic enforcement timelines. Cairo-Alexandria corridor manufacturers pre-register natural additive portfolios to capture first-mover positioning.
Ghana
West African sourcing hub expansion supports natural colorant concentrate supply to regional compounders. Weather-dependent annatto and turmeric harvests create formulation cost volatility for confectionery exporters. Accra-Tema industrial zones develop batch-traceability infrastructure to meet ISO 22000 documentation demands from multinational buyers.
Africa Food Additives Market Competitive Environment
Player mix skews toward integrated multinationals with Africa-specific sourcing infrastructure and regional specialists with formulation technical service capabilities. Three strategic archetypes dominate: global ingredient conglomerates with captive West African supply chains, European starch modification specialists serving dairy and bakery verticals, and clean-label portfolio providers aligned with retailer procurement standards. Competitive moves concentrate on backward integration into domestic raw material processing and direct-to-processor digital distribution platform deployment.
Among the integrated multinational tier, Cargill Incorporated anchors procurement leverage through West African sourcing hub control. Tate & Lyle PLC occupies a position exemplifying specialized starch modification capabilities for regional dairy processors. Ingredion Incorporated represents the clean-label archetype with documented natural additive portfolios pre-qualified for Nigeria and Egypt retailer standards. These three entities sit within distinct competitive vectors—supply chain integration, technical specialization, and label-friendly positioning—rather than direct product overlap.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| CP Kelco U S Inc |
| Chemsystems |
| The Dow Chemical Company |
| Afro-Ingredients Ltd |
| Nile Chemicals |
| PureFood Additives |
| Others |
Value Chain & Pricing Dynamics
ISO 22000 certification gates both supplier qualification and price differentiation across Africa's food additives landscape, forcing procurement officers to pay certification premiums for documented hazard-critical control points while excluding uncertified traders from multinational processor contracts entirely. The resulting price stratification rewards compliant suppliers with tiered contract access and penalizes legacy distributors unable to meet documentation standards.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate sweetener and preservative procurement in Nigeria's Lagos-Abuja corridor, linking maltodextrin and glucose syrup pricing to domestic cassava starch spot markets. Price differentiation separates ISO 22000-certified suppliers from uncertified traders, with certification premiums of fifteen to twenty-five percent reflecting audit documentation and technical service bundling. Cost compression in natural colorants intensifies because weather-dependent annatto and turmeric harvests in Ghana create formulation cost instability. Small-scale artisanal producers exhibit highest price sensitivity, while multinational beverage conglomerates prioritize supply security over unit cost minimization.
Supply Chain Analysis
Strategic stockpiling of synthetic antioxidant precursors prevails among Nigerian compounders confronting supply concentration risk, while Kenyan dairy processors favor just-in-time enzymatic preparation deliveries to minimize cold-chain inventory exposure. Geographic supply concentration centers on China, India, and South Korea for BHA and BHT intermediates, with West African sourcing hubs in Ghana and Nigeria feeding natural colorant concentrates. Raw material dependencies encompass cassava starch, annatto extracts, and phospholipase enzymes. Single-source vulnerability in Asian antioxidant precursor supply exposes compounders to freight and currency shocks. Distribution runs through direct-to-processor digital platforms and traditional wholesaler networks serving mid-scale manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against enzymatic substitution decomposing traditional emulsifier demand, as lipase and phospholipase systems displace commodity lecithin volumes in South African and Kenyan bakery applications.
For Market Incumbents: Secure backward integration into domestic cassava starch modification capacity in Nigeria to lock in maltodextrin supply cost discipline against import dependency. Invest in ISO 22000 certification body accreditation partnerships to reduce six-to-nine-month auditor queue delays threatening facility qualification timelines. The enzymatic substitution threat demands repositioning around functional emulsifier blends that lipase systems cannot replicate. For New Entrants and Emerging Players: Technical service gaps in formulation support for mid-scale Kenyan dairy processors present white-space entry points where incumbents under-serve with standardized product catalogs. Egypt's Cairo-Alexandria clean-label segment offers lowest competitive density among major African markets, with retailer procurement standards tightening ahead of supply base compliance. A digital-native direct-to-processor platform targeting Lagos-Abuja manufacturers with accelerated sample-to-contract cycles provides the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic preparation manufacturing as toll production and contract fermentation reduce fixed asset requirements. Long-term viability through the next decade favors acquisition targets possessing documented natural additive portfolios pre-qualified for Nigeria NAFDAC and Egypt retailer standards. The signal to watch is Codex Alimentarius harmonization adoption velocity across national food safety authorities, which would compress fragmented registration burdens and reward early-compliant suppliers with temporary arbitrage windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Starch Modification | Nigerian cassava-to-sweetener investments reduce import dependency for beverage reformulation. |
| ISO 22000 Certification Acceleration | Johannesburg and Nairobi auditor queue delays threaten facility qualification timelines for multinational contracts. |
| Clean-Label Portfolio Pre-Registration | Egypt's tightening retailer procurement standards reward first-mover natural additive positioning in Cairo-Alexandria corridors. |
| Direct-to-Processor Digital Platform Deployment | B2B connectivity compresses traditional distributor margins and accelerates sample-to-contract cycles in Lagos-Abuja. |
| Enzymatic Preparation Manufacturing Scale-Up | Lipase and phospholipase commercial volumes decompose traditional lecithin demand in South African and Kenyan dairy processing. |
Study Parameters
A spread of perspectives from food processing procurement officers, regulatory affairs specialists at national food safety authorities, technical R&D directors at starch modification facilities, and distribution channel partners converged on the working assumptions underlying this analysis. Primary interviews combined with secondary validation from NAFDAC registration databases, Kenya Bureau of Standards enforcement bulletins, South African Department of Health fortification guidelines, and customs trade records. Bottom-up facility capacity assessments and top-down demand modeling triangulated volume estimates across the projection horizon.
Segmentation dimensions modeled encompass functional product category, end-use application, customer scale tier, and distribution channel structure, with additional granularity on certification status and geographic sourcing zone. CAGRs derive from regression-based trajectory fitting against historical procurement patterns and policy implementation timelines. Industry-specific forecast inputs include cassava starch processing capacity buildout schedules and Codex Alimentarius harmonization adoption velocity across national regulators.
Forecasts assume regulatory continuity in Nigeria NAFDAC enforcement, South African fortification mandates, and Kenya Bureau of Standards residue limits; material policy shifts would require re-modeling qualification burdens and supplier eligibility filters. Revision becomes warranted when enzymatic substitution rates in bakery and dairy applications cross thresholds that structurally decompose traditional emulsifier demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Latin America Food Enzymes Market
Food Additives and Ingredients
China Food Preservatives Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
North America Food Micronized Salt Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Pet Food Emulsifier Market
Food Additives and Ingredients
Monoglyceride Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market