
 United Arab Emirates Residential Real Estate Market | 2026-2036
United Arab Emirates Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Residential Real Estate Market Analytics
Direct-to-buyer digital sales channels are reshaping how UAE residential inventory reaches end users, bypassing traditional brokerage layers. Emaar Properties leverages its proprietary online platform to control buyer journeys from inquiry to contract. Aldar Properties anchors its Abu Dhabi dominance through integrated master-plan developments with captive retail and education assets. DAMAC Properties differentiates via branded residence partnerships that sustain premium pricing power.
United Arab Emirates residential real estate encompasses built-for-sale and built-for-rent dwelling units across freehold and leasehold tenure structures, typically delivered through concrete-frame construction with district cooling and smart home infrastructure. The primary purpose is to house a population where expatriates constitute roughly eighty-eight percent of residents, creating perpetual demand for leasehold and freehold product. Apartments dominate transaction volumes across Dubai and Sharjah, while villas command the deepest margin pools in Abu Dhabi's prime districts. First-time buyers face structural supply constraints in affordable tiers, pushing demand concentration into mid-range apartments. Investors from South Asia and Europe gravitate toward studio and one-bedroom units for rental yield optimization.
MOHAP, the Dubai Land Department, and RERA collectively govern off-plan sales escrow compliance, property registration, and broker licensing standards that determine market access legitimacy. RERA's mandatory registration of all sales and rental contracts through the Ejari system creates transaction transparency that underpins mortgage underwriting and dispute resolution. Stakeholders must monitor how Dubai's updated escrow release schedules and Abu Dhabi's emerging rent-cap policies alter developer cash flow timing and investor return profiles.
Market Dynamics
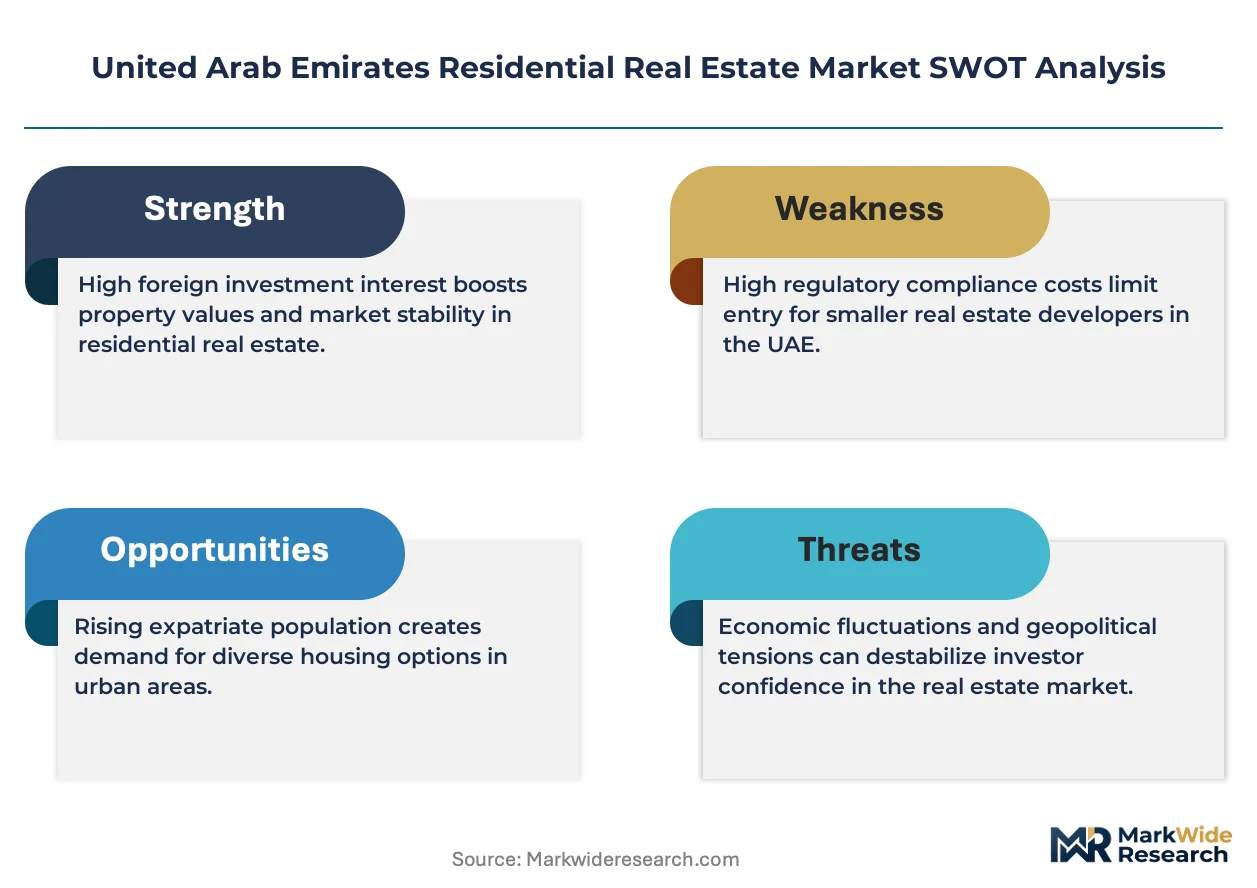
MOHAP's updated escrow account regulations for off-plan sales are tightening developer capital requirements and fundamentally restructuring how UAE residential projects secure financing, forcing developers toward alternative funding instruments and accelerating consolidation among mid-tier builders.
Growth Catalysts
- High-net-worth expatriate inflows:Buyers from India, the United Kingdom, and Russia are expanding their footprint in Dubai's premium villa segment, sustaining transaction velocity in the upper price tiers.
- Ejari system transparency:RERA's mandatory registration of all sales and rental contracts creates transaction visibility that underpins mortgage underwriting and dispute resolution, reducing counterparty risk for institutional capital.
- Smart home infrastructure penetration:District cooling integration with IoT-enabled energy management is becoming standard in new concrete-frame construction, attracting technology-forward buyers.
Market Restraints
- Escrow release schedule compression:MOHAP's tightened capital release timelines are constraining developer working capital and extending project completion cycles.
- Affordable tier supply scarcity:Structural land allocation limitations in Dubai and Sharjah are preventing first-time buyer product from reaching planned absorption volumes.
- Construction input cost volatility:Steel and aluminum price fluctuations are compressing margins on mid-range apartment developments where pricing power remains constrained.
Strategic Opportunities
- Saadiyat Island cultural district expansion:Abu Dhabi's positioning of this cluster as a cultural address is attracting institutional hospitality-residential hybrid investment.
- Direct-to-buyer digital channels:Proprietary online platforms are bypassing traditional brokerage layers, capturing margin previously distributed to intermediaries.
- Branded residence partnerships:Hospitality-operator co-development models are sustaining premium pricing power through service-integrated ownership structures.
Industry Challenges
- Broker licensing compliance complexity:RERA's evolving credentialing requirements are creating operational friction for sales teams managing cross-emirate transactions.
- Legacy system integration with smart infrastructure:Retrofitting district cooling and home automation into existing building management systems requires specialized technical expertise that remains scarce in the contracting base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Residential Real Estate Market |
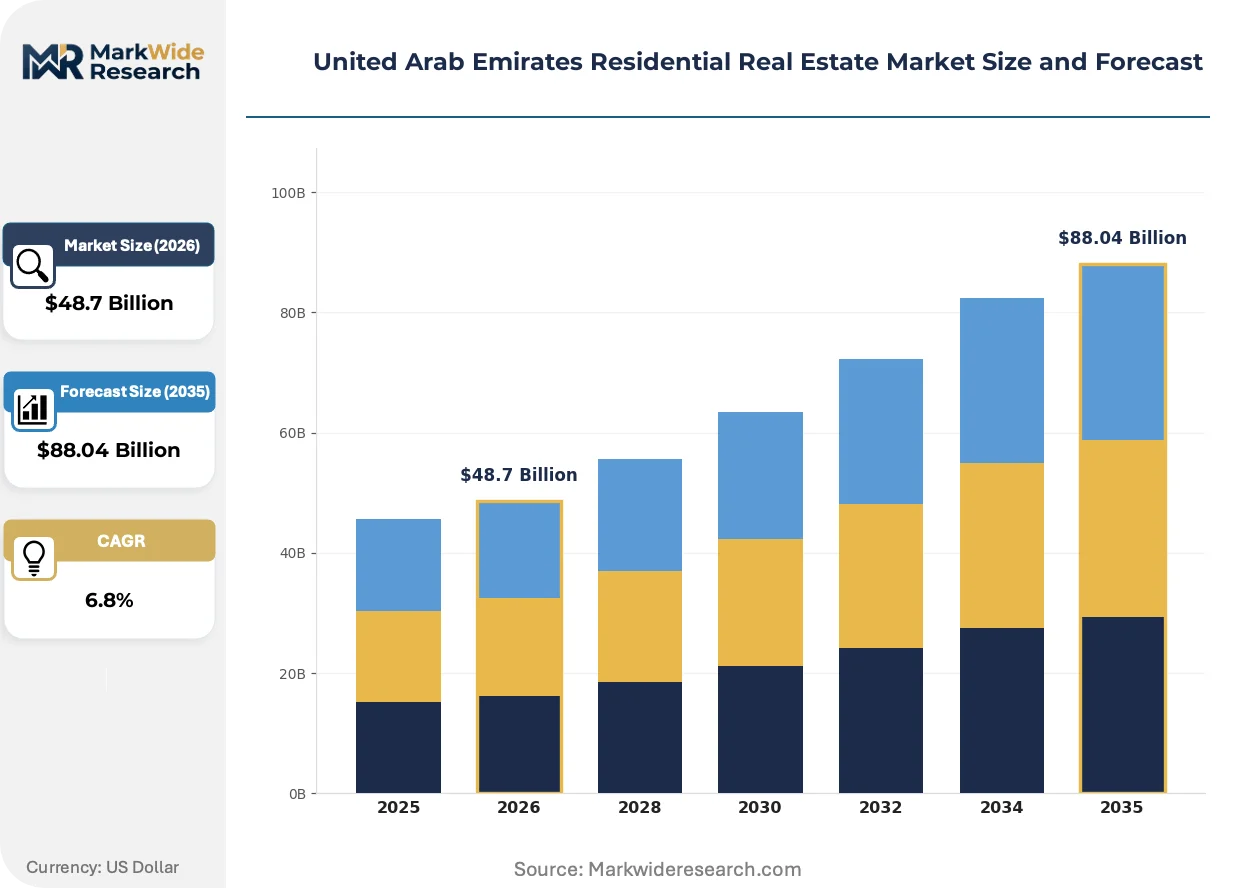
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Apartment, Villa, Townhouse, Studio Customer Type: First-Time Buyers, Investors, Renters, Expats Price Tier: Luxury, Mid-Range, Affordable, Budget Sale Channel: Direct Sales, Real Estate Agents, Online Platforms, Auctions |
| Companies Covered | Aldar Properties, Meraas, Emaar Properties, Select Group, Ellington Properties, Nakheel, Sobha Realty, Mira Developments, DAMAC Properties, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Residential Real Estate Market Evolving Landscape
Digital sales infrastructure and regulatory transparency mandates are converging to reshape how UAE residential inventory reaches end users, compressing transaction timelines while elevating compliance burdens on developers.
PropTech platforms for virtual staging and contract execution are hybridizing the buyer journey across inquiry, due diligence, and closing phases. High-net-worth expatriate segments are adopting these tools fastest, with waterfront and golf course community developers reporting compressed sales cycles. This technology is hybridizing traditional brokerage functions into developer-controlled digital ecosystems that capture customer data and reduce intermediary dependence.
MOHAP's escrow account regulations are tightening capital requirements for off-plan sales, forcing developers toward alternative financing structures. The industrial consequence is a bifurcation between large master-plan developers with captive balance sheet capacity and mid-tier builders facing liquidity constraints. Abu Dhabi's emerging rent-cap policies are creating parallel pressure, with institutional investors in Saadiyat Island repositioning toward shorter-hold strategies.
Buyers are consolidating purchase decisions around rental yield optimization rather than capital appreciation expectations, particularly for studio and one-bedroom units. Traditional brokerage channels are losing share to developer-direct platforms and referral networks among South Asian and European investor communities. Dubai's mid-range apartment segment is experiencing this shift most visibly, with transaction volumes concentrating in developments offering guaranteed rental management programs.
United Arab Emirates Residential Real Estate Market Segmentation
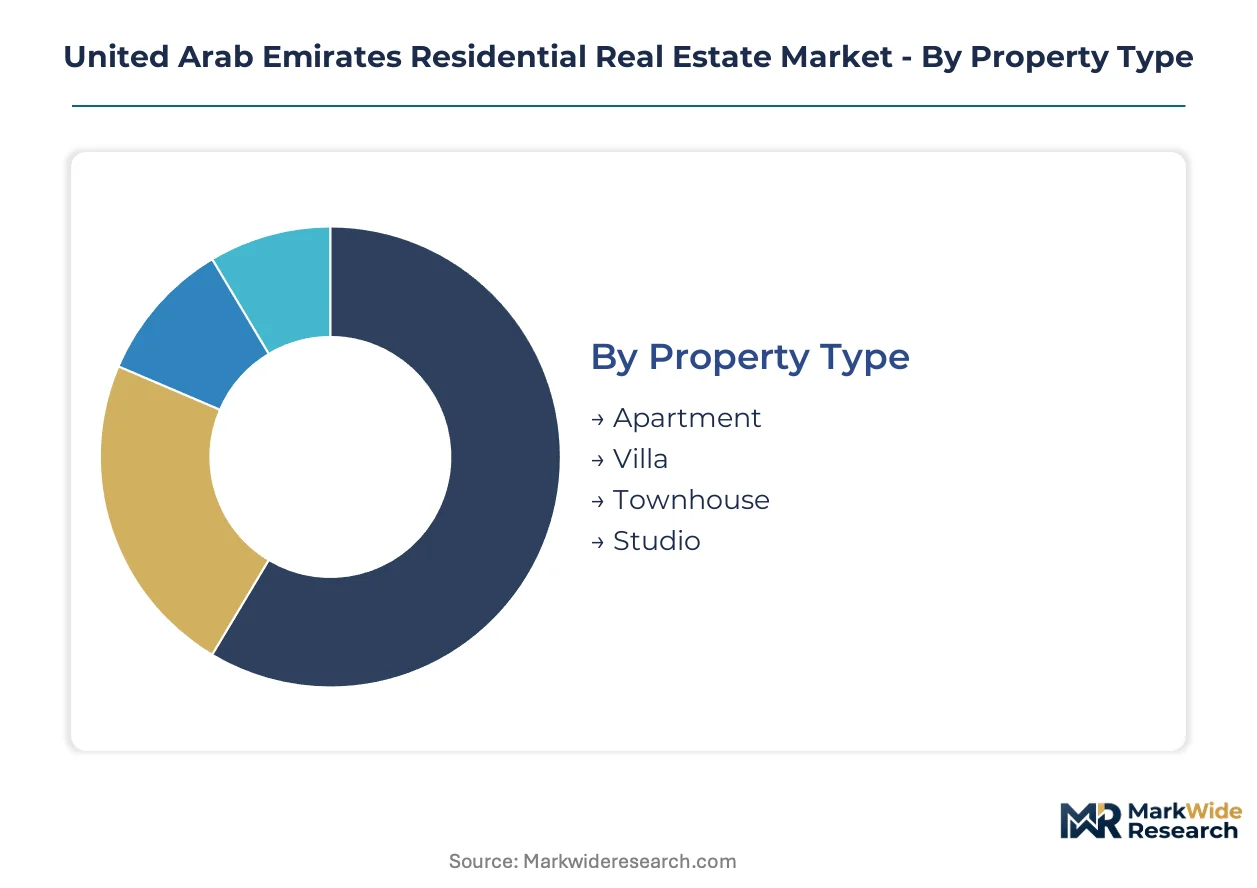
Segmentation in UAE residential real estate reveals divergent liquidity profiles across property types and buyer categories. Transaction velocity varies dramatically between investor-driven studio units and family-occupied villas, while digital channels are compressing sales cycles for specific customer segments.
Property Type:
Apartments turn inventory fastest with institutional buyer participation, while villas cycle slower but capture deeper margin pools per transaction.
- Apartment:Concrete-frame multi-unit structures dominate Dubai and Sharjah transaction volumes. Demand concentrates in waterfront districts and transit-proximate clusters where South Asian and European investors optimize rental yield on studio and one-bedroom configurations.
- Villa:Detached and semi-detached single-family dwellings command premium pricing in Abu Dhabi's Saadiyat Island and Dubai's golf course communities. High-net-worth expatriate buyers from India, the United Kingdom, and Russia sustain transaction velocity in this segment despite extended due diligence periods.
- Townhouse:Medium-density attached housing bridges apartment efficiency with villa spatial standards. First-time families in Dubai's mid-range districts favor this format where land allocation constraints limit detached supply.
- Studio:Compact single-room units represent the entry threshold for investor portfolios. Ejari-registered rental contracts underpin mortgage underwriting for this high-turnover category.
Apartments anchor the volume base while villas gain share at the steepest rate among premium buyer cohorts.
Customer Type:
Investor and expatriate segments drive transaction velocity through standardized purchase patterns, while first-time buyers face extended decision cycles amid supply scarcity.
- First-Time Buyers:Domestic and long-term resident purchasers seeking primary residence security. Structural supply constraints in affordable tiers push this cohort toward mid-range apartments with extended mortgage tenors.
- Investors:Yield-focused purchasers prioritizing rental income over capital appreciation. This segment adopts direct-to-buyer digital platforms fastest, bypassing traditional brokerage layers.
- Renters:Leasehold occupants constituting the majority of UAE residents given eighty-eight percent expatriate population composition. RERA's mandatory Ejari registration creates contract transparency that underpins institutional landlord participation.
- Expats:Foreign nationals purchasing freehold units in designated zones. MOHAP's escrow account regulations reduce counterparty risk for this geographically dispersed buyer pool.
Investors generate the highest transaction frequency while first-time buyers show the steepest unmet demand growth.
Price Tier:
Cost stratification determines financing structure and buyer access, with luxury and budget tiers operating on fundamentally different capital sources.
- Luxury:Premium-priced assets in prime waterfront and cultural district addresses. Branded residence partnerships with hospitality operators sustain pricing power through service-integrated ownership structures.
- Mid-Range:The primary battleground for Dubai's apartment developers. Guaranteed rental management programs increasingly influence purchase decisions in this crowded tier.
- Affordable:Entry-level ownership products facing structural land allocation limitations. MOHAP's tightened escrow release schedules constrain developer working capital for this lower-margin category.
- Budget:Subsidized and workforce housing segments with regulated pricing. Abu Dhabi's emerging rent-cap policies create parallel pressure on institutional investor returns in adjacent tiers.
Mid-range assets anchor developer revenue while luxury inventory climbs the fastest in absolute value terms.
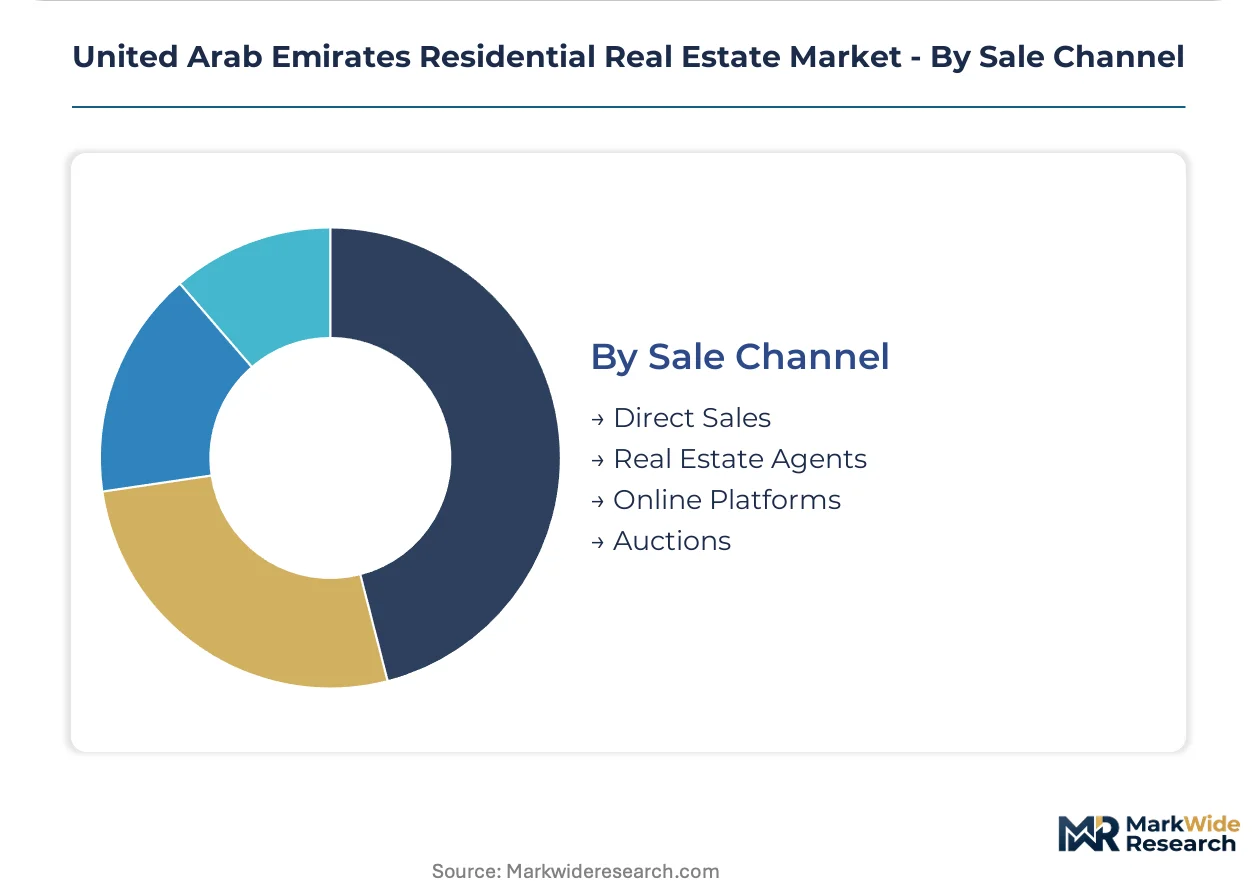
Sale Channel:
Channel selection determines margin capture and customer data ownership, with digital infrastructure displacing traditional intermediation.
- Direct Sales:Developer-controlled platforms capturing buyer journeys from inquiry to contract. Emaar Properties leverages proprietary digital infrastructure to reduce intermediary dependence.
- Real Estate Agents:Traditional brokerage facing share erosion from digital alternatives. RERA's evolving credentialing requirements create operational friction for cross-emirate transactions.
- Online Platforms:PropTech-enabled virtual staging and contract execution tools. High-net-worth segments adopt these fastest, compressing sales cycles for waterfront and golf course inventory.
- Auctions:Distressed and premium asset disposal mechanism with limited current deployment. Institutional sellers occasionally utilize this channel for portfolio rebalancing.
Direct sales channels anchor volume growth while online platforms expand most quickly in buyer adoption metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP's escrow account regulations and RERA's Ejari registration mandates are reshaping capital flows and transaction transparency across the Emirates. Dubai and Abu Dhabi anchor development activity, while Sharjah and the Northern Emirates capture spillover demand from supply-constrained prime markets.
Dubai
High-net-worth expatriate buyers from India, the United Kingdom, and Russia sustain transaction velocity in waterfront and golf course communities. RERA's mandatory Ejari system underpins mortgage underwriting and dispute resolution, reducing counterparty risk for institutional capital. The Dubai Land Department governs off-plan sales compliance, with master-plan developers leveraging proprietary digital platforms to bypass traditional brokerage layers.
Abu Dhabi
Saadiyat Island gains traction as a cultural district address, attracting institutional hospitality-residential hybrid investment. Emerging rent-cap policies create pressure on investor return profiles, prompting shorter-hold strategies among institutional landlords. Aldar Properties anchors market dominance through integrated developments with captive retail and education assets in prime districts.
Sharjah
First-time families favor medium-density townhouses where land allocation constraints limit detached villa supply. Structural affordable tier scarcity pushes demand concentration into mid-range apartments with extended mortgage tenors. The emirate's leasehold structures serve the majority expatriate population seeking ownership alternatives to Dubai's premium pricing.
Northern Emirates
Ajman, Ras Al Khaimah, and Fujairah capture budget-conscious buyers priced out of prime Dubai and Abu Dhabi markets. Workforce housing segments with regulated pricing attract South Asian investor communities optimizing rental yield on studio configurations. Limited master-plan development activity concentrates transaction volumes in scattered mid-range apartment projects.
United Arab Emirates Residential Real Estate Market Competitive Landscape
On the supply side, the industry is consolidating around large master-plan developers with captive balance sheet capacity, while mid-tier builders face liquidity constraints from tightened escrow release schedules. Three archetypes dominate: integrated master-plan developers controlling end-to-end value chains, branded residence specialists leveraging hospitality partnerships, and mid-tier builders dependent on alternative financing instruments. Competitive moves center on direct-to-buyer digital channel expansion and strategic consolidation to absorb distressed project pipelines.
Within the integrated developer tier, Emaar Properties exemplifies supply-side concentration through proprietary platform control over buyer journeys from inquiry to contract. Aldar Properties anchors Abu Dhabi dominance through captive balance sheet deployment across mixed-use ecosystems. DAMAC Properties occupies the branded residence specialization vector, sustaining premium pricing power through hospitality-operator co-development structures.
| Leading Market Players |
|---|
| Aldar Properties |
| Meraas |
| Emaar Properties |
| Select Group |
| Ellington Properties |
| Nakheel |
| Sobha Realty |
| Mira Developments |
| DAMAC Properties |
| Others |
Value Network & Pricing Analysis
Steel and aluminum sourcing from China, India, and Turkey anchors construction input costs for UAE residential developers, with volatility in these feedstocks compressing margins most severely in Dubai's mid-range apartment segment where pricing power remains constrained by oversupply.
Pricing Analysis
Volume-discount tiering structures separate luxury waterfront villas from mid-range apartments and budget workforce housing. Pricing stratifies across premium, standard, and economy tiers based on location proximity to cultural districts and golf course amenities, with brand affiliation to hospitality operators commanding additional premiums. Cost compression in mid-range apartments is intensifying because construction input volatility cannot be passed through to yield-sensitive investors. First-time buyers in affordable tiers exhibit highest price sensitivity, while high-net-worth expatriates purchasing Saadiyat Island villas show lowest elasticity.
Supply Chain Analysis
Extended payment terms from Chinese and Indian steel suppliers have become critical working capital bridges for mid-tier developers facing MOHAP's tightened escrow release schedules. Raw material dependencies center on structural steel, aluminum curtain wall systems, and district cooling equipment sourced predominantly from China, South Korea, and Germany. Single-source vulnerability in specialized HVAC components creates project delay risk. Distribution runs through developer-procurement teams managing direct relationships with EPC contractors, bypassing traditional materials trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE residential market sits in a cyclical recovery phase supported by sustained high-net-worth expatriate inflows from India, the United Kingdom, and Russia.
For Market Incumbents: Entrench market position through accelerated consolidation of distressed mid-tier developer pipelines and captive control over district cooling infrastructure. Escrow regulation tightening threatens smaller competitors with liquidity failure. Backward integration into smart home technology supply secures margin capture from technology-forward buyer segments. For New Entrants and Emerging Players: Establish a beachhead in Sharjah's townhouse segment where land allocation constraints limit detached supply and first-time family demand runs ahead of inventory. The Northern Emirates workforce housing tier offers parallel white-space opportunity with regulated pricing attracting South Asian investor communities. Partner with PropTech platforms for virtual staging and contract execution to compress customer acquisition costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier developers facing working capital strain from compressed escrow release timelines. Long-term viability hinges on master-plan scale and captive retail or education asset integration. Watch for inflection in MOHAP's enforcement posture on alternative financing structures as signal for consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Buyer Digital Platform Launch | Emaar Properties' proprietary infrastructure captures buyer data and eliminates brokerage margin leakage. |
| Branded Residence Partnership Expansion | DAMAC Properties' hospitality-operator co-development sustains premium pricing through service-integrated ownership. |
| Master-Plan Ecosystem Integration | Aldar Properties anchors Abu Dhabi dominance through captive retail and education assets in prime districts. |
| Escrow Compliance Infrastructure Investment | MOHAP's tightened capital requirements favor developers with balance sheet capacity for alternative financing. |
| Saadiyat Island Cultural District Positioning | Institutional hospitality-residential hybrid investment flows toward Abu Dhabi's emerging cultural address. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with property development executives, RERA-licensed brokerage principals, institutional investment officers, and district cooling infrastructure managers. Secondary validation drew from Dubai Land Department transaction records, MOHAP regulatory filings, Ejari registration databases, and master-plan developer disclosure documents. Bottom-up unit absorption estimates and top-down macroeconomic indicators were triangulated to anchor market sizing.
Calibration against historical transaction velocity and supply pipeline data shaped the analytical framework across the analysis window. Segmentation dimensions modeled include property type, customer archetype, price tier, and sale channel structure. CAGRs were derived from regression analysis of absorption rates against population inflow and mortgage origination trends. Forecast inputs incorporated escrow regulation implementation timelines and expatriate visa policy evolution.
Stress conditions across steel price volatility, expatriate inflow disruption, and escrow enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and construction cost normalization. Macroeconomic contraction, further escrow tightening, or technological disruption in PropTech distribution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
E House Market
Residential Real Estate Market
Europe Residential Real Estate Market
Residential Real Estate Market
Qatar Manufactured Homes Market
Residential Real Estate Market
Singapore Real Estate Market
Residential Real Estate Market
US E-House Market
Residential Real Estate Market
Latin America Residential Real Estate Market
Residential Real Estate Market
France Luxury Residential Real Estate Market
Residential Real Estate Market
Spain Manufactured Homes Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
Mexico Residential Real Estate Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Germany Manufactured Homes Market
Residential Real Estate Market
Canada Residential Real Estate Market
Residential Real Estate Market
India Residential Construction Market