
 Thailand Real Estate Market | 2026-2036
Thailand Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Real Estate Market Outlook
Building information modeling adoption is narrowing the design-to-delivery cycle for Thai developers. Asset World Corp Public Company Ltd leverages its hospitality-heavy portfolio to dominate Bangkok's riverside regeneration zone. Frasers Property (Thailand) anchors its competitiveness through integrated retail-residential complexes in secondary provinces. Central Pattana Public Company Ltd sustains market leadership via captive footfall data that shapes mixed-use site selection.
Thailand real estate encompasses land and permanent structures developed for residential habitation, commercial activity, or industrial production, with specifications governed by the Thai Building Control Act and local environmental impact assessments that mandate seismic resilience and flood mitigation in designated zones. Its primary purpose centers on wealth storage, rental income generation, and operational space provision for households and enterprises. Residential property leads transaction volume yet industrial land in the Eastern Economic Corridor posts the fastest value appreciation as manufacturing relocates from China. REITs concentrate institutional capital in income-generating commercial assets while direct ownership retains dominance among domestic retail investors seeking inflation hedges.
The Condominium Act administered by Thailand's Land Department shapes foreign buyer participation through ownership ratio caps, while the Board of Investment coordinates zoning incentives for industrial estate developers. Thailand's central bank, the Bank of Thailand, calibrates mortgage lending rules that directly throttle or release household purchasing capacity. Stakeholders must monitor whether infrastructure completion timelines for the Eastern Economic Corridor align with industrial land absorption rates or create supply-demand mismatches.
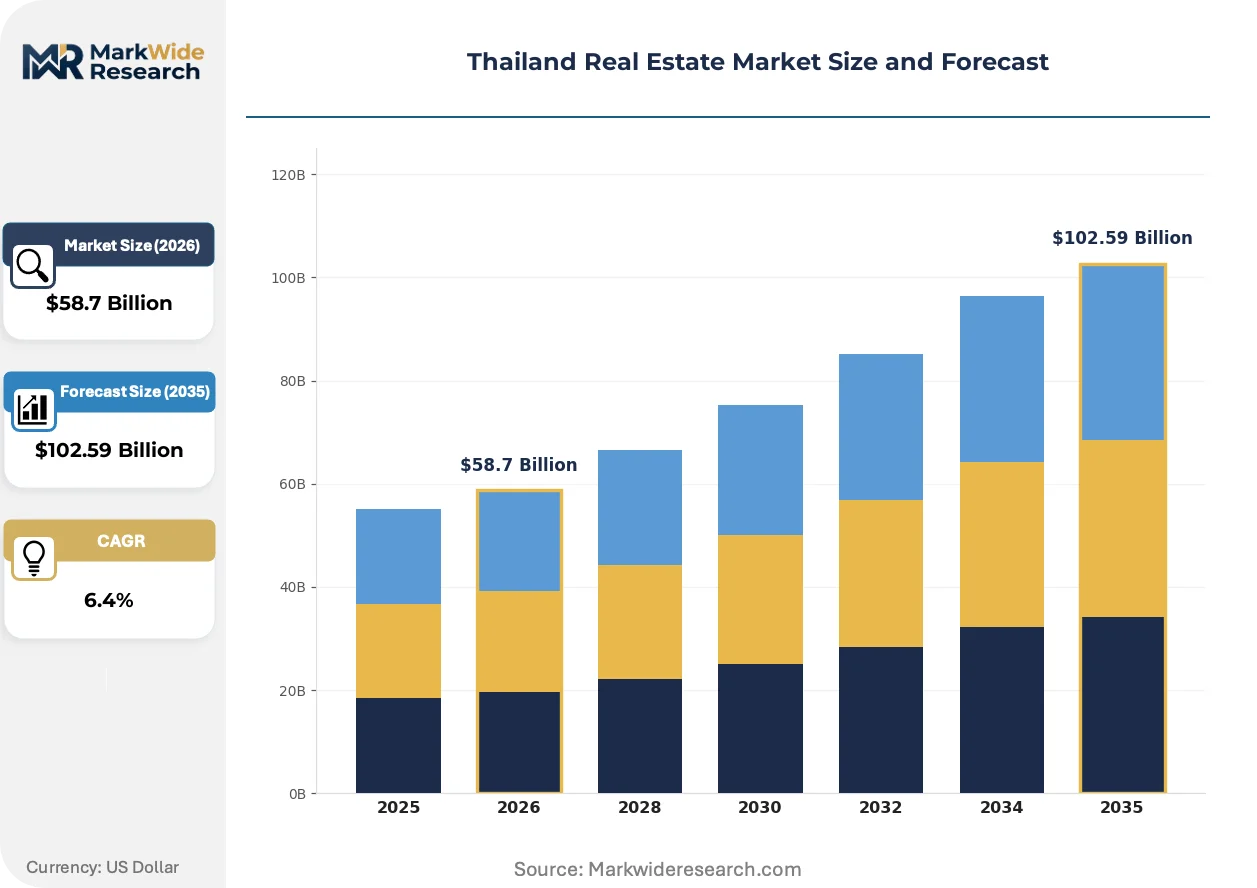
Market Dynamics
Thailand's real estate sector pivots on foreign capital inflows channeled through the Board of Investment's zoning incentives and the Bank of Thailand's mortgage lending calibration. Institutional investors target income-generating assets while domestic households navigate credit tightening.
Growth Catalysts
- Eastern Economic Corridor infrastructure:Industrial land absorption accelerates as manufacturing relocates from China, with the Board of Investment offering tax holidays for estate developers.
- Condominium Act amendments:Foreign ownership ratio relaxation draws cross-border buyers into Greater Bangkok's high-rise residential pipeline.
- Building information modeling:Design-to-delivery cycle compression reduces construction timelines for Thai developers bidding on mixed-use projects.
Market Restraints
- Mortgage lending rules:Bank of Thailand loan-to-value caps throttle household purchasing capacity during credit tightening cycles.
- Flood mitigation mandates:Thai Building Control Act requirements for seismic resilience and drainage infrastructure inflate development costs in designated zones.
- Supply concentration in Greater Bangkok:Transaction volume dominance creates regional price volatility when capital flows shift.
Strategic Opportunities
- Secondary province retail-residential complexes:Frasers Property anchors competitiveness outside Bangkok through integrated developments in underserved provincial hubs.
- REIT channel expansion:Institutional capital concentration in income-generating commercial assets creates liquidity for portfolio holders.
- Riverside regeneration zone:Asset World Corp leverages hospitality-heavy positioning to capture premium valuations along Bangkok's Chao Phraya corridor.
Industry Challenges
- Environmental impact assessment timelines:Local authority approval delays extend project commencement for developments in flood-prone zones.
- Captive footfall data integration:Mixed-use site selection requires merging retail analytics with residential demand forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Real Estate Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $102.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Residential, Commercial, Industrial, Mixed-Use Investment Type: Direct Ownership, REITs, Joint Ventures, Development Projects Buyer Profile: Local Investors, Foreign Investors, Expatriates, Developers Financing Model: Mortgage, Cash Purchase, Leasing, Developer Financing |
| Companies Covered | Asset World Corp Public Company Ltd, Frasers Property (Thailand), Central Pattana Public Company Ltd, Lalin Property Public Company Ltd, Origin Property Public Company Ltd, WHA Corp Public Company Ltd, Amata Corporation, Raimon Land, Land and Houses Public Company Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Real Estate Market Strategic Shifts
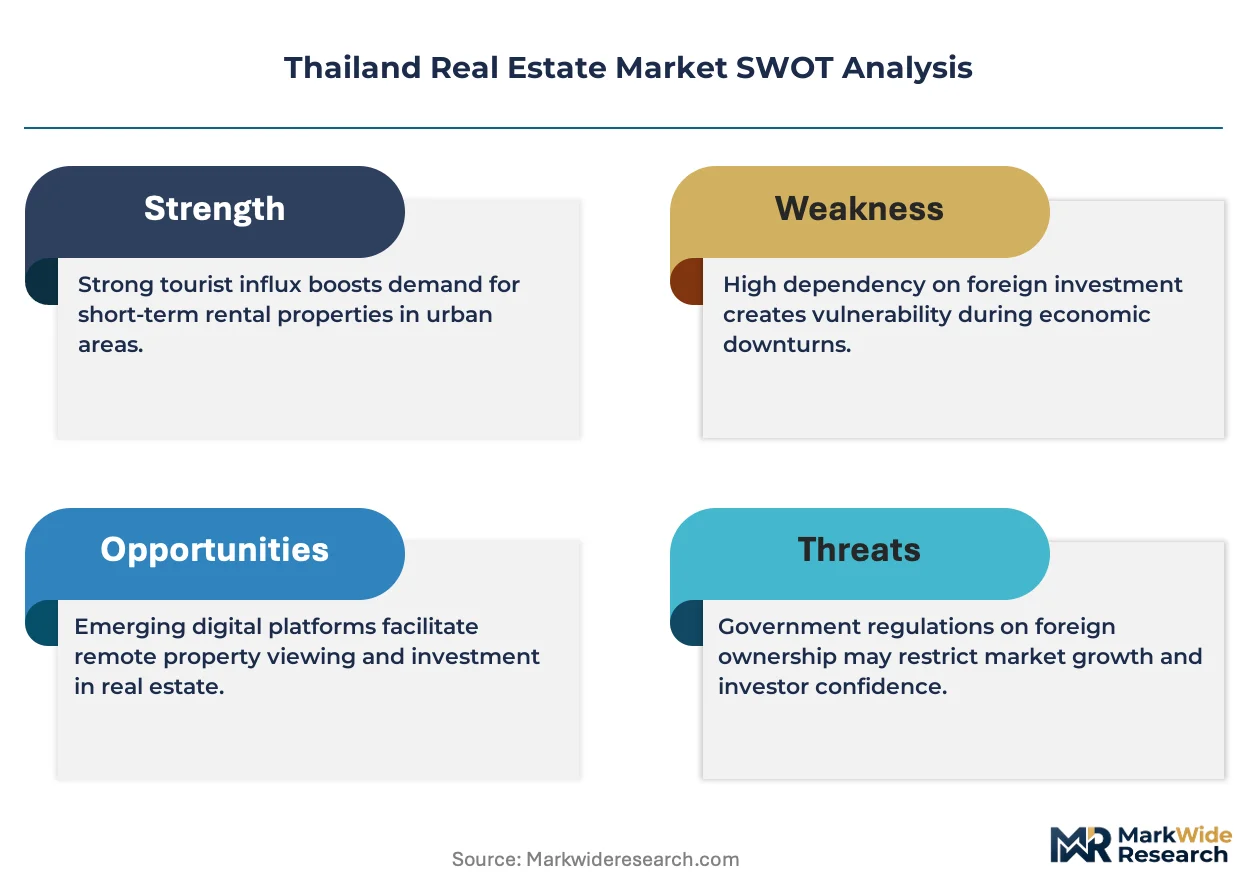
Digital twin technology and sustainability mandates are compressing traditional development cycles while reshaping investor due diligence. Thai developers face pressure to demonstrate environmental compliance before securing institutional capital.
Building information modeling is collapsing the handoff friction between architectural design and construction execution. Mid-tier developers in Greater Bangkok adopt cloud-based coordination platforms to synchronize contractors across multi-phase projects. The technology is collapsing rework rates and accelerating certificate of occupancy timelines for condominium towers.
The Condominium Act amendments administered by Thailand's Land Department reshape foreign buyer eligibility thresholds. Industrial estate developers now coordinate zoning incentives with the Board of Investment's manufacturing relocation targets. Secondary provinces absorb the regulatory tailwind as Bangkok's ownership saturation limits further foreign ratio expansion.
Institutional due diligence now mandates climate risk disclosure for assets in Thailand's flood-prone eastern seaboard. Pension funds and REIT sponsors demand third-party resilience certification before deploying capital into industrial estates. The Eastern Economic Corridor's manufacturing tenants increasingly require flood-mitigation infrastructure as a lease precondition.
Thailand Real Estate Market Segmentation
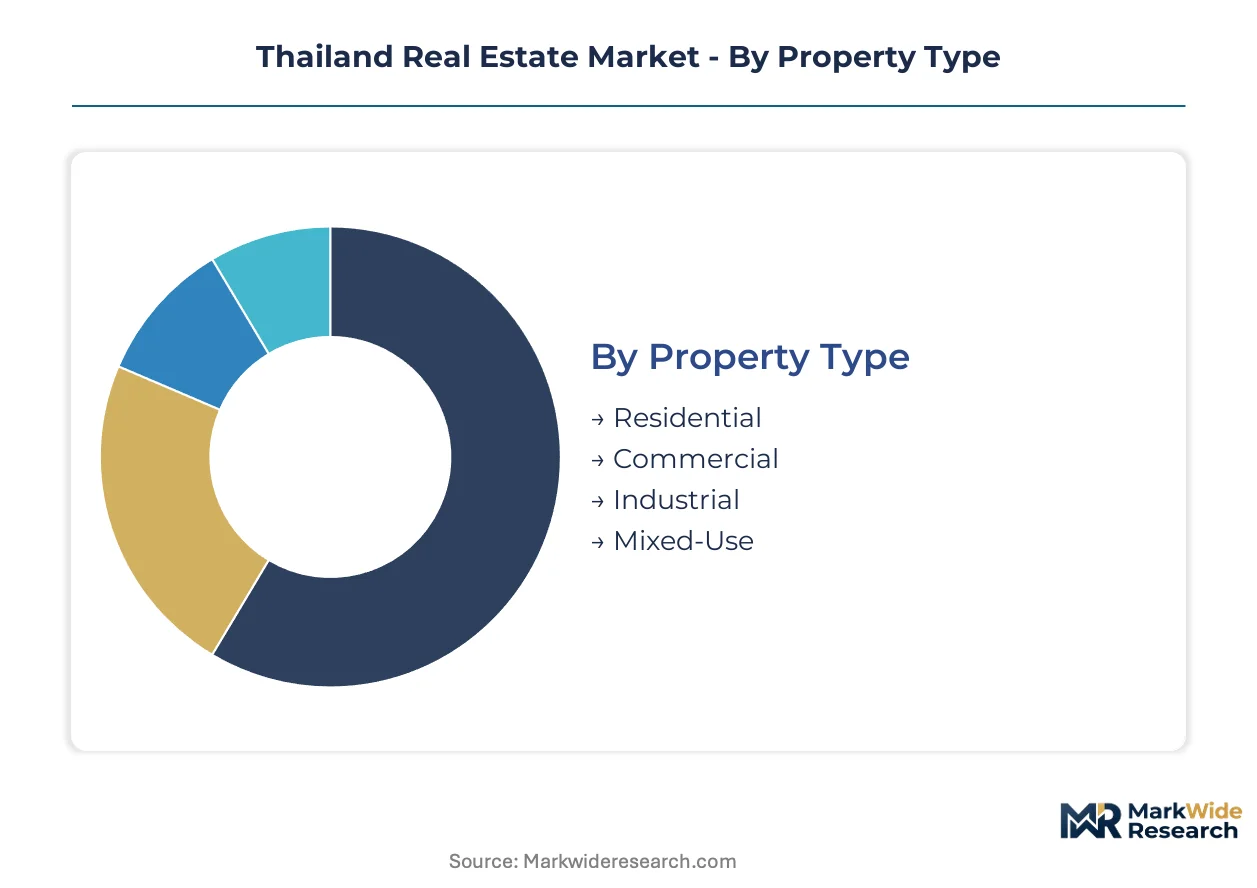
Thailand's real estate segmentation reveals distinct capital velocity profiles across property categories. Transaction cycle lengths vary from months for condominium resales to decades for industrial estate maturation, shaping portfolio construction strategies for domestic and foreign capital pools.
Property Type:
Cycle times compress from industrial land banking through residential condominium turnover, with mixed-use developments occupying intermediate liquidity positions.
- Residential:Condominium units in Greater Bangkok achieve certificate of occupancy within 24-36 months from land acquisition, the shortest development cycle among major property types. Demand concentrates in transit-oriented locations along mass transit extensions, with the Bank of Thailand's loan-to-value ratios directly governing household absorption capacity.
- Commercial:Office and retail assets require 48-60 month development horizons due to tenant pre-commitment requirements and extended lease-up periods. Bangkok's central business district and secondary provincial hubs absorb institutional capital seeking yield compression through captive footfall data integration.
- Industrial:Eastern Economic Corridor land plots extend to 120-month holding periods before full infrastructure maturation and tenant stabilization. Board of Investment tax holidays accelerate developer returns despite elongated timelines, with flood mitigation mandates adding regulatory complexity.
- Mixed-Use:Integrated retail-residential complexes synchronize construction phasing across income streams, requiring coordination platforms to manage interdependent completion schedules.
Residential anchors the volume base while industrial gains share at the steepest rate as manufacturing relocates from China.
Investment Type:
Capital deployment structures stratify by liquidity preference and regulatory exposure, from direct asset control to pooled vehicle participation.
- Direct Ownership:Domestic retail investors retain dominant share for inflation hedging, with foreign buyers constrained by Land Department ownership ratio caps under the Condominium Act. Bangkok's riverside regeneration zone attracts premium valuations for trophy assets held outright.
- REITs:Institutional capital concentrates in income-generating commercial assets, with sponsors demanding climate risk disclosure for eastern seaboard exposure. Pension fund allocations create liquidity for portfolio holders seeking exit pathways.
- Joint Ventures:Foreign capital pairs with local developers to navigate zoning incentives and land assembly complexities, particularly in secondary provinces where Frasers Property anchors integrated retail-residential complexes.
- Development Projects:Ground-up construction carries highest execution risk, with building information modeling adoption compressing design-to-delivery cycles for competitive bidding.
Direct ownership dominates transaction count while REITs expand most quickly as institutional allocation thresholds rise.
Buyer Profile:
Purchasing capacity and regulatory eligibility create distinct demand segments with divergent price sensitivity and holding period expectations.
- Local Investors:Domestic households navigate Bank of Thailand mortgage lending calibration, with credit tightening cycles directly throttling transaction velocity. Secondary provincial markets absorb savings seeking yield beyond deposit rates.
- Foreign Investors:Cross-border capital targets Greater Bangkok's high-rise residential pipeline following Condominium Act amendments relaxing ownership thresholds. Institutional due diligence mandates third-party resilience certification for flood-prone zone exposure.
- Expatriates:Long-term residents in Thailand's manufacturing and services sectors drive rental demand and selective ownership in condominium segments with foreign quota availability.
- Developers:Asset World Corp and Central Pattana Public Company Ltd deploy captive operational data to shape site selection and pricing strategies across mixed-use pipelines.
Local investors anchor the volume base while foreign investors gain share at the steepest rate following regulatory relaxation.
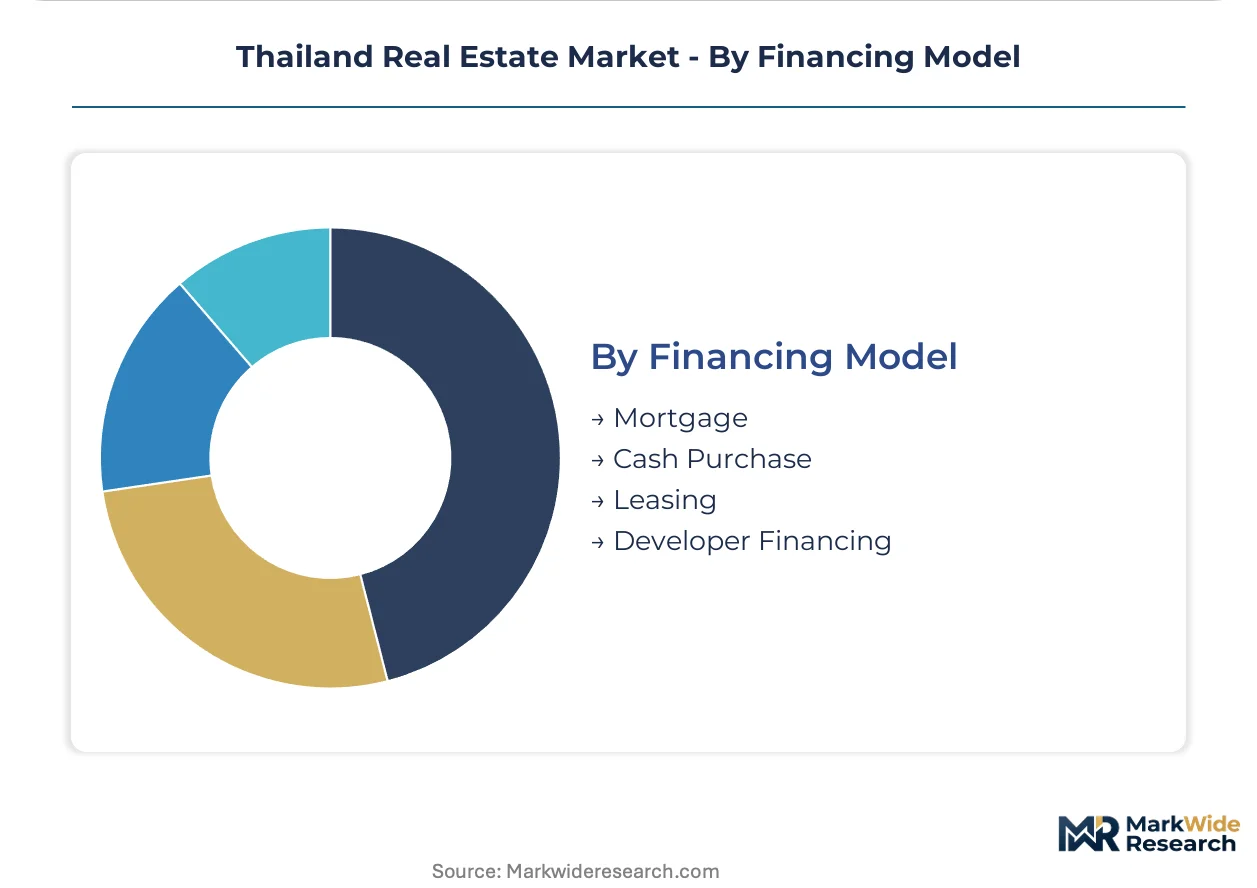
Financing Model:
Capital structure choices reflect buyer regulatory status, asset type liquidity, and interest rate environment sensitivity.
- Mortgage:Bank of Thailand loan-to-value caps govern household leverage capacity, with central bank calibration releasing or constraining purchasing power cyclically. Greater Bangkok's condominium absorption tracks mortgage approval velocity closely.
- Cash Purchase:Foreign buyers and high-net-worth domestic investors bypass credit constraints, concentrating in premium segments where ownership ratio caps limit competitive supply.
- Leasing:Industrial estate tenants in the Eastern Economic Corridor negotiate lease structures with flood-mitigation infrastructure preconditions, shifting capital expenditure burdens to developers.
- Developer Financing:Installment schemes bridge construction-phase funding gaps, with completion risk borne by purchasers until certificate of occupancy issuance.
Mortgage financing anchors the volume base while cash purchases gain share at the steepest rate among foreign buyer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's real estate sector channels cross-border investment flows from Greater Bangkok into the Eastern Economic Corridor, with manufacturing relocation from China driving industrial land absorption across provincial sub-markets.
Greater Bangkok
Mass transit extensions and condominium development attract institutional capital into transit-oriented locations. The Bank of Thailand calibrates loan-to-value caps that govern household purchasing capacity in high-rise residential segments. Asset World Corp anchors riverside regeneration projects along the Chao Phraya corridor.
Eastern Economic Corridor
Industrial estate developers absorb manufacturing demand relocating from China through Board of Investment tax holidays. Flood mitigation mandates under the Thai Building Control Act inflate development costs in designated zones. WHA Corp and Amata Corporation concentrate land banking across Chonburi and Rayong provinces.
Chiang Mai-Chiang Rai Corridor
Secondary provincial markets attract integrated retail-residential complexes seeking yield beyond deposit rates. Local environmental impact assessments extend project commencement timelines in flood-prone northern zones. Frasers Property anchors competitiveness through developments in underserved regional hubs.
Phuket-Krabi Tourism Belt
Hospitality-heavy portfolios capture premium valuations from international visitor recovery and long-stay demand. The Condominium Act's foreign ownership ratio caps constrain supply in coastal condominium segments. Raimon Land occupies positioning within luxury residential developments across island sub-markets.
Northeastern Industrial Hubs
Logistics and distribution centers exploit highway connectivity to Mekong-border trade corridors. Central Pattana deploys captive footfall data to shape mixed-use site selection in Khon Kaen and Udon Thani. Manufacturing tenants require flood-resilience infrastructure as lease preconditions.
Thailand Real Estate Market Competitive Environment
On the supply side, the industry is consolidating around integrated developers with captive operational data and diversified asset portfolios. Listed entities with hospitality, retail, and industrial exposure command valuation premiums over pure-play residential developers. Three archetypes dominate: diversified conglomerates with data-driven site selection, industrial estate specialists leveraging Board of Investment incentives, and mid-tier provincial developers executing joint ventures with foreign capital. Competitive moves center on portfolio diversification across asset classes and geographic expansion into secondary provinces.
Within the diversified conglomerate tier, Asset World Corp Public Company Ltd and Central Pattana Public Company Ltd exemplify developers leveraging captive footfall analytics and hospitality exposure to shape mixed-use pipelines. Frasers Property (Thailand) represents the provincial expansion archetype, anchoring integrated retail-residential complexes outside Bangkok through joint venture structures with foreign capital partners.
| Leading Market Players |
|---|
| Asset World Corp Public Company Ltd |
| Frasers Property (Thailand) |
| Central Pattana Public Company Ltd |
| Lalin Property Public Company Ltd |
| Origin Property Public Company Ltd |
| WHA Corp Public Company Ltd |
| Amata Corporation |
| Raimon Land |
| Land and Houses Public Company Ltd |
| Others |
Value Chain & Pricing Dynamics
Flood mitigation mandates under the Thai Building Control Act create a regulatory chokepoint that determines both pricing tier spreads and supply chain shape. Developers absorbing elevated compliance costs in designated zones pass through premiums that widen spreads between resilient-certified assets and standard inventory.
Pricing Analysis
Technology-generation pricing gaps separate BIM-enabled developments from conventional construction and legacy stock awaiting renovation. Three-tier pricing structure across premium, standard, and economy levels governs Greater Bangkok condominium absorption, with certification grade and seismic resilience ratings as primary differentiation drivers. Pricing pressure stems from Bank of Thailand loan-to-value caps constraining household leverage capacity. Local investors exhibit highest price sensitivity, while foreign cash purchasers in quota-limited segments demonstrate lowest elasticity.
Supply Chain Analysis
Contract manufacturing concentration rests with Thai construction conglomerates and regional engineering firms holding prefabrication capacity across Greater Bangkok and Chonburi. Geographic supply concentration centers on Thailand, China, and South Korea for structural steel, concrete additives, and MEP systems. Raw material dependencies include cement clinker, rebar, and aluminum curtain wall systems. Single-source vulnerability persists for specialized flood-mitigation drainage components. Distribution runs through developer-direct procurement with tiered subcontractor networks executing site installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's real estate sector enters a cyclical recovery phase as manufacturing relocation from China accelerates Eastern Economic Corridor absorption. Bank of Thailand monetary calibration and Board of Investment incentive extensions provide the cyclical driver for this inflection.
For Market Incumbents: Entrench market position through backward integration into captive construction material supply and accelerated BIM adoption compressing design-to-delivery cycles. Asset World Corp and Central Pattana Public Company Ltd should leverage captive footfall data to preempt site selection in secondary provincial hubs before foreign capital joint ventures saturate these markets. Threat substitution from mid-tier developers executing low-margin bidding requires margin defense through certification premiums. For New Entrants and Emerging Players: Pursue integrated retail-residential complexes in Khon Kaen and Udon Thani where Central Pattana's captive data advantage remains underdeveloped. Secondary provincial markets offer the most penetrable geography given Bangkok's ownership saturation and foreign quota constraints. Go-to-market execution should anchor through joint venture structures with local land assembly partners navigating zoning incentives. For Investors and Strategic Acquirers: Industrial estate specialists with Board of Investment tax holiday positioning and flood-resilience infrastructure deployment represent the priority acquisition archetype. Long-term viability frames around manufacturing tenant stabilization across the Eastern Economic Corridor's maturation horizon. Monitor industrial land absorption velocity against infrastructure completion timelines as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Building Information Modeling Adoption | BIM compression of design-to-delivery cycles accelerates certificate of occupancy timelines for Thai developers bidding competitively. |
| Secondary Province Expansion | Integrated retail-residential complexes in Khon Kaen and Udon Thani exploit yield gaps beyond Bangkok deposit rates. |
| REIT Channel Development | Institutional capital concentration creates liquidity pathways for portfolio holders seeking exit from income-generating commercial assets. |
| Flood-Mitigation Infrastructure Investment | Resilience certification satisfies pension fund due diligence mandates for eastern seaboard industrial estate exposure. |
| Joint Venture Structuring | Foreign capital pairings with local developers navigate Land Department ownership ratio caps and land assembly complexities. |
Study Parameters
Initial hypotheses were tested against primary input from property development executives, Land Department regulatory affairs specialists, institutional fund managers, and construction procurement directors and refined through secondary validation. Bottom-up triangulation combined Bank of Thailand mortgage lending data, Board of Investment incentive filings, and Eastern Economic Corridor infrastructure progress disclosures with top-down sectoral analysis. Primary stakeholder interviews captured execution timelines for Condominium Act amendment implementations and flood mitigation compliance cost structures.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled encompass property type liquidity profiles, investment vehicle structures, buyer regulatory eligibility tiers, and financing model sensitivity to central bank calibration. CAGRs derived from industrial land absorption velocity, condominium turnover cycles, and REIT expansion trajectories. Forecast inputs incorporated mass transit extension completion schedules and manufacturing relocation pipeline commitments from China.
Macroeconomic conditions sit as an overlay; deviation in Bank of Thailand policy rates, Chinese manufacturing relocation velocity, or regional currency stability would shift the trajectory. Forecasts reflect documented assumptions regarding infrastructure completion timelines and regulatory amendment implementation cadence. Quarterly review of mortgage approval velocity, industrial land transaction volume, and foreign ownership quota utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
United States Self Storage Market
Real Estate Services
Global Home Services Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Home Warranty Service Market
Real Estate Services
Lease Management Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
US Home Service Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Warehousing Services Market