
 United Arab Emirates Kitchen Furniture Market | 2026-2036
United Arab Emirates Kitchen Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Kitchen Furniture Market Analytics
Asset-light leasing models for showroom and manufacturing space are reconfiguring capital deployment across the UAE kitchen furniture sector. Kitchen King UAE leverages its Dubai-based fabrication facility to sustain rapid turnaround on custom orders. Scavolini competes through Italian-designed system kitchens positioned at the premium end of the market. Ikea anchors volume sales via its Jebel Ali distribution hub and flat-pack logistics network.
United Arab Emirates kitchen furniture encompasses fixed and modular storage units, work surfaces, and seating designed for food preparation and dining environments, typically constructed from engineered wood substrates, stainless steel, or natural stone with moisture-resistant finishes rated for Gulf climate conditions. The primary commercial purpose centers on optimizing residential and hospitality spatial efficiency while meeting durability standards for high-temperature, high-humidity operation. Cabinets dominate product-type revenue due to their structural role in kitchen fit-outs and integration with MEP routing. Wood materials lead the material split, though laminate surfaces gain traction among cost-sensitive project developers. Modern styling commands the style category, driven by Dubai's contemporary architectural vernacular and developer specification trends.
MOHAP and ESMA jointly govern product safety and material emissions standards for kitchen furniture sold across the Emirates, with ESMA's UAE.S GSO standards specifically addressing formaldehyde release limits in wood-based panels. Dubai Municipality's building code amendments for kitchen ventilation and fire suppression further shape cabinet specification and installation protocols. Stakeholders must monitor evolving ESMA harmonization with Gulf Standardization Organization requirements, as alignment decisions will determine import eligibility for European and Asian manufacturers serving UAE project pipelines.
Market Dynamics
Emirates Authority for Standardization and Metrology certification mandates are compressing import timelines and elevating compliance costs for wood-based panel suppliers serving UAE project pipelines.
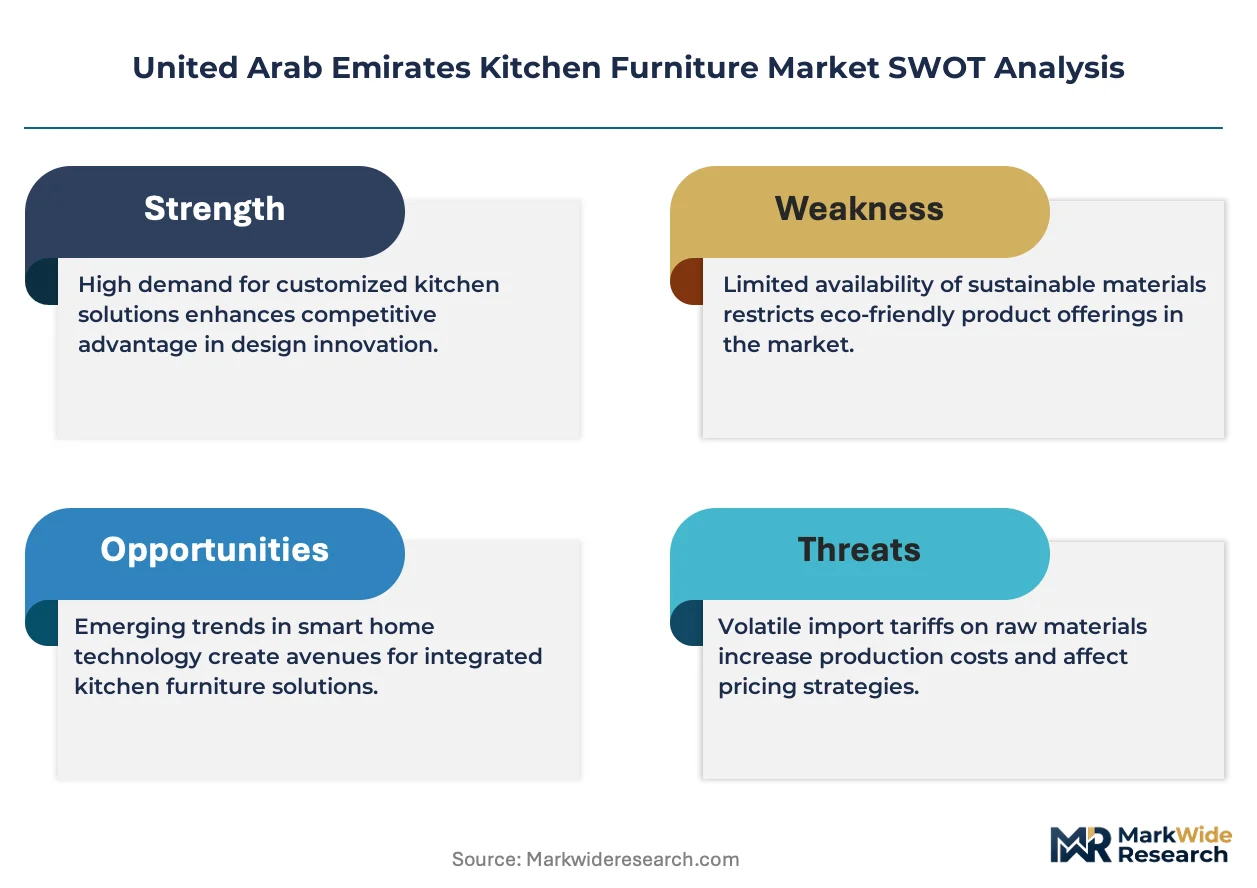
Growth Catalysts
- Luxury villa completions:Developments across Emirates Hills and Saadiyat Island are generating concentrated demand for European-imported hardware and stone surfaces from high-net-worth buyers.
- MOHAP safety alignment:Joint governance with ESMA on material emissions standards is accelerating formaldehyde-compliant product substitution across residential fit-outs.
- Modular fabrication:Asset-light leasing models for showroom and manufacturing space are enabling rapid turnaround on custom orders without fixed capital deployment.
Market Restraints
- European supply concentration:Premium hardware and stone surface procurement relies on Italian and German manufacturing clusters, exposing buyers to extended lead times and currency volatility.
- ESMA compliance friction:Harmonization uncertainties with Gulf Standardization Organization requirements are creating import eligibility ambiguities for Asian panel manufacturers.
- Climate-rated material costs:Moisture-resistant finishes and engineered wood substrates rated for Gulf conditions command 15-25% premiums over standard specifications.
Strategic Opportunities
- Abu Dhabi cultural district expansion:Museum and hospitality developments on Saadiyat Island are specifying integrated kitchen systems for staff and visitor amenities.
- Dubai South logistics integration:Proximity to Jebel Ali distribution infrastructure enables same-day fulfillment models for flat-pack and semi-custom product lines.
- Smart home convergence:Integration of sensor-enabled cabinet systems with building management platforms is opening specification channels with premium developers.
Industry Challenges
- Certification timeline compression:ESMA's evolving UAE.S GSO standards require continuous re-testing of wood-based panels, straining quality assurance resources.
- Installation skill scarcity:MEP-integrated cabinet systems demand certified technicians familiar with Dubai Municipality ventilation and fire suppression protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Kitchen Furniture Market |
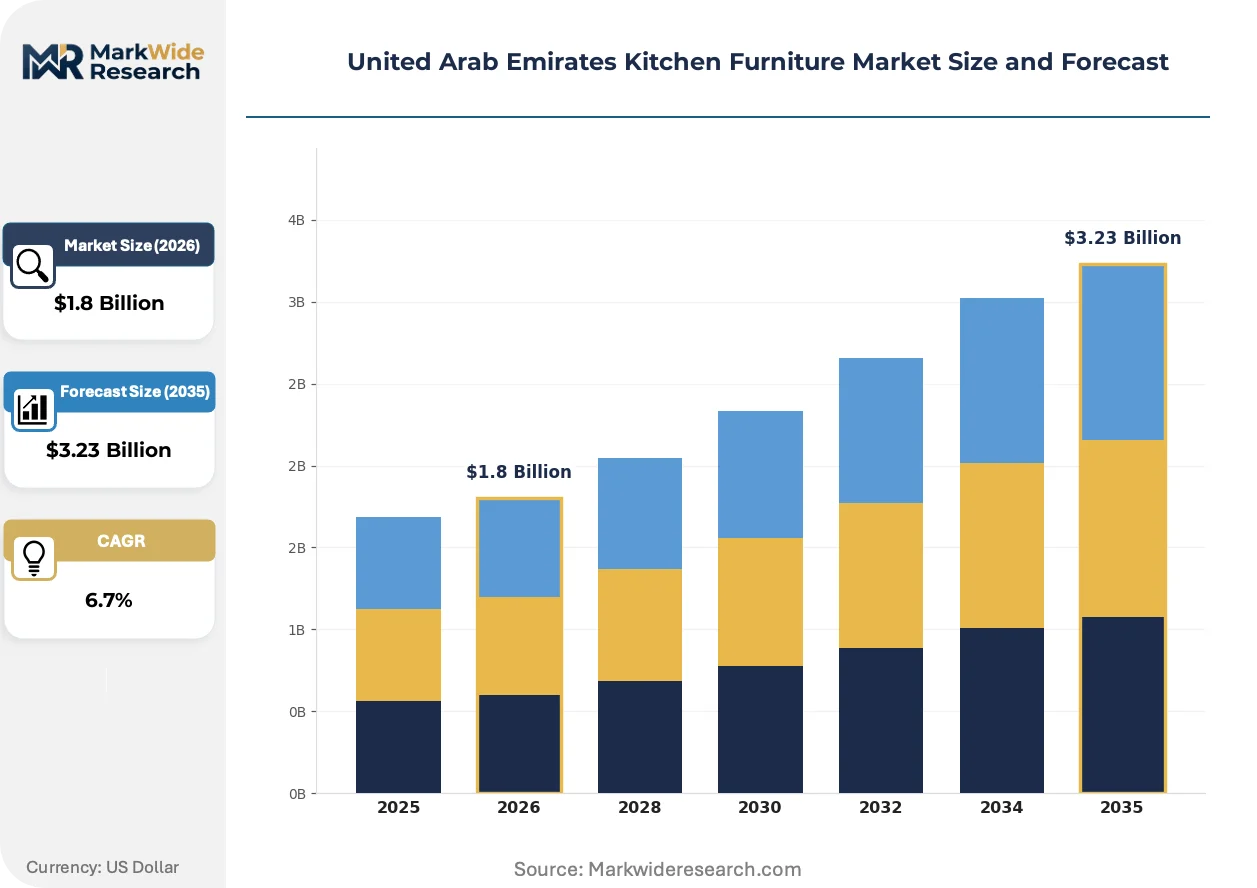
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Countertops, Tables, Chairs Material: Wood, Metal, Glass, Laminate Style: Modern, Traditional, Minimalist, Rustic End User: Residential, Commercial, Industrial, Hospitality |
| Companies Covered | Ikea, Kitchen King UAE, Space 3 LLC, VOX Furniture UAE, Al Marri Metal Kitchen Factory LLC, Pottery Barn, Scavolini, Home Centre, SieMatic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Kitchen Furniture Market Evolving Landscape
Three distinct vectors are reshaping product development and procurement patterns across the Emirates: material substitution under climate pressure, regulatory harmonization across Gulf markets, and developer-led specification centralization.
Quartz composite surfaces are collapsing the traditional natural stone premium segment by delivering equivalent durability ratings at reduced weight and installation complexity. Dubai's master developers now specify engineered stone as standard in mid-premium residential packages, compressing margins for Italian marble suppliers while expanding addressable volume for regional fabricators. The technology is collapsing differentiation between luxury and upper-mid market tiers.
MOHAP and ESMA joint governance on kitchen furniture safety is mandating formaldehyde emission thresholds that exceed legacy Gulf Cooperation Council voluntary guidelines. Manufacturers must now maintain dual certification documentation for UAE and broader Gulf markets, elevating documentation costs but creating compliance moats against uncertified competitors. Wood-based panel imports from Southeast Asia face the steepest adaptation requirements.
Developer-led interior packages are consolidating procurement authority away from individual buyers toward centralized specification teams at Emaar, Aldar, and Dubai Holding. This concentration is compressing vendor counts per project while extending contract durations and performance guarantees. The shift is most visible in Dubai's off-plan residential sector, where hardware and surface selections are locked 18-24 months pre-handover.
United Arab Emirates Kitchen Furniture Market Segmentation
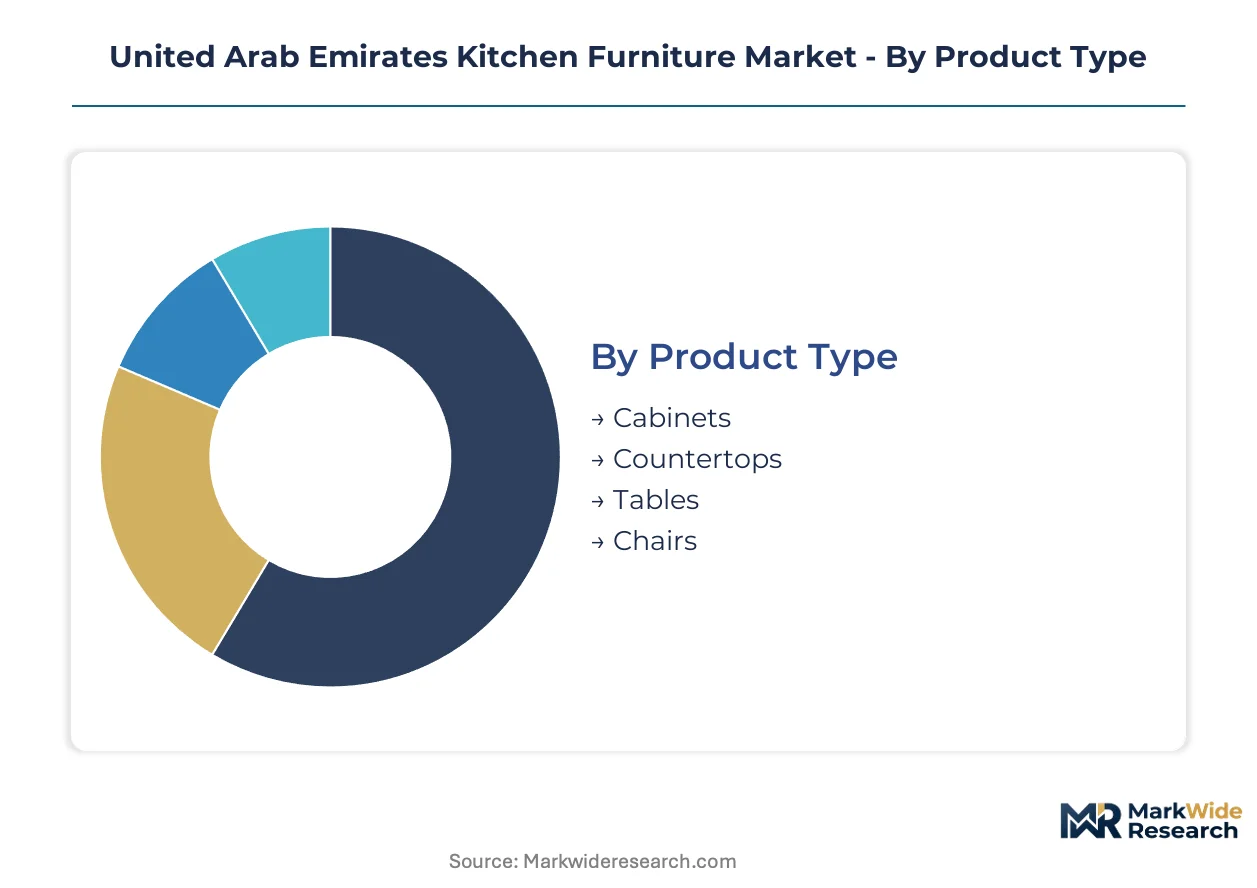
Segmentation in the UAE kitchen furniture sector reveals how procurement authority concentrates with master developers and how climate-rated specifications reshape material selection. Understanding these splits exposes where compliance costs accumulate and where specification cycles accelerate.
Product Type:
Cabinets turn over slowest due to MEP integration and 15-20 year replacement cycles, while seating and surfaces refresh fastest through renovation-driven demand.
- Cabinets:Structural storage units engineered from moisture-resistant particleboard or MDF with ESMA-certified formaldehyde emissions below 0.1 ppm. Demand concentrates in Dubai's off-plan residential sector where Emaar and Aldar specify hardware-integrated systems 18-24 months pre-handover, constrained by installation skill scarcity for MEP-integrated configurations.
- Countertops:Work surfaces in natural stone, engineered quartz, or stainless steel rated for Gulf humidity and temperature cycling. Saadiyat Island luxury villas and Emirates Hills developments drive procurement of Italian-imported stone, though quartz composites are collapsing the traditional premium tier through reduced weight and faster installation.
- Tables:Dining and prep surfaces spanning fixed island configurations to freestanding units, typically specified through developer interior packages rather than individual buyer selection.
- Chairs:Seating solutions for kitchen-dining environments, experiencing faster replacement cycles through hospitality refurbishment and residential renovation activity.
Cabinets dominate installed base through structural permanence and MEP integration. Countertops represent the fastest expansion trajectory as engineered stone displaces natural marble in mid-premium specifications.
Material:
Cost tier stratification runs from premium natural materials through economy laminates, with compliance premiums of 15-25% separating climate-rated from standard specifications.
- Wood:Engineered substrates including particleboard, MDF, and plywood with moisture-resistant finishes mandatory for Gulf conditions. ESMA's UAE.S GSO formaldehyde standards and continuous re-testing requirements strain quality assurance resources for Southeast Asian panel suppliers.
- Metal:Stainless steel and aluminum framing systems for structural support and appliance integration, specified increasingly for fire suppression compliance under Dubai Municipality building code amendments.
- Glass:Tempered and laminated surfaces for cabinet fronts and decorative elements, gaining traction in modern styling specifications for contemporary Dubai architectural vernacular.
- Laminate:Cost-sensitive surfacing for budget residential and bulk hospitality procurement, expanding addressable volume among project developers prioritizing capital efficiency over natural material premiums.
Wood commands the largest share of material procurement by value. Laminate surfaces are gaining share fastest among cost-sensitive developers in Dubai's mid-market residential pipeline.
Style:
Volume concentrates in modern styling aligned with Dubai's contemporary built environment, while traditional and rustic segments serve heritage hospitality and expatriate preference niches.
- Modern:Clean lines, handle-less cabinetry, and integrated appliance fronts specified as standard across Emaar, Aldar, and Dubai Holding developments. This styling locks hardware and surface selections 18-24 months before handover, consolidating vendor relationships with European system kitchen suppliers.
- Traditional:Ornate detailing, raised panel doors, and decorative hardware serving heritage hospitality projects and specific expatriate residential preferences in established Emirates communities.
- Minimalist:Reduced visual complexity with concealed storage and monochromatic palettes, specified for Saadiyat Island cultural district staff amenities and premium residential compact footprints.
- Rustic:Natural wood grains, distressed finishes, and farmhouse-influenced aesthetics serving niche hospitality theming and individual villa customization outside developer-led procurement.
Modern styling dominates specification authority through developer centralization. Minimalist is climbing the fastest as compact urban residential formats proliferate across Dubai South and Abu Dhabi cultural district expansions.
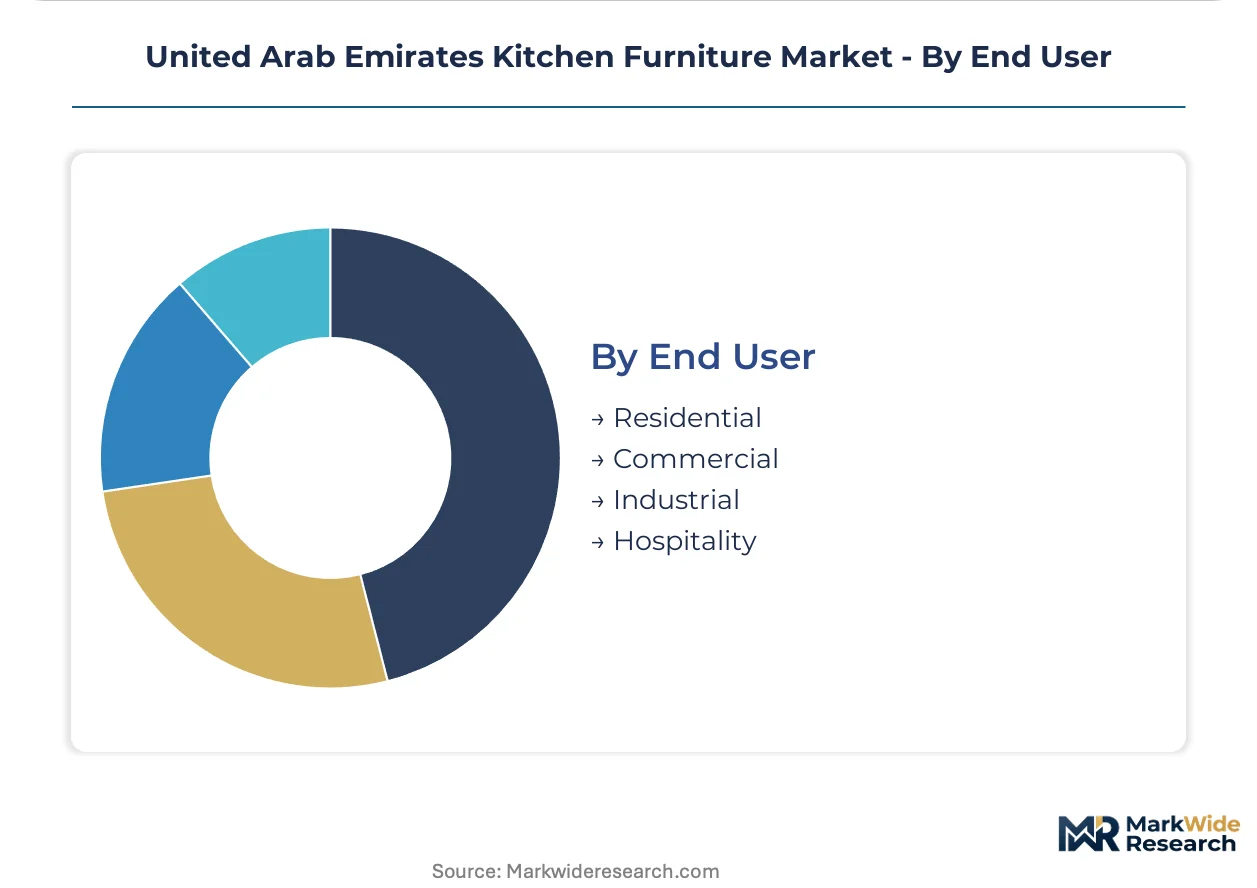
End User:
Customer type determines procurement channel, with residential flowing through developer packages and hospitality/conmercial requiring direct vendor negotiation for integrated systems.
- Residential:Individual and investor buyers accessing kitchen furniture through developer interior packages or post-handover customization, with procurement authority shifting decisively toward centralized specification teams at major master developers.
- Commercial:Office and retail food service environments requiring durability-rated systems with accelerated replacement cycles and standardized maintenance protocols.
- Industrial:Staff canteen and facility kitchen installations prioritizing cost efficiency and regulatory compliance over aesthetic specification.
- Hospitality:Hotel, restaurant, and museum amenity kitchens on Saadiyat Island and Dubai's cultural districts, specifying integrated systems with performance guarantees and 24-36 month contract durations.
Residential channels command the deepest vendor relationships through developer concentration. Hospitality is where specification values concentrate most intensely per square meter of installed kitchen space.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi's Saadiyat Island luxury developments command 40% pricing premiums over Dubai South mid-market specifications, creating a two-tier procurement geography within the Emirates.
Dubai
Emirates Hills and Palm Jumeirah villa completions drive demand for Italian-imported hardware and natural stone surfaces. Dubai Municipality's ventilation and fire suppression code amendments shape cabinet installation protocols. Jebel Ali's distribution infrastructure anchors flat-pack logistics networks serving same-day fulfillment models.
Abu Dhabi
Saadiyat Island museum and hospitality developments specify integrated kitchen systems for staff and visitor amenities. MOHAP safety alignment with ESMA accelerates formaldehyde-compliant product substitution across cultural district fit-outs. Aldar Properties' centralized specification teams lock vendor relationships 18-24 months before handover.
Sharjah
Cost-sensitive residential developments prioritize laminate surfaces and engineered wood substrates over natural material premiums. ESMA's UAE.S GSO formaldehyde standards strain quality assurance resources for Southeast Asian panel suppliers serving mid-market pipelines. Industrial zones near Sharjah International Airport concentrate fabrication facilities for rapid turnaround orders.
Northern Emirates
Ras Al Khaimah and Fujairah hospitality projects specify durability-rated systems for resort and marina amenities. Climate-rated material costs command 15-25% premiums over standard specifications for moisture-resistant finishes. Developer-led interior packages consolidate procurement authority away from individual buyers toward centralized teams.
United Arab Emirates Kitchen Furniture Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on material supply. The vendor base stratifies across three tiers: European system kitchen suppliers, regional fabricators with captive installation capabilities, and volume distributors leveraging flat-pack logistics. Two strategic archetypes dominate—asset-light leasers of showroom and manufacturing space, and vertically integrated operators controlling fabrication through handoff. Competitive moves concentrate on M&A for installation skill acquisition and strategic partnerships with master developers for pre-handover specification lock-in.
Among European-origin system suppliers, Scavolini and SieMatic occupy positions exemplifying the premium-tier vector anchored by Italian design heritage. Kitchen King UAE represents the regional fabricator archetype with Dubai-based production proximity. Ikea anchors the volume distribution tier through Jebel Ali hub infrastructure and flat-pack logistics scale.
| Leading Market Players |
|---|
| Ikea |
| Kitchen King UAE |
| Space 3 LLC |
| VOX Furniture UAE |
| Al Marri Metal Kitchen Factory LLC |
| Pottery Barn |
| Scavolini |
| Home Centre |
| SieMatic |
| Others |
Value Network & Pricing Analysis
European hardware supply concentration determines both tier spreads and supply chain shape in the UAE kitchen furniture sector. Italian and German manufacturing clusters anchor premium cabinet systems, while Southeast Asian panel suppliers face ESMA compliance chokepoints that compress margins and extend procurement timelines for mid-market developers.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing across the Emirates. Three-tier pricing structure across premium, standard, and economy levels separates Italian-imported stone surfaces from regional quartz fabricators and Southeast Asian laminate suppliers. Cost compression in the standard tier intensifies as engineered stone displaces natural marble in Aldar and Emaar specifications. Hospitality developers exhibit least price sensitivity due to performance guarantee requirements and extended contract durations.
Supply Chain Analysis
Extended payment terms from Dubai master developers strain working capital for regional fabricators serving pre-handover specification cycles. Supply draws from Italy for premium hardware, Germany for engineered stone machinery, and China for laminate substrates and metal framing systems. Single-source vulnerability concentrates in Italian cabinet system suppliers serving Saadiyat Island luxury developments. Distribution runs through Jebel Ali port infrastructure with same-day fulfillment models for flat-pack inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE kitchen furniture market functions as a service-attach opportunity where installation and maintenance contracts expand faster than cabinet hardware sales. Recurring revenue from MEP-integrated system servicing and ESMA compliance certification renewal outpaces product turnover cycles.
For Market Incumbents: Insulate specification relationships with Emaar, Aldar, and Dubai Holding through captive installation capabilities and ESMA certification investment. European system kitchen suppliers face substitution risk from regional fabricators offering faster turnaround on quartz composite surfaces. Backward integration into Dubai-based fabrication facilities reduces lead time exposure and locks pre-handover vendor selection. For New Entrants and Emerging Players: Sharjah's cost-sensitive residential pipeline offers the most penetrable entry point for laminate-focused product lines. White-space targets include mid-market hospitality refurbishment cycles and industrial canteen installations prioritizing capital efficiency over aesthetic specification. Direct contractor relationships bypass developer procurement centralization and accelerate initial project wins. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regional fabricators with captive installation networks. Five-to-ten year viability hinges on ESMA harmonization completion and smart home integration capability buildout. Acquisition target archetype: Dubai-based operators controlling fabrication through handoff with certified MEP integration teams. The signal to watch is Dubai Municipality building code amendments affecting fire suppression and ventilation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| ESMA Certification Investment | Creates compliance moats against uncertified Southeast Asian panel suppliers. |
| Installation Capability Acquisition | Addresses skill scarcity for MEP-integrated cabinet systems under Dubai Municipality protocols. |
| Smart Home Integration Partnership | Opens specification channels with premium developers deploying sensor-enabled building management platforms. |
| Quartz Composite Fabrication Scale-Up | Captures volume expansion as engineered stone displaces Italian marble in mid-premium specifications. |
| Developer Pre-Handover Lock-In | Secures 18-24 month specification cycles before individual buyer influence enters the procurement chain. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Interviews covered procurement directors at master developers, technical managers at ESMA-certified fabrication facilities, hospitality FF&E consultants, and MEP contractors familiar with Dubai Municipality installation protocols. Secondary sources included ESMA certification registries, Dubai Municipality building code amendments, customs import records for wood-based panels, and hospitality development tender documents. Bottom-up project pipeline enumeration triangulated against top-down sector expenditure estimates.
Forecast inputs considered product type substitution rates, material compliance cost trajectories, and developer specification centralization trends across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, styling category, and end-user channel. CAGRs derived from fitted growth curves anchored to observed completion schedules for Emirates Hills, Saadiyat Island, and Dubai South developments. Climate-rated material premiums and ESMA testing timeline compression factored as industry-specific demand modifiers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese laminate suppliers or accelerated smart home convergence by European system kitchen vendors would shift outcomes. Macroeconomic deviation in Gulf construction lending, regulatory acceleration of GSO harmonization timelines, or breakthroughs in climate-resistant bio-composite materials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Qatar Kitchen Hood Market