
 North America Tabletop Kitchen Products Market | 2026-2036
North America Tabletop Kitchen Products Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tabletop Kitchen Products Market Intelligence
The substitution of traditional ceramic with advanced, shatter-resistant plastic composites in casual dinnerware is expanding the addressable market for specific applications. Corelle Brands LLC leverages its proprietary glass laminate technology to maintain a strong position in the durable dinnerware segment. Lifetime Brands, Inc. competes across a broad portfolio, utilizing a diverse material sourcing strategy to serve multiple price points. Libbey Inc. specializes in glassware for both the foodservice and consumer markets in the United States and Canada.
Tabletop kitchen products encompass items used for serving, dining, and decorating a table setting. This category includes articles made from materials like ceramic, glass, and stainless steel, often specified by their durability, heat resistance, and non-porous surface qualities. The dinnerware product type remains the largest segment by value, while serveware shows high growth potential within the restaurant end-user category. In terms of materials, ceramic holds a dominant share, but high-grade stainless steel flatware commands premium pricing through specialty store distribution channels.
In the United States, the FDA's regulations for food-contact substances in Title 21 CFR dictate material safety for all tabletop products. Similarly, Health Canada sets requirements for the safety of consumer products, including glassware and dinnerware, impacting market access. Navigating these distinct national standards, particularly for materials like plastic and ceramic glazes, remains a critical compliance challenge for manufacturers distributing across North America.
Market Dynamics
The central dynamic in the North America tabletop kitchen products market is the intersection of aesthetic demand from the hospitality industry and stringent food-contact safety regulations. This requires manufacturers to balance innovative, visually appealing designs with material compliance dictated by agencies like the FDA.
Growth Catalysts
- Hospitality Sector Expansion:The growth of the restaurant and hotel industry in the United States fuels demand for durable and aesthetically unique serveware and dinnerware, driving volume in the commercial end-user segment.
- Advanced Material Adoption:The substitution of traditional ceramics with shatter-resistant plastic composites and proprietary glass laminates is expanding the market into applications requiring high durability, such as outdoor dining and institutional use.
- High Consumer Spending:Strong consumer purchasing power, particularly in the United States, supports consistent demand for premium and specialty tabletop products, including high-grade stainless steel flatware and designer dinnerware sets sold through specialty stores.
Market Restraints
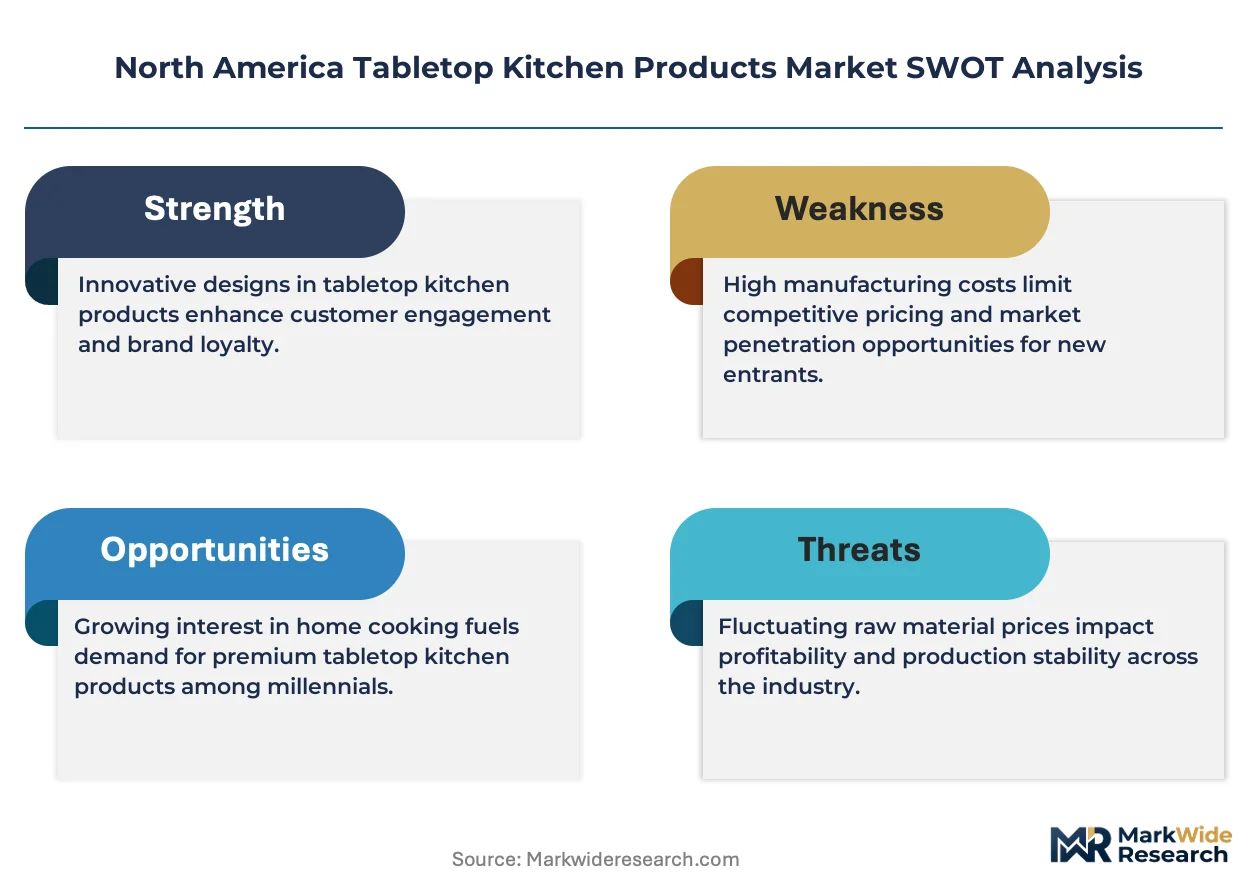
- Regulatory Divergence:Navigating the distinct food-contact material standards of the FDA in the United States and Health Canada creates compliance complexity and increases testing costs for manufacturers distributing across the entire region.
- Input Cost Volatility:Fluctuations in the price of raw materials, particularly high-grade stainless steel and specific ceramic clays, introduce margin pressure for flatware and premium dinnerware producers.
- Substitution from Disposables:The availability of premium, aesthetically designed disposable tableware presents a substitution threat in catering and casual event settings, where convenience can outweigh the need for reusable products.
Strategic Opportunities
- Health and Wellness Niche:There is an opportunity to develop specialized products for the health and wellness segment, such as portion-control plates and bowls, catering to health-conscious consumers.
- Direct-to-Consumer Channels:Artisanal and small-batch producers can leverage e-commerce and direct-to-consumer (DTC) models to reach customers seeking unique, high-end ceramic and glass products, bypassing traditional retail gatekeepers.
- Sustainable Materials:Developing tabletop lines from recycled glass, sustainable bamboo, or biodegradable composites can attract environmentally conscious consumers, a growing demographic in both the United States and Canada.
Industry Challenges
- Material Certification Timelines:The lengthy and costly process for achieving FDA compliance under Title 21 CFR for new food-contact substances, especially novel polymers and glazes, can delay product introductions and increase development expenses.
- Supply Chain Complexity:Managing a diverse global sourcing strategy to serve multiple price points—from economy to premium—while ensuring consistent quality and regulatory adherence remains a significant operational challenge for large-portfolio brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tabletop Kitchen Products Market |
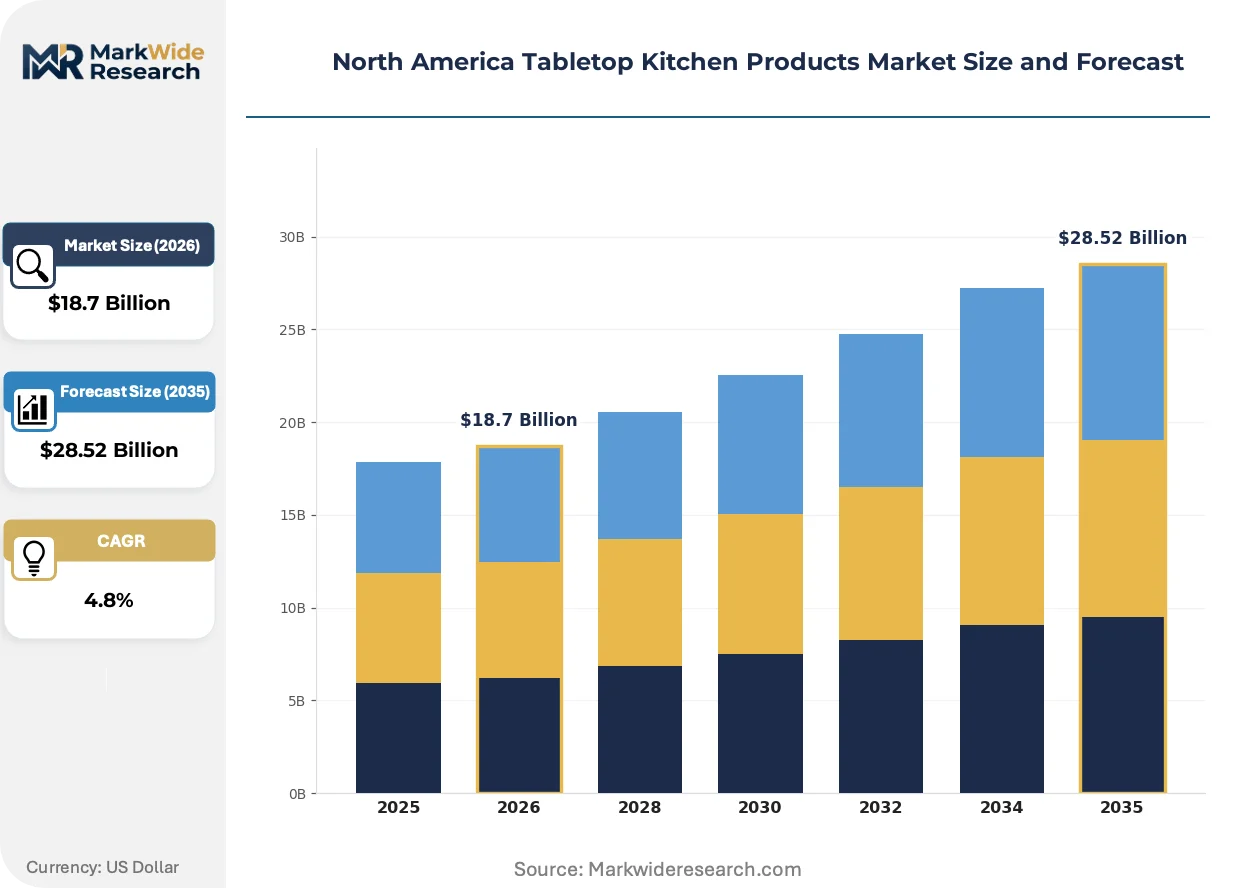
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dinnerware, Serveware, Flatware, Glassware Material: Ceramic, Glass, Stainless Steel, Plastic End User: Households, Restaurants, Cafés, Catering Services Distribution Channel: Online Retail, Specialty Stores, Department Stores, Wholesale |
| Companies Covered | Villeroy & Boch AG, Lenox Corporation, The Oneida Group, Inc, Lifetime Brands, Inc., Libbey Inc., Noritake Co., Corelle Brands LLC, Fiskars Group, Steelite International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tabletop Kitchen Products Market Strategic Shifts & Innovations
Material science is actively reshaping product capabilities, with a focus on enhancing durability and safety. This evolution occurs alongside a regulatory environment that places increasing emphasis on material composition, while consumer preferences pivot toward multi-functionality and sustainability in their purchasing decisions.
Proprietary glass laminate technology provides superior resistance to chipping, breaking, and staining compared to traditional ceramic or porcelain. This technology is widely adopted by households and high-traffic foodservice operators in the United States seeking lower long-term replacement costs. The introduction of such durable materials is rewriting the established product lifecycle for the casual dinnerware segment, extending replacement cycles significantly.
Heightened regulatory focus from the FDA on heavy metals in ceramic glazes is a critical driver of material formulation changes. This forces manufacturers, especially those importing goods, to invest in lead-free and cadmium-free glaze technologies and implement stricter quality control testing to comply with Title 21 CFR. The ceramic dinnerware segment is the most affected, compelling a shift toward safer materials to maintain market access.
A clear behavioral shift toward multi-functional and stackable product designs is evident among North American consumers, particularly those in urban environments with limited storage. This trend disrupts the traditional sales model centered on large, formal dinnerware sets, favoring smaller, modular collections that can be mixed and matched. This purchasing pattern is most pronounced in the direct-to-consumer channel, which effectively targets younger demographics.
North America Tabletop Kitchen Products Market Segmentation
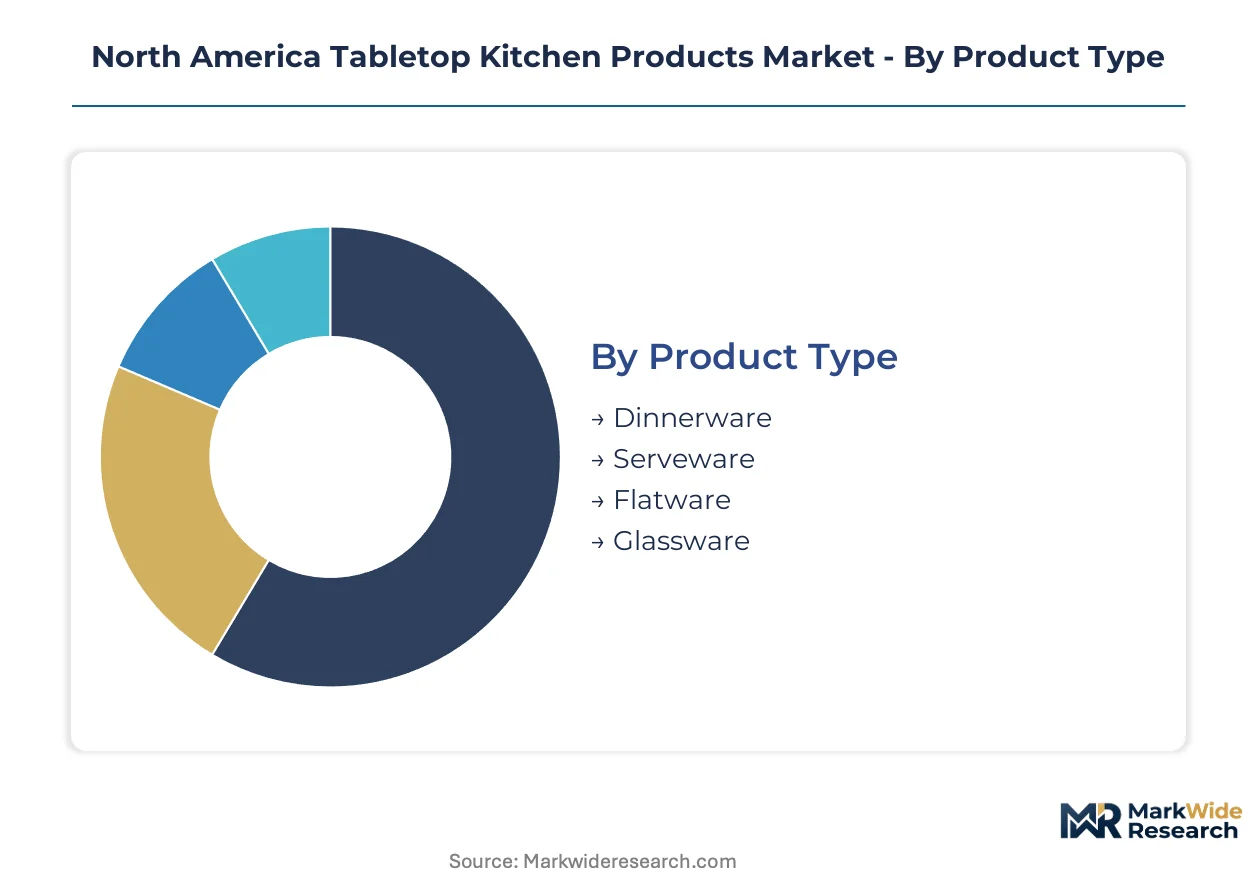
Understanding the North America tabletop kitchen products market requires granular analysis across its diverse components. This segmentation highlights distinct consumer preferences, material science advancements, and varied purchasing behaviors that influence product development. Manufacturers leverage these insights to tailor offerings and optimize market penetration across the United States and Canada.
Product Type:
Buyer preferences in the tabletop kitchen products market often differentiate based on primary function and aesthetic requirements for specific meal occasions.
- Dinnerware:Comprises plates, bowls, and cups, forming the core dining set for everyday and formal use. This category commands the largest market share by value, driven by consistent household replacement cycles and restaurant demand for durable options.
- Serveware:Includes platters, serving bowls, and pitchers, designed for presenting food at the table. This segment exhibits high growth potential within the restaurant and catering end-user categories, fueled by aesthetic demand from the hospitality industry.
- Flatware:Consists of forks, knives, and spoons, primarily made from stainless steel for durability and hygiene.
- Glassware:Encompasses drinking vessels like tumblers, wine glasses, and specialty beverage containers for both domestic and commercial use.
Dinnerware leads volumes today; serveware is gaining share fastest.
Material:
Material selection in tabletop products is critically influenced by functional requirements such as durability, heat resistance, and compliance with food-contact regulations.
- Ceramic:Features traditional earthenware, stoneware, and porcelain, valued for its heat retention and aesthetic versatility. This material holds a dominant market share, particularly in dinnerware, despite regulatory scrutiny on glazes by the FDA in the United States.
- Plastic:Includes advanced composites and shatter-resistant polymers, offering lightweight and robust alternatives to traditional materials. Its adoption expands into casual dinnerware and institutional use, driven by requirements for high durability and reduced breakage in North America.
- Glass:Utilized for transparent and non-porous items, including proprietary glass laminate technologies offering superior resistance to chipping.
- Stainless Steel:Preferred for flatware due to its corrosion resistance, durability, and ability to command premium pricing through specialty channels.
Ceramic dominates the material landscape; plastic shows strong momentum in specific applications.
End User:
End-user categories exhibit distinct purchasing patterns and product requirements, influencing design, durability, and volume procurement in the North American market.
- Restaurants:Requires highly durable, aesthetically pleasing, and often specialized serveware and dinnerware for high-traffic environments. The hospitality sector's expansion in the United States directly fuels significant demand for commercial-grade products.
- Households:Represents a broad consumer base driven by aesthetic trends, personal preferences, and replacement cycles for everyday and special occasion items. High consumer spending in the United States supports consistent demand for premium and specialty tabletop products.
- Cafés:Focuses on functional and often branded glassware and ceramic items suitable for beverage service and casual dining.
- Catering Services:Seeks robust, easily transportable, and sometimes disposable-alternative tabletop solutions for large-scale events.
Households remain the largest consumer segment; restaurants represent a growing commercial segment.
Distribution Channel:
Distribution channels determine market reach and pricing strategies, with varying levels of overhead and customer engagement across the North American tabletop market.
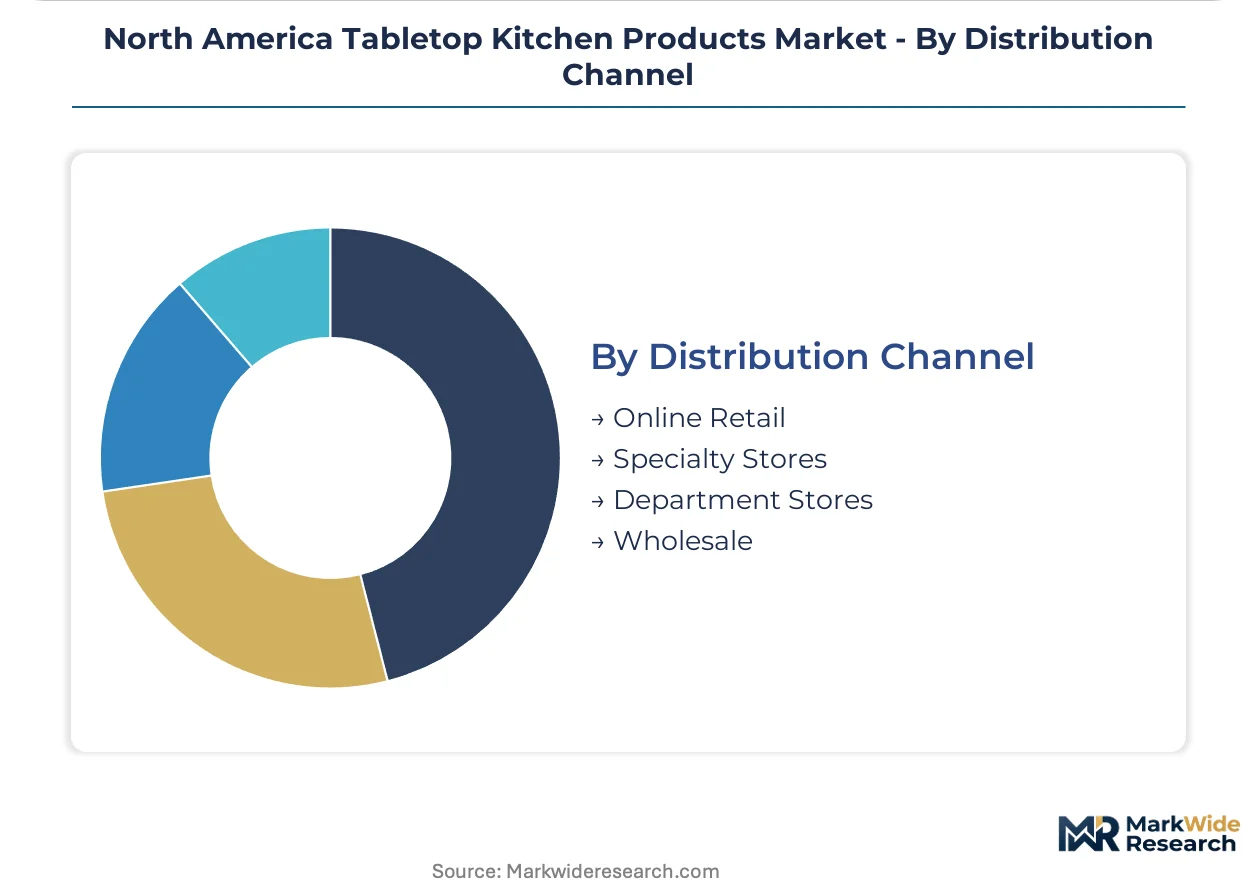
- Online Retail:Provides broad product access and direct-to-consumer opportunities, particularly attractive to younger demographics seeking modular collections. This channel facilitates market entry for artisanal brands and offers convenience to urban consumers in the United States.
- Specialty Stores:Focuses on curated selections, premium brands, and high-grade materials like stainless steel flatware, catering to consumers seeking unique or luxury items. These stores command higher margins by offering personalized service and product expertise across North America.
- Department Stores:Offers a wide range of established brands and collections, appealing to consumers seeking variety and traditional shopping experiences.
- Wholesale:Serves commercial clients like restaurants and hotels, providing bulk purchasing options and often specialized commercial-grade products.
Wholesale provides extensive commercial access; online retail offers a rapidly expanding consumer reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The extensive hospitality industry in the United States drives significant demand for tabletop kitchen products across North America. This market benefits from strong consumer spending and a focus on aesthetically pleasing, durable items. Manufacturers navigate distinct regulatory environments across the region.
United States
High consumer spending and the expanding restaurant sector fuel consistent demand for premium dinnerware and specialized serveware. The FDA's regulations under Title 21 CFR dictate material safety, particularly for food-contact substances. Major culinary hubs like New York City and Los Angeles showcase diverse product needs, from high-end ceramic to shatter-resistant plastic composites.
Canada
Consumer preferences in Canada increasingly favor sustainable materials and multi-functional designs, influencing purchasing patterns. Health Canada sets stringent requirements for the safety of consumer products, including glassware and dinnerware. Toronto's growing culinary scene and strong household replacement cycles contribute to steady market expansion.
Mexico
Mexico's expanding tourism sector and a rising middle class generate demand for durable and aesthetically appealing tabletop products. The country's national health and safety standards govern food-contact materials, ensuring product compliance for market entry. Mexico City's diverse culinary landscape and hospitality industry foster a need for varied product types.
North America Tabletop Kitchen Products Market Key Industry Players
Global majors compete with regional champions across product innovation and market reach in the North America tabletop kitchen products market. The competitive structure features a blend of companies specializing in proprietary technologies and those offering broad portfolios. Strategic archetypes include durable dinnerware specialists, diverse material providers, and glassware experts. Portfolio diversification and leveraging proprietary technology are common competitive moves.
Proprietary technology specialists, such as Corelle Brands LLC, maintain a strong position through their unique glass laminate technology for durable dinnerware. Lifetime Brands, Inc. exemplifies a broad portfolio provider, utilizing a diverse material sourcing strategy to serve multiple price points across the market. Libbey Inc. occupies a specialized niche, focusing primarily on glassware for both foodservice and consumer markets in the United States and Canada.
| Leading Market Players |
|---|
| Villeroy & Boch AG |
| Lenox Corporation |
| The Oneida Group, Inc |
| Lifetime Brands, Inc. |
| Libbey Inc. |
| Noritake Co. |
| Corelle Brands LLC |
| Fiskars Group |
| Steelite International |
| Others |
Cost & Logistics Intelligence
Ceramic clay spot prices and stainless steel commodity benchmarks cascade through the North America tabletop kitchen products market, influencing pricing tiers for both raw materials and finished goods. This market sees a clear interaction where material cost fluctuations directly impact manufacturer margins and consumer prices.
Pricing Analysis
Input cost pass-through from raw materials, particularly high-grade stainless steel and specific ceramic clays, significantly impacts pricing. The market operates on a tiered pricing structure across premium, standard, and economy levels. Price differentiation stems from material quality grade, proprietary technology, and brand premium. Pricing pressure stems from input cost volatility, particularly for flatware and premium dinnerware producers. Households purchasing specialty items demonstrate lower price sensitivity, while commercial buyers for restaurants exhibit higher sensitivity to bulk pricing.
Supply Chain Analysis
Managing returns of durable tabletop products presents a unique reverse logistics challenge for North American manufacturers. The supply chain for tabletop kitchen products draws from global manufacturing hubs, with significant concentration in China and Mexico for finished goods. Key raw material dependencies include ceramic clays and stainless steel. Input cost volatility for these materials represents a structural supply chain risk. Distribution runs through a hybrid model combining direct wholesale for commercial clients and online retail for household consumers across the United States and Canada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story driven by the adoption of advanced materials that reduce long-term replacement costs for end-users. Manufacturers can leverage material science innovations to capture greater value.
For Market Incumbents: Anticipate continued regulatory scrutiny on traditional materials like ceramic glazes. Diversify material portfolios to include advanced shatter-resistant plastic composites and proprietary glass laminates. Invest in material certification processes for novel food-contact substances to mitigate regulatory delays. Control distribution through direct-to-consumer channels to capture higher margins and better understand evolving consumer preferences, particularly in urban environments.
For New Entrants and Emerging Players: Health Canada's stringent requirements for consumer product safety in Canada opens a window for specialized manufacturers focusing on compliant, innovative materials. Target the health and wellness niche with portion-control plates or sustainable materials like recycled glass. The direct-to-consumer channel offers the most penetrable application for artisanal and small-batch producers. Leverage e-commerce platforms to reach health-conscious consumers seeking unique, high-end ceramic and glass products.
For Investors and Strategic Acquirers: Asymmetric upside sits with companies specializing in proprietary material technologies or those with robust, diversified global sourcing strategies. Long-term viability hinges on adaptability to evolving regulatory landscapes and consumer shifts toward sustainability. Target acquisition archetypes include specialized material science firms or established brands with strong direct-to-consumer engagement. Practitioners should monitor new material certifications and shifts in hospitality sector investment for early signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Sustainable Material Lines | Attracts environmentally conscious consumers in the United States and Canada, expanding market reach. |
| Invest in Material Certification | Ensures compliance with FDA and Health Canada regulations, maintaining market access for new products. |
| Expand Direct-to-Consumer Channels | Reaches younger demographics and offers higher margin potential for unique, modular collections. |
| Enhance Proprietary Glass Laminate Technology | Extends product lifecycle and reduces replacement costs for high-traffic foodservice operators. |
| Target Health and Wellness Product Niche | Caters to health-conscious consumers with specialized items like portion-control dinnerware. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, providing a comprehensive view of the North America tabletop kitchen products market. Primary research involved discussions with restaurant owners, hospitality procurement managers, household consumers, and material scientists. This was validated against secondary sources such as FDA regulations, Health Canada guidelines, trade association reports, and company financial filings, allowing for bottom-up and top-down triangulation.
The analytical framework applied segment-weighting across product type, material, end-user, and distribution channel to model market dynamics. Compound annual growth rates were derived from historical data and projected trends across the analysis window. Industry-specific forecast inputs included hospitality sector growth rates in the United States and consumer spending indices for premium goods across North America.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme raw material price volatility or significant shifts in regulatory enforcement. Forecasts reflect assumptions regarding economic stability and consumer purchasing power. Practitioners should monitor new material certifications and changes in hospitality investment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
UK Ceramic Tableware Market