
 UK Ceramic Tableware Market | 2026-2036
UK Ceramic Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
UK Ceramic Tableware Market Outlook
BSI kitemark certification for food-contact materials is redrawing competitive boundaries across the UK ceramic tableware sector. Churchill China leverages vertical integration through its Stoke-on-Trent manufacturing base to sustain cost discipline and quality consistency. Steelite International anchors its position through specialized vitrified hotelware engineered for commercial dishwasher cycles. Portmeirion Group competes via design-led differentiation across its portfolio of artisan and contemporary collections.
Ceramic tableware encompasses fired clay bodies—typically porcelain, stoneware, or earthenware—glazed to achieve impermeability and decorated for functional or aesthetic presentation, with vitrification temperatures ranging from 1,200°C to 1,400°C determining durability and translucency. Plates and mugs dominate volume throughput across UK manufacturing, while serving dishes command disproportionate margin pools in hospitality contract channels. The everyday use occasion segment leads consumer frequency, though formal dining and special occasions drive premium pricing stratification across specialty and department store retail.
BIS standards for ceramic ware safety, together with REACH compliance for glaze constituents and local authority environmental health regulations, collectively elevate compliance costs while restricting market access for uncertified imports. The Food Standards Agency enforces lead and cadmium migration limits that directly shape glaze formulation decisions across domestic producers. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and carbon border adjustment mechanisms to anticipate cost structure shifts and sourcing strategy revisions.
Market Dynamics
BSI kitemark certification requirements for food-contact materials are compressing supplier margins while creating tiered competitive access across UK hospitality and retail procurement channels. The Stoke-on-Trent manufacturing cluster's concentration of vitrified hotelware capacity shapes national supply reliability and cost structures.
Growth Catalysts
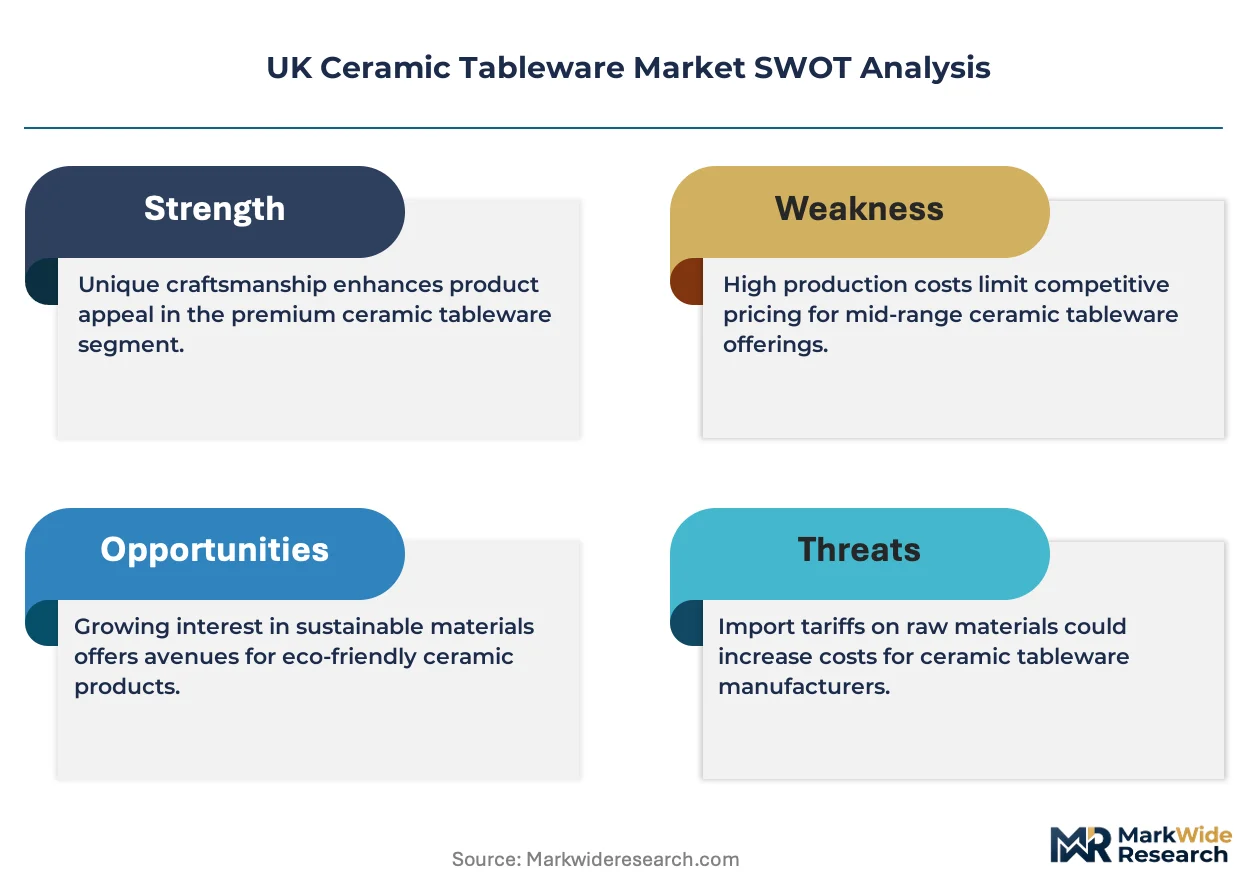
- Premium hospitality procurement:Boutique hotel chains and independent restaurant groups are specifying BSI-certified vitrified ware for commercial dishwasher durability, pulling volume through specialized contract channels.
- Extended Producer Responsibility frameworks:UK government consultations on ceramic waste recovery are incentivizing domestic remanufacturing investments and closed-loop glaze recycling systems.
- Staffordshire cluster concentration:Proximity of clay suppliers, kiln infrastructure, and skilled ceramicists within Stoke-on-Trent sustains cost-competitive, short-lead production for mid-scale orders.
Market Restraints
- Natural gas kiln dependency:Firing temperatures of 1,200°C to 1,400°C for vitrification expose producers to volatile UK wholesale energy pricing and carbon levy accumulation.
- Lead and cadmium migration testing:Food Standards Agency enforcement of glaze constituent limits requires batch-level laboratory certification, extending production timelines and raising compliance overhead.
- Import price pressure:Uncertified Asian ceramic ware enters UK retail through direct-to-consumer e-commerce channels, undercutting BSI-compliant domestic pricing in the everyday use segment.
Strategic Opportunities
- Carbon border adjustment preparation:Early alignment with anticipated UK CBAM mechanisms positions domestic manufacturers to capture public sector procurement preference as import ceramic costs rise.
- Design-led Greater London retail:Department store and specialty channel buyers in the capital are sourcing limited artisan collections at premium positioning, rewarding Stoke-on-Trent design innovation.
- REACH-compliant glaze chemistry:Reformulation investments eliminating restricted substances open access to EU re-export markets and hospitality chains with cross-border supply requirements.
Industry Challenges
- Master ceramicist succession:Traditional hand-throwing and kiln-firing expertise concentrates among aging practitioners, constraining artisan collection scaling and knowledge transfer to automated production.
- BSI certification timeline compression:Third-party testing queue lengths and documentation requirements delay new product launches, particularly for seasonal hospitality contract bidding cycles.
- Legacy glaze inventory stranding:Existing stockpiles of pre-REACH reformulation materials face accelerated write-downs as Food Standards Agency enforcement tightens batch traceability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Ceramic Tableware Market |
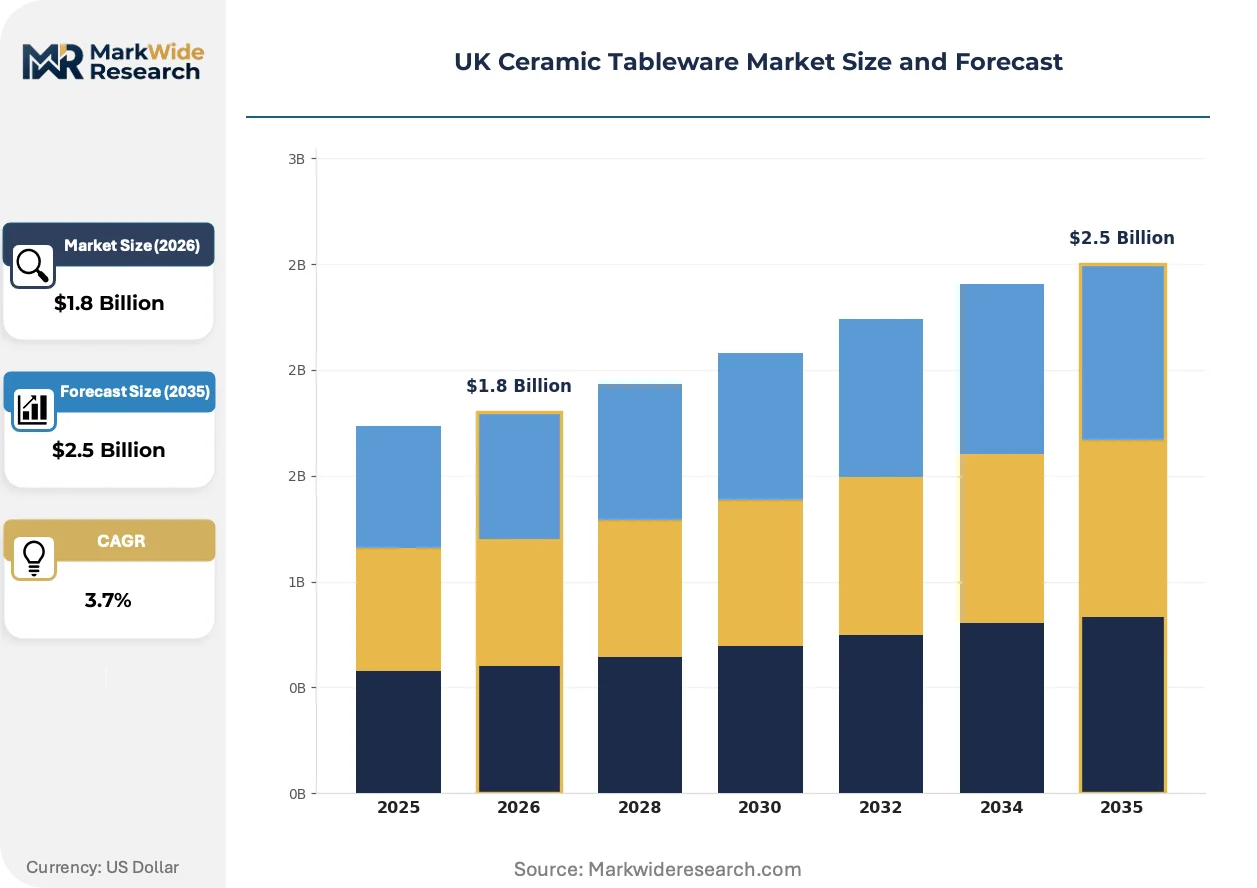
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Mugs, Serving Dishes Usage Occasion: Everyday Use, Formal Dining, Special Occasions, Outdoor Events Design Style: Traditional, Modern, Minimalist, Artistic Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Churchill China, Portmeirion Group, Steelite International, Dudson Group, Denby Pottery, Emma Bridgewater, Mason Cash, Wedgwood, Royal Doulton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Ceramic Tableware Market Strategic Shifts
Digital decoration technologies and automated kiln control systems are compressing design-to-delivery timelines while enabling micro-batch customization for hospitality contract clients. Regulatory chemistry requirements and procurement digitization are simultaneously reshaping production and distribution architectures.
Single-fire digital inkjet decoration is miniaturizing the traditional multi-step glazing process, eliminating intermediate firing stages and reducing energy consumption per piece. Boutique hotel procurement teams are specifying digitally printed custom patterns with 48-hour sample turnaround. This technology is compressing minimum viable order quantities from thousands to hundreds of units, fragmenting contract manufacturing into smaller, higher-margin production runs.
REACH compliance for ceramic glaze constituents is forcing systematic substitution of lead-based fluxes and cadmium pigments across UK manufacturing formulations. The Food Standards Agency's tightened migration limit enforcement has triggered laboratory capacity bottlenecks and extended certification timelines. Hospitality contract channels are responding by consolidating supplier relationships toward vertically integrated manufacturers with captive testing facilities.
Direct-to-trade e-procurement platforms are displacing traditional rep-driven hospitality sales models, compressing price discovery and sample logistics into centralized digital workflows. Restaurant group purchasing consortia are aggregating volume across multiple independent operators to access tiered pricing previously reserved for national chains. This channel shift concentrates most visibly in Greater London's dense independent restaurant ecosystem, where procurement managers prioritize single-source catalog consolidation over multi-supplier relationships.
UK Ceramic Tableware Market Segmentation
Channel mix varies sharply across UK ceramic tableware segments. Hospitality procurement concentrates in vitrified hotelware, while retail channels fragment across design-led and mass-market positioning.
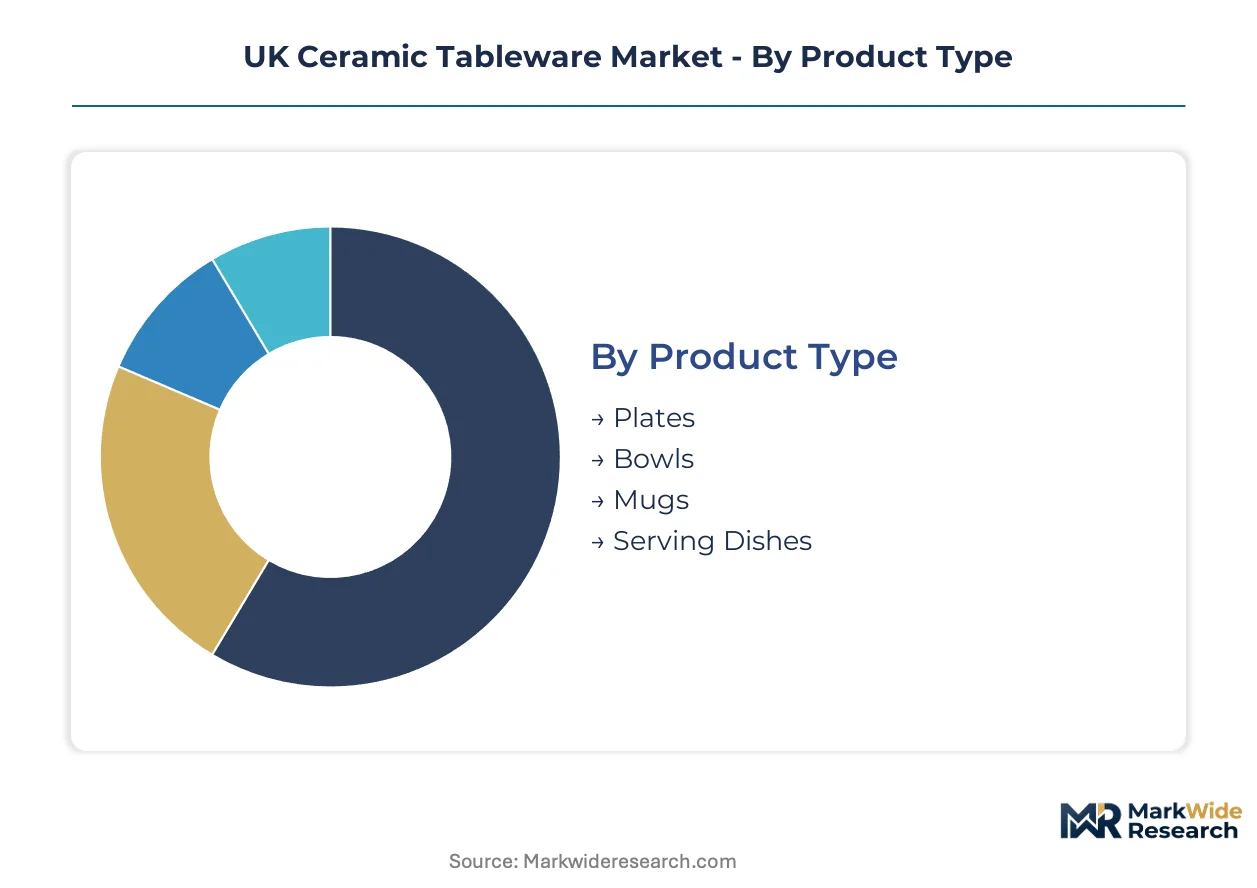
Product Type:
Plates and mugs dominate volume throughput across Stoke-on-Trent manufacturing, while serving dishes concentrate margin capture in contract hospitality channels.
- Plates:Vitrified porcelain and stoneware bodies fired at 1,200°C to 1,400°C achieve dishwasher durability for commercial hospitality. Demand concentrates in Staffordshire manufacturing for mid-scale restaurant group procurement.
- Mugs:High-volume production of cylindrical forms with handle attachment dominates automated kiln throughput. Greater London specialty retail channels pull artisan and design-led collections at premium positioning.
- Bowls:Deeper forms requiring controlled glaze flow management during firing.
- Serving Dishes:Larger format pieces command disproportionate margin pools in boutique hotel and restaurant contract bidding.
Plates dominate installed base. Serving dishes are where expansion concentrates.
Usage Occasion:
Cost tier stratification separates mass-market everyday positioning from formal dining premium extraction, with special occasions bridging volume and margin.
- Everyday Use:Functional earthenware and stoneware prioritizing chip resistance and microwave safety. Import price pressure from uncertified Asian ware compresses domestic margins in this tier.
- Formal Dining:Translucent porcelain with elevated glaze quality and decorative finishing. Greater London department store buyers source limited collections for registry and gift positioning.
- Special Occasions:Seasonal and commemorative patterns with shorter production runs.
- Outdoor Events:Lightweight, durable formulations for catering and hospitality rental channels.
Everyday use holds volume concentration. Formal dining is climbing the fastest.
Design Style:
Customer type fragmentation separates heritage-seeking collectors from contemporary hospitality specifiers, with minimalist positioning gaining traction in urban retail.
- Traditional:Heritage patterns referencing Staffordshire ceramic history with cobalt blue motifs and gilded detailing. Stoke-on-Trent master ceramicists anchor authenticity claims for export and domestic gift markets.
- Modern:Clean lines and neutral palettes aligned with contemporary hospitality interior design. Boutique hotel procurement teams specify these collections for brand consistency across property portfolios.
- Minimalist:Reduced surface decoration emphasizing form and glaze quality.
- Artistic:Limited edition and hand-finished pieces for collector and gallery retail channels.
Traditional commands heritage premium. Modern is gaining share fastest.
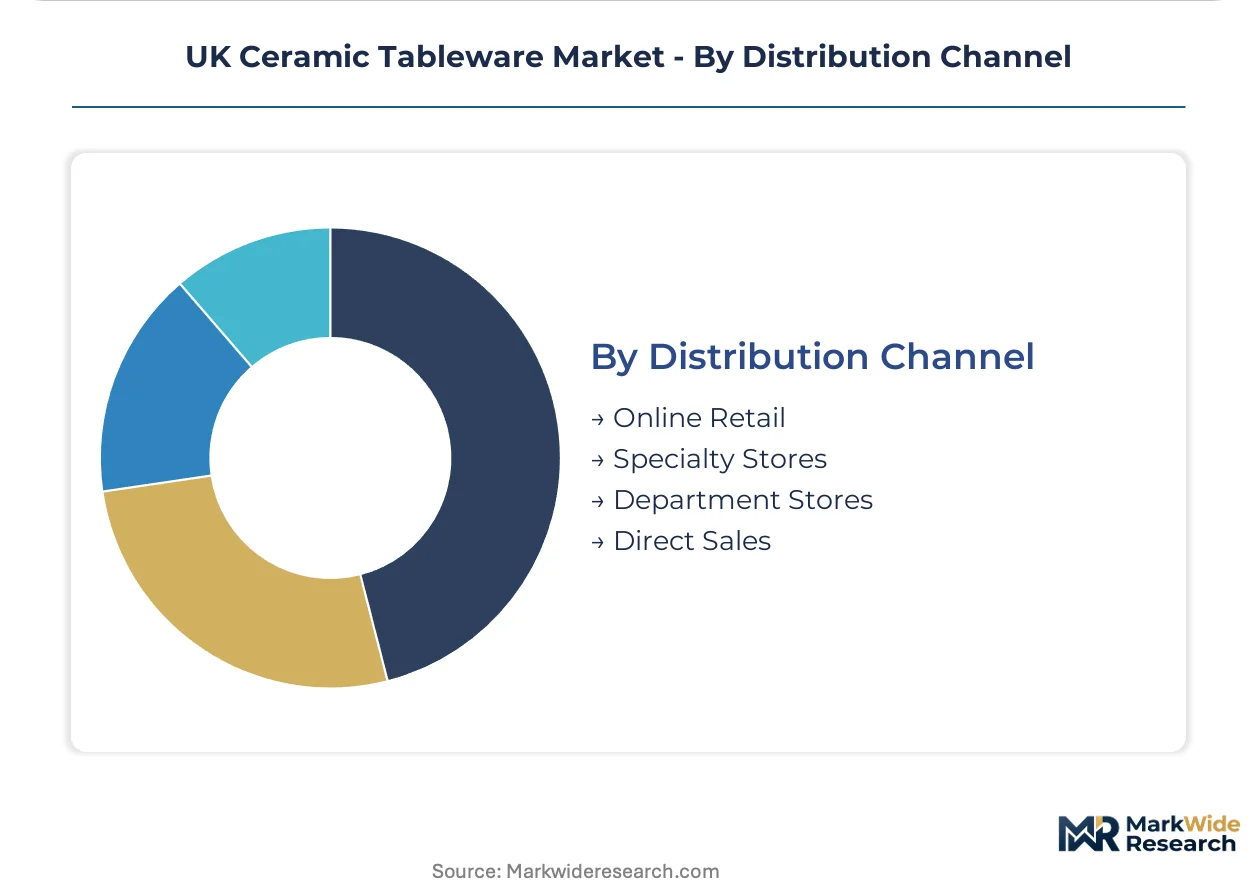
Distribution Channel:
Supply concentration in Staffordshire clusters shapes fulfillment economics, with digital channels fragmenting legacy rep-driven sales architecture.
- Online Retail:Direct-to-consumer platforms enabling 48-hour sample turnaround for hospitality contract bidding. E-procurement consolidation aggregates independent restaurant group purchasing power.
- Specialty Stores:Curated artisan collections with design consultation and registry services. Greater London density supports highest per-square-foot ceramic tableware revenue in this channel.
- Department Stores:Multi-brand assortment with seasonal promotional calendars.
- Direct Sales:Manufacturer-owned showrooms and trade exhibition presence for contract hospitality.
Department stores anchor legacy volume. Online retail shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospitality procurement teams and design-led retail buyers concentrate purchasing power in England's industrial clusters and London's commercial corridors. Regional variation reflects divergent channel access, regulatory proximity, and manufacturing heritage concentration.
London and the Southeast
Boutique hotel chains and independent restaurant groups drive premium hospitality procurement through specialized contract channels. The Food Standards Agency's enforcement of lead and cadmium migration limits shapes supplier qualification requirements for buyers in this corridor. Greater London's design-led retail density supports highest per-square-foot ceramic tableware revenue through department store and specialty channel concentration.
West Midlands and Staffordshire
The Stoke-on-Trent ceramics cluster anchors national vitrified hotelware capacity with integrated clay sourcing and kiln infrastructure. BSI kitemark certification requirements compress margins while creating tiered competitive access for manufacturers based in this concentration. Proximity of skilled ceramicists and remanufacturing facilities sustains short-lead production for mid-scale hospitality orders.
North England
Heritage manufacturing sites and artisan pottery workshops serve collector and gift market channels with traditional Staffordshire-influenced patterns. Extended Producer Responsibility framework consultations incentivize closed-loop glaze recycling investments among producers in this region. Yorkshire and Lancashire distribution nodes connect northern manufacturing to Scottish hospitality markets.
Scotland
Edinburgh and Glasgow hospitality sectors pull vitrified ware through procurement consortia serving independent restaurant groups. REACH compliance requirements for glaze constituents restrict market access for uncertified imports entering through Scottish ports. Highland and Islands tourism accommodation generates seasonal demand for durable outdoor event tableware formulations.
Wales
Small-batch artisan producers serve specialty retail and direct-to-consumer channels with limited design-led collections. Local authority environmental health regulations enforce batch-level laboratory certification extending production timelines. Cardiff and Swansea hospitality clusters represent emerging contract opportunities for BSI-certified domestic manufacturers.
UK Ceramic Tableware Market Competitive Environment
Player mix skews toward vertically integrated heritage manufacturers and design-led portfolio groups competing across tiered hospitality and retail channels. Market structure concentrates manufacturing capacity in the Staffordshire cluster while fragmenting brand presence across specialty and mass-market positioning. Two strategic archetypes dominate: vitrified hotelware specialists optimizing for commercial dishwasher durability, and artisan-heritage houses extracting premium through design differentiation and collector market access. Competitive moves center on captive testing facility investments to compress BSI certification timelines, and direct-to-trade e-procurement platform development to displace legacy rep-driven sales architectures.
Within the heritage-integrated tier, Churchill China and Portmeirion Group occupy positions exemplifying divergent strategic emphases—Churchill China representing Stoke-on-Trent manufacturing concentration with captive kiln infrastructure, Portmeirion Group anchoring design-led portfolio diversification across artisan and contemporary collections. Steelite International sits within the hospitality-specialist archetype, its market presence tied to vitrified hotelware specification for commercial durability requirements. These three companies collectively illustrate the competitive segmentation between manufacturing-scale efficiency and design-premium extraction that defines supplier positioning across UK procurement channels.
| Leading Market Players |
|---|
| Churchill China |
| Portmeirion Group |
| Steelite International |
| Dudson Group |
| Denby Pottery |
| Emma Bridgewater |
| Mason Cash |
| Wedgwood |
| Royal Doulton |
| Others |
Value Chain & Pricing Dynamics
Natural gas-to-electricity kiln conversion trials across Stoke-on-Trent simultaneously redraw fuel sourcing geographies and recast energy cost structures for vitrified ware producers. This substitution dynamic compresses margin predictability while rewarding early adopters with carbon levy positioning against import competition.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate hospitality procurement agreements, insulating Staffordshire manufacturers from spot volatility while exposing them to wholesale price spikes. Price differentiation separates BSI-certified vitrified tiers from uncertified import alternatives, with certification grade and volume scale as primary drivers. Pricing pressure stems from direct-to-consumer Asian e-commerce undercutting domestic everyday-use positioning. Independent restaurant groups exhibit highest price sensitivity, while boutique hotel chains prioritize durability specifications over unit cost.
Supply Chain Analysis
Inventory cycles of six to eight weeks for finished vitrified hotelware reflect kiln batch constraints and seasonal hospitality ordering patterns. Supply concentrates in England's Staffordshire cluster, with secondary capacity in Portugal and limited artisan production in Wales. Raw material dependencies center on Cornish china clay, feldspar from Norway, and cobalt pigments from the Democratic Republic of Congo. Single-source vulnerability sits with natural gas pipeline infrastructure for firing operations. Distribution runs through direct-to-trade e-procurement platforms displacing legacy rep networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The narrowing pipeline of master ceramicists with hand-throwing and kiln-firing expertise constrains artisan collection scaling, creating acquisition premiums for heritage manufacturers with captive skill development programs.
For Market Incumbents: Consolidate testing facility investments to compress BSI certification timelines against third-party laboratory queue bottlenecks. Deepen captive clay sourcing through Cornwall deposit agreements to hedge import mineral volatility. Defensive priority centers on carbon border adjustment alignment to capture public sector procurement preference as import ceramic costs rise. For New Entrants and Emerging Players: Differentiate on REACH-compliant glaze chemistry eliminating restricted substances for EU re-export market access. White-space targets include Welsh hospitality clusters underserved by BSI-certified domestic suppliers and micro-batch digital decoration for boutique hotel custom pattern specifications. Go-to-market angle leverages 48-hour sample turnaround through single-fire inkjet technology. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed hospitality ware specialists lacking vertical integration into kiln infrastructure. Long-term viability favors manufacturers with captive Staffordshire production bases and design-led portfolio diversification across heritage and contemporary positioning. Signal to monitor: Food Standards Agency batch traceability enforcement tightening as inflection indicator for compliance cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Facility Investment | BSI kitemark certification timelines compress from weeks to days for hospitality contract bidding. |
| Digital Decoration Technology Deployment | Single-fire inkjet systems reduce energy consumption while enabling micro-batch customization. |
| Closed-Loop Glaze Recycling System | Extended Producer Responsibility frameworks incentivize domestic remanufacturing investments. |
| Direct-to-Trade E-Procurement Platform | Centralized digital workflows displace legacy rep-driven sales architectures in Greater London. |
| Cornish Clay Deposit Long-Term Agreement | Upstream mineral control hedges feldspar and pigment import volatility for vitrified body formulations. |
Study Parameters
Cross-validation between primary hospitality procurement interviews and secondary regulatory filing analysis anchors the qualitative findings. Plant managers at Stoke-on-Trent vitrified hotelware facilities, category buyers at Greater London department stores, Food Standards Agency compliance officers, and independent restaurant group purchasing managers provided operational perspective. Secondary sources encompassed BSI certification databases, Food Standards Agency enforcement bulletins, UK government Extended Producer Responsibility consultation documents, and customs trade records. Bottom-up production capacity estimates triangulated against top-down hospitality procurement spend analysis.
Sensitivity analysis across natural gas price scenarios and carbon levy implementation timelines informed projection robustness. The analytical framework segmented volume and value across product type, usage occasion, design style, and distribution channel dimensions throughout the forecast period. CAGRs derived from historical production trajectory analysis adjusted for regulatory compliance cost step-changes and hospitality sector recovery patterns. Industry-specific inputs included kiln capacity utilization rates and BSI certification queue length trends.
Material uncertainties — wholesale energy pricing volatility, REACH enforcement intensity, and carbon border adjustment mechanism timing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding hospitality procurement recovery and regulatory implementation schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
Asia-Pacific Modular Kitchen Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Oman Kitchen Hood Market
Kitchen and Dining
Dining Table Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
China Kitchen Products Market