
 United Kingdom Furniture Market | 2026-2036
United Kingdom Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Furniture Market Analytics
The United Kingdom furniture market is repositioning around a widening split between heritage craftsmanship commanding premium price points and flat-pack commodity lines competing on cost and speed. DFS Furniture leverages its vertically integrated British manufacturing to sustain domestic production credibility. Howdens Joinery Group anchors its position through trade-only distribution, controlling kitchen and joinery supply to builders. Dunelm Group competes across mid-market soft furnishings with broad SKU breadth and rapid online fulfilment.
United Kingdom furniture encompasses movable objects constructed from wood, metal, upholstered textiles, or glass, engineered for human support, storage, or workspace organisation within interior environments. Manufacturing processes span CNC-machined hardwood frames, cold-rolled steel fabrication, foam-in-place upholstery systems, and tempered glass tempering, with flammability compliance testing mandated under domestic safety law. Sofas and upholstered seating command the largest revenue pool due to replacement-driven residential demand, while online distribution channels are capturing the fastest volume growth as logistics networks compress delivery windows. Wood materials dominate structural categories, though metal and glass gain share in commercial and hospitality fit-outs where durability and aesthetic minimalism matter.
The UK's Furniture and Furnishings (Fire) (Safety) Regulations, enforced by local trading standards authorities, mandate ignition resistance testing for foam fillings and cover fabrics, directly constraining material sourcing and design freedom. BSI Kitemark certification and EU-derived CE marking under retained law continue shaping product liability and market access benchmarks for imported and domestically manufactured goods. Stakeholders must monitor potential divergence between UK-specific safety standards and evolving EU harmonised norms post-Brexit, as regulatory misalignment would fragment sourcing strategies and compliance costs.
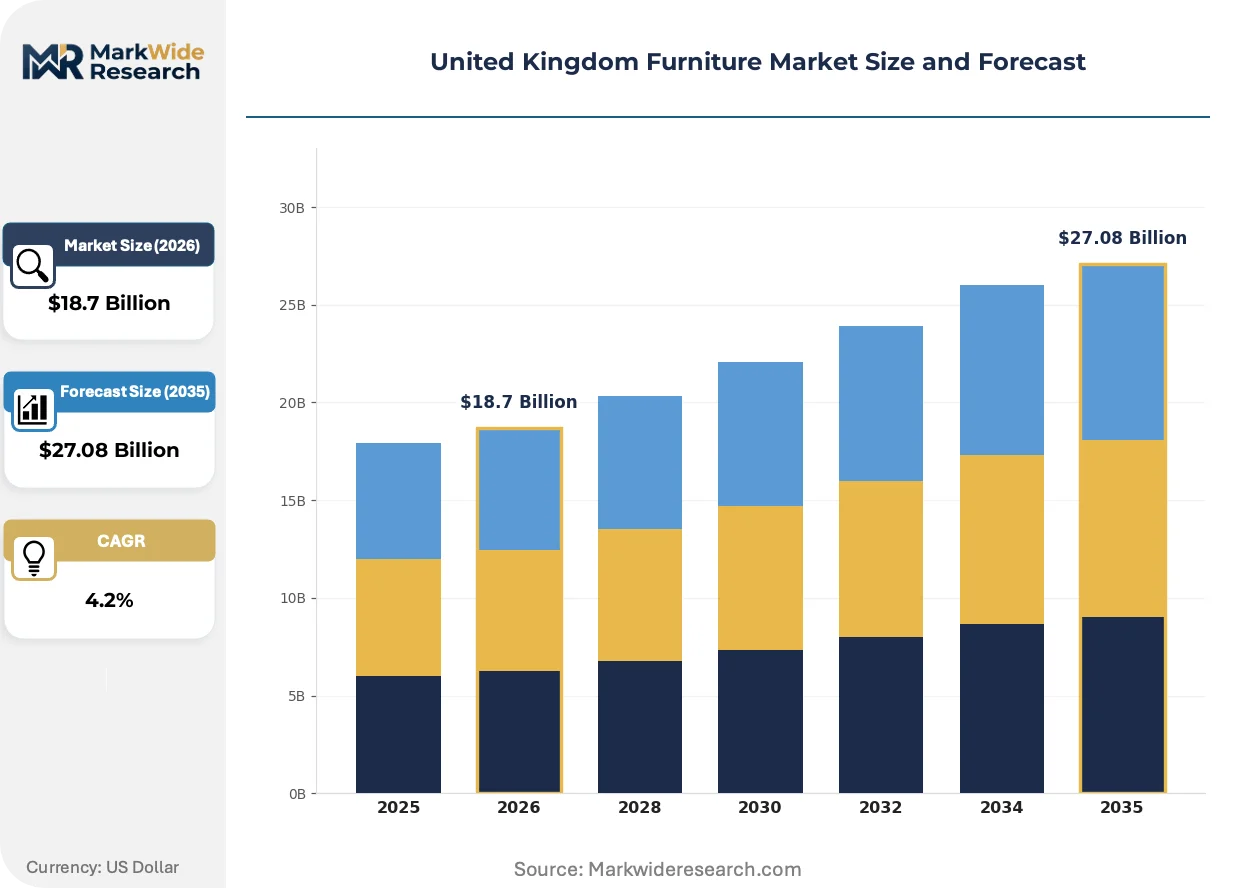
Market Dynamics
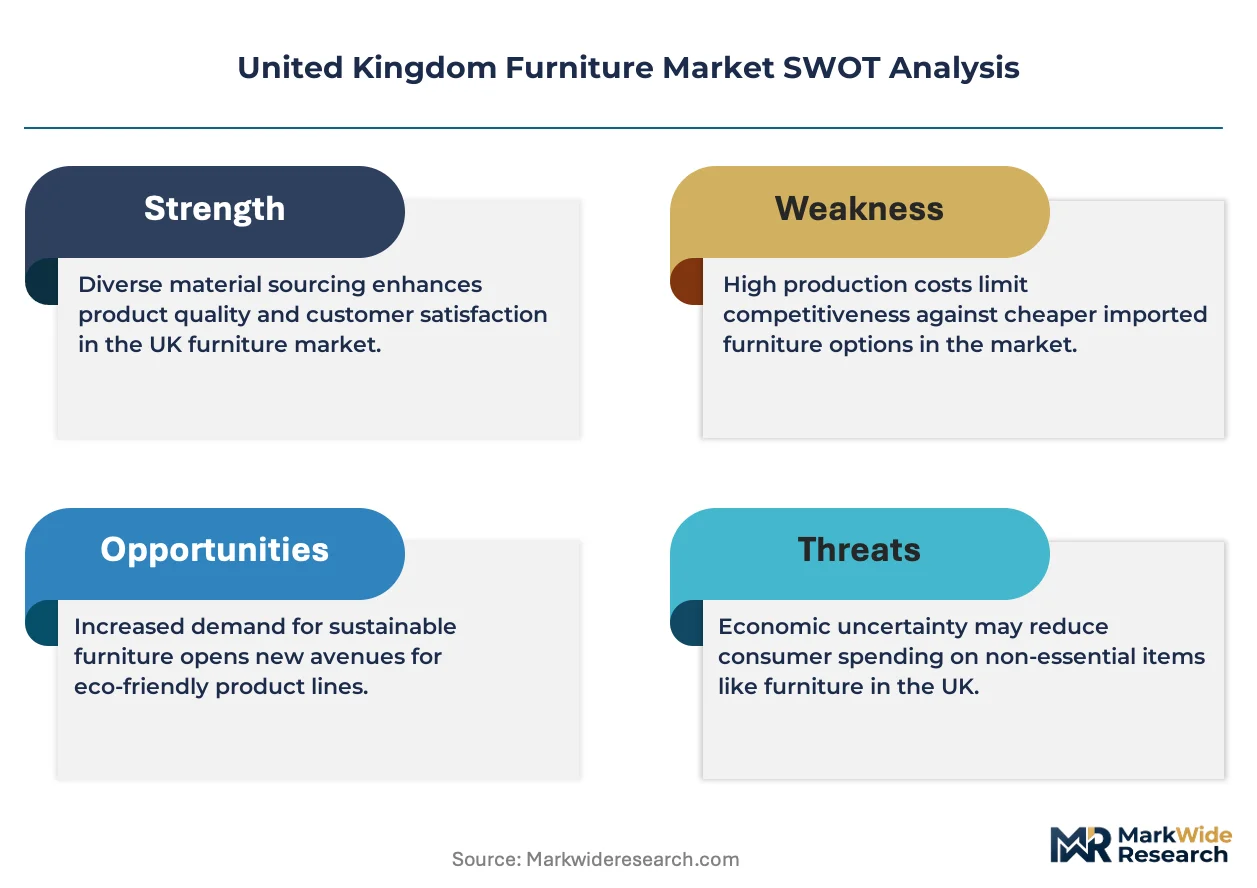
The UK's Furniture and Furnishings (Fire) (Safety) Regulations 1988 and its amendments are compressing design freedom while elevating compliance costs, forcing manufacturers to reengineer foam formulations and fabric sourcing. This regulatory pressure intersects with residential renovation cycles to reshape competitive positioning between heritage craft and commodity flat-pack producers.
Growth Catalysts
- Residential renovation activity:Greater London and South East property turnover sustains replacement-driven demand for sofas and upholstered seating as households refresh interiors between ownership transfers.
- BSI Kitemark certification:Third-party flammability testing creates quality signaling that protects domestic manufacturers from low-cost imports lacking equivalent safety verification.
- CNC machining adoption:Automated hardwood frame production reduces lead times for bespoke furniture, enabling British workshops to compete with offshore assembly on speed-to-delivery.
Market Restraints
- Polyurethane foam price volatility:Petrochemical feedstock fluctuations squeeze margin on upholstered products where foam constitutes substantial material cost.
- EU regulatory divergence risk:Post-Brexit misalignment between UK flammability standards and evolving EU harmonised norms threatens to fragment sourcing strategies for cross-border suppliers.
- Flat-pack substitution pressure:Cost-conscious consumers trade down to particleboard alternatives, compressing addressable market for solid wood heritage positioning.
Strategic Opportunities
- Scottish and Northern English underpenetration:Lower property turnover rates in these sub-regions indicate latent replacement demand as housing mobility eventually normalises.
- CE marking retention:Maintaining EU-derived conformity assessment expands export eligibility to Republic of Ireland and continental markets without duplicate certification burden.
- Online fulfilment infrastructure:Compressed delivery windows through dedicated furniture logistics networks enable direct-to-consumer channels to capture volume from traditional showroom retail.
Industry Challenges
- Upholstery craft skill scarcity:Traditional hand-tied spring and horsehair stuffing techniques face generational attrition, constraining premium heritage production capacity.
- Flammability testing timeline compression:Local trading standards enforcement demands extended pre-market validation cycles that delay new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Furniture Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Beds Material: Wood, Metal, Upholstered, Glass Distribution Channel: Online, Retail Stores, Showrooms, Wholesale End User: Residential, Commercial, Hospitality, Offices |
| Companies Covered | Dunelm Group, Symphony Group, IKEA UK Ltd, Habitat, Heal’s, Howdens Joinery Group, DFS Furniture, Flexiform, Wren Kitchens Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Furniture Market Evolving Landscape
Digital fabrication and regulatory digitisation are converging to reshape how British furniture is designed, certified, and delivered. These shifts favour operators who can integrate compliance automation with responsive manufacturing.
CNC-machined hardwood frame production is consolidating workshop-scale custom furniture into scalable operations. Regional manufacturers serving architects and interior designers are adopting five-axis routing to reduce hand-finishing labour. This technology diffusion is compressing the price gap between bespoke and semi-custom product tiers.
The UK's retained EU law framework around CE marking is diverging from Brussels regulatory updates, creating compliance uncertainty for importers. Trading standards authorities in England and Wales are enforcing UKCA transition timelines that differ from Scottish implementation guidance. Upholstered seating manufacturers with cross-border supply chains face the highest adaptation burden as they reconcile dual conformity requirements.
Direct-to-consumer showroom bypass is displacing traditional retail intermediation in soft furnishings and bedroom furniture. Dunelm's rapid online fulfilment model demonstrates logistics density enabling next-day delivery promises. Greater London households exhibit the strongest channel-switching behaviour, with suburban and ex-urban catchments following at slower adoption rates.
United Kingdom Furniture Market Segmentation
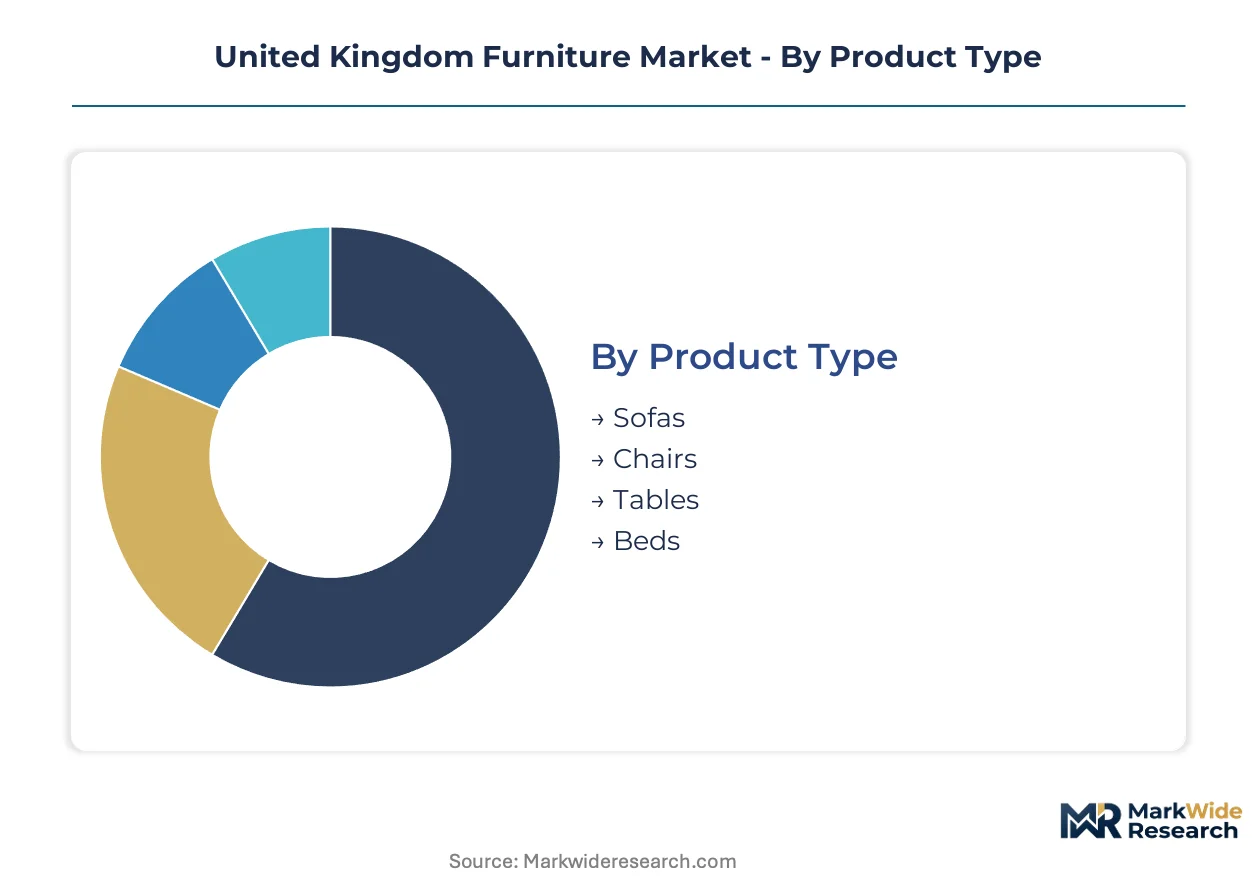
Segmentation in the United Kingdom furniture market reveals how capital deployment, regulatory exposure, and channel economics split competitive returns across product lines. Manufacturers must align production assets against the specific compliance and logistics demands of each slice.
Product Type:
Capital intensity peaks where foam-in-place upholstery systems and flammability testing cycles dominate production economics.
- Sofas:Foam-in-place upholstery systems with hardwood frames require dedicated cutting and sewing stations plus extended flammability validation under the Furniture and Furnishings (Fire) (Safety) Regulations. Greater London residential turnover sustains replacement demand, though polyurethane feedstock volatility squeezes margin on high-volume lines.
- Chairs:Dining and accent seating span CNC-machined hardwood to tubular steel fabrication, with lower per-unit foam content reducing regulatory testing burden relative to fully upholstered pieces. South East hospitality fit-outs drive specification-grade demand for contract durability ratings.
- Tables:Structural categories concentrate sawmill-to-finish capacity in particleboard, solid oak, and tempered glass combinations.
- Beds:Divan and frame production couples sprung base manufacturing with headboard upholstery, splitting capital between woodworking and textile operations.
Most installed capacity flows through Sofas. Expansion is steepest in Chairs.
Material:
Supply chain configuration determines which material classes absorb freight and tariff exposure from divergent sourcing geographies.
- Wood:CNC-machined hardwood frames and particleboard substrates anchor domestic manufacturing credibility, with British sawmills supplying oak, ash, and beech to heritage-positioned workshops. Flammability compliance concentrates on finished goods rather than raw timber, reducing pre-market testing timelines versus upholstered competitors.
- Metal:Cold-rolled steel and aluminum extrusion serve commercial and hospitality segments where durability specifications exceed residential wear expectations. Birmingham and Sheffield fabrication clusters compress lead times for contract furniture specifying BS EN 1725 structural load ratings.
- Upholstered:Foam formulations and fabric sourcing face the strictest ignition resistance mandates, constraining design freedom and elevating compliance costs.
- Glass:Tempered and laminated glass integrates into tabletops and display units, with thickness specifications varying by end-use safety requirements.
Wood commands the largest production footprint. Upholstered categories are climbing the fastest as online fulfilment compresses delivery windows for soft seating.
Distribution Channel:
Margin structure fragments between inventory-heavy showroom operations and asset-light digital intermediation.
- Online:Direct-to-consumer platforms bypass retail intermediation through dedicated furniture logistics networks enabling next-day delivery promises in Greater London and South East catchments. Compressed return windows and damage rates in last-mile handling elevate customer acquisition costs relative to in-store conversion.
- Retail Stores:High-street and out-of-town superstores carry inventory risk for fast-turn accessories while operating made-to-order systems for bulky items. Foot traffic dependency concentrates performance in suburban and ex-urban locations with parking accessibility.
- Showrooms:Trade-only and public display spaces serve specification-grade procurement where tactile evaluation precedes contract commitment.
- Wholesale:Builder merchant and independent furniture retailer supply operates on volume rebates and extended payment terms.
Retail Stores still absorb the majority of volume. Online channels are gaining share fastest as logistics density enables showroom bypass.
End User:
Procurement authority and replacement cycle length diverge sharply between owner-occupier households and institutional specification.
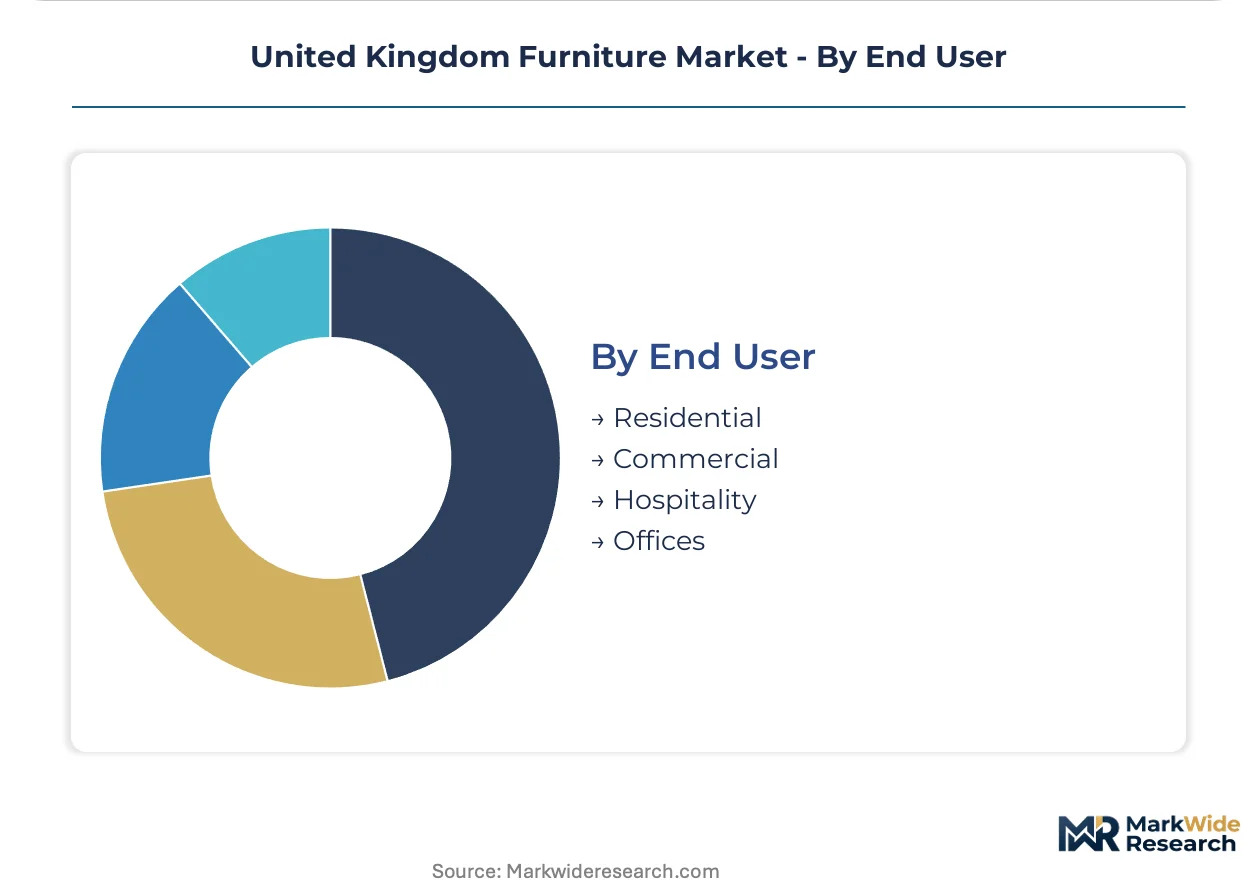
- Residential:Owner-occupier replacement demand concentrates in Greater London and South East property turnover corridors, with renovation activity pulling upholstered seating refresh. Individual purchasing decisions favor cost-accessible flat-pack alternatives for secondary bedrooms and home office setups.
- Commercial:Corporate office fit-outs specify contract-grade durability ratings and fire safety certification for open-plan and executive environments. Procurement runs through facilities management intermediaries with multi-year framework agreements.
- Hospitality:Hotel, restaurant, and bar operators prioritize rapid-turn replacement cycles and stain-resistant fabric treatments.
- Offices:Dedicated workplace furniture spans task seating, storage, and meeting tables with ergonomic certification requirements.
Residential captures the deepest volume base. Commercial applications are expanding most quickly as hybrid workplace models drive fit-out reinvestment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled upholstery craftsmen cluster in England's traditional manufacturing heartlands, with frame makers and foam specialists distributed across Midlands fabrication zones and Scottish timber regions.
London and South East
Property turnover rates in Greater London and surrounding counties sustain replacement-driven demand for sofas and upholstered seating. Trading standards authorities enforce the Furniture and Furnishings (Fire) (Safety) Regulations through pre-market testing validation. High Wycombe's historic chair-making district now hosts CNC machining operations serving architect-specified contract furniture.
Midlands
Nottinghamshire and Leicestershire concentrate divan bed manufacturing alongside upholstered headboard production. Local trading standards offices coordinate flammability compliance enforcement across foam formulation suppliers. Birmingham's metal fabrication heritage supports cold-rolled steel frame production for commercial seating specifications.
North England
Lancashire and Yorkshire retain wool textile weaving capacity feeding heritage upholstery workshops. The retained EU law framework around CE marking creates compliance complexity for exporters serving Republic of Ireland markets. Manchester's logistics infrastructure enables next-day delivery fulfillment to suburban catchments.
Scotland
Scottish Borders and Aberdeen timber mills supply hardwood frames to domestic workshops. The Scottish government's implementation guidance on UKCA marking diverges from English and Welsh trading standards timelines. Edinburgh's interior design sector specifies bespoke joinery for hospitality fit-outs.
Wales
South Wales manufacturing zones produce particleboard substrates for flat-pack assembly systems. Welsh trading standards authorities apply Furniture and Furnishings (Fire) (Safety) Regulations enforcement with regional inspection priorities. Cardiff's retail corridors channel mid-market furniture distribution to ex-urban households.
United Kingdom Furniture Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered positioning. Domestic manufacturers with captive sawmill and upholstery operations face pressure from import-reliant retailers optimizing logistics density. Three archetypes dominate: vertically integrated heritage workshops, trade-only kitchen specialists, and broad-assortment soft furnishings operators. Competitive moves center on showroom network consolidation and dedicated furniture logistics infrastructure deployment.
Among UK-based operators, DFS Furniture plc exemplifies vertically integrated manufacturing credibility through domestic hardwood frame production. Howdens Joinery Group plc occupies the trade-only distribution position controlling builder merchant supply channels. Dunelm Group plc anchors the mid-market soft furnishings tier with rapid online fulfillment capabilities. These three represent the structural separation between craft-positioned, trade-captive, and mass-market retail archetypes.
| Leading Market Players |
|---|
| Dunelm Group |
| Symphony Group |
| IKEA UK Ltd |
| Habitat |
| Heal's |
| Howdens Joinery Group |
| DFS Furniture |
| Flexiform |
| Wren Kitchens Ltd |
| Others |
Value Network & Pricing Analysis
Flammability certification under the UK's Furniture and Furnishings (Fire) (Safety) Regulations gates both qualified foam suppliers and premium-tier pricing access, compressing margins for uncertified imports while rewarding domestic manufacturers with BSI Kitemark verification. This regulatory filter concentrates pricing power among incumbents who have absorbed compliance costs into captive upholstery operations.
Pricing Analysis
Bundled delivery-and-assembly services command 15-25% premiums over unbundled product-only transactions, particularly in Greater London where logistics density enables next-day fulfillment promises. Three-tier pricing structure across heritage craft, mid-market semi-custom, and flat-pack economy levels reflects certification grade and domestic manufacturing credibility. Cost compression in particleboard flat-pack tiers is intensifying because petrochemical feedstock volatility squeezes foam-dependent upholstered lines. First-time buyers and rental property investors exhibit highest price sensitivity, while architect-specified contract purchasers prioritize fire safety certification over unit economics.
Supply Chain Analysis
Reverse-logistics flows for sofa returns and refurbishment are expanding as online fulfillment elevates damage rates in last-mile handling, creating secondary market supply for reupholstery specialists. Manufacturing concentration spans China for particleboard substrates, Poland for upholstered component assembly, and domestic Midlands workshops for CNC-machined hardwood frames. Raw material dependencies center on Baltic birch plywood, Malaysian rubberwood, and petrochemical-derived polyurethane foam formulations. Single-source vulnerability concentrates in flame-retardant chemical suppliers facing REACH regulatory restriction. Distribution runs through dedicated furniture logistics networks bypassing traditional retail intermediation in Greater London and South East catchments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom furniture market operates as a regulatory compounder where the 1988 Furniture and Furnishings (Fire) (Safety) Regulations and subsequent amendments continuously reshape competitive economics by elevating compliance barriers that protect domestic incumbents.
For Market Incumbents: Deploy CNC machining capacity expansion to compress bespoke-to-delivery timelines against offshore flat-pack competitors. Capture trade-only distribution channels through builder merchant exclusivity agreements that lock out import-reliant retailers. Counter polyurethane foam price volatility through backward integration into foam formulation or long-term supply agreements with certified chemical suppliers. For New Entrants and Emerging Players: Independent interior designers represent the most accessible channel partner type for heritage-positioned workshops seeking specification-grade procurement authority. Target Scottish Borders and Northern England sub-regions where lower property turnover has suppressed replacement demand that will normalize. Penetrate through architect-direct relationships emphasizing UKCA-compliant fire safety certification as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated upholstery specialists because generational craft skill attrition constrains premium production capacity expansion. Five-to-ten year viability hinges on regulatory divergence between UK and EU flammability standards creating persistent compliance moats. Monitor trading standards enforcement intensity and UKCA marking implementation timelines as inflection indicators for import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Flammability Certification Investment | BSI Kitemark acquisition protects domestic manufacturers from uncertified import competition under retained EU law. |
| CNC Machining Capacity Expansion | Five-axis routing adoption compresses bespoke furniture lead times against offshore assembly in architect-specified segments. |
| Direct-to-Consumer Logistics Buildout | Dedicated furniture delivery networks enable next-day fulfillment promises that displace traditional showroom retail in Greater London. |
| Trade-Only Distribution Exclusivity | Builder merchant channel control locks out competitors from kitchen and joinery specification through Howdens-style positioning. |
| Scottish and Northern English Market Development | Latent replacement demand in underpenetrated sub-regions offers volume expansion as housing mobility normalizes. |
Research Methodology
Multiple input streams — structured interviews with furniture manufacturing executives, regulatory compliance officers, and architect procurement leads; trade data from HMRC customs records and Office for National Statistics production surveys; and company filings from listed operators — were reconciled through bottom-up production capacity modeling and top-down demand segmentation triangulation. Secondary validation drew from trading standards enforcement reports, BSI certification databases, and regional property transaction data.
Historical volume trajectories were cross-referenced against panel input from upholstery workshop owners and logistics network operators to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product type, material class, distribution channel, and end-user procurement authority. CAGRs were derived from replacement cycle analysis tied to regional property turnover rates and renovation expenditure patterns, with flammability regulatory compliance timelines and petrochemical feedstock cost indices serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to UK-EU regulatory divergence and generational upholstery craft attrition. Practitioners should monitor trading standards enforcement intensity, UKCA marking implementation timelines, and polyurethane foam price volatility for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Bean Bag Chairs Market
Furniture
Armchairs with Footrest Market
Furniture
Children's Home Study Desks Market
Furniture
Russia Home Furniture Market
Furniture
Furniture & Cabinet Hardware Market
Furniture
Ergonomic Chair for Children Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Spain Furniture Market
Furniture
US Sustainable Furniture Market
Furniture
United Arab Emirates Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Saudi Arabia Home Furniture Market
Furniture
Pedicure Chair Market
Furniture
Italy Office Furniture Market
Furniture
Indonesia Furniture Market
Furniture
Europe Wood Decorative Wall Panel Market