
 Europe Kitchen Hobs Market | 2026-2036
Europe Kitchen Hobs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Kitchen Hobs Market Foresight
The Europe kitchen hobs category is decoupling into two distinct performance tiers. Premium built-in induction systems with zoneless cooking surfaces and bridge-fusion zones now command fundamentally different margin structures than commodity gas-on-glass alternatives. Miele & Cie. KG anchors the upper tier through captive motor manufacturing and German domestic production. Electrolux AB competes across both tiers with modular platform architectures that share chassis components between brands. Arçelik A.Ş. dominates value-oriented electric hobs through Turkish manufacturing scale and private-label supply contracts with continental retailers.
A kitchen hob is a flat cooking surface, typically 60–90 cm in width, housing gas burners, electric resistive elements, or electromagnetic induction coils beneath a tempered glass or stainless-steel top, designed to heat cookware directly for residential or commercial food preparation. Gas hobs retain installed-base dominance in Southern Europe where existing pipeline infrastructure lowers switching costs, though their growth trajectory has flattened. Induction hobs represent the fastest-expanding product type, driven by ErP-mandated efficiency minimums and consumer preference for precise thermal control; touch control interfaces increasingly displace knob mechanisms in this segment as digital user experience becomes a differentiation vector. Built-in installation types capture the majority of replacement demand, while freestanding units concentrate in rental housing and temporary commercial kitchens.
The EU Ecodesign Directive and F-Gas Regulation shape product development trajectories by mandating efficiency disclosures and restricting fluorinated greenhouse gases in manufacturing processes. CE marking requirements enforce electrical safety and electromagnetic compatibility standards that raise compliance costs for non-European suppliers. Germany's Federal Environment Agency and France's ADEME administer national rebate programs that accelerate induction adoption in existing building stock. Stakeholders must monitor how the EU Green Deal's building renovation wave redirects public subsidy flows between efficiency upgrades and appliance replacement cycles.
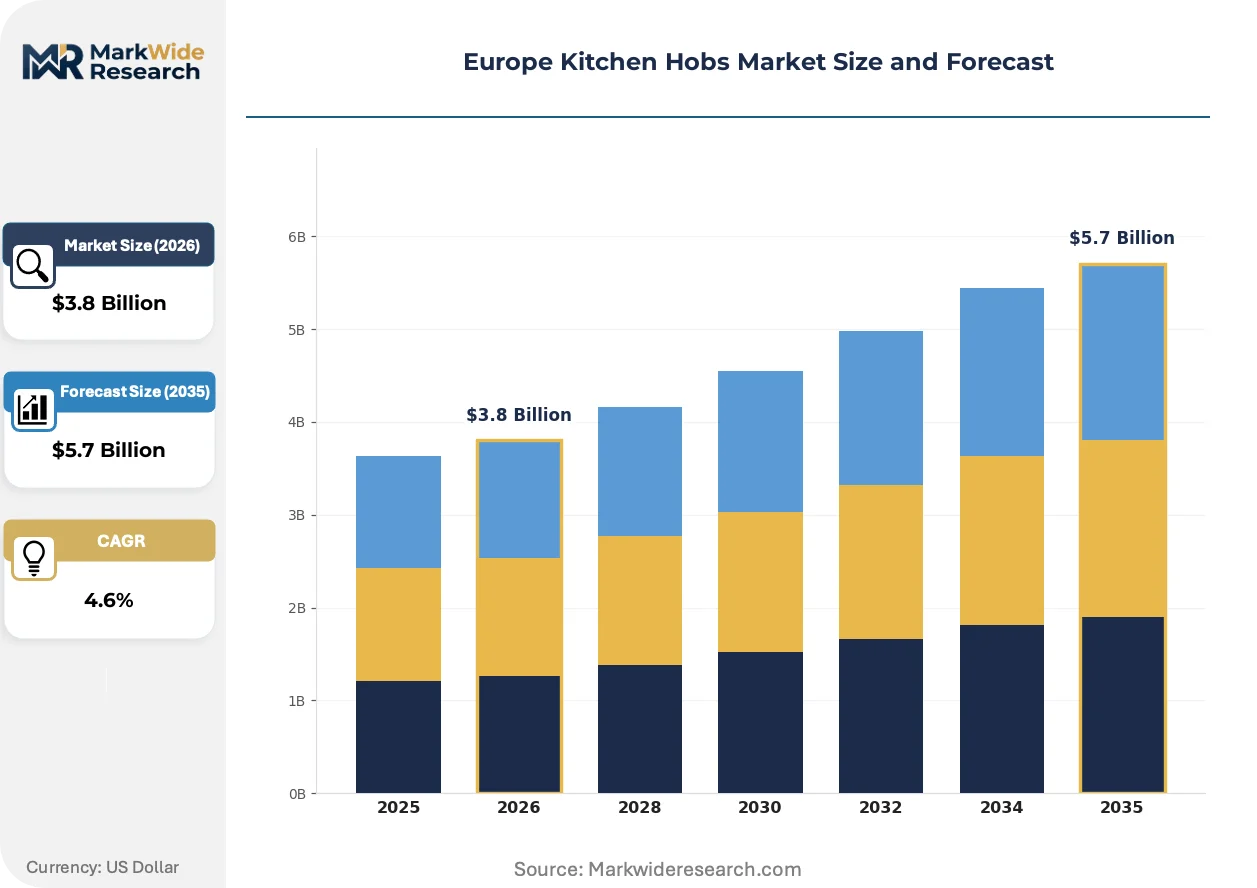
Market Dynamics
The EU Ecodesign Directive is compressing replacement cycles across Europe's kitchen hobs installed base by mandating efficiency disclosures that expose performance gaps in aging gas systems. This regulatory pressure is redirecting renovation spending toward induction platforms with zoneless coil architectures.
Growth Catalysts
- ErP-mandated efficiency minimums:These thresholds disqualify legacy resistive electric hobs from new installations, forcing builders and renovators toward electromagnetic induction systems in Germany, France, and Italy.
- Residential kitchen renovations:Germany's premium appliance corridor exhibits decisive preference for energy-labeled products, accelerating replacement demand for built-in systems with bridge-fusion zones.
- Bridge-fusion zone technology:This coil architecture enables contiguous cooking surfaces that accommodate irregular cookware shapes, driving specification upgrades in mid-market kitchen refits.
Market Restraints
- Copper coil cost volatility:Induction hob manufacturing depends on copper for electromagnetic coils, exposing margin structures to commodity price swings that compress working capital for mid-tier producers.
- Southern European gas infrastructure lock-in:Existing pipeline networks in Spain, Portugal, and Greece lower switching costs for gas hobs, creating installed-base inertia that slows induction penetration rates.
- CE marking compliance costs:Electromagnetic compatibility testing and electrical safety certification raise barriers for non-European suppliers attempting continental market entry.
Strategic Opportunities
- France's ADEME rebate programs:National subsidies for efficient appliance replacement in existing building stock create demand pull for premium induction systems in renovation channels.
- Zoneless cooking surface convergence:Integration of touch control interfaces with sensor-based pan detection is opening specification opportunities in high-end residential developments.
- Turkish manufacturing scale:Arçelik's captive production capacity positions private-label suppliers to capture value-oriented electric hob demand through continental retail contracts.
Industry Challenges
- Electromagnetic compatibility certification timelines:CE marking requirements for interference testing extend product launch cycles, compressing revenue recognition windows for seasonal kitchen renovation demand.
- Touch control interface integration:Digital user experience differentiation demands software engineering capabilities that traditional appliance manufacturers must acquire or partner to deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Kitchen Hobs Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Hobs, Electric Hobs, Induction Hobs, Dual Fuel Hobs Installation Type: Built-In, Freestanding, Portable, Drop-In Control Type: Touch Control, Knob Control, Slide Control, Remote Control End User: Residential, Commercial, Professional Chefs, Catering Services |
| Companies Covered | Miele & Cie. KG, Samsung Electronics, BSH Home Appliances, Gorenje Group, LG Electronics, Electrolux AB, Arçelik A.Ş., SMEG S.p.A., Whirlpool Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Kitchen Hobs Market Shifts & Advancements
Induction coil architectures are fragmenting into distinct performance tiers that demand fundamentally different manufacturing competencies and margin structures. This technological divergence is reshaping competitive positioning across Europe's kitchen hobs value chain.
Zoneless electromagnetic induction is modularizing around standardized coil matrices that accommodate variable cookware placement without predefined burner boundaries. German premium appliance manufacturers are adopting these architectures fastest, integrating them with bridge-fusion capabilities that merge adjacent cooking zones. This modularity is enabling platform sharing between product lines while compressing development costs for mid-market variants.
The EU F-Gas Regulation is restricting fluorinated greenhouse gases in manufacturing processes, forcing coil encapsulation and glass bonding suppliers to reformulate adhesive chemistries. This industrial consequence raises material costs for induction hob assembly while creating compliance differentiation for early reformulators. Southern European gas hob producers face the steepest adaptation burden due to limited in-house chemical engineering capabilities.
Kitchen renovation procurement is fragmenting between project-based contractor channels and direct-to-consumer retail. German and French buyers increasingly research energy labels online before specifying appliances, displacing traditional kitchen studio intermediaries. This channel rotation concentrates price transparency pressure on mid-tier brands while rewarding premium positioning with demonstrable efficiency credentials.
Europe Kitchen Hobs Market Segmentation
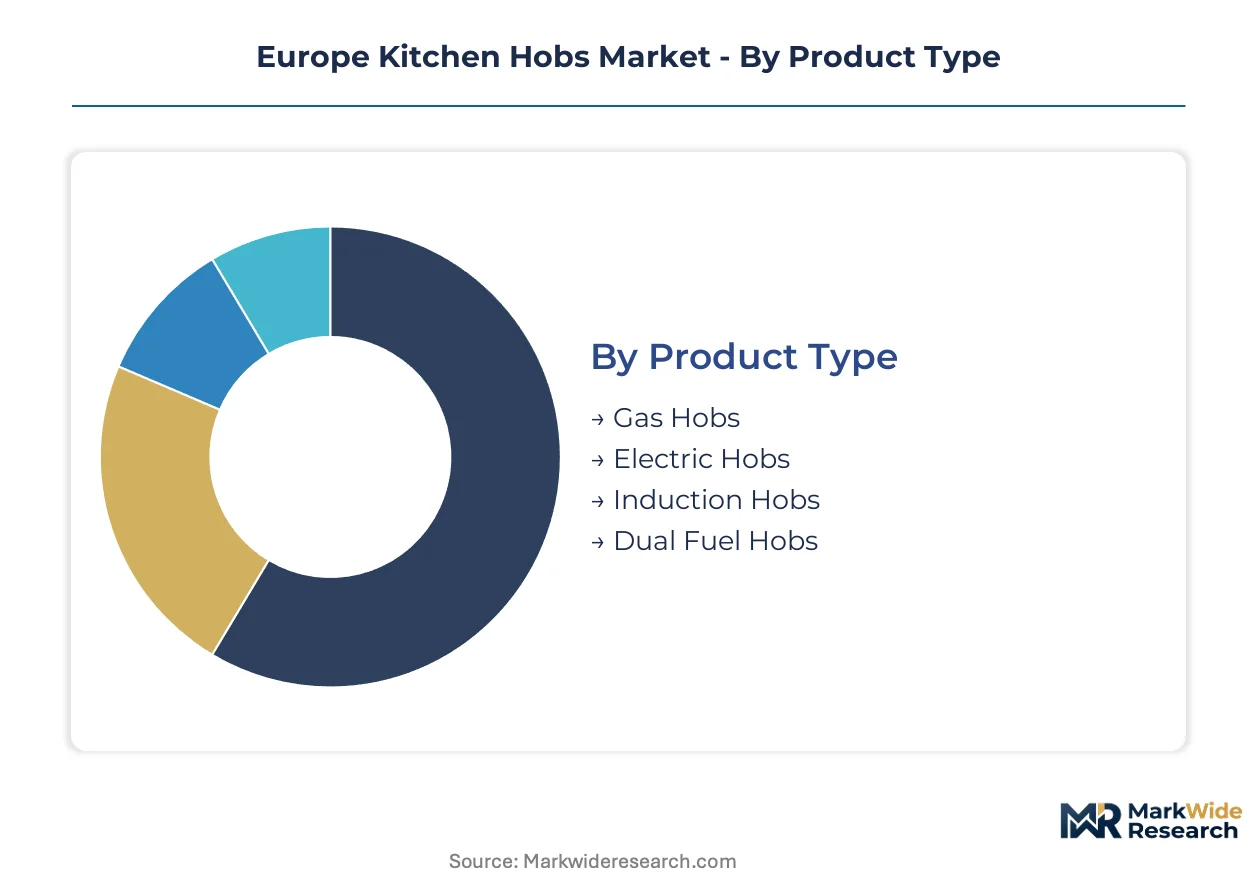
European kitchen hob procurement fragments across four distinct segmentation axes. Product type and installation format determine manufacturing scale economies, while control interface and end-user specifications dictate margin capture and channel strategy.
Product Type:
Supply concentration tilts heavily toward electromagnetic coil production in Germany and Turkey, with gas burner assembly retaining pockets of Southern European manufacturing.
- Induction Hobs:Electromagnetic coil systems beneath ceramic glass surfaces deliver thermal efficiency above 90%. German premium appliance corridors specify these for energy-labeled kitchen renovations, with ErP-mandated minimums disqualifying resistive alternatives in new installations.
- Gas Hobs:Atmospheric or sealed burner configurations atop tempered glass or stainless steel retain installed-base dominance where pipeline infrastructure lowers switching costs. Spanish and Portuguese replacement demand concentrates here despite flattening growth trajectories.
- Electric Hobs:Resistive radiant elements beneath glass-ceramic surfaces serve value-oriented renovation channels. Turkish manufacturing scale positions private-label suppliers to capture continental retail contract volume.
- Dual Fuel Hobs:Hybrid configurations combining gas burners with electric or induction zones accommodate transitional kitchen designs. French and Italian mid-market refits specify these for flexible cooking surface requirements.
Induction hobs absorb the bulk of installed capacity expansion; dual fuel configurations are expanding most quickly in transitional renovation segments.
Installation Type:
Channel economics diverge sharply between permanent built-in specifications and flexible freestanding procurement, with margin structures reflecting installation permanence and replacement cycle length.
- Built-In:Flush-mounted units integrated into countertop surfaces dominate residential replacement cycles. Germany's premium appliance corridor exhibits decisive preference for these systems with bridge-fusion zone capabilities.
- Freestanding:Self-contained units with integrated bases serve rental housing and temporary commercial kitchens. French urban renovation programs channel subsidy flows toward these for existing building stock upgrades.
- Portable:Compact single or dual-zone units for supplemental cooking surface. Italian small-appliance retailers stock these for seasonal dwelling and outdoor kitchen extensions.
- Drop-In:Units recessed into custom countertop cutouts without surrounding frame. Commercial catering specifications in Spain favor these for cleaning accessibility and surface continuity.
Built-in installations command the majority of replacement expenditure; portable units gain share fastest in seasonal dwelling and outdoor kitchen segments.
Control Type:
Interface technology stratifies along digital capability curves, with touch and remote systems demanding software engineering competencies that reshape manufacturer competitive sets.
- Touch Control:Capacitive glass interfaces with slider or point-activation zones. Premium induction systems across Germany and France increasingly specify these as digital user experience becomes a specification differentiator.
- Knob Control:Rotary mechanical or electronic interfaces with tactile feedback. Gas hobs in Southern Europe retain these for familiarity and repair accessibility in aging installed bases.
- Slide Control:Linear touch strips enabling continuous power adjustment. Mid-market induction platforms adopt these for intuitive operation without full touchscreen complexity.
- Remote Control:Wireless or app-connected interfaces enabling preheating and monitoring. Connected home integrations in Dutch and Scandinavian residential developments specify these for smart kitchen ecosystems.
Touch control absorbs dominant share in new induction specifications; remote control interfaces climb fastest in connected home development pipelines.
End User:
Demand concentration patterns split between residential renovation volume and commercial durability requirements, with procurement channels and margin structures diverging accordingly.
- Residential:Home kitchen installations across owned and rental housing. German kitchen renovation cycles concentrate replacement demand here, with energy label research preceding specification decisions.
- Commercial:Restaurant, hotel, and institutional foodservice operations. CE marking compliance costs and electromagnetic compatibility certification filter supplier bases for this segment.
- Professional Chefs:High-performance specifications for culinary training and demonstration facilities. Bridge-fusion zone technology and precise thermal control dominate procurement criteria here.
- Catering Services:Mobile and event-based food preparation requiring portable or rapidly deployable equipment. French outdoor event infrastructure and Italian wedding venue suppliers drive demand concentration.
Residential end users absorb the bulk of unit volume; professional chef specifications are expanding most quickly in culinary training facility investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milan's appliance manufacturing corridor anchors European kitchen hob production, with German and Turkish industrial clusters supplying coil architectures and glass-ceramic assemblies across continental renovation channels.
Germany
Berlin's Federal Environment Agency administers rebate programs accelerating induction adoption in existing building stock. The EU Ecodesign Directive enforces ErP-mandated efficiency minimums that disqualify legacy resistive electric hobs from new installations. Bavaria's premium appliance corridor concentrates specification demand for bridge-fusion zone systems with energy-labeled credentials.
France
ADEME's national subsidy schemes redirect renovation spending toward efficient appliance replacement in metropolitan housing. The EU F-Gas Regulation restricts fluorinated greenhouse gases in manufacturing processes, forcing adhesive chemistry reformulation. Île-de-France's kitchen studio networks channel specification authority toward touch-control induction platforms with demonstrable efficiency credentials.
Italy
Emilia-Romagna's small-appliance retailers stock portable induction units for seasonal dwelling extensions. CE marking requirements enforce electromagnetic compatibility standards that raise compliance costs for non-European suppliers. Milan's design-driven procurement clusters specify zoneless cooking surfaces for high-end residential developments.
Spain
Existing gas pipeline infrastructure in Madrid and Barcelona lowers switching costs for atmospheric burner replacements. The EU Green Deal's building renovation wave redirects public subsidy flows between efficiency upgrades and appliance replacement cycles. Andalusia's rental housing markets concentrate freestanding unit demand for temporary commercial kitchen deployments.
United Kingdom
London's connected home development pipelines specify remote-control interfaces for smart kitchen ecosystem integration. GDPR compliance adds data governance costs to app-connected appliance platforms. Southeast England's renovation channels exhibit preference for built-in installation formats with energy disclosure transparency.
Europe Kitchen Hobs Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coil architecture sophistication and control interface digitalization. The vendor base organizes into three tiers: German-engineered premium specialists, modular platform architects spanning multiple price bands, and Turkish-scale value producers. Strategic moves concentrate on captive motor manufacturing and private-label supply contract consolidation.
Within the premium-engineered tier, Miele & Cie. KG and Electrolux AB occupy positions defined by domestic production scale and platform-sharing architectures. Arçelik A.Ş. exemplifies the manufacturing-scale archetype through Turkish production capacity serving continental retail contracts. Samsung Electronics and LG Electronics represent the electronics-integrated vector, leveraging display and semiconductor competencies for touch-control interface development. SMEG S.p.A. anchors Italian design-positioned specialization for aesthetic-driven specification channels.
| Leading Market Players |
|---|
| Miele & Cie. KG |
| Samsung Electronics |
| BSH Home Appliances |
| Gorenje Group |
| LG Electronics |
| Electrolux AB |
| Arçelik A.Ş. |
| SMEG S.p.A. |
| Whirlpool Corporation |
| Others |
Supply & Pricing Matrix
Bridge-fusion zone specifications from German kitchen renovators are forcing coil suppliers toward higher-complexity electromagnetic architectures that compress margin structures at the mid-tier while expanding premium pricing headroom.
Pricing Analysis
Energy-label performance outcomes anchor pricing power across European kitchen hobs, with A+++ certified induction systems commanding substantial premiums over resistive alternatives disqualified by ErP minimums. Price differentiation rests on coil architecture sophistication and control interface digitalization, with touch-control platforms separating premium specifications from knob-based gas alternatives. Cost compression in value-oriented electric hobs is intensifying because Turkish manufacturing scale feeds private-label retail contracts. Contractor channels exhibit highest price sensitivity due to project-bid transparency, while design-studio specifications show lowest sensitivity where efficiency credentials justify specification premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German appliance manufacturers, while distributor networks serve renovation contractors across France and Italy. Manufacturing concentrates in Germany for premium coil systems, Turkey for value-oriented electric hobs, and Italy for design-positioned gas assemblies. Raw material dependencies center on copper for electromagnetic coils, specialized glass-ceramic for cooking surfaces, and rare-earth elements for magnetic field generation. Single-source vulnerability in copper coil supply exposes margin structures to commodity price swings. Distribution runs through kitchen studio intermediaries in premium segments and big-box retail in value tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's kitchen hobs sector sits in a technology-transition phase, with electromagnetic induction systems displacing legacy gas infrastructure across renovation channels.
For Market Incumbents: Anchor defensive positioning through captive coil manufacturing and CE marking certification depth that raises barriers for non-European entrants facing electromagnetic compatibility testing timelines. Threats concentrate in Turkish-scale producers capturing private-label volume through continental retail contracts. Priority levers include backward integration into copper coil production and platform-sharing architectures that compress development costs across brand tiers. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer the most penetrable route into French and British markets where online energy-label research precedes specification decisions. White-space targets include connected-home remote-control interfaces for Dutch and Scandinavian residential developments, and portable induction units for Italian seasonal dwelling extensions. Go-to-market positioning should emphasize demonstrable efficiency credentials that displace traditional kitchen studio intermediaries. For Investors and Strategic Acquirers: The window for entry favors manufacturing-scale specialists with Turkish production footprints and established private-label retail relationships. Long-term viability hinges on coil architecture sophistication and software engineering capabilities for touch-control integration. Acquisition target archetypes include mid-tier electromagnetic specialists with underutilized capacity and design-positioned Italian brands with aesthetic-driven specification channels. The signal to watch is ADEME and Federal Environment Agency subsidy redirection between efficiency upgrades and appliance replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Manufacturing | Captive copper coil production insulates margin structures from commodity volatility and accelerates product launch cycles. |
| Platform Architecture Standardization | Shared chassis components between Electrolux brand tiers compress development costs and enable rapid specification response. |
| CE Marking Certification Investment | Electromagnetic compatibility testing depth raises barriers for non-European suppliers attempting continental market entry. |
| Direct-to-Consumer Channel Expansion | Online energy-label research in Germany and France displaces kitchen studio intermediaries and concentrates price transparency. |
| Touch Control Interface Development | Capacitive glass integration with sensor-based pan detection opens specification opportunities in high-end residential developments. |
Research Methodology
EU Ecodesign Directive filings, ErP compliance databases, and national rebate program records from ADEME and Germany's Federal Environment Agency formed the secondary backbone. Primary interviews with appliance procurement managers at continental retailers, kitchen studio specification consultants, and coil manufacturing plant engineers combined with secondary validation. Bottom-up and top-down triangulation cross-referenced shipment data from Turkish and German production clusters against renovation permit flows in France, Italy, and Spain.
Bottom-up modeling built from product-type, installation format, control interface, and end-user specifications across the projection horizon. Top-down validation referenced macroeconomic indicators for residential construction and kitchen renovation spending. CAGRs derived from segment-level growth rate aggregation weighted by base-year value shares. Industry-specific forecast inputs included copper price trajectory assumptions and subsidy program duration estimates from national environmental agencies.
The model holds under sustained ErP efficiency threshold enforcement and stable copper supply conditions; deviation in rebate program cancellation or electromagnetic compatibility certification timeline extension would shift replacement cycle velocity. Forecasts reflect documented assumptions regarding renovation spending patterns and regulatory compliance cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
North America Kitchen Furniture Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
Outdoor Kitchen Market