
 Built-In Cabinet Market | 2026-2036
Built-In Cabinet Market Size, Share, and Industry Trends Forecast 2026-2036
Built-In Cabinet Market Insights
North American cabinetry production is consolidating as larger manufacturers absorb regional woodshops and streamline distribution. MasterBrand Cabinets leverages extensive dealer networks to sustain market presence across the United States. IKEA anchors volume demand through flat-pack logistics and accessible price positioning. American Woodmark differentiates via contractor-direct relationships and semi-custom product breadth.
Built-in cabinets are factory-manufactured storage enclosures designed for permanent installation within architectural recesses, typically constructed from engineered wood substrates with melamine or thermofoil surfacing and measured to precise dimensional tolerances for seamless wall integration. Kitchen cabinets command the largest material throughput within product type segmentation, while bathroom cabinets generate disproportionate margin contribution due to moisture-resistant specification requirements. MDF and plywood substrates dominate material selection for residential applications, though solid wood persists in premium hospitality specifications where natural grain visibility carries design weight.
EPA formaldehyde emission standards under TSCA Title VI govern composite wood products used in cabinet construction, while California Air Resources Board (CARB) Phase 2 requirements extend compliance obligations for products sold into that state. OSHA workplace safety regulations influence finishing operations and dust collection investments at manufacturing facilities. Stakeholders must monitor evolving state-level low-VOC mandates and building code amendments that will determine which material formulations and production locations retain market access.
Market Dynamics
California's Title 24 building energy standards are compressing material choice sets across the United States, forcing manufacturers to retool substrate sourcing and finishing processes or lose access to the country's largest residential construction market.
Growth Catalysts
- Sun Belt Housing Expansion:Residential building developers in Texas, Florida, and Arizona are embedding built-in cabinets as standard specifications in new single-family and multifamily construction.
- EPA TSCA Title VI:Federal formaldehyde emission standards for composite wood products are harmonizing compliance requirements, reducing state-by-state regulatory fragmentation for national manufacturers.
- Renovation Cycle Compression:Homeowners are accelerating kitchen and bathroom remodel timelines, shortening replacement intervals for aging cabinet installations.
Market Restraints
- Engineered Wood Input Volatility:MDF and particleboard substrate costs fluctuate with resin and timber feedstock availability, compressing margin predictability for mid-tier producers.
- Regional Supply Concentration:Cabinet manufacturing clusters in the Southeast and Midwest create logistics cost penalties for Western US project bids.
- Flat-Pack Substitution:Ready-to-assemble alternatives from mass-market retailers capture price-sensitive renovation demand.
Strategic Opportunities
- Moisture-Resistant Bathroom Specification:Higher-margin vanity and storage cabinet categories remain underpenetrated relative to kitchen saturation.
- Low-VOC Formulation Mandates:CARB Phase 2 and emerging state-level air quality standards reward early movers with compliant coating and adhesive portfolios.
- Direct Contractor Channel Development:Bypassing traditional dealer networks captures margin and reduces project specification friction in production homebuilding.
Industry Challenges
- Skilled Installation Labor Scarcity:Precise dimensional tolerances for seamless wall integration require trained finish carpenters, constraining project velocity in tight labor markets.
- Multi-Jurisdiction Compliance Burden:OSHA workplace safety rules, EPA emissions monitoring, and state-level VOC mandates demand dedicated regulatory staff and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Built-In Cabinet Market |
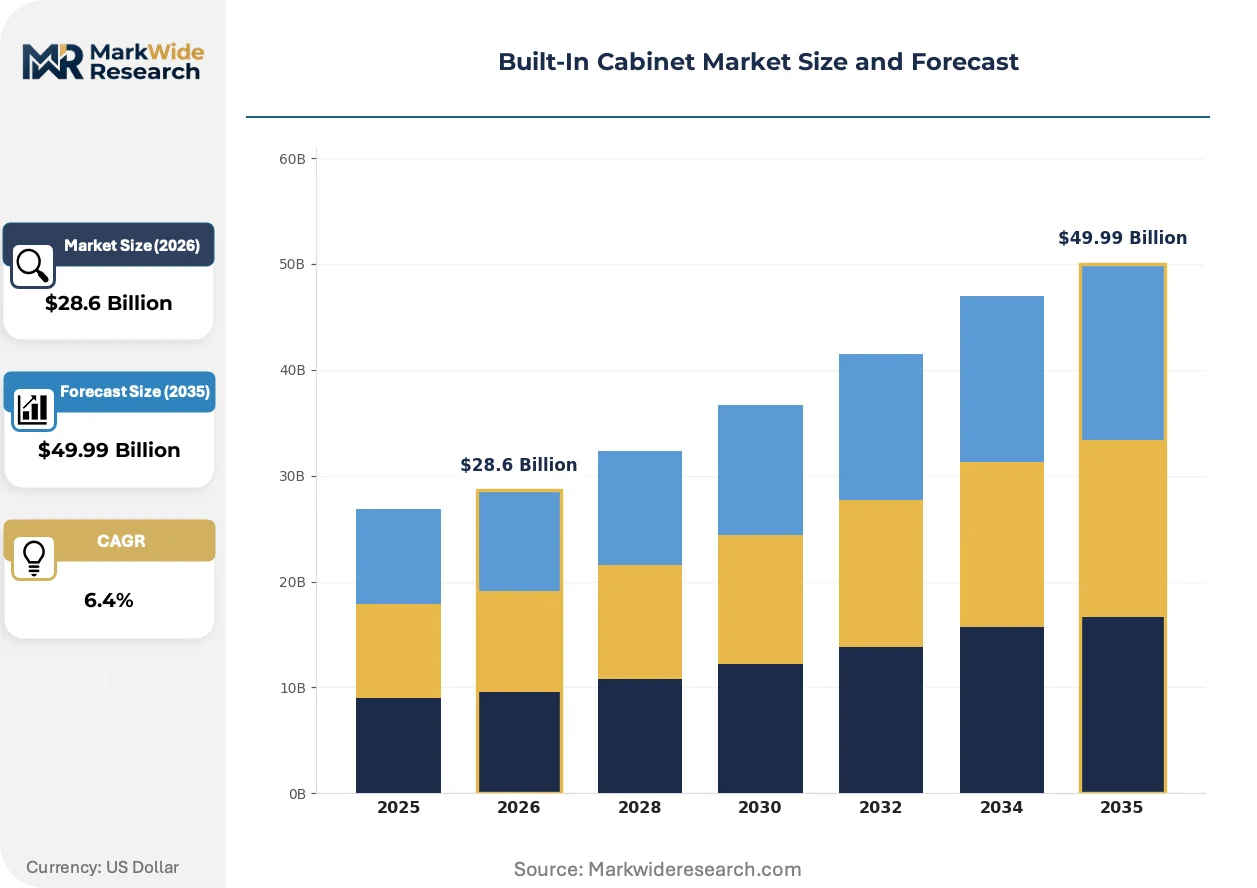
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kitchen Cabinets, Bathroom Cabinets, Wardrobes, Bookcases, Media Cabinets Material: Wood, MDF, Plywood, Metal, Laminates, Glass Application: Residential Buildings, Commercial Properties, Hospitality Spaces, Educational Facilities, Retail Outlets Distribution Channel: Direct Sales, Specialty Stores, Online Retailers, Home Improvement Chains, Interior Designers |
| Companies Covered | IKEA, MasterBrand Cabinets, American Woodmark, KraftMaid, Merillat, Wellborn Cabinet, Nobia, OPPOLIA, Fabuwood Cabinetry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Built-In Cabinet Market Trends and Innovations
Digital specification tools and automated production systems are compressing lead times from measurement to installation, while material science advances expand design flexibility without sacrificing regulatory compliance.
Thermoformed vinyl surfacing is integrating into residential cabinet specifications as a cost-effective alternative to painted wood and laminate finishes. Production homebuilders in the Sun Belt are specifying thermofoil for its moisture resistance and color consistency across large developments. This technology is integrating moisture protection directly into the substrate-facing layer, reducing field failure rates and warranty claims.
California Air Resources Board Phase 2 requirements are extending compliance verification obligations through the entire distribution chain. Manufacturers must maintain chain-of-custody documentation from panel supplier to finished product. Semi-custom producers serving the California market are investing in in-house emissions testing capacity to avoid third-party bottlenecks.
Builder procurement teams are consolidating cabinet specifications across regional divisions, reducing supplier counts in exchange for volume commitments and dedicated production slots. National production homebuilders are negotiating direct relationships with manufacturers, displacing traditional distributor intermediaries. This concentration is most visible in Texas and Florida markets where single-family permit volumes support dedicated production lines.
Built-In Cabinet Market Segmentation
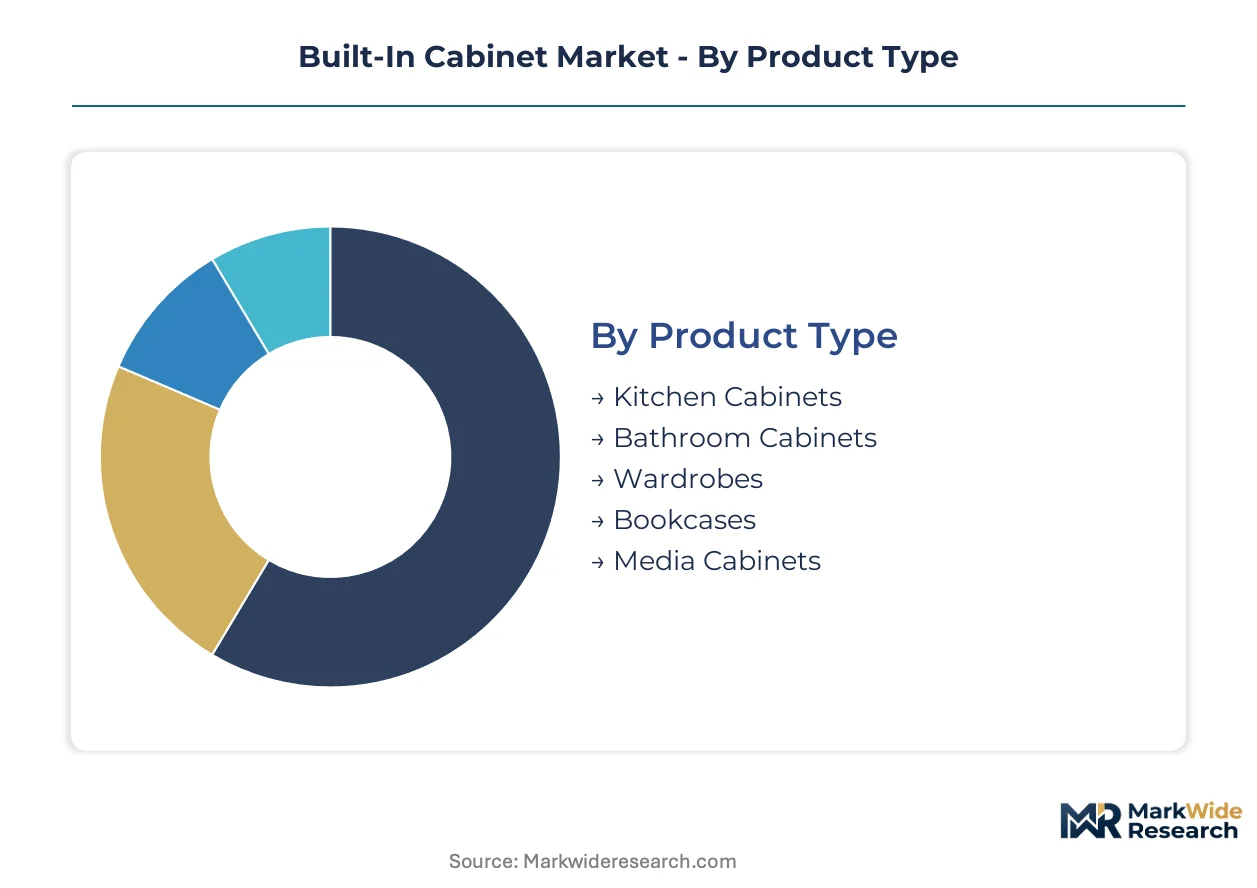
Built-in cabinet segmentation reveals how regulatory compliance burdens, material cost structures, and channel economics concentrate profitability across distinct product configurations. Each dimension carries specific certification requirements and margin profiles that determine competitive positioning.
Product Type:
Kitchen cabinets carry EPA TSCA Title VI certification obligations for formaldehyde emissions, while bathroom specifications demand moisture-resistant validation under California CARB Phase 2 standards.
- Kitchen Cabinets:Engineered wood enclosures with melamine or thermofoil surfacing dominate material throughput in residential construction. Sun Belt developers in Texas and Florida embed these as standard specifications in new single-family housing, driving volume concentration.
- Bathroom Cabinets:Moisture-resistant substrate formulations with vinyl-wrapped or sealed edges command disproportionate margin contribution. California Title 24 energy standards push manufacturers toward low-emission adhesives and finishes in this category.
- Wardrobes:Vertical storage systems with sliding door hardware and internal organization components serve bedroom and closet applications.
- Bookcases:Open-shelving and enclosed storage units for residential and commercial interior fit-outs.
- Media Cabinets:Ventilated enclosures with cable management and component cooling for entertainment equipment housing.
Kitchen cabinets sit at the top of the volume ranking, with bathroom cabinets climbing the fastest.
Material:
Raw material selection determines compliance pathways and cost tier positioning across residential, commercial, and hospitality end-uses.
- MDF:Medium-density fiberboard substrates with thermofoil or painted finishes offer cost-effective dimensional stability. Production homebuilders specify MDF for large developments where color consistency and moisture protection reduce field failures.
- Plywood:Cross-laminated veneer construction provides structural integrity for load-bearing cabinet applications. Southeast and Midwest manufacturing clusters source plywood regionally, creating logistics cost penalties for Western US project bids.
- Wood:Solid hardwood and veneer-over-substrate constructions persist in premium hospitality specifications where natural grain visibility carries design weight.
- Metal:Steel and aluminum framing systems for industrial and high-traffic commercial environments.
- Laminates:High-pressure and low-pressure decorative surfaces bonded to engineered cores for durability and cleanability.
- Glass:Tempered and laminated glazing for display cabinets and visual openness in retail and residential applications.
MDF captures the highest shipment volumes, with plywood expanding most quickly in moisture-resistant bathroom specifications.
Application:
End-use concentration shapes demand cycles, with residential construction driving material throughput and hospitality commanding specification premiums.
- Residential Buildings:Single-family and multifamily new construction plus renovation activity constitutes the dominant demand pool. Sun Belt states experiencing rapid housing growth concentrate order volume for kitchen and bathroom installations.
- Commercial Properties:Office fit-outs and tenant improvements generate project-based demand with compressed lead time requirements.
- Hospitality Spaces:Hotels and extended-stay properties specify durable, replaceable cabinet systems with standardized dimensions for maintenance efficiency.
- Educational Facilities:K-12 and higher education construction programs with public procurement cycles and prevailing wage requirements.
- Retail Outlets:Fixture and display cabinet systems for merchandising environments with high visual impact specifications.
Residential buildings anchor demand volume, with hospitality spaces gaining share fastest on renovation cycle compression.
Distribution Channel:
Channel structure determines margin capture and specification control, with direct contractor relationships displacing traditional dealer intermediaries in production homebuilding.
- Direct Sales:Manufacturer-to-builder relationships bypass distributor markups and secure dedicated production slots. National production homebuilders negotiate volume commitments in exchange for specification consolidation.
- Specialty Stores:Independent dealers serve renovation and custom home markets with design consultation and installation coordination.
- Online Retailers:Flat-pack logistics and accessible price positioning capture price-sensitive renovation demand.
- Home Improvement Chains:Big-box retail with in-stock inventory and contractor loyalty programs for repair and replacement.
- Interior Designers:Specification influence in high-end residential and commercial projects with custom finish requirements.
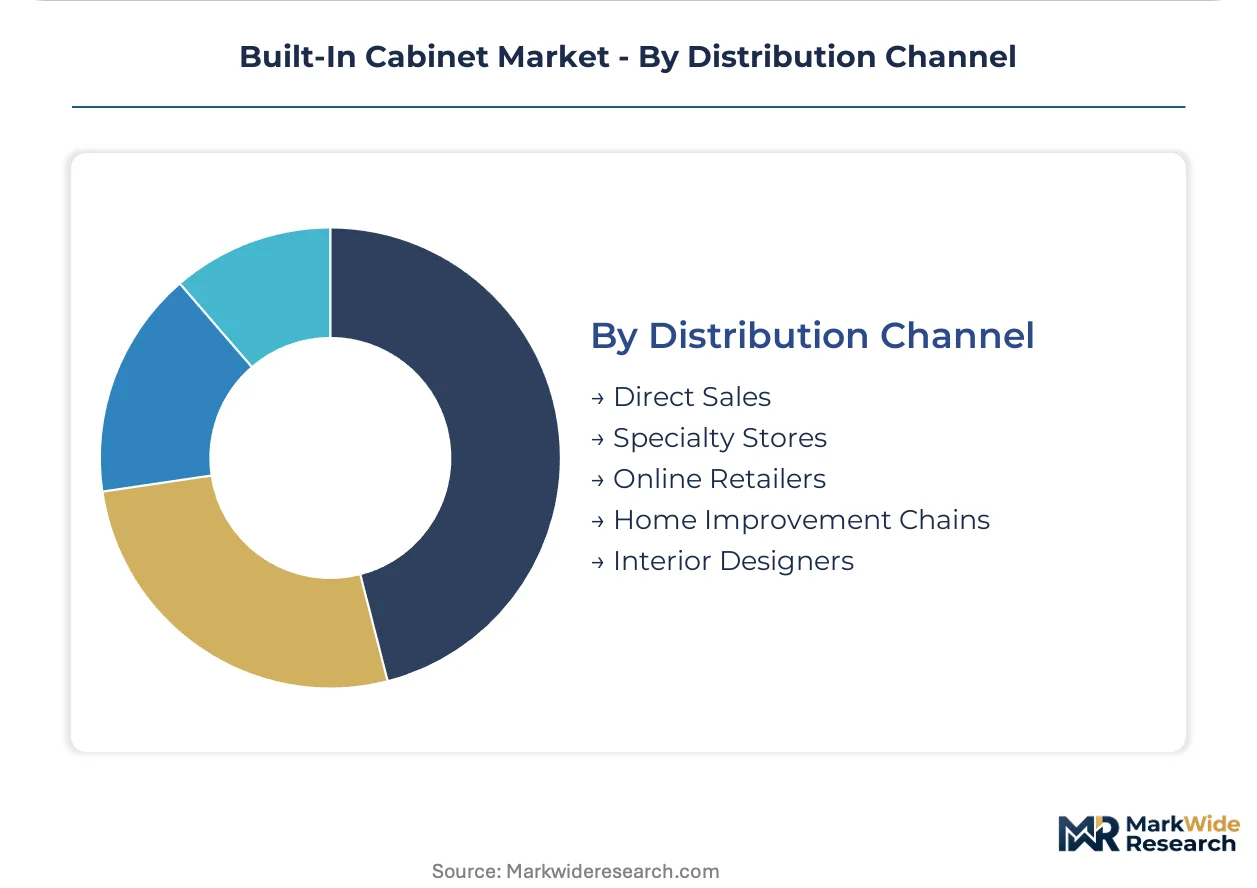
Direct sales holds the largest revenue share, with online retailers climbing fastest on flat-pack substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates substantially higher built-in cabinet throughput than Canada, though both markets face tightening low-emission material standards that reshape supplier qualification requirements.
United States
Texas and Florida single-family developers embed thermofoil kitchen cabinets as standard specifications, driving volume concentration in Sun Belt metros. EPA TSCA Title VI formaldehyde standards govern composite wood products nationwide, harmonizing compliance burdens for interstate manufacturers. Southeast manufacturing clusters in Georgia and North Carolina absorb regional woodshops to streamline distribution toward Western project bids.
Canada
Ontario and British Columbia residential construction sustains steady demand for moisture-resistant bathroom cabinet specifications. Health Canada administers chemical substance regulations that align with California CARB Phase 2 emission thresholds for cross-border suppliers. Quebec manufacturing facilities leverage provincial forestry resources to serve both domestic and US Northeast renovation markets.
Germany
Renovation activity in Berlin and Munich compresses kitchen replacement cycles for engineered wood cabinetry. ECHA REACH regulations restrict hazardous substance use in adhesives and surface coatings, forcing substrate sourcing adjustments. North Rhine-Westphalia industrial zones host automated production systems that export flat-pack configurations throughout Europe.
China
Urban residential towers in Shanghai and Shenzhen specify standardized built-in storage for space optimization. MIIT and GB standards govern formaldehyde emission limits for interior wood products, with stricter enforcement in coastal provinces. Pearl River Delta manufacturing bases supply both domestic developers and export markets through integrated logistics corridors.
India
Maharashtra and Karnataka apartment construction accelerates demand for cost-effective MDF wardrobe systems. BIS certification requirements for wood-based panel products create compliance entry barriers for unorganized suppliers. Gujarat industrial corridors attract modular furniture investments targeting middle-income residential segments.
Built-In Cabinet Market Competitive Landscape
Southeast US producers anchor one tier; European flat-pack specialists hold another through distinct channel economics. The vendor base concentrates around three strategic archetypes: mass-market retailers with logistics networks, semi-custom fabricators serving production homebuilders, and premium hospitality specialists. Consolidation momentum favors acquisition of regional woodshops by national platforms. Direct contractor relationships displace traditional dealer intermediaries as the dominant competitive move.
Among mass-market retailers, IKEA exemplifies flat-pack logistics efficiency and accessible price positioning. MasterBrand Cabinets occupies a position within the semi-custom tier, leveraging extensive dealer networks across the United States. American Woodmark represents the contractor-direct archetype, capturing margin through production homebuilder relationships rather than distributor markups.
| Leading Market Players |
|---|
| IKEA |
| MasterBrand Cabinets |
| American Woodmark |
| KraftMaid |
| Merillat |
| Wellborn Cabinet |
| Nobia |
| OPPOLIA |
| Fabuwood Cabinetry |
| Others |
Pricing and Supply Chain Analysis
California's Title 24 building energy standards gate both qualified supply and premium-tier pricing access, restricting market participation to manufacturers with verified low-emission substrate portfolios and compliant finishing processes. Manufacturers lacking CARB Phase 2 certification face automatic exclusion from the nation's largest residential construction market, while compliant producers command pricing premiums through scarcity-driven positioning.
Pricing Analysis
Capacity additions in the Southeast United States are reshaping price floors for engineered wood substrates, compressing margins for mid-tier producers dependent on spot resin purchases. Three-tier pricing structure across premium, standard, and economy levels separates solid wood hospitality specifications from thermofoil residential volumes and flat-pack import alternatives. Price differentiation rests on certification grade and volume scale, with production homebuilders extracting quantity discounts through direct contracting. Cost compression in the economy tier intensifies because IKEA's flat-pack logistics erode regional manufacturer price positioning. Renovation contractors show highest price sensitivity, while hospitality procurement teams prioritize durability specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Southeast US panel suppliers, where Georgia and North Carolina manufacturing clusters feed national distribution networks. Raw material flows draw from Canadian timber feedstocks, Chinese melamine surfacing imports, and domestic resin production. Supply chain risk centers on tariff exposure for thermofoil vinyl films sourced from East Asian chemical processors. Distribution runs through consolidated homebuilder procurement teams, bypassing traditional dealer intermediaries in volume construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The built-in cabinet market functions as a stable compounder, with Sun Belt housing expansion driving steady replacement and new construction demand through demographic migration patterns.
For Market Incumbents: Deepen backward integration into engineered wood panel production to insulate margin from resin price volatility and secure TSCA Title VI certification continuity. Acquire regional woodshops in Texas and Florida to consolidate distribution reach and defend against flat-pack substitution. Prioritize in-house emissions testing capacity to eliminate third-party bottlenecks under California CARB Phase 2 verification requirements.
For New Entrants and Emerging Players: Capture moisture-resistant bathroom cabinet specifications, where kitchen saturation leaves white-space opportunity for specialized producers. Target direct contractor channel development in Arizona and Nevada production homebuilding markets, where dealer network displacement creates entry pathways. Lead with low-VOC formulation credentials to differentiate against legacy manufacturers with compliance retrofit burdens.
For Investors and Strategic Acquirers: Valuations sit cheapest among semi-custom fabricators lacking California market access, creating acquisition opportunity for compliance-capable platforms. Long-term viability favors manufacturers with integrated substrate supply and direct builder relationships. Watch Sun Belt permit volatility as the primary inflection signal for capacity utilization and pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-VOC Formulation Certification | CARB Phase 2 compliance unlocks California market access and commands specification premiums. |
| Direct Contractor Channel Development | Bypassing dealer networks captures margin in Texas and Florida production homebuilding. |
| Backward Integration into Panel Production | In-house substrate supply insulates margins from resin cost volatility and EPA certification risk. |
| Moisture-Resistant Product Line Expansion | Bathroom specifications generate disproportionate margin contribution versus saturated kitchen categories. |
| Automated Production System Investment | Digital specification tools compress lead times from measurement to installation for builder clients. |
Research Methodology
Coverage spans the United States, Canada, Germany, China, and India, with primary inputs from each geography informing demand and supply characterizations. The analysis combines structured interviews with production homebuilder procurement directors, cabinet manufacturer operations executives, regional woodshop owners, and distributor account managers with secondary validation from EPA regulatory filings, CARB compliance databases, customs trade records, and building permit aggregators. Bottom-up shipment estimates by product type and material triangulate against top-down construction spending allocations.
Rate-of-change decomposition separates volume growth from price movement across the projection horizon, with analytical frameworks modeling product type, material substrate, application end-use, and distribution channel dimensions. CAGRs derive from trend extrapolation of housing permit data, renovation cycle compression indicators, and regulatory phase-in schedules. Industry-specific forecast inputs include Sun Belt migration patterns, formaldehyde emission standard enforcement intensity, and skilled installation labor availability indices.
Regulatory enforcement delays, engineered wood input cost spikes, and construction labor strikes are the dominant revision risks that could compress or extend forecast trajectories. Forecasts reflect documented assumptions about compliance timeline adherence and housing market cyclicality. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
Restaurant Chairs Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market