
 Outdoor Kitchen Market | 2026-2036
Outdoor Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Kitchen Market Intelligence
A fragmentation of the buyer base to include more contractors and developers alongside traditional homeowners is repositioning competitive dynamics. Weber leverages its extensive distribution network and brand recognition in the broader grilling market. In contrast, Kalamazoo Outdoor Gourmet specializes in the ultra-high-end custom segment, offering bespoke solutions. Bull Outdoor Products competes by providing a wide array of modular components that allow for semi-custom configurations.
An outdoor kitchen is an external food preparation and cooking area, featuring weather-resistant cabinetry and appliances. Components often utilize 304-grade stainless steel for corrosion resistance and require utility hookups for gas and electricity. While custom installations using stone and tile command high margins, the modular installation segment is expanding rapidly due to its flexibility. Integrated product types like sinks and countertops are increasingly standard as homeowners seek complete outdoor culinary spaces.
Product safety is governed by standards from bodies like the CSA Group in North America and the CE marking framework in Europe. Local municipal building codes in countries like the United States and Australia also dictate requirements for permanent structures, plumbing, and electrical work. Future success for manufacturers depends on creating product lines that can be adapted to these varied international and local regulatory demands.
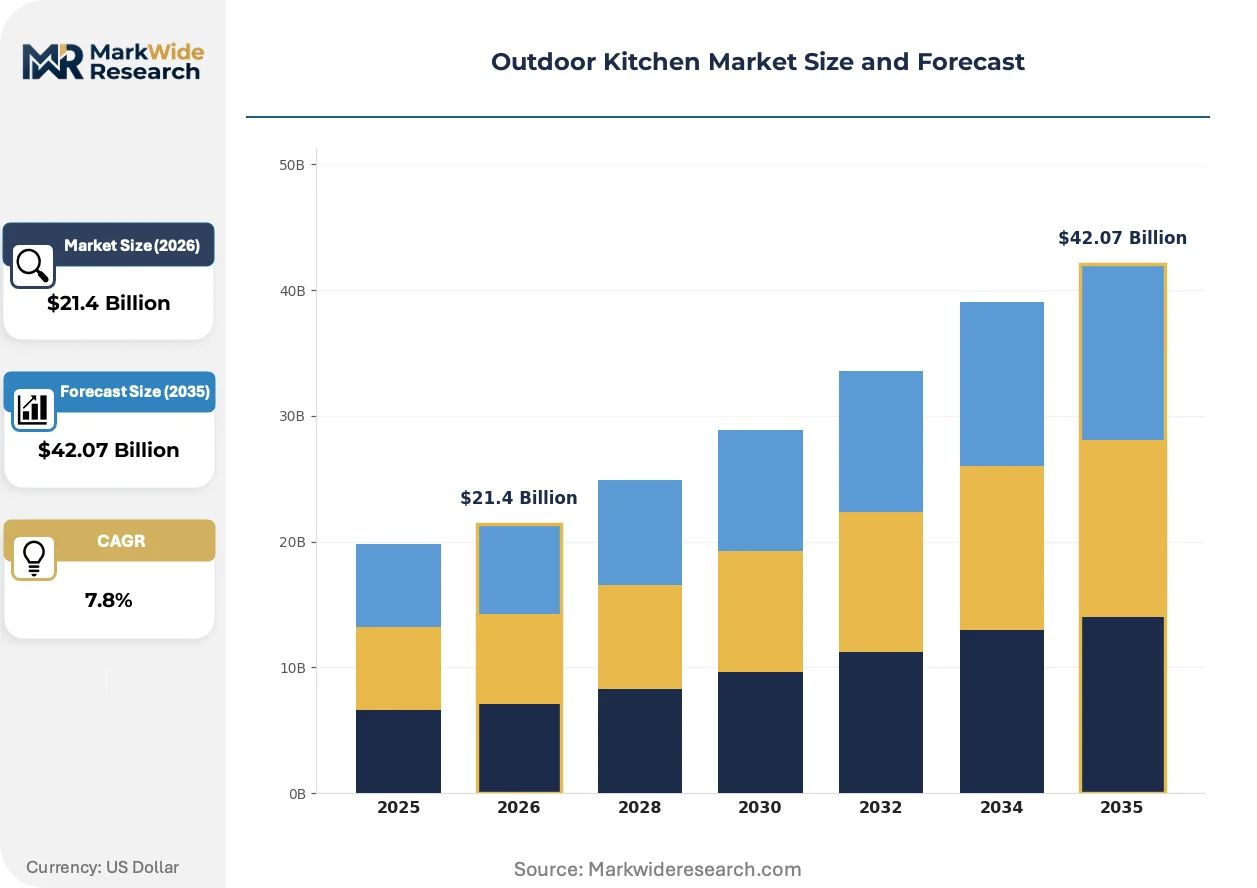
Market Dynamics
The market's central dynamic is the transition from standalone luxury purchases to integrated architectural elements within new construction and major renovations. This shift is driven by the entry of developers and contractors as a primary buyer segment, altering product design and distribution channels.
Growth Catalysts
- Property Value Enhancement:Homeowners in affluent US and Australian suburbs invest in outdoor kitchens to increase property value, driving demand for complete installations.
- Modular System Accessibility:Modular components lower installation complexity and cost, expanding the market beyond custom builds and broadening consumer access.
- Smart Technology Integration:IoT-enabled grills and lighting systems meet consumer demand for convenience, creating a distinct technology-driven product category.
Market Restraints
- High Capital Outlay:The cost of durable materials like 304-grade stainless steel and specialized appliances is a significant investment barrier for many households.
- Restrictive Building Codes:Local municipal codes in the US and Australia governing utilities and permanent structures add complexity and cost to installations.
- Skilled Labor Scarcity:Custom projects require specialized tradespeople like masons and electricians, whose scarcity constrains project timelines and budgets.
Strategic Opportunities
- European Market Expansion:Affluent urban markets in Western Europe represent a significant, underdeveloped opportunity for both modular and custom outdoor kitchen solutions.
- Commercial Sector Development:Targeting developers of multi-family residences and hotels with specific product lines opens a new B2B channel for volume sales.
- Advanced System Integration:Integrating with home automation platforms offers seamless control of outdoor components, providing a differentiated user experience.
Industry Challenges
- Regulatory Fragmentation:Designing products to comply with disparate international standards like CSA Group in North America and CE marking in Europe increases R&D and certification costs.
- Supply Chain Volatility:Price fluctuations and availability of critical materials, particularly corrosion-resistant 304-grade stainless steel, pose a risk to production costs and manufacturing schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Kitchen Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $42.07 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grills, Cabinets, Sinks, Countertops Material: Stainless Steel, Wood, Stone, Tile Installation: Built-in, Modular, Portable, Custom End User: Homeowners, Contractors, Restaurateurs, Developers |
| Companies Covered | Bull Outdoor Products, Alfresco Grills, Weber, DCS by Fisher & Paykel, Coyote Outdoor Living, Napoleon Products, Lynx Grills, Kalamazoo Outdoor Gourmet, Middleby Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Kitchen Market Strategic Shifts & Innovations
The concept of the outdoor kitchen is evolving from a simple barbecue area into a fully functional, weather-resistant extension of the home's primary living space. This transformation is driven by a convergence of material science, digital technology, and changing consumer expectations for outdoor entertainment.
Smart appliance connectivity provides remote monitoring and control for outdoor kitchen components like grills and refrigerators. Initially adopted by the ultra-high-end custom segment, this functionality is now in high demand among mainstream premium buyers. Consequently, this integrated technology is expanding into modular and semi-custom product lines, becoming a key competitive differentiator.
Europe's CE marking framework imposes strict safety and environmental standards on outdoor appliances sold within the EU. This regulation forces manufacturers to engineer products, particularly gas and electrical units, to meet specific compliance criteria for market access. The most affected segments are grills and integrated refrigeration, often requiring region-specific designs.
A notable behavioral shift is the inclusion of contractors and property developers as a primary buyer category alongside individual homeowners. This disrupts traditional retail channels, favoring a B2B sales model focused on project specifications and volume pricing for new builds. This pattern is most visible in large-scale residential developments across the United States.
Outdoor Kitchen Market Segmentation
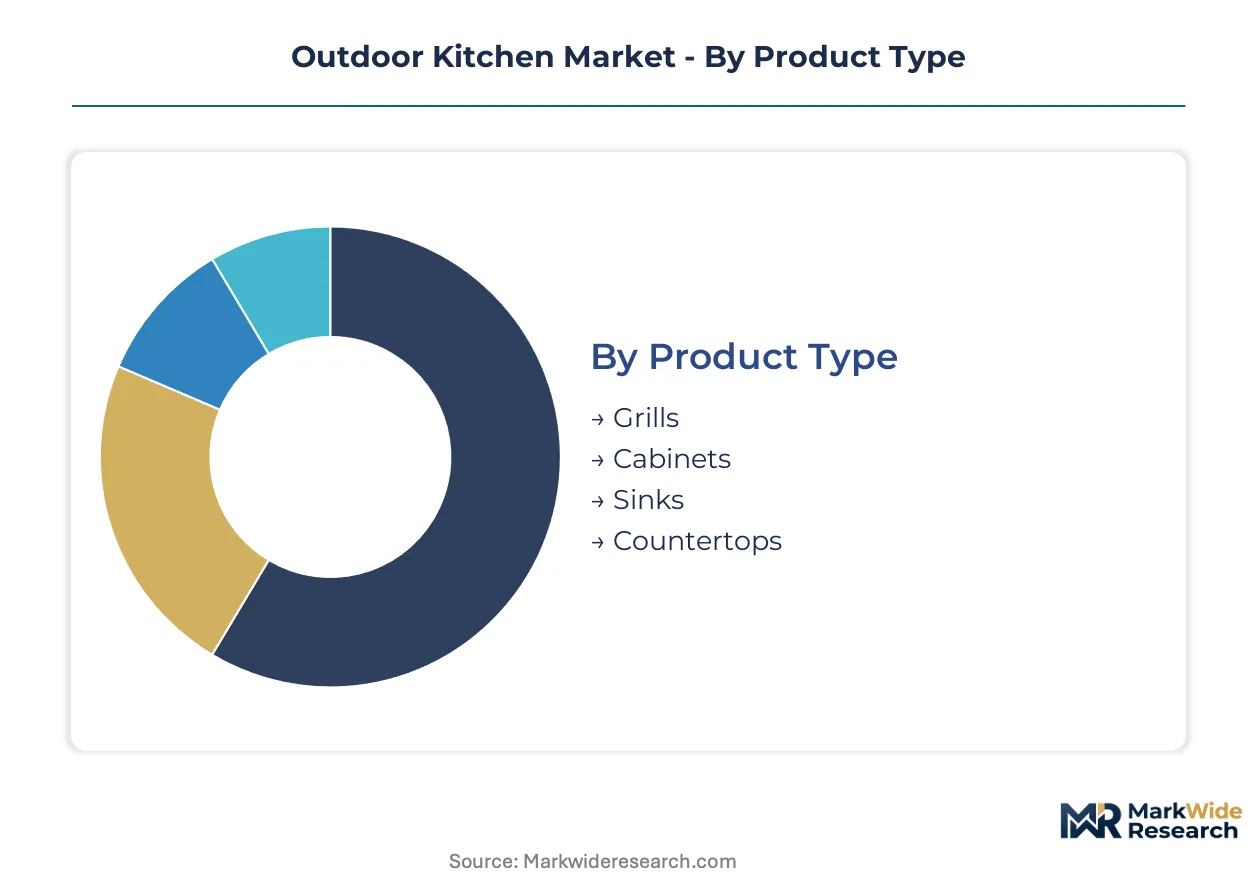
Understanding the Outdoor Kitchen Market's segmentation provides clarity on diverse consumer needs and evolving procurement channels. This granular view reveals specific product preferences, material choices, and installation methods that influence purchasing decisions across different end-user groups. Manufacturers align product development and distribution strategies with these distinct segments for targeted market penetration.
Product Type:
Buyer decisions often hinge on the primary function and desired level of integration within the outdoor culinary space.
- Grills:IoT-enabled grills offer remote monitoring and precise temperature control for enhanced cooking experiences. Affluent homeowners in the United States drive demand for these smart appliances, prioritizing convenience and technological sophistication.
- Cabinets:Weather-resistant cabinetry, frequently constructed from 304-grade stainless steel, provides durable storage and aesthetic appeal. New residential developments by property developers increasingly integrate modular cabinet systems, enhancing outdoor living functionality.
- Sinks:Integrated sinks provide essential water access and waste disposal capabilities for comprehensive outdoor food preparation.
- Countertops:Durable countertops, available in materials like stone or tile, create robust surfaces for food preparation and serving areas.
Grills leads on scale; Cabinets leads on momentum.
Material:
The choice of material reflects specific application requirements and long-term durability expectations for outdoor environments.
- Stainless Steel:304-grade stainless steel offers superior corrosion resistance and hygiene for appliances and cabinetry. Coastal lifestyle communities in Australia show strong demand for stainless steel products, valuing their resilience against harsh weather.
- Wood:Wood materials provide a natural aesthetic and warmth, often selected for specific design schemes and complementary outdoor décor.
- Stone:Natural stone offers exceptional durability, luxurious appearance, and high thermal mass for custom countertops and structural elements. Ultra-high-end custom segments in affluent suburbs prioritize stone for its premium feel and bespoke integration.
- Tile:Tile provides a versatile and customizable surface option for countertops, backsplashes, and decorative accents in outdoor kitchens.
Material selections demonstrate a clear focus on specific performance attributes and aesthetic preferences.
Installation:
Cost tiers significantly influence the selection of installation types, balancing upfront investment with flexibility and permanence.
- Built-in:Built-in installations permanently integrate appliances and components into custom-designed structures for a seamless appearance.
- Modular:Modular components offer flexible configurations and simplified assembly, reducing overall installation complexity and time. Developers and contractors increasingly adopt modular systems for new construction projects, valuing their scalability and streamlined deployment.
- Portable:Portable units provide temporary and flexible outdoor cooking solutions without requiring permanent utility connections or structural modifications.
- Custom:Custom installations involve bespoke design and construction, often using premium materials like stone and tile, tailored to specific architectural visions. Affluent homeowners in the United States seek custom solutions for unique outdoor spaces and high-end finishes.
Different installation types reflect varying market penetration strategies and consumer budget ranges.
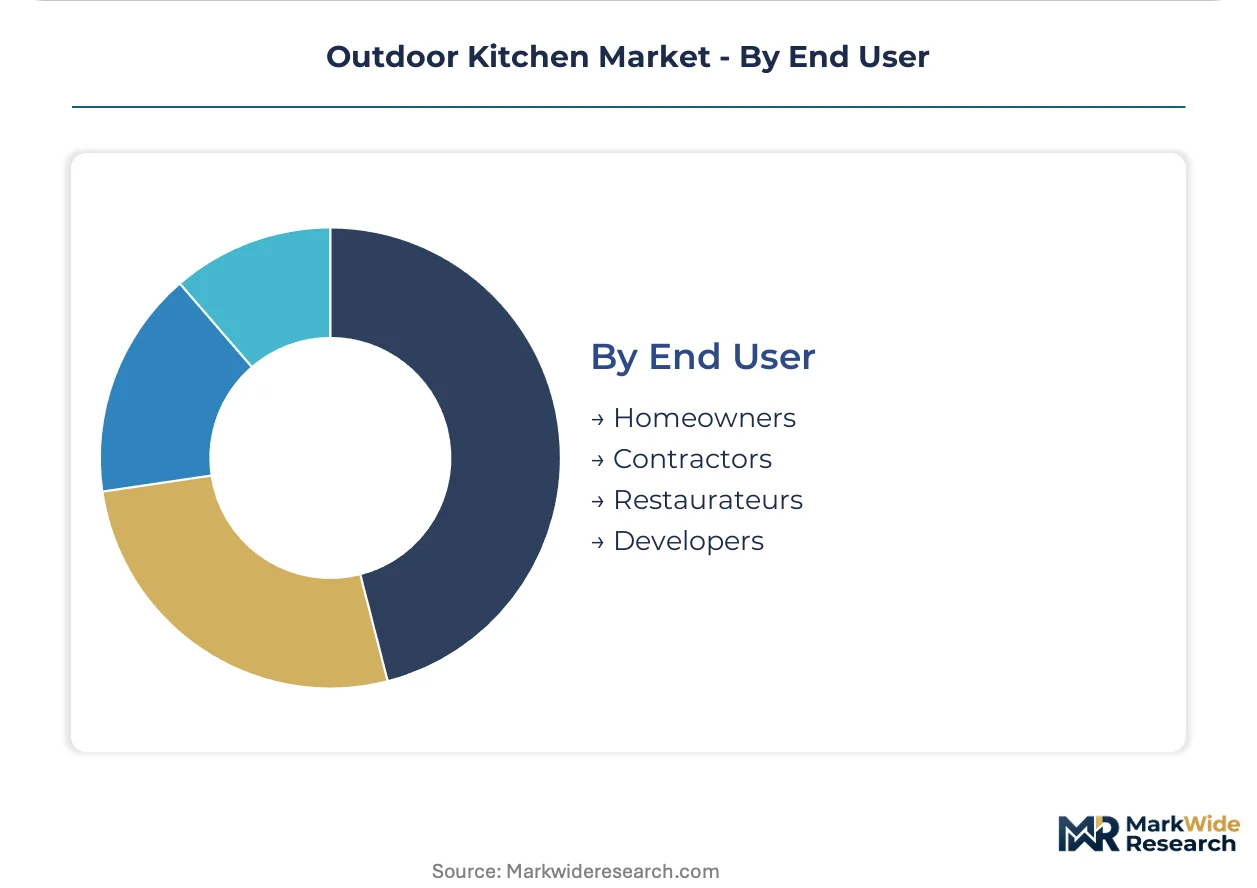
End User:
Distinct customer types drive demand based on their specific procurement models and project objectives.
- Homeowners:Individual homeowners invest in outdoor kitchens to enhance property value, expand living space, and improve lifestyle amenities. Affluent US and Australian suburbs represent a primary demand base for complete, high-value outdoor kitchen installations.
- Contractors:Contractors procure outdoor kitchen components for integration into broader residential renovation or landscaping projects.
- Restaurateurs:Restaurateurs occasionally invest in outdoor kitchen solutions for commercial dining spaces, catering to al fresco dining trends.
- Developers:Property developers integrate outdoor kitchens into new residential constructions, including single-family homes and multi-family units. Large-scale residential developments in the United States drive significant volume sales through established B2B channels.
End-user segments demonstrate distinct purchasing behaviors and project scales across the market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled workforce in construction and design underpins the robust outdoor kitchen market in the United States. Homeowners in affluent suburbs actively invest in premium outdoor living spaces. This demand drives innovation in integrated architectural elements for new construction and major renovations.
United States
Affluent US homeowners prioritize outdoor kitchens to enhance property value and integrate smart home technology. Local municipal building codes dictate requirements for permanent structures and utility work. New residential developments in Florida and California are increasingly incorporating these features into architectural designs.
Australia
Coastal lifestyle communities in Australia exhibit strong demand for durable outdoor kitchen solutions. Australian municipal building codes govern permanent outdoor structures and utility connections. In Sydney and Perth, property developers incorporate complete outdoor culinary spaces into new luxury homes.
Germany
European market expansion opportunities for outdoor kitchens are evident in Germany's affluent urban areas. The CE marking framework imposes strict safety and environmental standards on outdoor appliances. In Munich and Berlin, premium homeowners seek bespoke outdoor kitchen designs adapted to local architectural styles.
France
France's luxury segment shows a growing appetite for custom outdoor kitchen installations. Compliance with the CE marking framework is essential for manufacturers targeting this market. Affluent regions like the French Riviera are seeing increased investment in elaborate outdoor culinary and entertainment zones.
Canada
Canadian homeowners are increasingly investing in outdoor kitchens to extend their living spaces. Product safety is governed by standards from bodies like the CSA Group in North America. In Toronto and Vancouver, modular outdoor kitchen systems gain traction due to flexibility and ease of installation.
Outdoor Kitchen Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the outdoor kitchen market. This dynamic creates a tiered structure where global appliance manufacturers coexist with niche, high-end custom builders. Strategic archetypes include mass-market modular providers, ultra-high-end custom solution providers, and technology integrators for smart outdoor appliances. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach and integrate new technologies.
Within the ultra-high-end custom segment, Kalamazoo Outdoor Gourmet exemplifies bespoke solutions for discerning clients, focusing on specialized craftsmanship. Bull Outdoor Products occupies a position as a provider of wide-array modular components, enabling semi-custom configurations for a broader market. Weber, a well-established brand with extensive distribution, represents a strong presence in the broader grilling market, adapting its offerings to outdoor kitchen integration. These companies collectively illustrate the market's segmentation across luxury, modular, and mass-market premium offerings.
| Leading Market Players |
|---|
| Bull Outdoor Products |
| Alfresco Grills |
| Weber |
| DCS by Fisher & Paykel |
| Coyote Outdoor Living |
| Napoleon Products |
| Lynx Grills |
| Kalamazoo Outdoor Gourmet |
| Middleby Corporation |
| Others |
Cost & Logistics Intelligence
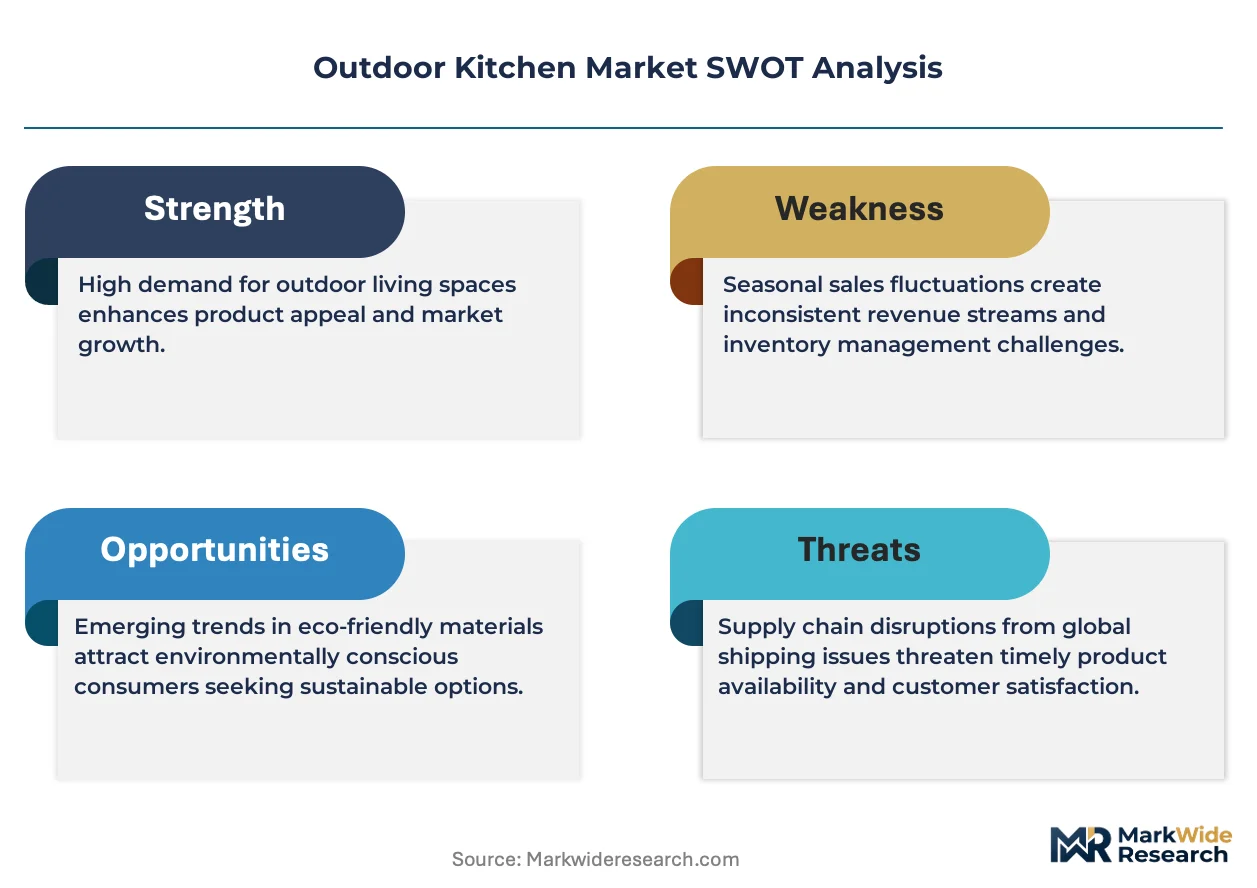
Homeowner demand for integrated smart technology in outdoor kitchens forces manufacturers to invest in complex components, driving up pricing for advanced product categories. Developers' preference for modular systems also reshapes supply chain efficiency, influencing cost structures.
Pricing Analysis
Capacity additions in North America are reshaping price floors for modular outdoor kitchen components. The market utilizes a hybrid pricing model, combining project-based quotations for custom installations with per-unit transactional pricing for modular systems. Price differentiation stems from customization levels, the specific grade of 304-stainless steel, and integrated smart technology features. Pricing pressure trends upward due to material costs and specialized labor scarcity. Affluent homeowners prioritize bespoke design and premium materials, exhibiting lower price sensitivity than property developers seeking volume discounts.
Supply Chain Analysis
Single-source vulnerability sits with specialized component manufacturers in Europe for high-end grills. The supply chain draws heavily on 304-grade stainless steel from Asian markets and IoT chipsets from global electronics hubs. Commodity price volatility for stainless steel poses a structural risk, impacting production costs and schedules. Distribution runs through a dual model, leveraging B2B direct sales for developers and specialized distributors for homeowners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The outdoor kitchen market represents a late-cycle quality story, driven by a pronounced demand-shift towards premium specifications and integrated architectural elements. Homeowners increasingly seek complete, high-value outdoor culinary spaces for property enhancement.
For Market Incumbents:Cement existing B2B relationships with property developers and contractors to secure volume sales amidst competitive dynamics. Invest in advanced smart home integration R&D to counter emerging technology-driven entrants, leveraging existing brand recognition. Focus certification investment on CE marking for European market access, mitigating regulatory fragmentation as a threat. Expanding modular product lines helps address developer demand, while optimizing 304-grade stainless steel procurement mitigates supply chain volatility.
For New Entrants and Emerging Players:Enter via strategic partnerships with home automation platforms to offer seamless outdoor kitchen control, targeting technology-forward homeowners. Focus on European affluent urban markets, particularly Germany and France, which show underdeveloped potential for modular solutions. The most penetrable segment involves modular systems featuring advanced smart technology integration, balancing cost and convenience. Provide bespoke design services for commercial sector developers, capturing multi-family residence and hotel project opportunities.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized technology integrators and modular component manufacturers poised for sustained growth in outdoor living. The long-term viability of the market remains strong, driven by homeowners' desire to enhance property value and lifestyle amenities. Target acquisition profiles include companies with robust B2B channels serving developers and strong intellectual property in smart home connectivity. The signal to watch is the adoption rate of IoT-enabled outdoor appliances in large-scale residential developments across the United States.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Modular Product Lines | Addresses developer demand for flexible, scalable outdoor kitchen solutions. |
| Invest in IoT Integration R&D | Enhances user experience and meets consumer demand for convenience in outdoor spaces. |
| Target European Market Expansion | Captures underdeveloped demand in affluent urban areas of Germany and France. |
| Secure 304-Grade Stainless Steel Supply | Mitigates production cost volatility and ensures material availability for manufacturers. |
| Strengthen Developer Partnerships | Establishes reliable volume sales channels for new construction projects in the United States. |
Research Approach
Bottom-up homeowner and developer end-use modeling reconciled against top-down outdoor kitchen component supply tracking forms the analytical core. This approach integrates primary interviews with property developers, outdoor kitchen manufacturers, specialized contractors, and appliance engineers. Secondary validation utilizes building permit data from the United States and Australia, industry association reports, and material trade statistics. Triangulation of these data sources ensures robust market sizing and segmentation.
An input-output matrix defines the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions modeled include product type, material, installation method, end-user category, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical data extrapolation and projected demand drivers like housing starts in the United States and Australia. Smart home technology penetration rates also serve as a key forecast input.
Inputs from manufacturer financial reports and building code databases were available through the study window; gaps in granular regional material pricing data introduce uncertainty bands. Forecasts reflect assumptions regarding economic stability and consumer discretionary spending. Supply chain volatility for 304-grade stainless steel is a key risk factor, meaning outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Kitchen Hand Tools Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
UAE Kitchen Hoods Market
Kitchen and Dining
United States Modular Kitchen Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Europe Kitchen Furniture Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
Rainbow Flatware Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Kitchen Countertop Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
Interactive Tables Market