
 Kitchen Faucets Market | 2026-2036
Kitchen Faucets Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Faucets Market Analysis
WaterSense certification is redrawing competitive boundaries in the North American kitchen faucet trade. Delta Faucet Company leverages its captive brass foundry network to control alloy quality from ingot to finished cartridge. Kohler Co. anchors its position through vertical integration into ceramic disc valve manufacturing, a capability few rivals replicate at comparable scale. Hansgrohe SE differentiates through German-engineered spray-head aeration systems that exceed baseline flow-reduction thresholds.
A kitchen faucet is a valved plumbing fixture that delivers temperature-controlled water to food-preparation and cleaning sinks, typically rated for pressures between 20 and 125 psi and constructed with lead-free brass bodies or 304-grade stainless steel castings to comply with potable-water contact standards. Its primary commercial purpose is to regulate flow volume, temperature mixing, and spray modality in residential and food-service environments. Pull-down configurations now lead volume in new construction due to integrated hose-retract mechanisms that reduce cabinet intrusion, while matte black and brushed nickel finishes command margin premiums over commodity chrome as design-build specifications gravitate toward tonal coordination with appliance suites. Brass material grades remain the default in premium channels, though stainless steel gains specification share in coastal markets where salinity accelerates zinc-alloy corrosion.
EPA WaterSense and California CEC Title 20 jointly constrain maximum flow rates at 1.8 gallons per minute for labeled products, compelling manufacturers to redesign cartridge geometry without degrading user-perceived pressure. The EU Ecodesign Directive and associated CE marking requirements enforce comparable efficiency thresholds across member states, creating a dual-compliance burden for exporters. REACH restrictions on nickel release rates further limit surface-plating chemistries available to European-bound production lines. Stakeholders must monitor evolving state-level lead-content thresholds and determine whether regional SKU proliferation or unified global platform design offers superior capital efficiency.
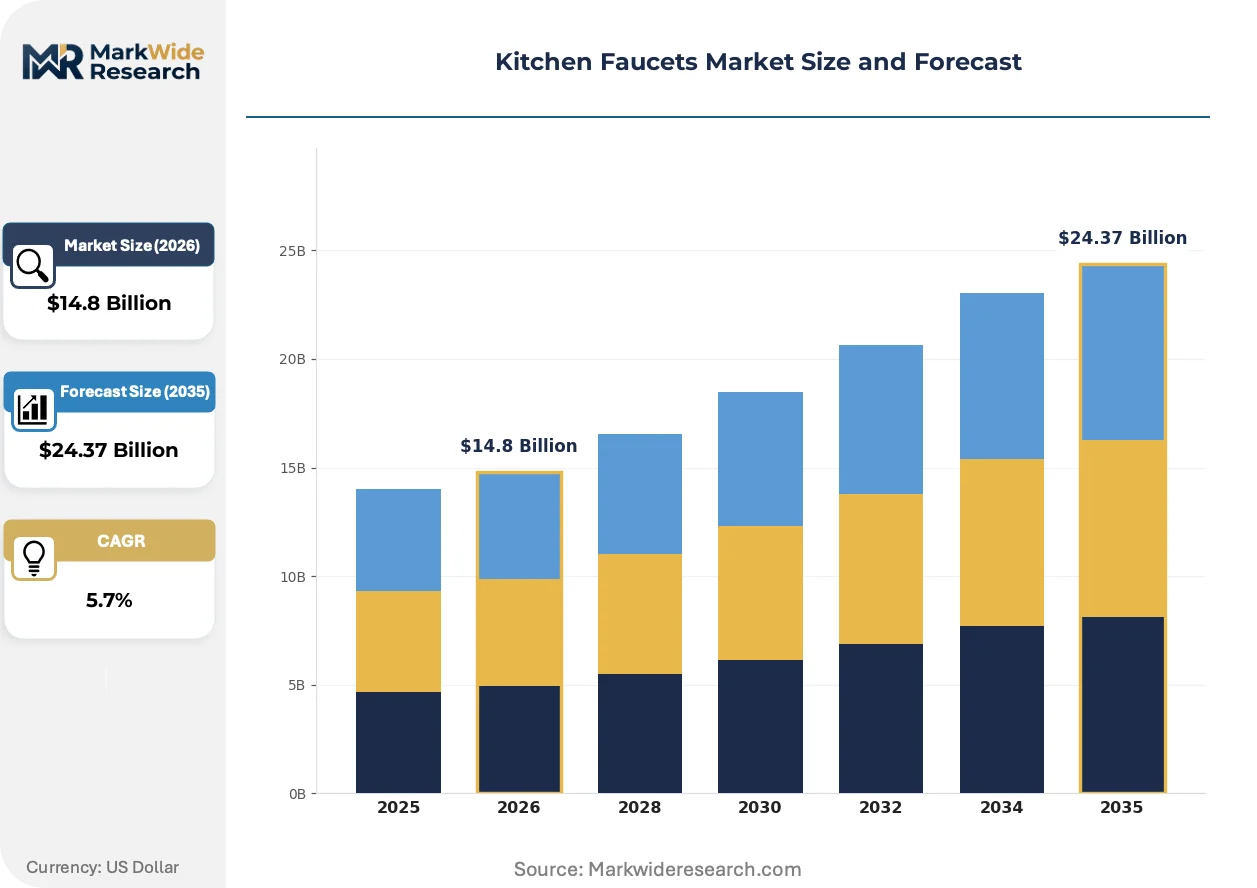
Market Dynamics
EPA WaterSense flow-rate ceilings and REACH nickel-release limits are compressing cartridge design freedom while fragmenting SKU portfolios between compliant and non-compliant production streams.
Growth Catalysts
- Residential renovation cycles:Single-family homeowners in the United States are replacing fixtures at accelerated cadences as housing turnover rates climb and kitchen aesthetic refresh timelines compress.
- EU Ecodesign Directive enforcement:Mandatory CE marking for water-efficiency performance is creating specification pull across German, French, and Italian distribution channels for certified pull-down configurations.
- Touchless sensor integration:Infrared proximity activation modules are penetrating mid-range price bands as Chinese sensor OEMs drive component costs downward.
Market Restraints
- Brass alloy cost volatility:LME copper and zinc price swings directly compress foundry margins, forcing quarterly contract renegotiations with fixture assemblers.
- Zhejiang province supply concentration:Over sixty percent of global ceramic disc valve output originates from Wenzhou-area manufacturers, creating single-point vulnerability to regional power rationing or logistics disruption.
- California CEC Title 20 preemption:State-level flow-rate standards that exceed federal baselines force parallel inventory maintenance for California-bound versus rest-of-country distribution.
Strategic Opportunities
- India urban housing clusters:Mumbai and Bangalore high-rise construction pipelines remain undersupplied with mid-range pull-down faucets relative to fixture-per-unit penetration rates in Chinese comparable developments.
- Voice-activated temperature control:Integration of Alexa and Google Home protocols with thermostatic mixing valves opens specification channels in smart-home new construction verticals.
- Modular cartridge retrofit kits:Aftermarket conversion packages that upgrade legacy single-handle bodies to WaterSense-compliant flow profiles bypass full-fixture replacement economics for budget-constrained renovators.
Industry Challenges
- Lead-free casting expertise scarcity:Foundry workforce attrition in Ohio and Pennsylvania brass-producing regions constrains capacity expansion for domestic EPA-compliant supply.
- Dual-certification timeline compression:Simultaneous WaterSense and CE marking test cycles extend product launch windows by four to six months versus single-territory rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Faucets Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pull-Down, Pull-Out, Single Handle, Double Handle Material: Stainless Steel, Brass, Plastic, Nickel Style: Modern, Traditional, Rustic, Industrial Finish: Chrome, Matte Black, Brushed Nickel, Oil-Rubbed Bronze |
| Companies Covered | Delta Faucet Company, Lixil Group Corporation, Kohler Co., Hansgrohe SE, American Standard Brands, Moen Incorporated, Toto Ltd., Masco Corporation, Grohe AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Faucets Market Emerging Trajectories
Sensor-activated flow control, regulatory compliance automation, and finish-coordination specifications are converging to redefine product architecture and procurement criteria across residential and commercial channels.
Solenoid-actuated cartridge assemblies are miniaturizing to fit within standard faucet body dimensions without sacrificing flow precision. Custom home builders in Texas and Florida are specifying these modules at triple the rate of two years prior. The technology is miniaturizing control electronics sufficiently to displace mechanical mixing valves in volume-priced segments previously resistant to automation premiums.
REACH Annex XVII nickel-release amendments are restricting chromium-nickel plating chemistries for European-bound production lines. Surface finish houses in Guangdong province are pivoting to PVD titanium-nitride alternatives that satisfy ECHA thresholds while maintaining abrasion resistance. Matte black PVD coatings now capture specification share previously held by brushed nickel in German kitchen retail channels.
Builder procurement departments are consolidating vendor lists to reduce compliance audit burdens. National production homebuilders in the United States are awarding three-year exclusive supply agreements to single-source faucet manufacturers with pre-certified WaterSense portfolios. This concentration is most visible in Arizona and Nevada master-planned communities where design-center option packages standardize across hundreds of annual closings.
Kitchen Faucets Market Segmentation
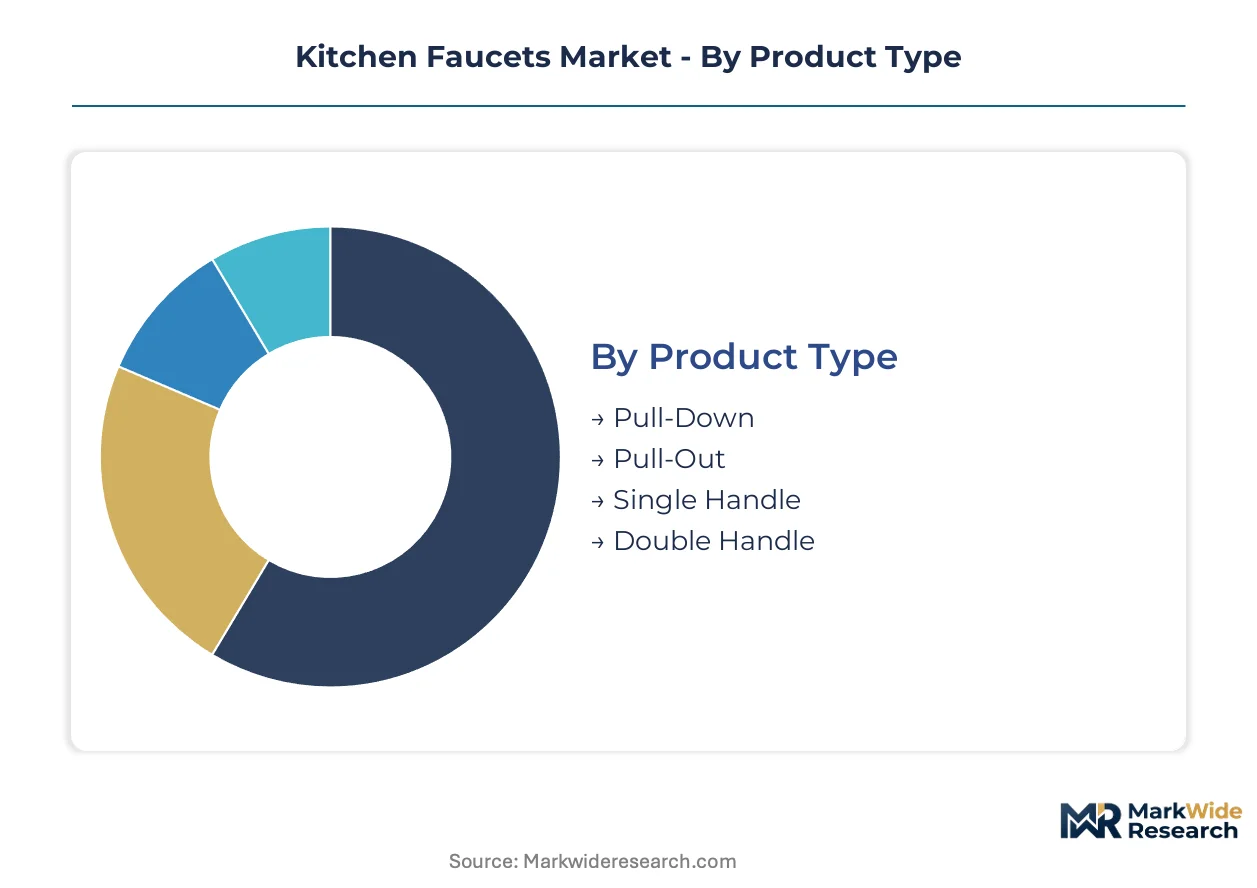
Kitchen faucet procurement decisions cascade through multiple attribute layers, from functional mechanism to surface chemistry, each carrying distinct margin profiles and specification authority. Builders, renovators, and retail buyers weight these dimensions differently across project types and price bands.
Product Type:
Margin pools concentrate in configurations that integrate hose-retract mechanisms and multi-function spray heads, commanding specification premiums in design-build channels.
- Pull-Down:Integrated counterweight hose-retract systems and magnetic docking deliver professional-grade spray functionality within residential body dimensions. Demand clusters in Chinese urban high-rise developments and US master-planned communities where space efficiency and task versatility drive specification. EPA WaterSense certification requirements favor these configurations for their precise flow modulation capabilities.
- Pull-Out:Compact hose extension suits smaller sink basins and bar-prep applications where cabinet depth constraints limit vertical clearance. European kitchen renovations in German and French metropolitan areas specify these for secondary sink locations, balancing maneuverability with countertop footprint discipline.
- Single Handle:Cartridge-based temperature mixing dominates volume production through simplified installation and one-handed operation.
- Double Handle:Separate hot-cold valve bodies persist in traditional aesthetic specifications and heritage property restorations.
Pull-Down holds installed capacity. Pull-Out is rotating up the share rankings in compact kitchen renovations.
Material:
Cost tier stratification runs from commodity polymer housings through engineered alloys, with coastal corrosion resistance and lead-content compliance reshaping procurement priorities.
- Brass:Lead-free copper-zinc castings remain the default for premium channels, offering machinability for complex internal waterways and reliable ceramic disc valve seating. Foundry capacity in Ohio and Pennsylvania constrains domestic EPA-compliant supply expansion. REACH nickel-release thresholds in Europe complicate surface plating chemistries for brass-bound export production.
- Stainless Steel:304-grade castings gain specification share in Florida, California, and other coastal markets where atmospheric salinity accelerates dezincification of traditional alloys. PVD coating adhesion on stainless substrates enables matte black and brushed finish durability without chromium-nickel plating.
- Plastic:Glass-reinforced polymer bodies serve economy price bands and rental-property replacement cycles where first-cost minimization overrides longevity specifications.
- Nickel:Solid nickel alloy applications remain niche, concentrated in laboratory and healthcare-adjacent residential installations requiring superior corrosion resistance.
Brass dominates current revenue contribution. Stainless Steel is climbing the fastest in coastal specification channels.
Style:
Application context determines aesthetic authority, with new construction favoring clean lines and renovation projects accommodating existing architectural vocabulary.
- Modern:Minimalist cylindrical bodies and right-angle spout geometries align with appliance-suite coordination in contemporary kitchen design. Texas and Florida custom home builders specify these at accelerated rates for open-concept entertaining spaces.
- Traditional:Curved spout profiles and cross-handle detailing serve heritage property renovations and transitional design schemes. US Northeast and Midwest housing stock turnover sustains replacement demand.
- Rustic:Farmhouse-inspired bridge configurations and oil-rubbed bronze finishes target rural and exurban residential construction.
- Industrial:Exposed spring-coil spouts and utilitarian lever handles capture commercial-kitchen aesthetic translations in residential loft conversions.
Modern holds specification momentum in new construction. Traditional maintains renovation channel loyalty.
Finish:
Surface chemistry differentiation now carries compliance burdens alongside aesthetic function, with European-bound production facing REACH Annex XVII nickel-release constraints.
- Matte Black:PVD titanium-nitride deposition satisfies ECHA thresholds while delivering abrasion resistance and tonal coordination with black stainless appliance suites. German kitchen retail channels have shifted specification share from brushed nickel toward this finish.
- Brushed Nickel:Satin-surface chromium-nickel plating persists in North American mid-market specifications despite European regulatory pressure. Builder procurement consolidation in Arizona and Nevada master-planned communities standardizes this finish across option packages.
- Chrome:Mirror-polished electroplating retains economy segment dominance and commercial food-service specification.
- Oil-Rubbed Bronze:Living-finish chemistry darkens with age, suiting traditional and rustic style coordination.
Matte Black is gaining share fastest in European specification. Brushed Nickel retains volume leadership in North American production homebuilding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-family renovators and production homebuilders concentrate procurement authority in distinct geographic clusters, with regulatory divergence fragmenting product specifications across national boundaries.
United States
Master-planned communities in Arizona and Nevada standardize faucet specifications across design-center option packages, compressing vendor lists to reduce compliance audit burdens. EPA WaterSense certification requirements tighten flow-rate ceilings to 1.8 gallons per minute, forcing cartridge redesigns. Ohio and Pennsylvania brass foundries face workforce attrition that constrains domestic lead-free casting capacity expansion.
China
Urban high-rise construction in Shanghai and Shenzhen sustains volume procurement of mid-range pull-down configurations for compact kitchen footprints. The country's national standards body enforces GB potable-water contact requirements that align with international lead-content thresholds. Wenzhou-area manufacturers concentrate over sixty percent of global ceramic disc valve output, creating single-point vulnerability to regional power rationing.
Germany
Kitchen retail channels in Munich and Hamburg have shifted specification share from brushed nickel toward matte black PVD finishes that satisfy ECHA nickel-release thresholds. EU Ecodesign Directive enforcement mandates CE marking for water-efficiency performance, creating specification pull for certified configurations. Baden-Württemberg engineering clusters anchor spray-head aeration system development for premium export markets.
India
Mumbai and Bangalore high-rise construction pipelines remain undersupplied with mid-range pull-down faucets relative to fixture-per-unit penetration rates in Chinese comparable developments. The Bureau of Indian Standards enforces BIS certification for plumbing fixtures in urban housing projects. Gujarat manufacturing corridors attract brass foundry investment serving domestic renovation demand and Middle East export contracts.
United Arab Emirates
Luxury residential towers in Dubai specify premium finishes that coordinate with European appliance import suites. The country's national standards regulator enforces UAE-specific water-efficiency labeling that exceeds baseline Gulf Cooperation Council thresholds. Sharjah industrial zones host assembly operations for regional distribution into Saudi Arabian and Qatari construction markets.
Kitchen Faucets Market Vendor Landscape
Player mix skews toward vertically integrated brass foundry operators and specialist finish-coating houses. The competitive terrain splits between scale-driven manufacturers with captive alloy supply and design-oriented specialists competing on spray-engineering differentiation. Three archetypes dominate: foundry-integrated assemblers controlling ingot-to-cartridge quality chains; sensor-technology integrators sourcing Chinese OEM proximity modules; and surface-finish specialists pivoting to PVD chemistries for European REACH compliance. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing three-year exclusive supply agreements with national production homebuilders.
Among North American fixture manufacturers, Delta Faucet Company and Kohler Co. occupy positions that exemplify foundry-integrated competitive architecture, while Hansgrohe SE anchors the European engineering-specialist tier. These three names represent distinct strategic postures: captive brass supply control, ceramic disc valve manufacturing depth, and German-engineered aeration system differentiation respectively.
| Leading Market Players |
|---|
| Delta Faucet Company |
| Lixil Group Corporation |
| Kohler Co. |
| Hansgrohe SE |
| American Standard Brands |
| Moen Incorporated |
| Toto Ltd. |
| Masco Corporation |
| Grohe AG |
| Others |
Supply Flow & Price Mechanics
Foundry capacity utilization rates above eighty percent in Guangdong and Zhejiang provinces compress brass alloy pricing power toward assemblers while elevating spot-market premiums for EPA-compliant lead-free castings. This scale concentration shapes both supply availability and price floors across residential renovation and new construction channels.
Pricing Analysis
Cost-plus contracts with LME copper and zinc indexation dominate brass foundry agreements, forcing quarterly renegotiations when alloy baskets swing. Pricing stratifies across premium, standard, and economy tiers based on WaterSense certification status and finish durability specifications. Cost compression in mid-range segments is intensifying as Chinese sensor OEMs drive touchless module prices downward. Production homebuilders in Arizona and Nevada master-planned communities exhibit lowest price sensitivity due to three-year exclusive supply agreements, while independent renovators in the US Northeast demonstrate highest elasticity.
Supply Chain Analysis
Strategic stockpiling of ceramic disc valves and brass ingots prevails among tier-one assemblers wary of Wenzhou-area power rationing, while smaller fabricators run lean just-in-time inventories. Supply concentrates in China, the United States, and Germany for finished assemblies, with India emerging as an alternative brass foundry location. Raw material dependencies center on LME-traded copper and zinc, plus rare-earth elements for sensor modules. Single-source vulnerability pervades ceramic disc valve procurement from Wenzhou manufacturers. Distribution runs through big-box retail chains, plumbing wholesale distributors, and direct builder supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between EPA WaterSense, EU Ecodesign, and REACH Annex XVII creates niche positioning opportunities for specialists capable of dual-certification efficiency. Specification authority dispersal across production homebuilders, design-build renovators, and retail channels fragments demand into addressable pockets.
For Market Incumbents: Consolidate brass foundry capacity through acquisition of distressed Ohio and Pennsylvania operators facing workforce attrition. Secure exclusive three-year supply agreements with national production homebuilders to lock out sensor-technology integrators before Chinese OEM modules commoditize touchless activation. Prioritize backward integration into PVD coating facilities to bypass REACH nickel-release constraints on European-bound production. For New Entrants and Emerging Players: WaterSense fast-track certification programs open specification channels in California CEC Title 20 and federal renovation rebate programs. Target Mumbai and Bangalore high-rise construction pipelines where mid-range pull-down penetration lags Chinese comparable developments. Pursue modular cartridge retrofit kits as the go-to-market angle, bypassing full-fixture replacement economics for budget-constrained US renovators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors foundry-integrated assemblers with captive brass supply and pre-certified regulatory portfolios over pure-play finish-coating houses. Long-term viability hinges on voice-activated temperature control integration and smart-home protocol adoption rates. Watch Alexa and Google Home faucet skill activation volumes as the inflection indicator for premium segment shift timing.| Strategic Initiative | Industry Significance |
|---|---|
| Brass Foundry Acquisition | Captive lead-free casting capacity secures EPA compliance amid Ohio and Pennsylvania workforce attrition. |
| Dual-Certification Platform Design | Unified WaterSense and CE marking reduces SKU fragmentation and accelerates product launch timelines. |
| Voice-Activated Integration | Alexa and Google Home protocol compatibility opens smart-home new construction specification channels. |
| Modular Retrofit Kit Development | Aftermarket cartridge upgrades bypass full-fixture replacement economics for budget renovators. |
| PVD Coating Facility Investment | In-house titanium-nitride deposition satisfies REACH Annex XVII thresholds for European market access. |
Methodological Framework
Desk research of customs trade databases, EPA WaterSense product directories, and EU Ecodesign compliance registries preceded structured interviews with brass foundry operations managers, plumbing wholesale procurement directors, production homebuilder specification coordinators, and ceramic disc valve manufacturing engineers. Secondary validation drew from LME metals pricing archives, REACH Annex XVII amendment filings, and BIS plumbing fixture certification records. Bottom-up demand modeling triangulated against top-down construction permit data across the analysis window.
Variance decomposition across product type, material grade, finish chemistry, and regional regulatory cluster anchored the analytical framework throughout the projection horizon. CAGRs derived from segmented volume trajectories weighted by replacement cycle timing and new construction pipeline visibility. Forecast inputs incorporated housing turnover velocity, LME alloy price band assumptions, and sensor module cost decline curves.
Underlying assumptions cover stable brass foundry capacity utilization, continued WaterSense specification pull in US master-planned communities, and REACH Annex XVII enforcement consistency, with deviation risk concentrated in Wenzhou-area logistics disruption and California CEC Title 20 preemption expansion. Revision becomes warranted when ceramic disc valve supply concentration or voice-activated adoption rates cross material thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Housewares (Tabletopware) Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market
Kitchen and Dining
Prefabricated Kitchen Pod Market
Kitchen and Dining
Europe Restaurant Furniture Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Interactive Tables Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
GCC Modular Kitchen Market