
 Housewares (Tabletopware) Market | 2026-2036
Housewares (Tabletopware) Market Size, Share, and Industry Trends Forecast 2026-2036
Housewares (Tabletopware) Market Intelligence
A renewed focus on artisanal design and specialized craftsmanship is reorganizing competitive dynamics in the premium tabletopware segment. Lenox Corporation leverages its brand heritage in fine dinnerware to appeal to this trend. In contrast, WMF Group differentiates through its focus on German engineering in stainless steel flatware and utensils. Arc International sustains its market position through large-scale glassware production across multiple continents.
Housewares, specifically tabletopware, encompasses the range of products used for setting a table, serving food, and dining. These items, including dinnerware, flatware, and glassware, are manufactured from materials like ceramic, glass, and 18/10 stainless steel. The material composition, such as the grade of porcelain or the lead content in crystal, dictates both aesthetic quality and functional use. While ceramic and glass products lead the market, the household customer segment is showing a clear preference for sustainable options like bamboo and melamine.
Global market access is governed by stringent food-contact material regulations. The U.S. FDA sets limits on lead and cadmium in ceramicware, while the EU's REACH framework restricts certain chemicals used in manufacturing processes. Similarly, China's GB standards impose strict food safety requirements on all tabletop products. Navigating this fragmented regulatory landscape to ensure compliance for materials and finished goods remains a primary challenge for manufacturers.
Market Dynamics
A fundamental divergence between mass-market scale and premium-segment artisanal demand is shaping the tabletopware industry. This structural split forces specialization, pitting large-scale production for hospitality against high-value, design-led dinnerware and flatware for discerning consumers.
Growth Catalysts
- Hospitality Sector Expansion:Growth in hotel and catering services, particularly in developing economies like India and Brazil, directly fuels volume demand for durable dinnerware, glassware, and stainless steel flatware.
- Sustainable Materials Adoption:Consumer and corporate ESG mandates are driving the adoption of materials like bamboo, recycled glass, and lead-free crystal, creating new product categories and value propositions.
- Urbanization and Housing Growth:Rising disposable incomes and housing development in Southeast Asian and Middle Eastern urban centers stimulate household demand for full tableware sets, moving beyond basic necessities.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the costs of high-grade inputs like 18/10 stainless steel, soda-lime glass, and specialized ceramic clays compress manufacturer margins and complicate long-term pricing.
- Fragmented Food-Contact Regulations:Disparities between the EU's REACH framework, US FDA limits on heavy metals, and China's GB standards create significant compliance costs and market entry barriers.
- Competition from Disposable Alternatives:In high-volume food service and casual dining, high-quality disposable or compostable tableware presents a persistent substitution threat to traditional ceramic and glass products.
Strategic Opportunities
- Health and Wellness Niche:Development of tabletopware with antimicrobial coatings or materials that do not leach chemicals offers a premium-priced opportunity in health-conscious consumer and healthcare segments.
- Direct-to-Consumer (DTC) Channels:Leveraging e-commerce platforms allows artisanal and specialized brands to bypass traditional retail, building direct relationships with consumers and capturing higher margins.
- African Hospitality Growth:As tourism and business travel expand in countries like Nigeria and Kenya, the nascent high-end hotel sector represents an underpenetrated market for premium tabletopware suppliers.
Industry Challenges
- Lengthy Certification Cycles:Obtaining food-contact safety certifications, such as those required by the EFSA in Europe or the FSSAI in India, involves prolonged testing that can delay new product launches.
- Supply Chain Reconfiguration:Shifting production away from single-country concentrations to mitigate geopolitical risk requires substantial capital investment and the qualification of new material suppliers.
- Scarcity of Artisanal Skills:The premium segment's reliance on specialized craftsmanship, such as hand-painting ceramics or advanced glassblowing, faces a challenge from a diminishing pool of trained artisans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Housewares (Tabletopware) Market |
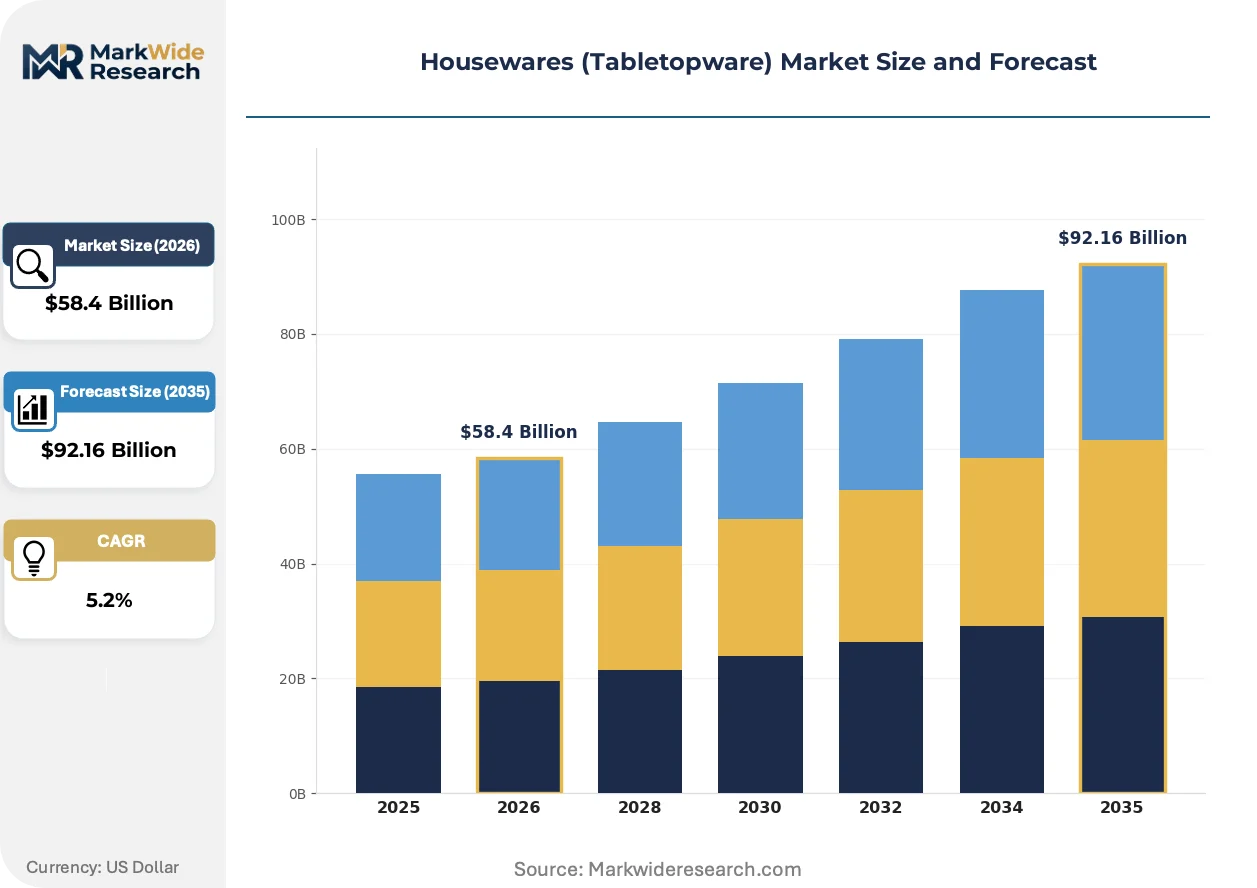
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $92.16 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dinnerware, Flatware, Glassware, Serveware, Kitchen Utensils Material: Ceramic, Stainless Steel, Glass, Plastic, Bamboo, Melamine Distribution Channel: Specialty Stores, Mass Merchandisers, Online Retailers, Department Stores, Direct Sales Customer Type: Households, Restaurants, Cafes, Hotels, Catering Services |
| Companies Covered | Lenox Corporation, Matfer Bourgeat International, Arc International, Bormioli Rocco, WMF Group, The Oneida Group, The Vollrath Company, Fortessa Tableware Solutions, Libbey Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Housewares (Tabletopware) Market Strategic Shifts & Innovations
Product innovation in tabletopware is now driven by the convergence of material science and sustainability mandates. This shift, which is reshaping design, prioritizes non-toxic, circular, and ethically sourced materials, altering both manufacturing processes and brand messaging for glassware and dinnerware producers.
Advanced melamine and reinforced bamboo composites offer lightweight, durable alternatives to traditional ceramics. The fast-casual dining and institutional catering sectors are rapidly adopting these materials for their break-resistance and operational efficiency. This adoption of engineered composites is displacing heavier, more fragile ceramic and stoneware in high-turnover commercial environments.
The European Union's heightened enforcement of REACH regulations restricts the use of certain plasticizers and heavy metals in manufacturing processes. This is forcing a redesign of supply chains and material formulations for any producer exporting to the EU. The glassware and decorated ceramic segments are most affected, accelerating the move toward lead-free crystal and organic-based pigments to ensure market access.
A preference for curated, mix-and-match table settings is altering household purchasing patterns. This behavior disrupts the traditional sale of complete, uniform dinnerware sets, favoring retailers and brands that offer individual pieces or small, coordinated collections. The trend is most prominent in North American and European e-commerce channels, driven by social media aesthetics and a desire for personalization.
Housewares (Tabletopware) Market Segmentation
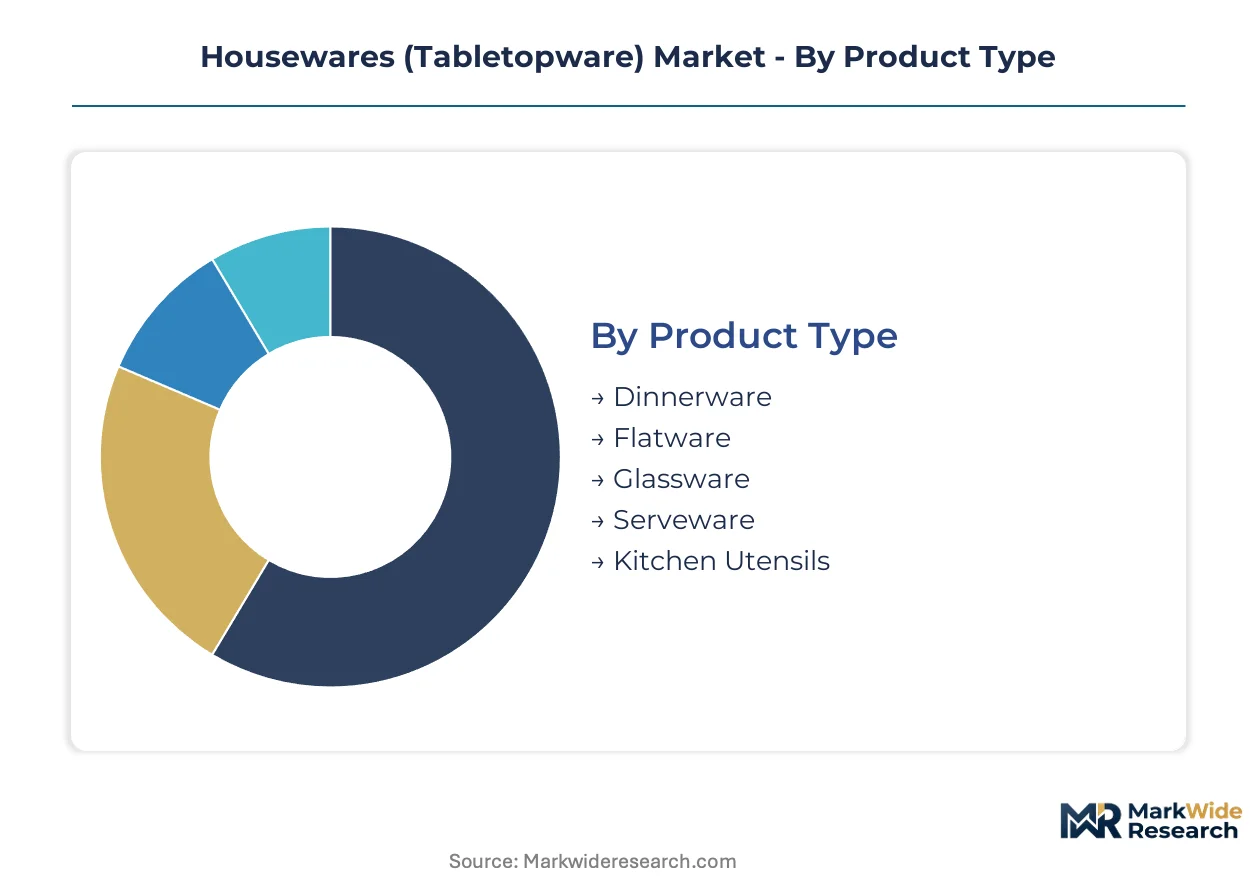
Segmentation within the tabletopware market reveals distinct demand drivers and competitive landscapes. Understanding these divisions helps manufacturers tailor product lines and distribution strategies. This granular analysis identifies where value accrues across diverse product types and customer bases.
Product Type:
Margin pools within the product type category are bifurcated. Premium artisanal dinnerware and specialized flatware command higher value, while mass-produced items operate on thinner margins.
- Dinnerware:Dinnerware includes plates, bowls, and cups, typically ceramic, forming the core of any table setting. Demand for durable dinnerware concentrates in India's expanding hospitality sector.
- Flatware:Flatware encompasses forks, knives, and spoons, primarily 18/10 stainless steel, designed for functionality and aesthetic appeal. Premium flatware sees demand in European households seeking artisanal designs.
- Glassware:Glassware comprises drinking vessels and serving items, manufactured from soda-lime glass or lead-free crystal.
- Serveware:Serveware includes platters, bowls, and tureens for presenting food, often made from ceramic or metal.
- Kitchen Utensils:Kitchen utensils cover tools for food preparation and cooking, utilizing stainless steel, silicone, and wood.
Dinnerware holds significant installed capacity in manufacturing. Flatware is rotating up the share rankings, especially in the premium segment.
Material:
Material segmentation highlights diverse cost tiers and functional properties in tabletopware. Material choice impacts durability, aesthetics, and regulatory compliance.
- Ceramic:Ceramic materials, including porcelain and stoneware, are used for dinnerware due to versatility and heat retention. Demand concentrates in European markets for fine dining.
- Bamboo:Bamboo offers a sustainable, lightweight alternative for durable plates and bowls. This material gains traction in North American households, driven by sustainability mandates.
- Stainless Steel:Stainless steel, particularly 18/10 grade, is primary for flatware, valued for corrosion resistance and strength.
- Glass:Glass is essential for drinkware, ranging from soda-lime for mass production to lead-free crystal for premium use.
- Plastic:Plastic provides lightweight, break-resistant options, primarily used in casual dining, outdoor settings, and children's tableware.
- Melamine:Melamine, a durable plastic, offers chip resistance and is favored for commercial catering and fast-casual dining.
Bamboo and melamine composites are expanding most quickly. Ceramic maintains its market presence across various price points.
Distribution Channel:
Distribution channels define how tabletopware reaches diverse customer segments, influencing brand visibility and price accessibility. Each channel caters to specific purchasing behaviors.
- Specialty Stores:Specialty stores focus on niche selections, emphasizing premium, artisanal, or design-led tabletopware, providing a curated experience. These cater to consumers in Germany and France.
- Mass Merchandisers:Mass merchandisers offer a broad range of affordable tabletopware, targeting budget-conscious consumers through high-volume sales.
- Online Retailers:Online retailers offer extensive product selections and convenience, enabling direct-to-consumer sales. This channel grows in North America and Europe, driven by consumer preferences for curated table settings.
- Department Stores:Department stores provide a mid-to-high-end shopping environment, featuring established brands and seasonal collections.
- Direct Sales:Direct sales involve manufacturers selling directly to commercial clients like hotels, often for custom orders and bulk purchases.
Procurement patterns are shifting towards online retailers. Specialty stores maintain their appeal for unique, high-value purchases.
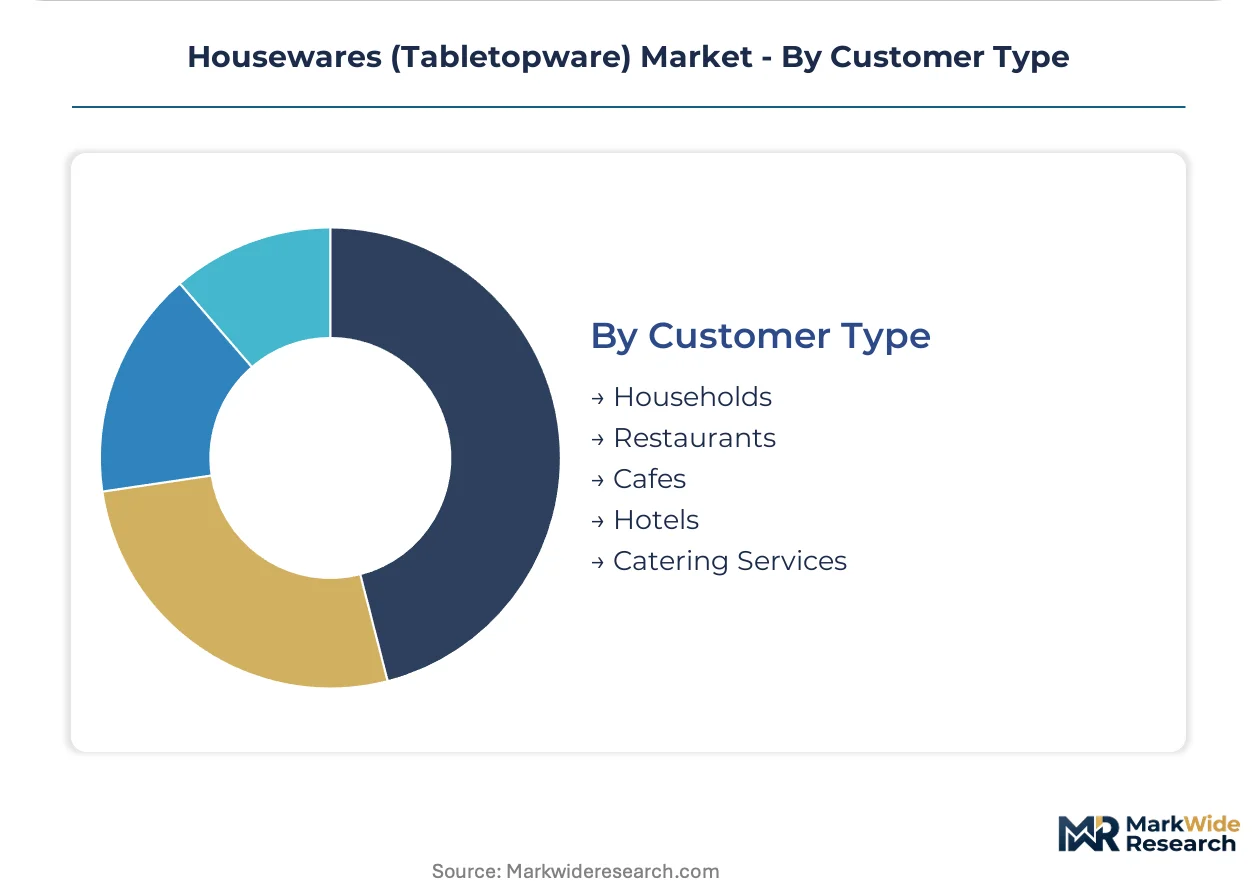
Customer Type:
Customer type segmentation distinguishes between high-volume commercial demand and value-driven household consumption. Each segment has unique requirements for durability and design.
- Households:Households represent individual consumers purchasing tabletopware for personal use, driven by aesthetic preferences and lifestyle trends. Demand is strong in Southeast Asian urban centers and the Middle East.
- Restaurants:Restaurants demand resilient and visually appealing tabletopware that can withstand frequent use and commercial dishwashing.
- Cafes:Cafes typically require functional and stylish drinkware and small plates, prioritizing durability and ease of cleaning.
- Hotels:Hotels require durable, aesthetically consistent tabletopware, often procured in bulk. High-end hotel expansion in Nigeria and Kenya creates substantial demand for premium dinnerware.
- Catering Services:Catering services need portable, durable, and stackable tabletopware suitable for events, balancing aesthetics with logistical efficiency.
Volume concentration for tabletopware is evident within the hospitality sector. Households drive demand for personalized collections.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's FSSAI regulations shape product standards for a significant and expanding tabletopware market. This market sees substantial growth from its hospitality sector and rising household demand. Developing economies are driving volume, while established markets focus on premium offerings.
India
FSSAI standards govern food-contact materials for India's burgeoning tabletopware sector. Its rapidly expanding hospitality industry, particularly in urban centers like Mumbai and Bangalore, fuels high volume demand. The country's growing middle class also drives household purchases. This combination positions India as a significant growth engine.
Germany
Germany's market demands premium, design-led tabletopware, aligning with its strong artisanal tradition. The EU's REACH framework significantly influences material choices and manufacturing processes for German producers. Bavaria remains a hub for specialized ceramic and glassware manufacturers, focusing on high-value exports. This region emphasizes quality and sustainable production.
United States
The United States market exhibits a strong preference for curated, mix-and-match table settings through e-commerce channels. FDA regulations set strict limits on heavy metals in ceramicware, guiding material sourcing. Major urban centers like New York and Los Angeles influence design trends and drive demand for personalized household collections. Sustainable materials are also gaining traction.
China
China's vast manufacturing capabilities support both domestic consumption and global tabletopware exports. GB standards impose rigorous food safety requirements on all products, affecting production lines. Manufacturing hubs in Guangdong and Zhejiang provinces specialize in large-scale ceramic and glassware production. The domestic market also sees rising demand for quality products.
Nigeria
Nigeria represents an underpenetrated market for premium tabletopware, driven by expanding high-end hotel sectors. NAFDAC regulations ensure safety and quality for imported and domestically produced food-contact items. Major cities like Lagos and Abuja are experiencing significant hospitality development, creating specific demand for durable and aesthetically consistent products. Tourism growth also contributes to this demand.
Housewares (Tabletopware) Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the tabletopware market structure. This market exhibits a structural split between mass-market scale production and premium-segment artisanal demand. Archetypes include large-scale manufacturers, heritage brands focusing on craftsmanship, and specialized material innovators. Companies pursue strategic partnerships for market access and expand production capacity to meet volume demand.
Within the heritage brand segment, Lenox Corporation exemplifies a focus on fine dinnerware, leveraging its established brand history. WMF Group, a German entity, occupies a position emphasizing engineering excellence in stainless steel flatware and utensils. Arc International, a French glassware manufacturer, anchors the large-scale production archetype, serving diverse global markets. These companies represent distinct strategic approaches within the competitive landscape.
| Leading Market Players |
|---|
| Lenox Corporation |
| Matfer Bourgeat International |
| Arc International |
| Bormioli Rocco |
| WMF Group |
| The Oneida Group |
| The Vollrath Company |
| Fortessa Tableware Solutions |
| Libbey Inc. |
| Others |
Cost & Logistics Intelligence
US FDA regulations directly influence the qualification of tabletopware suppliers and establish a baseline for price differentiation in export markets. Compliance costs and material specifications elevate pricing for certified goods.
Pricing Analysis
Price spreads for tabletopware vary significantly across regions, with premium artisanal items commanding higher prices in European markets. The market primarily operates on a per-unit transactional model, with pricing stratifying across premium, standard, and economy tiers. Quality grade, such as 18/10 stainless steel or lead-free crystal, and brand heritage drive differentiation. Pricing softness stems from raw material price volatility and competition from disposable alternatives, particularly impacting mass-market segments where buyers exhibit high price sensitivity.
Supply Chain Analysis
Inventory management and lead times face challenges due to global sourcing complexities for tabletopware components. Supply concentrates heavily in China for large-scale production, alongside specialized manufacturing hubs in Germany. Production draws from key raw materials like 18/10 stainless steel, soda-lime glass, and specialized ceramic clays. Commodity price volatility represents a structural risk. Distribution runs through online retailers for personalized household collections and direct sales for commercial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tabletopware market requires a strong substitution defense, as high-quality disposable or compostable alternatives present a persistent threat to traditional products. Incumbents must navigate this challenge strategically.
For Market Incumbents:Secure supply chains for sustainable materials like recycled glass and bamboo to meet evolving consumer preferences. Invest in advanced material science to develop antimicrobial coatings, enhancing product value in health-conscious segments. Strengthen brand heritage and artisanal design to counter mass-market competition and disposable product threats.
For New Entrants and Emerging Players:Differentiate on health and wellness attributes, developing tabletopware with antimicrobial properties or non-leaching materials for premium pricing. Target underpenetrated markets like African hospitality, focusing on high-end hotels in Nigeria and Kenya. Leverage direct-to-consumer e-commerce platforms to build brand loyalty and capture higher margins from specialized design-led collections.
For Investors and Strategic Acquirers:Carve-out targets emerge from larger conglomerates divesting non-core housewares divisions or from regional manufacturers seeking scale. The market demonstrates long-term viability, driven by urbanization and premiumization trends in developing economies. Watch for specialized material innovators or heritage brands with strong intellectual property and compliance expertise as acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Brand Extension | Lenox Corporation could extend its fine dinnerware heritage into sustainable material lines. |
| Direct-to-Consumer Launch | WMF Group can launch specialized flatware collections directly to European households. |
| Sustainable Material Integration | Arc International must integrate recycled glass into its large-scale glassware production. |
| Geographic Manufacturing Footprint | Matfer Bourgeat International should expand production capacity in Southeast Asian urban centers. |
| Certification Investment | The Oneida Group needs investment in EFSA and FSSAI certifications for global market access. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform market dynamics and validate data. Primary interviews included hospitality procurement managers, household goods retailers, material science engineers, and regulatory compliance officers. Secondary validation drew from FDA filings, EU REACH reports, China GB standards documents, and industry trade association reports. This approach facilitated bottom-up and top-down triangulation for robust market sizing.
The market forecast spans across the analysis window, utilizing an analytical framework that integrates quantitative and qualitative insights. Segmentation dimensions modeled include product type, material, distribution channel, customer type, and regional regulatory compliance frameworks. Compound annual growth rates were derived from historical data and projected market shifts, incorporating inputs like urbanization rates and hospitality sector expansion projections.
The analysis sits within stated boundaries; outcomes outside significant raw material price volatility or geopolitical shifts would require recalibration. Forecasts reflect assumptions regarding regulatory stability and consumer behavior. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Global Kitchenware Market
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Serveware Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
North America Tabletop Kitchen Products Market
Kitchen and Dining
United Arab Emirates Modular Kitchen Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
Skillets and Frying Pans Market