
 United Arab Emirates Hybrid and Electric Vehicles Market | 2026-2036
United Arab Emirates Hybrid and Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Hybrid and Electric Vehicles Market Analytics
Market Context
MOHAP's alignment with international vehicle safety protocols is decoupling import certification from legacy combustion-engine testing requirements. Tesla leverages its Supercharger footprint to anchor premium positioning across Dubai and Abu Dhabi. BYD sustains cost competitiveness through in-house battery production and scale manufacturing. Lucid Motors differentiates via extended-range powertrains that target luxury fleet contracts.
Technical and Structural Dimensions
Hybrid and electric vehicles integrate battery-electric drivetrains, regenerative braking systems, and power electronics with energy densities exceeding 250 Wh/kg for lithium-ion configurations, serving commercial and personal mobility with zero or reduced tailpipe emissions. Battery electric vehicles lead volume shipments among vehicle type segments, while fast charging stations command infrastructure investment flows due to fleet operator requirements for sub-30-minute turnaround times. Government agencies represent a concentrated end-user segment where procurement mandates direct manufacturer prioritization.
Regulatory Framework and Outlook
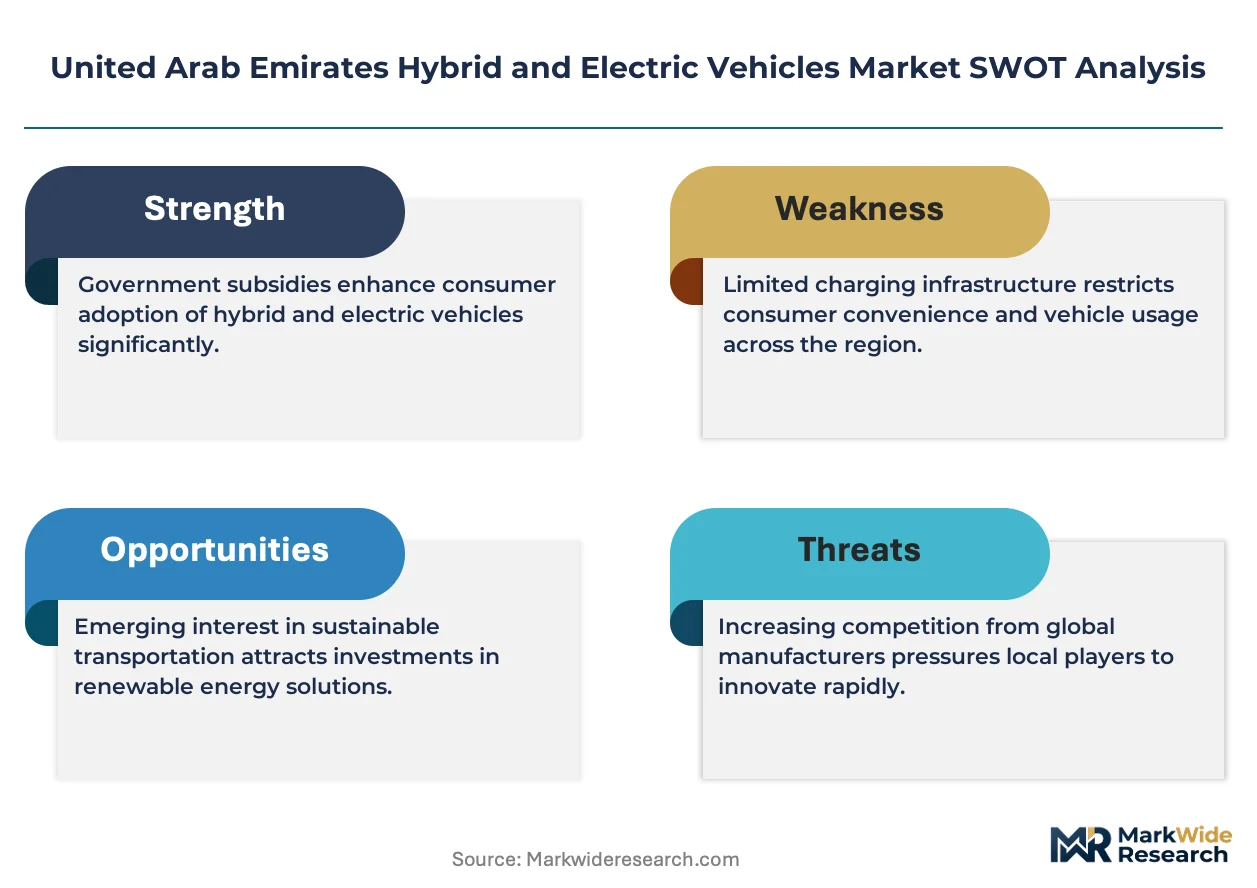
MOHAP and the Emirates Authority for Standardization and Metrology (ESMA) govern vehicle homologation and battery safety standards, compelling manufacturers to adapt thermal management systems to Gulf climate specifications. The UAE's net-zero commitments and Dubai's Green Mobility Strategy shape demand through public procurement quotas and free-zone incentives for EV assembly. Stakeholders must monitor charging infrastructure licensing rules and battery recycling mandates as the next regulatory frontier.
Market Dynamics
Fleet electrification mandates from Dubai's Roads and Transport Authority are compressing procurement cycles and forcing rapid supplier qualification changes across the Emirates' commercial vehicle channels.
Growth Catalysts
- Dubai Green Mobility Strategy 2030:Public sector procurement quotas now require 50% electrified vehicles in government fleets, creating guaranteed offtake for approved suppliers.
- Abu Dhabi Department of Energy charging standards:Unified technical specifications for fast-charging infrastructure are reducing deployment friction and accelerating network density along commercial corridors.
- Lithium iron phosphate battery chemistry:Improved thermal stability in Gulf climate conditions is extending vehicle operational lifespans and reducing warranty risk for fleet operators.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings of 40-60% over 18-month cycles are compressing battery pack margins and forcing price renegotiation clauses into supply contracts.
- Single-source dependency on Chinese cell suppliers:Concentration risk in Ningde and Shenzhen manufacturing clusters creates vulnerability to export license disruptions and shipping bottlenecks.
- ESMA thermal runaway testing protocols:Extended certification timelines for battery safety validation in ambient temperatures exceeding 45°C are delaying model launches by 8-14 months.
Strategic Opportunities
- Ras Al Khaimah free zone EV assembly:Zero customs duties on imported components and 15-year corporate tax holidays are attracting regional manufacturing investment.
- Vehicle-to-grid integration:Bidirectional charging protocols are enabling fleet operators to monetize stationary battery assets during peak demand periods.
- Sharjah commercial last-mile electrification:Underpenetrated logistics corridors present first-mover advantage for medium-duty electric truck deployment.
Industry Challenges
- Power electronics engineering talent scarcity:Shortage of qualified thermal management and inverter design specialists is constraining local R&D capacity and forcing reliance on foreign engineering services.
- Legacy fleet management system integration:Telematics platforms built for internal combustion monitoring require expensive retrofitting to capture electric drivetrain performance data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Hybrid and Electric Vehicles Market |
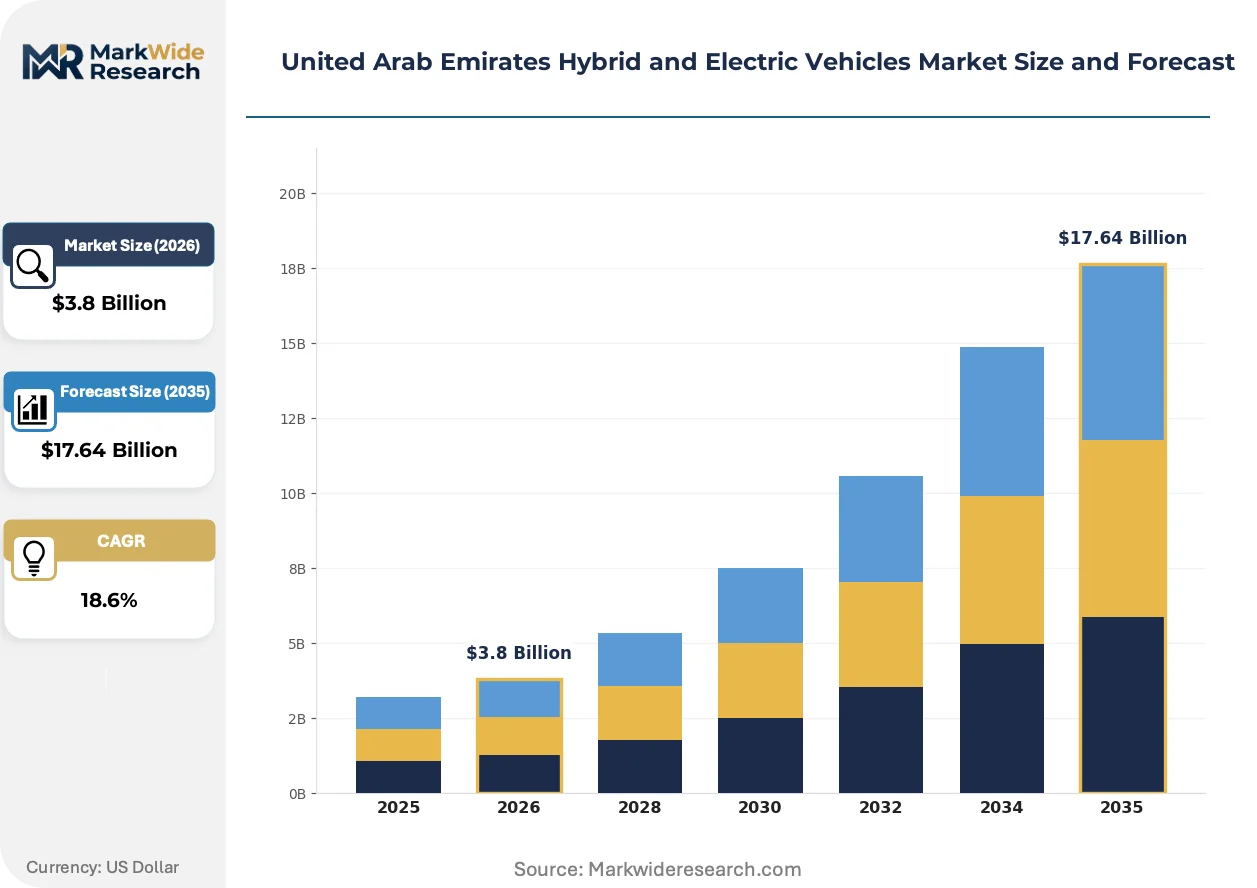
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Plug-in Hybrid, Battery Electric, Fuel Cell Electric, Mild Hybrid End User: Individual Consumers, Fleet Operators, Government Agencies, Ride-Sharing Services Battery Technology: Lithium-ion, Nickel-Metal Hydride, Solid State, Lead Acid Charging Infrastructure: Fast Charging Stations, Home Chargers, Standard Charging Points, Wireless Charging Solutions |
| Companies Covered | BMW, Lucid Motors, Tesla, Kia, NIO, BYD, Mercedes-Benz, MG Motor, Hyundai, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Hybrid and Electric Vehicles Market Evolving Landscape
Solid-state battery prototyping and silicon carbide power electronics are converging to redefine performance benchmarks, while regulatory pressure on supply chain provenance is forcing transparency investments.
Solid-state electrolyte technology is integrating ceramic separator layers that eliminate liquid thermal runaway risks. Dubai Electricity and Water Authority fleet pilots are testing prototype cells from Korean suppliers for 2026 deployment. This integration is compressing the safety margin requirements that previously dictated oversized battery enclosures and reduced payload capacity.
MOHAP's alignment with UN ECE R100 battery safety standards is decoupling UAE homologation from redundant European testing cycles. Manufacturers now submit single certification packages valid across GCC markets. Commercial vehicle segments with cross-border operating licenses are benefiting most, with Saudi and Bahrain fleet operators accepting UAE-certified vehicles without additional validation.
Corporate mobility budgets are consolidating under centralized procurement functions with total cost of ownership mandates replacing upfront price thresholds. Leasing providers and energy service companies are capturing fleet relationships previously held by traditional dealers. This concentration is most visible in Abu Dhabi's government-related entities, where Etihad Esco and Masdar joint ventures now specify 10-year operating contracts bundling vehicles, charging, and maintenance.
United Arab Emirates Hybrid and Electric Vehicles Market Segmentation
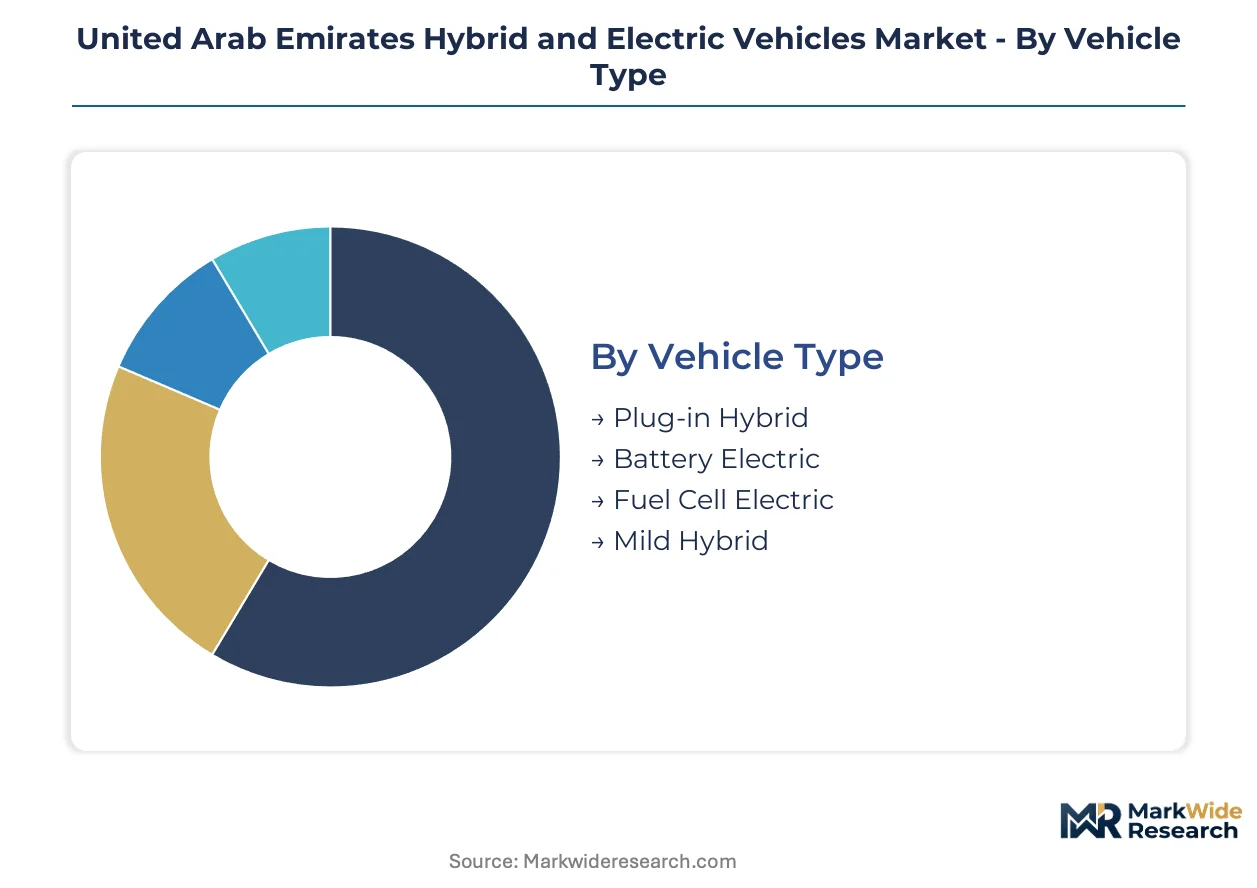
Segmentation in the UAE electrified vehicle market reveals how procurement concentration, climate adaptation requirements, and charging infrastructure economics fragment commercial opportunity across distinct technical and customer configurations.
Vehicle Type:
Supply concentration in battery pack assembly and powertrain integration favors vehicle architectures that leverage common cell formats and thermal management platforms.
- Battery Electric:Pure-electric drivetrains with energy densities exceeding 250 Wh/kg dominate fleet procurement in Dubai's commercial corridors, driven by government mandates for zero-emission government vehicle fleets. Battery electric configurations absorb the majority of charging infrastructure investment due to their complete dependency on grid electricity.
- Plug-in Hybrid:Dual-powertrain systems combining combustion engines with electric ranges of 50-80 kilometers serve long-distance commercial operators bridging Abu Dhabi-Dubai corridors where charging network density remains uneven. Plug-in hybrids attract individual consumers seeking fuel cost insulation without range anxiety.
- Mild Hybrid:48-volt belt-integrated starter-generator systems deliver marginal efficiency gains through regenerative braking without plug-in capability. Mild hybrid architectures penetrate price-sensitive fleet segments where full electrification capital costs exceed operational budget cycles.
- Fuel Cell Electric:Hydrogen fuel cell systems with polymer electrolyte membranes target heavy-duty commercial applications where battery weight penalties reduce payload capacity. Fuel cell deployment concentrates around industrial zones in Jebel Ali where hydrogen supply infrastructure receives state-backed development support.
Battery electric absorbs the bulk of installed capacity; plug-in hybrid is expanding most quickly among commercial operators managing transitional infrastructure risk.
End User:
Procurement authority concentration determines contract scale and technical specification complexity across customer categories.
- Fleet Operators:Commercial vehicle aggregators managing 50+ unit fleets specify standardized drivetrain platforms to simplify maintenance training and parts inventory. Dubai's Roads and Transport Authority electrification mandates compress procurement cycles for approved suppliers serving taxi, delivery, and logistics segments.
- Government Agencies:Centralized procurement functions within Dubai's Green Mobility Strategy specify 10-year operating contracts bundling vehicles, charging infrastructure, and maintenance services. Government fleet renewal programs create guaranteed offtake volumes that anchor manufacturer regional investment decisions.
- Individual Consumers:Private buyers respond to total cost of ownership calculations where electricity-fuel price differentials and reduced maintenance requirements offset higher acquisition premiums. Individual demand concentrates in premium segments where Tesla's Supercharger network anchors brand positioning.
- Ride-Sharing Services:Platform operators with centralized vehicle procurement specify durability-optimized battery chemistries capable of sustaining high daily utilization rates exceeding 300 kilometers. Ride-sharing electrification aligns with Dubai's smart city initiatives targeting reduced urban emissions intensity.
Fleet operators command the largest contract values; government agencies are climbing the fastest as procurement quotas accelerate deployment timelines.
Battery Technology:
Cell chemistry selection directly determines thermal management requirements and warranty exposure in ambient temperatures exceeding 45°C.
- Lithium-ion:Nickel-manganese-cobalt and lithium iron phosphate cathode configurations deliver the energy density and cycle life required for commercial fleet duty cycles. Lithium iron phosphate variants gain share in Gulf markets due to improved thermal stability reducing cooling system complexity.
- Solid State:Ceramic electrolyte systems eliminate liquid thermal runaway risks while enabling higher energy densities; Dubai Electricity and Water Authority pilots prototype cells from Korean suppliers for fleet deployment evaluation. Solid state remains pre-commercial with certification timelines extending 8-14 months under ESMA protocols.
- Nickel-Metal Hydride:Mature chemistry with lower energy density serves mild hybrid applications where battery mass and cost constraints outweigh performance optimization requirements. Nickel-metal hydride production concentrates in Japanese and Chinese manufacturing facilities.
- Lead Acid:Flooded and absorbed glass mat configurations persist in auxiliary power applications and low-speed commercial vehicles where energy density requirements remain minimal. Lead acid dominates replacement battery aftermarket segments due to established recycling infrastructure.
Lithium-ion holds the dominant installed base; solid state is gaining share fastest among premium fleet operators prioritizing safety margins.
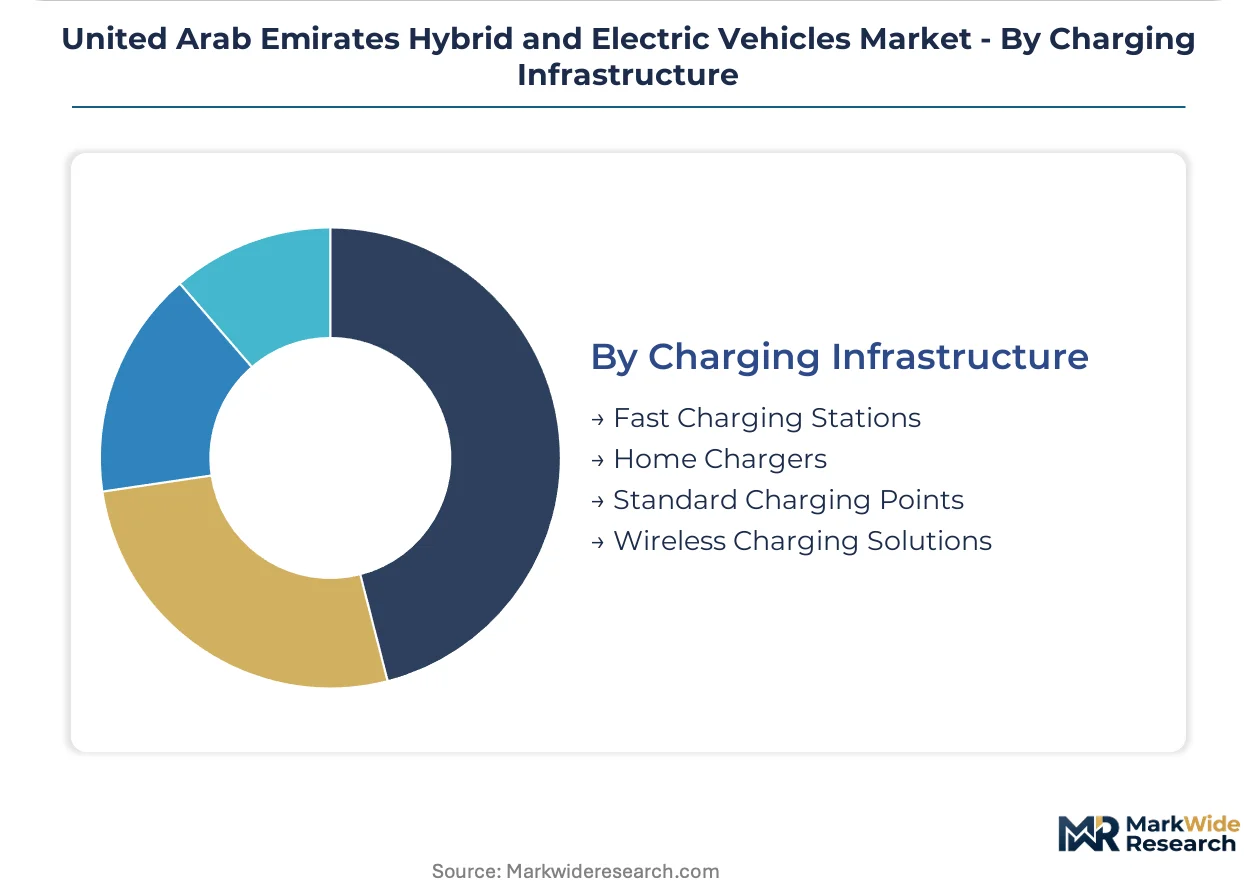
Charging Infrastructure:
Power delivery specifications and installation economics fragment infrastructure deployment across use cases and location types.
- Fast Charging Stations:DC rapid chargers delivering 150-350 kW enable sub-30-minute turnaround times required by commercial fleet operators. Fast charging deployment concentrates along Dubai-Abu Dhabi highway corridors and logistics hubs where vehicle utilization rates demand minimal downtime.
- Home Chargers:Level 2 AC charging equipment with 7-22 kW output serves individual consumers and small fleet operators with overnight dwell periods. Home charger installation rates track villa and townhouse construction in Dubai's suburban developments where dedicated parking enables electrical infrastructure upgrades.
- Standard Charging Points:Level 1 and Level 2 public installations with 3-22 kW output populate retail and workplace locations where dwell times exceed two hours. Standard charging receives municipal planning mandates in new commercial developments across Sharjah and Ras Al Khaimah.
- Wireless Charging Solutions:Inductive charging pads with automated alignment systems target premium fleet segments and autonomous vehicle applications where connector wear and vandalism risk deter plug-in infrastructure. Wireless systems remain limited to pilot deployments in Dubai's smart city test zones.
Fast charging stations absorb the majority of infrastructure capital; home chargers are expanding most quickly as residential electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement mandates from Dubai's Roads and Transport Authority concentrate demand in the emirate's commercial transport corridors, while Abu Dhabi's government-related entities anchor centralized electrification spending through long-term operating contracts.
Dubai
Dubai's Green Mobility Strategy 2030 requires 50% electrified vehicles in government fleets, creating guaranteed offtake volumes for approved suppliers. MOHAP's streamlined import certification protocols reduce homologation timelines for manufacturers meeting UN ECE R100 battery safety standards. Jebel Ali industrial zones host pilot deployments of hydrogen fuel cell systems where state-backed hydrogen supply infrastructure supports heavy-duty commercial applications.
Abu Dhabi
Abu Dhabi Department of Energy unified fast-charging specifications reduce deployment friction along commercial corridors connecting the capital to Dubai. Etihad Esco and Masdar joint ventures specify 10-year operating contracts bundling vehicles, charging infrastructure, and maintenance services for government-related entities. Yas Island and Saadiyat Island developments concentrate premium fleet electrification pilots targeting luxury hospitality and corporate mobility segments.
Sharjah
Underpenetrated logistics corridors in Sharjah present first-mover advantage for medium-duty electric truck deployment in last-mile commercial applications. Municipal planning mandates require standard charging installations in new commercial developments, accelerating network density in retail and workplace locations. Sharjah's industrial zones attract logistics operators seeking lower operational costs through electrified delivery fleets serving northern emirate markets.
Ras Al Khaimah
Ras Al Khaimah free zone incentives including zero customs duties on imported components and 15-year corporate tax holidays attract regional EV assembly investment. The emirate's lower land and labor costs support manufacturing operations targeting price-sensitive fleet segments across northern Emirates. Port infrastructure and proximity to Saudi border crossings position Ras Al Khaimah as a distribution hub for GCC-market vehicles.
Northern Emirates
Fujairah and Ajman residential developments drive home charger installation growth as villa and townhouse construction expands suburban electrification. Government fleet renewal programs in these emirates follow Dubai and Abu Dhabi procurement templates with scaled-down contract volumes. Northern Emirates logistics operators benefit from secondary charging network development along highway corridors connecting to major population centers.
United Arab Emirates Hybrid and Electric Vehicles Market Competitive Landscape
American producers anchor the premium-tier positioning through proprietary charging infrastructure and extended-range powertrain architectures; Chinese manufacturers hold cost-competitive volume segments through integrated battery production and scale manufacturing. The vendor base splits between vertically integrated technology specialists and regional assembly operations leveraging free-zone incentives. Three archetypes dominate: premium technology flagships, scale-driven cost leaders, and fleet-contract specialists. Competitive moves concentrate on strategic partnerships with local energy service companies and capacity expansion into GCC assembly operations.
Within the premium technology tier, Tesla leverages its Supercharger footprint to anchor brand positioning across Dubai and Abu Dhabi commercial corridors. Lucid Motors occupies a position targeting luxury fleet contracts through extended-range powertrain differentiation. BYD represents the scale-driven archetype, sustaining cost competitiveness through in-house battery production capabilities that reduce supply chain exposure to raw material volatility.
| Leading Market Players |
|---|
| BMW |
| Lucid Motors |
| Tesla |
| Kia |
| NIO |
| BYD |
| Mercedes-Benz |
| MG Motor |
| Hyundai |
| Others |
Value Network & Pricing Analysis
Premium-range powertrain certification tiers bifurcate the UAE electrified vehicle landscape, with UN ECE R100-compliant architectures commanding substantial positioning premiums while non-certified imports compete on stripped acquisition cost. This divergence manifests in parallel supply chain configurations: approved suppliers anchor Dubai government fleet contracts through integrated charging-maintenance bundles, while grey-market distributors serve price-sensitive northern emirate operators with minimal after-sales infrastructure.
Pricing Analysis
Volume shipments concentrate in mid-tier battery electric configurations where lithium iron phosphate cell chemistry enables competitive positioning, while margin capture resides in extended-range luxury architectures with proprietary fast-charging access. Price differentiation hinges on thermal management certification grade and bundled energy service contract duration. Cost compression in fleet procurement channels is intensifying as Etihad Esco and Masdar joint ventures consolidate demand under decade-long operating agreements. Individual consumers in Dubai's premium segments demonstrate lowest price sensitivity, prioritizing Supercharger network density over acquisition cost.
Supply Chain Analysis
ESMA battery safety validation and MOHAP import certification function as dual gating mechanisms that filter supplier participation, with extended timelines favoring incumbents with established regulatory affairs capabilities. Cell manufacturing concentrates in China, South Korea, and Japan, with Ningde and Shenzhen clusters supplying the majority of lithium iron phosphate capacity deployed in Gulf climate configurations. Raw material dependencies span lithium carbonate from South American salares, nickel from Indonesian processing facilities, and cobalt from Central African mining operations. Single-source vulnerability in Chinese cell supply creates exposure to export license disruptions. Distribution runs through Dubai-based fleet service companies that bundle vehicle procurement with charging infrastructure deployment and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE electrified vehicle sector sits at a battery chemistry transition phase, with solid-state ceramic electrolyte systems displacing liquid lithium-ion architectures in premium fleet evaluations. This technology inflection compresses legacy supplier margins while opening qualification windows for certified alternatives.
For Market Incumbents: To counter solid-state battery disruption from Korean suppliers, incumbents must secure backward integration into lithium iron phosphate cell production through Ras Al Khaimah free zone assembly partnerships. Thermal management R&D investment targeting 45°C ambient operation represents a critical certification lever for retaining Dubai Roads and Transport Authority fleet contracts.
For New Entrants and Emerging Players: The mid-fleet price-point gap between Tesla's premium positioning and BYD's economy scale creates white-space opportunity for regional assemblers targeting Sharjah's underpenetrated logistics corridors. First-mover advantage in medium-duty electric truck deployment, combined with vehicle-to-grid integration capabilities, offers a defensible go-to-market angle against established passenger vehicle competitors.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated battery-as-a-service providers given Dubai Green Mobility Strategy procurement quota acceleration. Long-term viability over a multi-year horizon favors operators with captive charging infrastructure and 10-year government contract backlogs. The signal to watch is ESMA certification timeline compression for solid-state architectures, which would trigger incumbent valuation recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium iron phosphate cell volumes from Chinese or Korean manufacturers for Gulf climate specifications. |
| Charging Infrastructure Partnership | Aligns with DEWA fast-charging specifications to accelerate network density along Dubai-Abu Dhabi corridors. |
| Geographic Manufacturing Footprint | Leverages Ras Al Khaimah free zone incentives for regional assembly targeting GCC market expansion. |
| Software-Defined Vehicle Investment | Enables fleet telematics integration and vehicle-to-grid bidirectional charging protocols for energy service contracts. |
| Platform Standardization | Reduces parts inventory complexity for fleet operators managing 50-plus unit electrified vehicle deployments. |
Research Methodology
Multi-period observation of fleet procurement volumes, charging infrastructure deployment rates, and battery chemistry adoption patterns anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors at Dubai government-related entities, and energy service company contract managers. Secondary validation drew from ESMA certification filings, DEWA infrastructure development disclosures, UN ECE R100 homologation records, and IHS Markit vehicle registration databases. Bottom-up fleet deployment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Input-output matrix framing structured the projection framework, with segmentation dimensions spanning vehicle propulsion architecture, battery chemistry tier, end-user procurement authority concentration, and charging infrastructure power delivery class. CAGRs were derived from trend extrapolation of fleet electrification mandates and infrastructure investment flows. Industry-specific forecast inputs incorporated lithium carbonate price cycle assumptions and ESMA certification timeline distributions for emerging battery technologies.
Inputs from government procurement disclosure databases and fleet operator contract announcements were available through the study window; gaps in real-time cell manufacturing cost data introduce uncertainty bands around battery pack pricing trajectories. Forecasts reflect documented assumptions regarding regulatory timeline adherence and raw material supply continuity. A model refresh is warranted upon material change in ESMA thermal runaway testing protocols or lithium export licensing restrictions from primary cell manufacturing jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Europe Mild Hybrid Vehicles Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
North America Mild Hybrid Vehicles Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
North America Micro Hybrid Vehicles Market
Hybrid Vehicles
Hydrogen Fuel Automotive Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market