
 North America Mild Hybrid Vehicles Market | 2026-2036
North America Mild Hybrid Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mild Hybrid Vehicles Market Analytics
Modular powertrain bundling is consolidating buyer choice around integrated 48-volt starter-generator systems rather than standalone component upgrades. Ford Motor Company leverages its truck-centric manufacturing scale to anchor mild hybrid offerings in the full-size pickup segment. General Motors competes through proprietary Ultium-derived power electronics that sustain margin capture across Cadillac and Chevrolet nameplates. Stellantis N.V. differentiates via multi-brand deployment of its eTorque architecture across Ram, Jeep, and Chrysler portfolios.
A mild hybrid vehicle integrates an electric motor and battery pack with an internal combustion engine to enable torque assist, energy recuperation, and engine-off coasting without sole electric propulsion capability; typical systems employ 48-volt lithium-ion batteries producing 10-20 kW of supplemental power. The primary purpose is reducing fuel consumption and CO₂ emissions through stop-start functionality and regenerative braking while avoiding the cost and weight penalties of full hybrid architectures. Gasoline fuel type configurations dominate volume given consumer familiarity and refueling infrastructure density across the United States and Canada. Start-stop system technology leads installations due to minimal incremental cost, though integrated starter generator platforms capture expanding share as automakers pursue greater electric assist bandwidth. Battery component suppliers occupy critical margin pools as cell chemistry shifts toward higher cycle-life formulations.
The EPA enforces Corporate Average Fuel Economy benchmarks that compel OEMs to deploy mild hybrid systems as compliance pathways, while Environment and Climate Change Canada administers parallel greenhouse gas regulations tightening through the decade. NHTSA safety standards for high-voltage systems additionally shape product design and technician certification requirements. California Air Resources Board zero-emission vehicle mandates create indirect pressure by establishing technology trajectory expectations that cascade into neighboring states through Section 177 adoption. Stakeholders must monitor how pending EPA rulemakings on particulate matter and greenhouse gas tailpipe limits recalibrate the cost-benefit calculus between mild hybrid investment and full electrification transitions.
Market Dynamics
The EPA's Corporate Average Fuel Economy standards are compressing product planning cycles, forcing OEMs to embed 48-volt mild hybrid architectures across vehicle classes faster than battery cost curves would otherwise justify.
Growth Catalysts
- EPA CAFE Standards:The agency's tightening fleet-average fuel economy benchmarks compel automakers to deploy mild hybrid systems as compliance pathways across light-duty truck segments.
- Great Lakes Manufacturing Corridor:Concentrated supplier ecosystems spanning Michigan, Ohio, and Ontario reduce logistics costs for 48-volt battery pack and power electronics integration.
- Commercial Fleet Electrification Mandates:Large logistics operators in the United States and Canada are embedding mild hybrid specifications into procurement criteria for medium-duty delivery vehicles.
Market Restraints
- Lithium-Ion Cell Cost Volatility:Raw material price swings for nickel and cobalt directly compress margins on 48-volt battery pack production.
- Single-Source Power Semiconductor Dependency:Integrated starter-generator inverters rely heavily on Asian-sourced IGBT and silicon carbide modules, creating supply concentration risk.
- Full Battery Electric Substitution Threat:Falling all-electric vehicle prices and expanding charging infrastructure in California and Quebec erode the total-cost-of-ownership advantage for mild hybrid architectures.
Strategic Opportunities
- Central Canadian Provinces:Environment and Climate Change Canada's federal purchase incentives for lower-emission commercial vehicles create underpenetrated demand in Alberta and Saskatchewan fleet markets.
- Dual-Voltage 12V/48V Convergence:Smart junction box architectures integrating legacy 12-volt loads with 48-volt propulsion assist open white space for tier-one electrical system suppliers.
- Section 177 State Adoption:California Air Resources Board zero-emission vehicle mandates cascading through northeastern and western states via regulatory harmonization create indirect technology trajectory pressure favoring electrified powertrains.
Industry Challenges
- High-Voltage Technician Certification Bottlenecks:NHTSA safety standards for 48-volt system servicing create training backlogs at dealer networks and independent repair facilities.
- Legacy Powertrain Integration Complexity:Engine control unit recalibration for stop-start functionality with existing automatic transmission shift logic demands extended validation cycles.
- Intellectual Property Licensing Friction:Patent thickets around belt-integrated starter-generator designs generate royalty disputes between tier-one suppliers and OEM captive powertrain divisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mild Hybrid Vehicles Market |
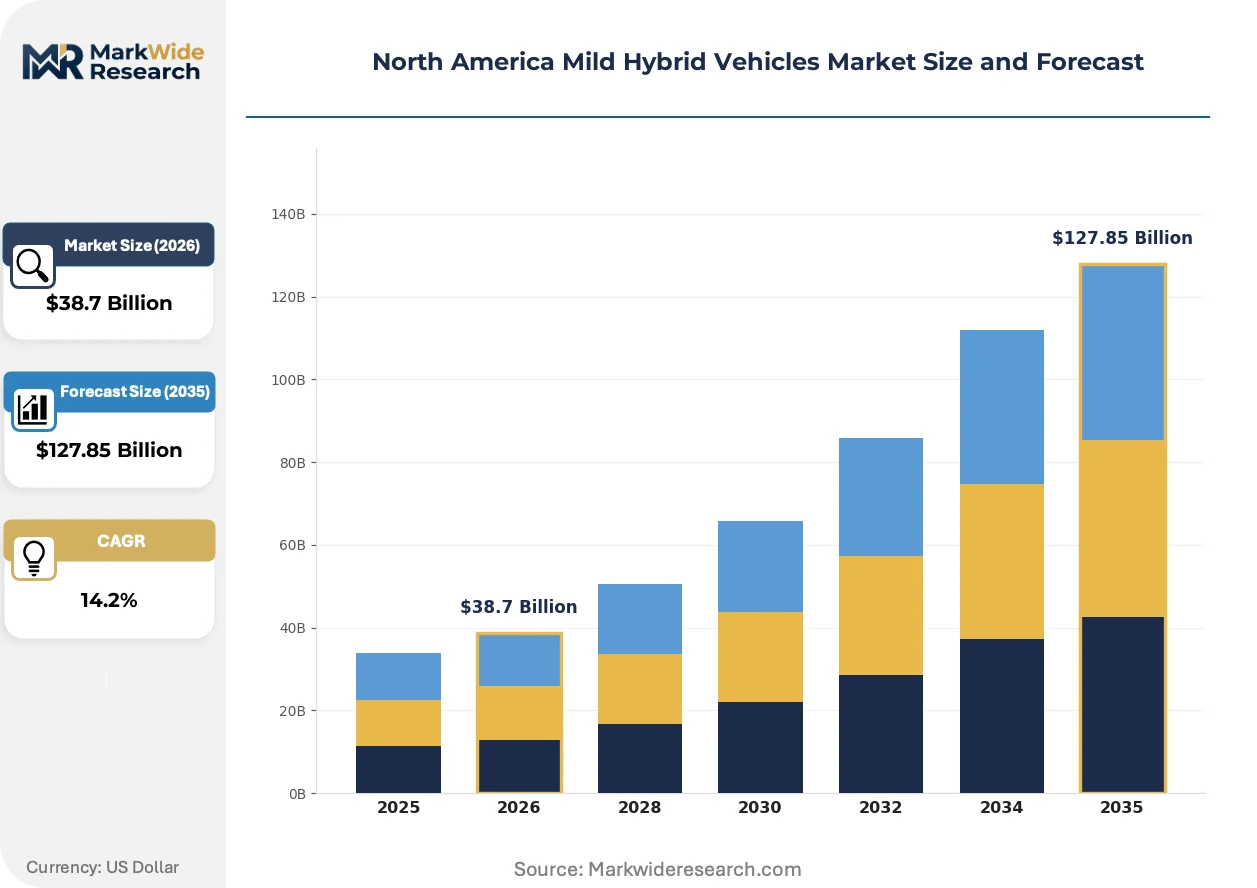
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Gasoline, Diesel, Ethanol, Others Component: Battery, Electric Motor, Transmission, Power Electronics Vehicle Type: SUV, Sedan, Hatchback, Coupe Technology: Start-Stop System, Regenerative Braking, Integrated Starter Generator, Electric Supercharger |
| Companies Covered | Honda Motor Co., Ltd., BMW AG, Ford Motor Company, Stellantis N.V., Mercedes-Benz Group AG, General Motors Company, Nissan Motor Co., Ltd., Hyundai Motor Company, Toyota Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mild Hybrid Vehicles Market Evolving Landscape
Powertrain electrification is fragmenting across voltage tiers, with 48-volt architectures carving out durable positioning between conventional internal combustion and full hybrid systems through modular cost engineering.
Integrated starter-generator technology is overtaking standalone belt-driven alternator-starter units in new vehicle programs. The integrated design mounts directly to the crankshaft, enabling torque-fill during gear shifts and extended engine-off coasting. Fleet buyers in the United States commercial van segment are specifying integrated systems at accelerating rates. This architecture is overtaking discrete component strategies by collapsing multiple functions into single hardware sets that reduce assembly complexity.
Environment and Climate Change Canada's greenhouse gas regulations for light-duty vehicles are tightening through model year 2035, creating parallel compliance pressure to EPA rules. The Canadian standards apply fleet-average CO₂ limits that favor mild hybrid deployment in pickup and SUV categories where full electrification remains cost-prohibitive. Manufacturers are responding by pre-homologating 48-volt systems for simultaneous United States and Canadian certification.
Aftermarket service unbundling is disrupting traditional dealer maintenance revenue streams. Independent repair networks in Texas and Florida are acquiring 48-volt diagnostic equipment faster than OEM authorized channels, capturing brake regeneration system servicing. Fleet operators with centralized maintenance facilities are bypassing dealer networks entirely for high-voltage battery health monitoring. This pattern is most visible in long-haul trucking corridors where uptime metrics override brand loyalty.
North America Mild Hybrid Vehicles Market Segmentation
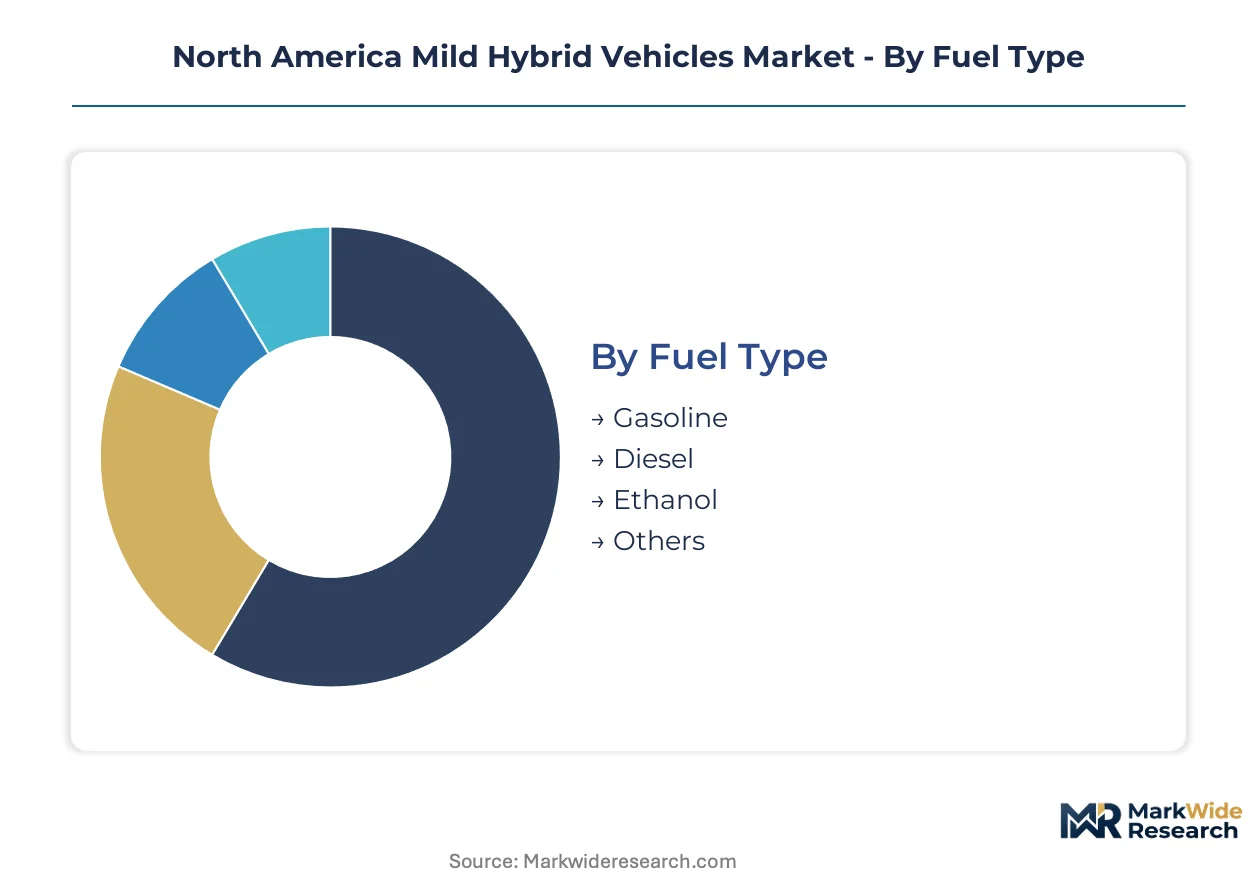
Mild hybrid architectures fragment across fuel types, component configurations, vehicle classes, and electrification technologies. Each dimension shapes cost structures, regulatory compliance pathways, and fleet procurement criteria differently across the United States and Canada.
Fuel Type:
Gasoline dominates absolute volume while diesel commands premium positioning in commercial applications.
- Gasoline:Four-cylinder and V6 configurations integrate 48-volt systems most cost-effectively. Demand concentrates in full-size pickup trucks across Michigan, Ohio, and Texas where EPA CAFE compliance pressures intersect with consumer price sensitivity.
- Diesel:Compression-ignition engines pair with mild hybrid assist for torque-fill during low-RPM operation. Fleet operators in Alberta and Saskatchewan specify diesel mild hybrids for medium-duty commercial routes where towing capacity requirements persist.
- Ethanol:Flex-fuel powertrains with mild hybrid integration serve Corn Belt agricultural logistics corridors.
- Others:Compressed natural gas and propane configurations occupy niche municipal fleet procurement in California and Quebec.
Today's leader: Gasoline. Tomorrow's challenger: Diesel.
Component:
Margin capture concentrates upstream in energy storage and power conversion subsystems.
- Battery:Lithium-ion cell chemistry dominates 48-volt architectures. Suppliers in the Great Lakes corridor manufacture packs with nickel-manganese-cobalt formulations for cycle-life optimization in stop-start duty cycles.
- Power Electronics:DC-DC converters and inverter modules determine system efficiency. Ontario-based suppliers specialize in silicon carbide semiconductor integration for thermal management in integrated starter-generator applications.
- Electric Motor:Belt-driven and crankshaft-mounted machines provide 10-20 kW supplemental output.
- Transmission:Torque converter lockup strategies recalibrate for engine-off coasting functionality.
Today's anchor: Battery. Tomorrow's margin driver: Power Electronics.
Vehicle Type:
Light truck platforms absorb the majority of 48-volt system installations.
- SUV:Three-row and compact utility vehicles deploy mild hybrid systems for stop-start refinement. California and Texas registrations lead volume as CARB-aligned states and oil-patch fleet operators converge on electrified light trucks.
- Sedan:Mid-size four-door configurations integrate 48-volt architectures for incremental efficiency gains. Ontario and Ohio manufacturing plants prioritize sedan mild hybrid lines for corporate fleet contracts.
- Hatchback:Compact five-door segments in Quebec and British Columbia adopt mild hybrid assist for urban delivery applications.
- Coupe:Performance-oriented two-door variants leverage electric supercharger integration for transient torque boost.
Today's volume center: SUV. Tomorrow's efficiency battleground: Sedan.
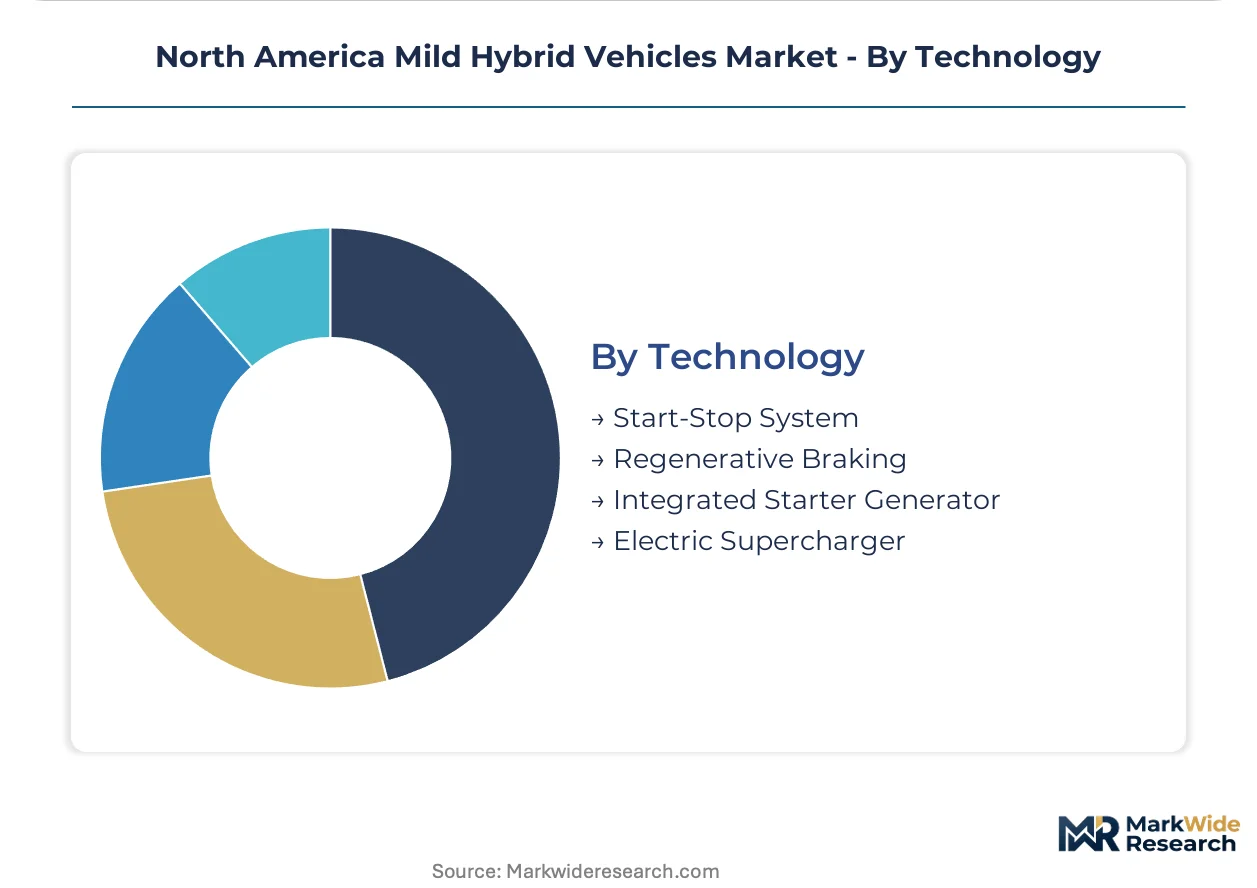
Technology:
System complexity escalates from discrete stop-start modules toward integrated crankshaft-mounted architectures.
- Start-Stop System:Discrete starter motor and enhanced battery configurations enable engine shutdown at idle. Cost minimization drives adoption in entry-level compact SUVs assembled in Mexico for United States distribution.
- Integrated Starter Generator:Crankshaft-mounted machines enable torque-fill during transmission shifts and extended coasting. Fleet specifications in the Great Lakes logistics corridor increasingly mandate this architecture for fuel economy validation.
- Regenerative Braking:Brake energy recuperation modules capture deceleration energy for 48-volt battery replenishment.
- Electric Supercharger:Belt-driven compressor systems eliminate turbo lag in performance applications.
Today's baseline: Start-Stop System. Tomorrow's standard: Integrated Starter Generator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mild hybrid vehicle development traces its commercial scaling to Detroit's post-2008 restructuring, when Ford and General Motors first embedded belt-alternator-starter systems into full-size truck platforms to meet early EPA fuel economy benchmarks.
United States
Full-size pickup fleets and commercial logistics operators drive system installations across Texas and Michigan. EPA Corporate Average Fuel Economy standards tighten through model year 2035, compelling OEMs to deploy 48-volt architectures across light-duty truck segments. The Great Lakes manufacturing corridor spanning Detroit, Toledo, and Flint concentrates battery pack assembly and power electronics integration.
Canada
Alberta and Saskatchewan fleet operators specify diesel mild hybrid configurations for medium-duty commercial routes. Environment and Climate Change Canada administers greenhouse gas regulations parallel to EPA benchmarks, favoring 48-volt deployment in pickup categories. Ontario's automotive supplier ecosystem in Windsor and Oshawa manufactures lithium-ion cells for cross-border vehicle programs.
Mexico
Export-oriented assembly plants in Nuevo León and the Bajío Region integrate mild hybrid systems for United States-bound compact SUVs. Mexican automotive manufacturing serves as a cost-optimized production node for entry-level 48-volt stop-start configurations. The Querétaro and Guanajuato industrial corridors house tier-one electrical component suppliers serving North American OEMs.
North America Mild Hybrid Vehicles Market Competitive Landscape
The competitive structure tilts toward diversified automotive conglomerates with captive powertrain divisions. Market concentration remains high among Detroit Three and multinational OEMs with established truck manufacturing scale. Two strategic archetypes dominate: integrated manufacturers controlling full powertrain development and brand-diversified groups deploying shared architectures across multiple nameplates. Capacity expansion in 48-volt battery pack assembly and strategic partnerships for semiconductor sourcing represent the prevailing competitive moves.
Within the integrated manufacturer tier, Ford Motor Company and General Motors occupy positions defined by truck-centric manufacturing heritage and proprietary power electronics development. Stellantis N.V. exemplifies the brand-diversified archetype, leveraging multi-brand deployment strategies across its portfolio. Honda Motor Co., Ltd. and Toyota Motor Corporation represent Japanese-origin competitors with hybrid technology lineages extending into mild hybrid adaptations for North American truck and SUV segments.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| BMW AG |
| Ford Motor Company |
| Stellantis N.V. |
| Mercedes-Benz Group AG |
| General Motors Company |
| Nissan Motor Co., Ltd. |
| Hyundai Motor Company |
| Toyota Motor Corporation |
| Others |
Value Network & Pricing Analysis
Fleet procurement mandates for integrated starter-generator specifications across commercial logistics operators force battery pack suppliers to consolidate 48-volt manufacturing in the Great Lakes corridor, compressing margins on nickel-manganese-cobalt cell formulations while elevating pricing power for silicon carbide semiconductor specialists in Ontario.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated starter-generator architectures from discrete stop-start modules and bare alternator-starter units. Price differentiation hinges on EPA CAFE certification tier and volume procurement scale from fleet operators. Cost compression in entry-level stop-start configurations is intensifying because Mexican assembly plants optimize for United States-bound compact SUV programs. Commercial fleet buyers in Alberta and Saskatchewan demonstrate lowest price sensitivity due to total-cost-of-ownership calculations, while individual consumers in Texas and Florida drive hardest bargain on sticker price.
Supply Chain Analysis
Single-source vulnerability sits with Asian-sourced IGBT and silicon carbide power modules for integrated starter-generator inverters. Geographic supply concentration centers on South Korea, Japan, and Taiwan for semiconductor fabrication, with China and Australia feeding lithium carbonate and nickel sulfate inputs. Supply chain risk manifests as tariff exposure on battery cell materials crossing United States-Canada border under USMCA rules of origin. Distribution runs through captive OEM channels and tier-one electrical system suppliers serving the Detroit Three manufacturing footprint.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America mild hybrid vehicles market functions as a stable compounder anchored by EPA CAFE standards that tighten through model year 2035, ensuring sustained OEM procurement of 48-volt architectures regardless of battery cost curve trajectories.
For Market Incumbents: Cement dominance in full-size pickup truck platforms by securing long-term lithium-ion cell offtake agreements with Great Lakes corridor suppliers before Environment and Climate Change Canada tightens parallel greenhouse gas regulations. Prioritize backward integration into silicon carbide semiconductor sourcing to offset single-source dependency on Asian IGBT modules that threatens margin stability. For New Entrants and Emerging Players: Independent repair networks in Texas and Florida present the most penetrable channel for 48-volt diagnostic equipment and battery health monitoring services, as fleet operators bypass dealer networks for uptime-critical maintenance. Target medium-duty commercial van specifications in the Great Lakes logistics corridor where integrated starter-generator mandates are accelerating fastest. For Investors and Strategic Acquirers: Asymmetric upside sits with tier-one electrical system suppliers controlling dual-voltage 12V/48V smart junction box architectures. Long-term viability rests on five-to-ten year regulatory compliance windows rather than consumer preference shifts, favoring acquisition targets with EPA and Environment and Climate Change Canada pre-homologation capabilities. Watch for inflection signals in California Air Resources Board rulemakings that cascade through Section 177 state adoption patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Ford and General Motors consolidate 48-volt architectures across truck and SUV nameplates to amortize development costs. |
| Battery Supply Agreement | Long-term lithium-ion cell contracts with Ontario-based suppliers secure capacity for cross-border United States-Canada vehicle programs. |
| Software-Defined Vehicle Investment | Engine control unit recalibration for stop-start functionality demands extended validation cycles and over-the-air update capability. |
| Geographic Manufacturing Footprint | Mexican assembly plants in Nuevo León optimize cost structures for entry-level 48-volt stop-start configurations. |
| Charging Infrastructure Partnership | Fleet operators in Alberta and Saskatchewan specify diesel mild hybrid configurations independent of electric vehicle charging networks. |
Research Methodology
Direct dialogue with OEM platform engineers, tier-one electrical system procurement leads, fleet operator maintenance directors, and aftermarket diagnostic equipment distributors grounded qualitative findings in operational reality. Secondary validation drew from EPA CAFE rulemaking dockets, Environment and Climate Change Canada greenhouse gas regulatory filings, IHS Markit vehicle registration databases, and United States-Canada customs trade records. Bottom-up build of 48-volt system installations by vehicle class converged with top-down OEM production planning disclosures through iterative triangulation.
Segmented outputs across fuel type, component subsystem, vehicle class, and electrification technology dimensioned the analytical framework over the projection horizon. CAGRs were derived from regression against EPA compliance pathway modeling and fleet procurement trend extrapolation. Industry-specific forecast inputs incorporated lithium-ion cell chemistry evolution timelines and integrated starter-generator adoption curves in commercial van segments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to California Air Resources Board zero-emission vehicle mandate stringency and full battery electric vehicle price parity achievement in Quebec and California. Forecasts reflect documented assumptions about regulatory trajectory persistence and raw material cost stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Hydrogen Fuel Automotive Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Hybrid Truck Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Hypercar Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market