
 Hydrogen Fuel Automotive Market | 2026-2036
Hydrogen Fuel Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Fuel Automotive Market Insights
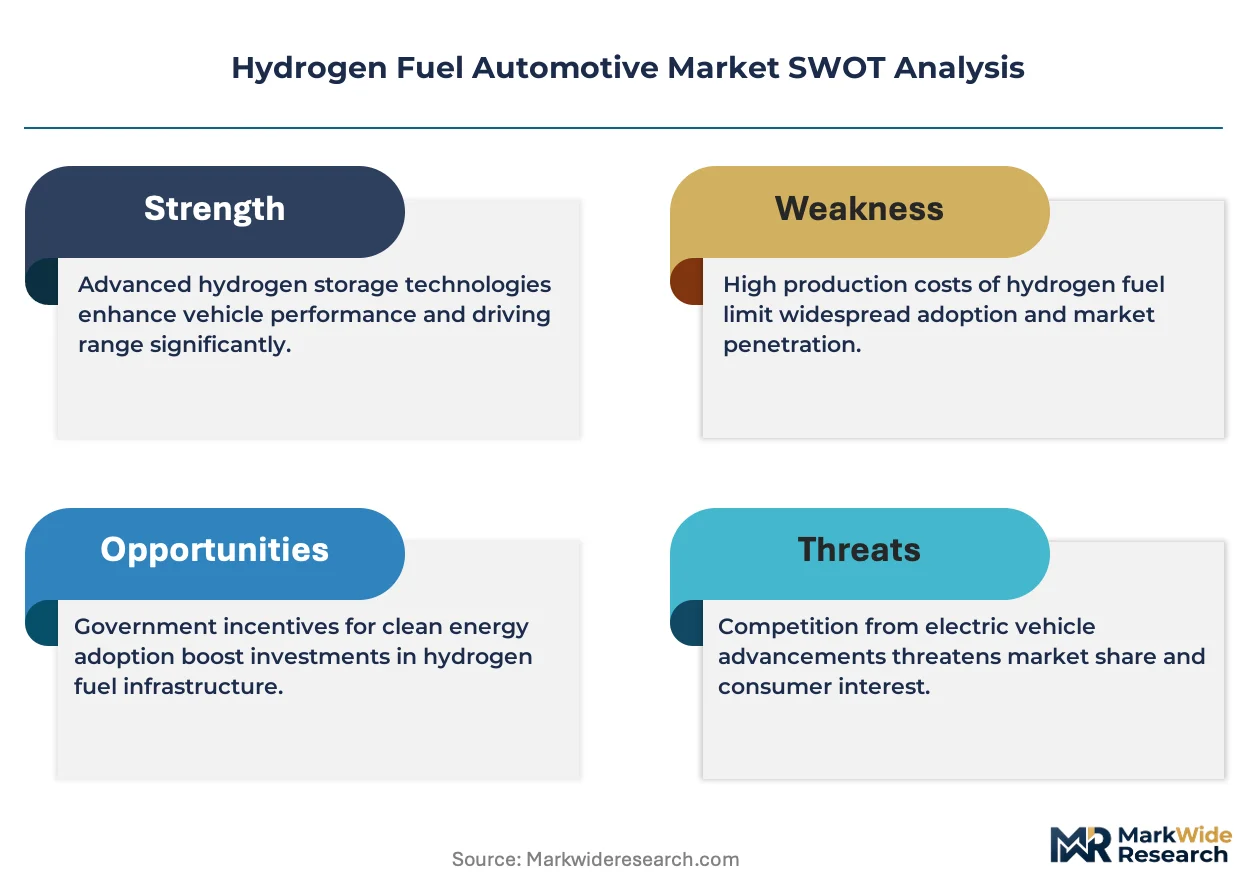
Automotive-grade fuel cell certification standards are bifurcating the competitive landscape into proven reliability tiers and emerging cost-optimized alternatives. Toyota Motor Corporation leverages its multi-generational Mirai platform to sustain technology leadership in passenger fuel cell systems. Hyundai Motor Group anchors its position through integrated heavy-duty truck fuel cell production at dedicated Korean manufacturing complexes. Ballard Power Systems specializes in commercial vehicle powertrains and competes aggressively on stack durability metrics for bus and truck applications.
Hydrogen fuel automotive technology converts gaseous hydrogen through polymer electrolyte membrane fuel cells into electrical energy, with systems typically operating at 60-80% efficiency and requiring 350-700 bar compressed hydrogen storage tanks. The primary commercial purpose centers on zero-emission transportation for weight-sensitive and long-range duty cycles where battery electrification imposes payload or charging time penalties. Heavy-duty trucks dominate current fuel cell stack shipments due to fleet operators prioritizing route flexibility over infrastructure density. Corporate fleet procurement channels capture the strongest margin pools as volume buyers negotiate service-level agreements encompassing hydrogen supply and maintenance. Passenger cars remain a maturing segment where government subsidies determine near-term uptake velocity.
The EPA tailpipe emission standards and NHTSA fuel economy regulations in the United States create compliance value for zero-emission vehicle credits traded across manufacturer portfolios. Japan's METI coordinates hydrogen station certification under JIS standards that dictate refueling protocol compatibility and safety interlock specifications. The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in fuel cell manufacturing, pressuring suppliers toward alternative membrane chemistries. Stakeholders must monitor hydrogen production source certification schemes as lifecycle carbon intensity thresholds harden across major automotive markets.
Market Dynamics
The hydrogen fuel automotive market pivots on the tension between heavy-duty fleet electrification mandates and the capital intensity of hydrogen production infrastructure. California's Advanced Clean Trucks regulation forces freight operators toward zero-emission powertrains before charging networks can support battery-electric long-haul routes.
Growth Catalysts
- California's Advanced Clean Trucks regulation:Mandates escalating zero-emission truck sales percentages, creating guaranteed demand pull for fuel cell powertrains in drayage and regional freight corridors.
- German National Hydrogen Strategy:Directs public capital into automotive fuel cell manufacturing clusters, compressing supplier development timelines through shared testing facilities.
- Heavy-duty trucking fleets:Prioritize route flexibility and payload preservation, selecting hydrogen systems where battery weight erodes cargo capacity below operational thresholds.
Market Restraints
- Electrolyzer capacity concentration:Green hydrogen production equipment manufacturing clusters in China and Germany, creating supply bottlenecks for station deployment elsewhere.
- Platinum group metal loadings:Fuel cell membrane electrode assemblies require iridium and platinum at volumes that amplify stack cost volatility against battery pack price declines.
- EU F-Gas Regulation:Restricts fluorinated gas use in fuel cell manufacturing, forcing membrane chemistry transitions that extend qualification timelines for automotive suppliers.
Strategic Opportunities
- Japan's METI subsidy acceleration:Expands fuel cell vehicle purchase incentives and station deployment targets, opening passenger car volume channels previously constrained by infrastructure gaps.
- Corporate fleet procurement:Aggregated buying through service-level agreements encompassing hydrogen supply and maintenance captures margin pools unavailable in fragmented retail sales.
- Polymer electrolyte membrane convergence with electrolysis:Shared catalyst and membrane advances across fuel cell and hydrogen production equipment compress R&D amortization for dual-use suppliers.
Industry Challenges
- Automotive-grade fuel cell certification:JIS and UN ECE R134 testing protocols demand 5,000+ hour durability validation, extending product launch timelines beyond battery-electric alternatives.
- Hydrogen station technician training:700-bar compressed hydrogen handling certification programs remain sparse, constraining maintenance network expansion for commercial vehicle deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Fuel Automotive Market |
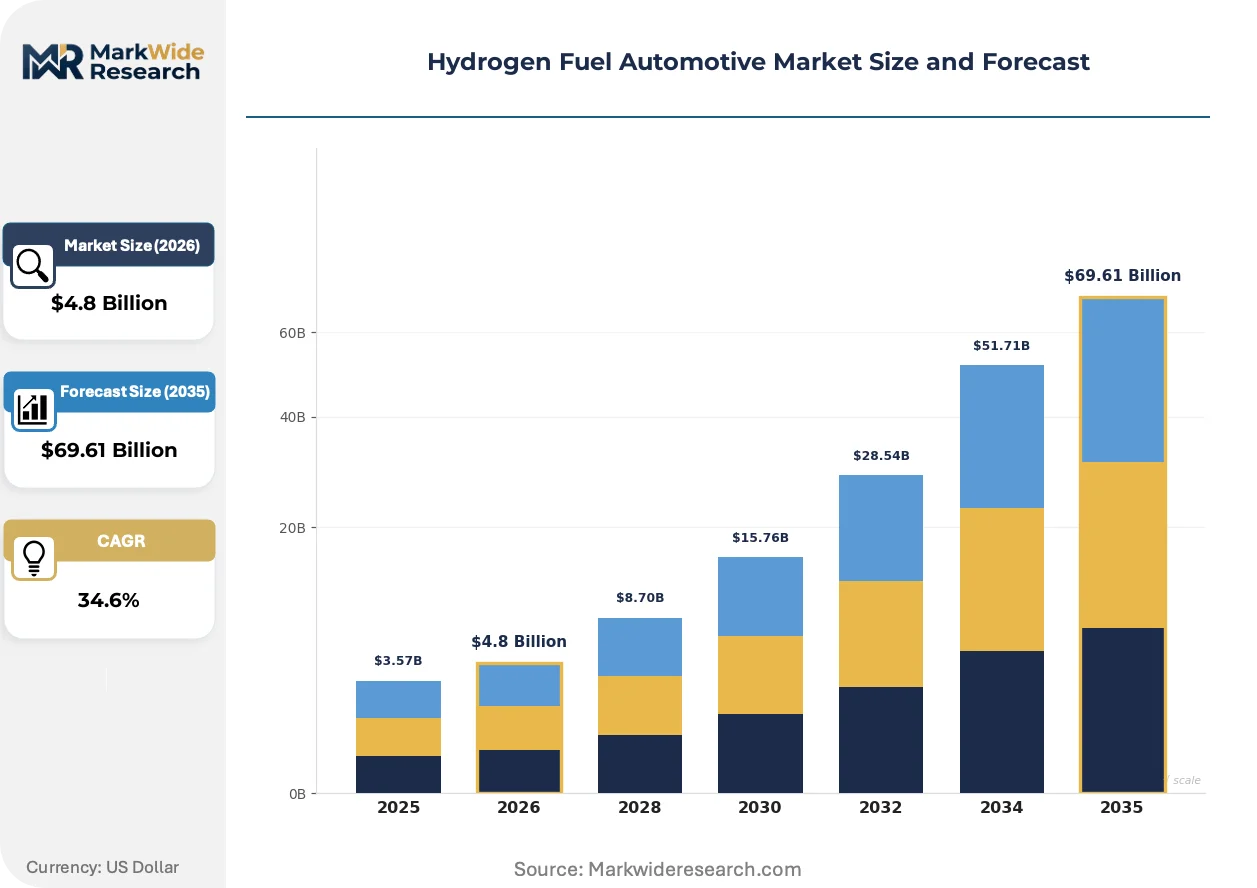
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $69.61 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
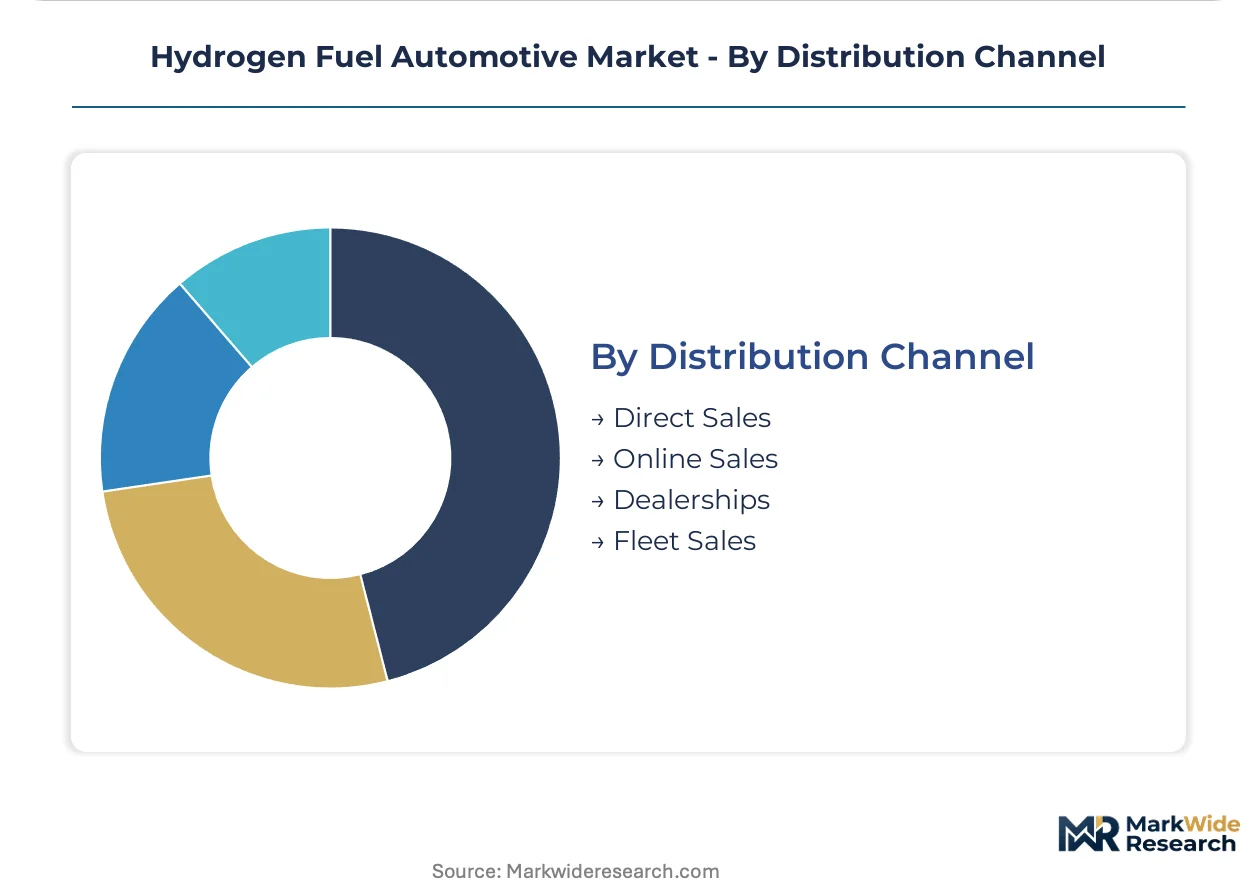
| Segmentation | Vehicle Type: Passenger Cars, Heavy-Duty Trucks, Buses, Motorcycles Component: Fuel Cell Stack, Hydrogen Storage, Power Control Unit, Electric Motor End User: Government, Corporate Fleets, Transportation Services, Private Individuals Distribution Channel: Direct Sales, Online Sales, Dealerships, Fleet Sales |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Group, Honda Motor Co., Ltd., Daimler AG, General Motors, BMW AG, Ballard Power Systems, Plug Power Inc., Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Fuel Automotive Market Trends and Innovations
Active reshaping in hydrogen automotive technology centers on stack architecture compression, regulatory chemistry constraints, and fleet procurement model evolution. These forces are compressing supplier margins while opening new service revenue channels.
High-pressure hydrogen storage tank manufacturing is miniaturizing carbon fiber winding patterns to reduce vessel wall thickness without sacrificing 700-bar safety margins. Commercial vehicle OEMs are adopting these lighter tanks for Class 8 tractors where every kilogram of storage system weight displaces freight revenue. The technology is miniaturizing the spatial footprint of onboard hydrogen systems, enabling roof-mount configurations that preserve frame rail space for battery hybridization.
The EU F-Gas Regulation is banning perfluorinated compounds in fuel cell membrane manufacturing, forcing suppliers toward hydrocarbon-based proton exchange materials. German and Korean stack producers are accelerating alternative ionomer qualification to maintain CE marking eligibility for European truck deployments. Passenger car segments face compressed timelines as the regulation's phase-down schedule outpaces current membrane development cycles.
Fleet operators are consolidating hydrogen procurement through long-term offtake agreements bundled with powertrain maintenance, displacing spot-market hydrogen purchasing. California freight carriers and German logistics groups are negotiating directly with electrolyzer developers for green hydrogen supply certainty. This pattern concentrates buyer power among volume accounts and marginalizes retail station networks in early deployment regions.
Hydrogen Fuel Automotive Market Segmentation
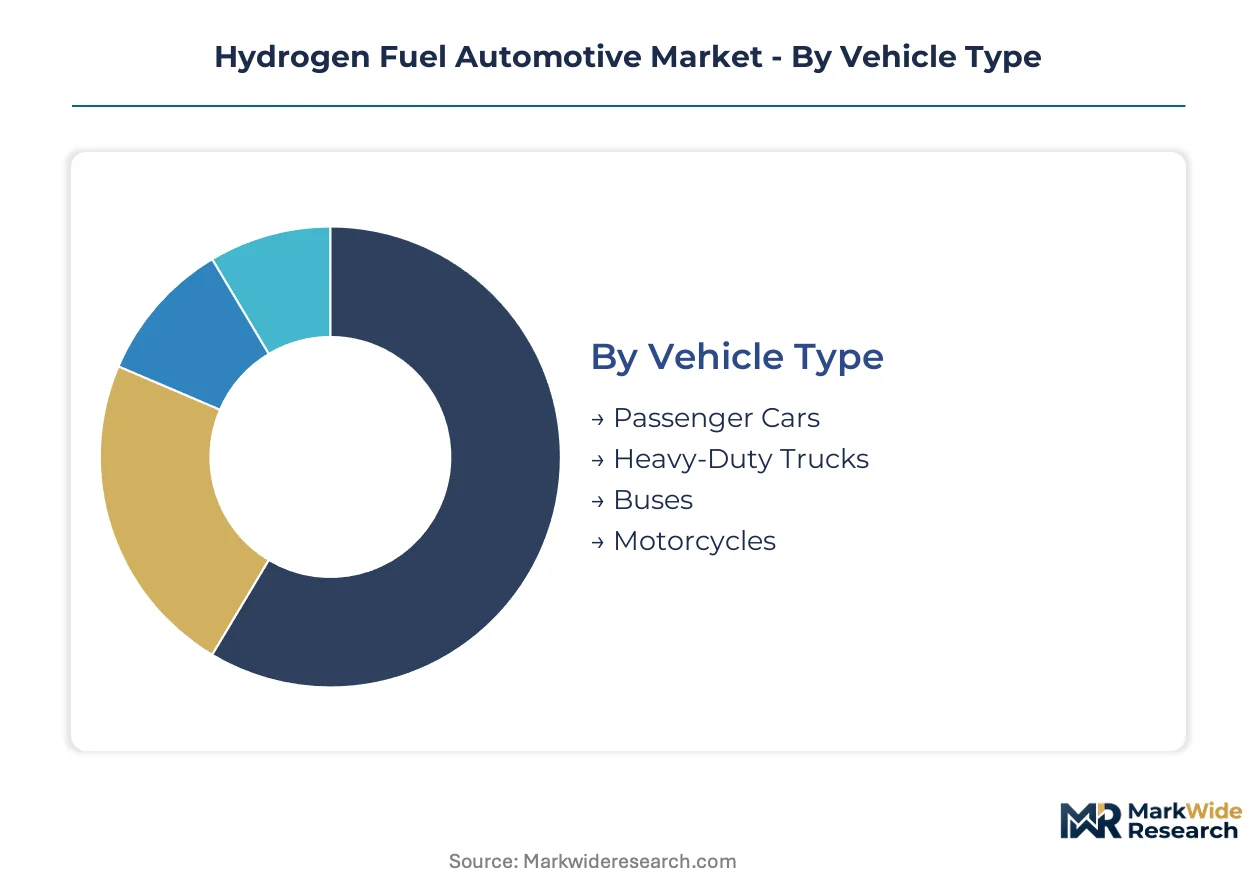
Segmentation in hydrogen fuel automotive markets reveals how procurement channels, component durability requirements, and fleet ownership structures reshape supplier strategies. Each dimension exposes distinct margin pools and certification barriers that separate proven automotive-grade suppliers from emerging cost-optimized entrants.
Vehicle Type:
Channel-mix patterns diverge sharply across vehicle categories, with heavy-duty platforms flowing through fleet procurement contracts while passenger cars rely on subsidized retail channels.
- Heavy-Duty Trucks:Class 8 tractors and regional freight vehicles deploy 100-200 kW fuel cell stacks with 700-bar composite storage systems. Demand concentrates in California drayage corridors and German logistics clusters where payload preservation overrides infrastructure density concerns. The Advanced Clean Trucks regulation forces fleet electrification timelines faster than battery-electric charging networks can support.
- Passenger Cars:Sedans and SUVs integrate 90-130 kW polymer electrolyte membrane systems with 5-6 kg hydrogen capacity delivering 500-650 km range. METI subsidies in Japan and German purchase incentives determine uptake velocity where station coverage remains sparse. Private buyers prioritize refueling convenience against battery charging downtime.
- Buses:Transit authorities specify 60-85 kW stacks for fixed-route urban service with depot-based hydrogen supply. Procurement runs through municipal tender processes with 12-year durability requirements.
- Motorcycles:Two-wheelers deploy compact 1-5 kW fuel cell range extenders targeting commercial delivery fleets in dense Asian urban cores.
By volume, Heavy-Duty Trucks leads. By growth pace, Passenger Cars is climbing the fastest as station deployment accelerates under national hydrogen strategies.
Component:
Cost tier stratification separates membrane electrode assemblies commanding premium pricing from balance-of-plant components facing commoditization pressure.
- Fuel Cell Stack:The electrochemical core contains membrane electrode assemblies, bipolar plates, and sealing gaskets operating at 80-95°C. Platinum and iridium loadings above 0.3 mg/cm² concentrate supply with Korean and German stack producers. UN ECE R134 durability validation demands 5,000+ hour automotive-grade certification.
- Hydrogen Storage:Type IV carbon fiber-wrapped pressure vessels store 350-700 bar compressed hydrogen with aluminum or polymer liners. Tank weight reduction below 5 kg/kg H₂ enables roof-mount configurations preserving frame rail space. Manufacturing clusters in Germany and Japan supply European and Asian OEM assembly lines.
- Power Control Unit:DC-DC converters and inverters manage voltage transformation between stack output and electric motor demand. Silicon carbide semiconductor adoption reduces switching losses in next-generation systems.
- Electric Motor:Permanent magnet synchronous motors deliver 200-400 kW peak output with liquid cooling circuits integrated into fuel cell thermal management.
By margin contribution, Fuel Cell Stack dominates. By supply expansion, Hydrogen Storage is gaining share fastest as tank manufacturing scales for commercial vehicle programs.
End User:
Customer type determines contract structure, with corporate aggregators negotiating service-level agreements that bundle hydrogen supply with maintenance.
- Corporate Fleets:Freight operators and logistics groups negotiate long-term offtake agreements directly with electrolyzer developers. California freight carriers and German distribution networks consolidate procurement power through aggregated buying. Service-level agreements spanning hydrogen supply, stack refurbishment, and technician training capture margin pools unavailable in fragmented retail.
- Government:Transit authorities and municipal procurement offices specify 12-year stack durability with localized maintenance support. Tender processes prioritize total cost of ownership over upfront capital expenditure.
- Transportation Services:Ride-hail and taxi operators demand rapid refueling turnaround incompatible with battery charging schedules. Fleet utilization rates above 80% justify hydrogen infrastructure investment.
- Private Individuals:Retail buyers respond to purchase subsidies and station availability with price sensitivity to total cost of ownership against battery-electric alternatives.
By contract value, Corporate Fleets leads. By subsidy dependence, Private Individuals shows steepest expansion trajectory where national hydrogen strategies accelerate station deployment.
Distribution Channel:
Volume concentration favors direct sales for commercial platforms while passenger segments fragment across dealership networks.
- Fleet Sales:Dedicated commercial vehicle divisions negotiate enterprise contracts with customized hydrogen supply arrangements. California and German freight operators bypass retail station networks through direct electrolyzer offtake agreements. Procurement teams specify stack durability guarantees and maintenance response times.
- Direct Sales:OEM-owned channels for passenger fuel cell vehicles concentrate in Japan and Korea where manufacturer-operated showrooms control brand positioning. METI-coordinated station deployment aligns with direct sales territory planning.
- Dealerships:Independent retail networks require 700-bar technician certification programs that remain sparse outside early deployment regions. Margin compression limits dealer enthusiasm where service revenue potential is uncertain.
- Online Sales:Digital configuration tools support corporate fleet pre-ordering with delivery scheduling tied to hydrogen infrastructure readiness.
By transaction size, Fleet Sales leads. By channel development investment, Direct Sales is expanding most quickly as OEMs integrate hydrogen supply into ownership experience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean fuel cell stack manufacturers export heavily to California freight operators and German logistics clusters, establishing the dominant trade corridor in heavy-duty hydrogen powertrains.
United States
California's Advanced Clean Trucks regulation mandates escalating zero-emission truck sales percentages, forcing drayage and regional freight operators toward fuel cell systems. The EPA tailpipe emission standards and NHTSA fuel economy regulations create compliance value for zero-emission vehicle credits traded across manufacturer portfolios. The Los Angeles-Long Beach port complex anchors North American fuel cell truck deployment with dedicated hydrogen corridors under construction.
Germany
The National Hydrogen Strategy directs public capital into automotive fuel cell manufacturing clusters, compressing supplier development timelines through shared testing facilities. The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in fuel cell manufacturing, pressuring suppliers toward alternative membrane chemistries. The Bavarian industrial corridor hosts concentrated stack production and carbon fiber tank manufacturing for European OEM assembly lines.
Japan
METI accelerated fuel cell vehicle subsidies and hydrogen station deployment targets, expanding passenger car volume channels previously constrained by infrastructure gaps. JIS standards dictate refueling protocol compatibility and safety interlock specifications for station certification. The Kanto region around Tokyo maintains the densest hydrogen station network globally, supporting manufacturer-operated direct sales channels.
South Korea
Integrated heavy-duty truck fuel cell production at dedicated domestic manufacturing complexes anchors Hyundai Motor Group's commercial vehicle export strategy. The country's national hydrogen regulator coordinates electrolyzer capacity expansion to support both domestic demand and stack component exports. The Busan-Ulsan industrial belt concentrates membrane electrode assembly production and bipolar plate fabrication for regional supply.
China
Electrolyzer capacity concentration in Chinese manufacturing clusters creates supply bottlenecks for station deployment elsewhere, constraining green hydrogen availability for automotive applications. The MIIT oversees fuel cell vehicle demonstration programs in select provinces with subsidy support for bus and truck fleets. The Yangtze River Delta hosts emerging carbon fiber tank production scaling for domestic commercial vehicle programs.
Hydrogen Fuel Automotive Market Competitive Landscape
Listed leaders compete with private specialists across fuel cell stack durability tiers, creating a bifurcated structure where proven automotive-grade certification separates premium suppliers from cost-optimized entrants. The market concentrates around three strategic archetypes: integrated automotive OEMs with multi-generational platforms, dedicated fuel cell powertrain specialists, and diversified industrial conglomerates leveraging electrolyzer synergies. Competitive moves center on backward integration into membrane electrode assembly production and captive hydrogen supply agreements with fleet operators.
Within the integrated OEM tier, Toyota Motor Corporation and Hyundai Motor Group exemplify multi-generational platform strategies spanning passenger and commercial vehicle segments. Ballard Power Systems occupies a specialist position focused on commercial vehicle powertrains with emphasis on stack durability metrics for bus and truck applications. These three anchors represent distinct competitive vectors: platform breadth, vertical integration depth, and application-specific specialization.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Group |
| Honda Motor Co., Ltd. |
| Daimler AG |
| General Motors |
| BMW AG |
| Ballard Power Systems |
| Plug Power Inc. |
| Cummins Inc. |
| Others |
Pricing and Supply Chain Analysis
Hydrocarbon-based proton exchange membrane chemistry displaces perfluorinated ionomers under EU F-Gas Regulation phase-down schedules, simultaneously relocating membrane electrode assembly production toward German and Korean qualification facilities and compressing pricing premiums for automotive-grade certification tiers.
Pricing Analysis
Third-generation Mirai stack architectures command 15-20% premiums over second-generation systems through improved platinum loading efficiency, while next-generation heavy-duty platforms face cost compression from silicon carbide power electronics adoption. Pricing stratifies across automotive-grade UN ECE R134 certified, pre-certified commercial, and uncertified industrial tiers. Corporate fleet procurement channels negotiate 12-18% volume discounts through bundled hydrogen supply agreements. Battery pack cost declines exert downward pressure on passenger fuel cell pricing, making METI subsidy levels the critical price elasticity determinant for private buyers.
Supply Chain Analysis
Container availability constraints on the Busan-Long Beach trade lane elevate inbound logistics costs for Korean membrane electrode assembly exports to California truck OEMs. Manufacturing gravity centers on South Korea, Germany, and Japan for fuel cell stacks, with China concentrating electrolyzer equipment for green hydrogen production. Platinum and iridium loadings above 0.3 mg/cm² tether stack costs to precious metals commodity volatility. Single-source vulnerability pervades carbon fiber hydrogen tank liner supply. Distribution runs through direct fleet sales contracts and OEM-integrated direct sales channels, marginalizing traditional dealership networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive-grade fuel cell certification demands 5,000+ hour durability validation that only a handful of stack producers have achieved, creating acute capability scarcity for fleet operators seeking qualified suppliers under accelerated electrification mandates.
For Market Incumbents: Shield technology leadership through backward integration into membrane electrode assembly production and captive iridium supply agreements with South African mining consortiums. Battery-electric range extension in Class 8 segments threatens fuel cell volume assumptions. Accelerate JIS and UN ECE R134 certification pipelines for next-generation hydrocarbon membrane architectures to preempt EU F-Gas Regulation displacement. For New Entrants and Emerging Players: Lead with balance-of-plant component specialization in power control units and thermal management subsystems where automotive-grade certification barriers remain lower than stack production. Municipal bus tender processes in Germany and California present the most penetrable procurement channels through 12-year durability specification compliance. Pursue joint development agreements with established stack producers rather than standalone platform competition. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors vertically integrated specialists with proven durability metrics over pure-play electrolyzer equipment manufacturers. Five-to-ten year viability hinges on green hydrogen production cost parity with diesel. Acquisition targets should demonstrate active fleet deployment contracts rather than demonstration programs. Monitor California Advanced Clean Trucks credit pricing as the inflection indicator for freight operator powertrain commitment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Chemistry Transition | Hydrocarbon ionomer qualification accelerates German and Korean stack producers toward CE marking retention under EU F-Gas Regulation. |
| Corporate Fleet Procurement Consolidation | Long-term offtake agreements between California freight carriers and electrolyzer developers concentrate buyer power and margin capture. |
| 700-Bar Technician Certification Expansion | Sparse hydrogen station maintenance training programs constrain commercial vehicle deployment network growth outside early regions. |
| Carbon Fiber Tank Weight Reduction | Miniaturized winding patterns below 5 kg/kg H₂ enable roof-mount configurations preserving frame rail battery hybridization space. |
| Shared Catalyst R&D with Electrolysis | Polymer electrolyte membrane convergence compresses R&D amortization for dual-use suppliers serving production and consumption equipment. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 fuel cell procurement leads, fleet operations managers at California freight carriers, and hydrogen station network developers, then refined against secondary validation from EPA zero-emission vehicle credit transaction records, METI hydrogen deployment statistics, UN ECE R134 certification databases, and EU F-Gas Regulation implementation guidance. Bottom-up stack shipment aggregation and top-down fleet procurement value estimates were triangulated to reconcile volume and pricing assumptions.
Variance decomposition across vehicle type, component tier, end-user category, and distribution channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented shipment trajectories and average selling price evolution by certification grade. Industry-specific forecast inputs included California Advanced Clean Trucks regulatory phase-in schedules and German National Hydrogen Strategy funding allocation patterns.
The analysis sits within stated boundaries; outcomes outside sustained green hydrogen production scaling or platinum group metal supply stability would require recalibration. Forecasts reflect documented assumptions regarding electrolyzer capacity expansion, membrane chemistry transition timelines, and fleet operator procurement consolidation velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Plug-In Hybrid Electric Vehicles (PHEV) Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
North America Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market
Hybrid Vehicles
High-Voltage Hybrid Vehicle Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
Hybrid Electric Vehicle Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market