
 Europe Mild Hybrid Vehicles Market | 2026-2036
Europe Mild Hybrid Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mild Hybrid Vehicles Market Foresight
Aftermarket battery refurbishment is reshaping margin distribution across the Europe mild hybrid value chain. Stellantis leverages its multi-brand manufacturing footprint to standardize 48V components across Peugeot and Fiat production lines. BMW sustains technology leadership through proprietary energy recuperation software integrated across its sedan and SUV portfolios. Volvo anchors its premium positioning with mild hybrid powertrains as standard equipment across its European lineup.
Mild hybrid vehicles integrate electric motor assistance with internal combustion engines through belt-driven or crankshaft-mounted starter-generator systems, typically operating at 48 volts to enable torque fill, regenerative braking, and coasting functionality without full electric propulsion capability. The 48V mild hybrid segment dominates powertrain technology adoption due to its cost-efficiency threshold relative to full hybrid architectures. Fleet services represent the fastest-growing end-user channel as corporate mobility managers prioritize CO2 compliance without charging infrastructure dependency. SUV body styles command premium positioning within personal use segments, reflecting consumer preference for elevated driving positions combined with emissions-conscious powertrain selection.
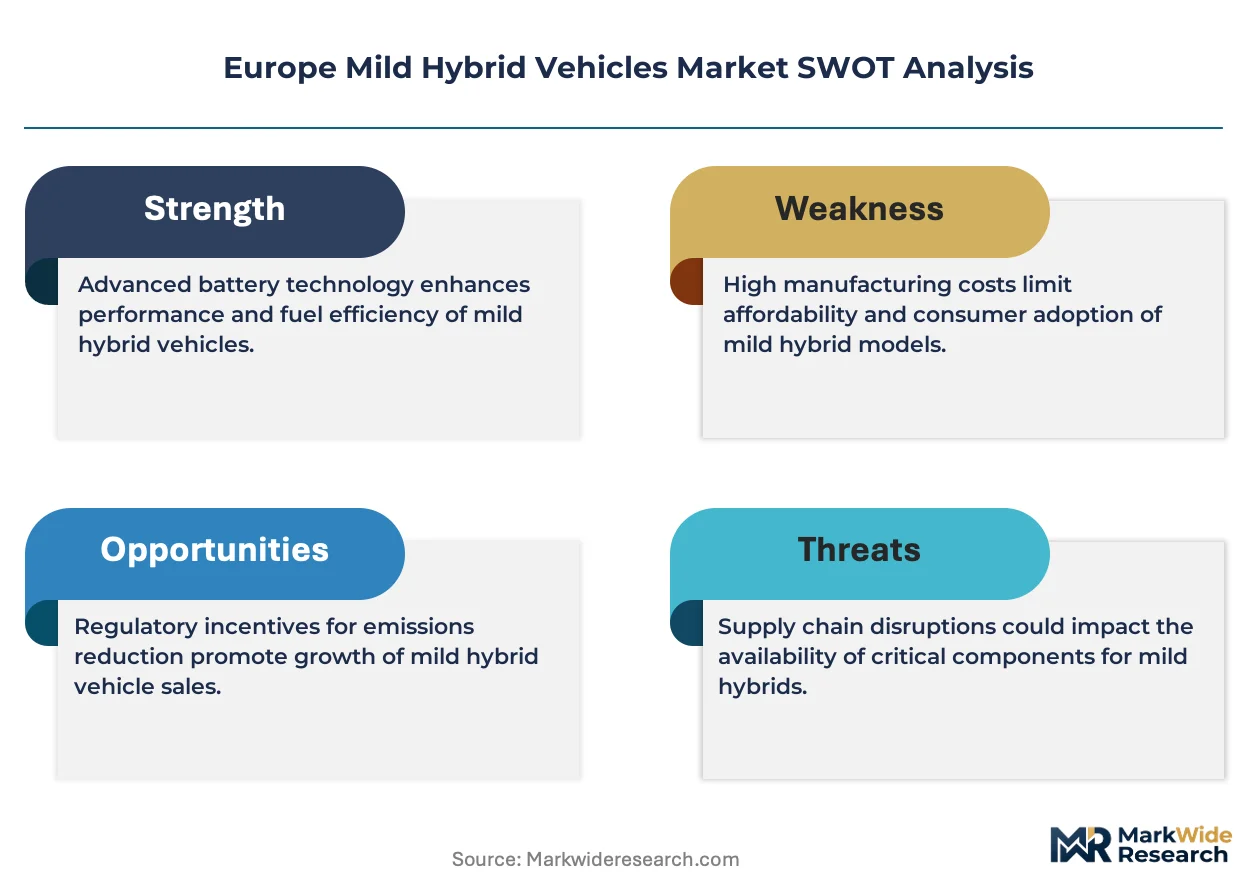
The EU Green Deal establishes binding CO2 reduction trajectories that OEMs must satisfy through mild hybrid penetration across mainstream vehicle categories. EMA transport emissions standards and national low-emission zone expansions in German cities including Berlin and Hamburg create regulatory pull for electrified powertrains below full battery-electric cost levels. The F-Gas Regulation indirectly shapes thermal management system specifications as mild hybrid architectures require optimized climate control efficiency. Stakeholders must monitor how the proposed Euro 7 emission standards redefine cost boundaries between advanced mild hybrid systems and entry-level plug-in alternatives.
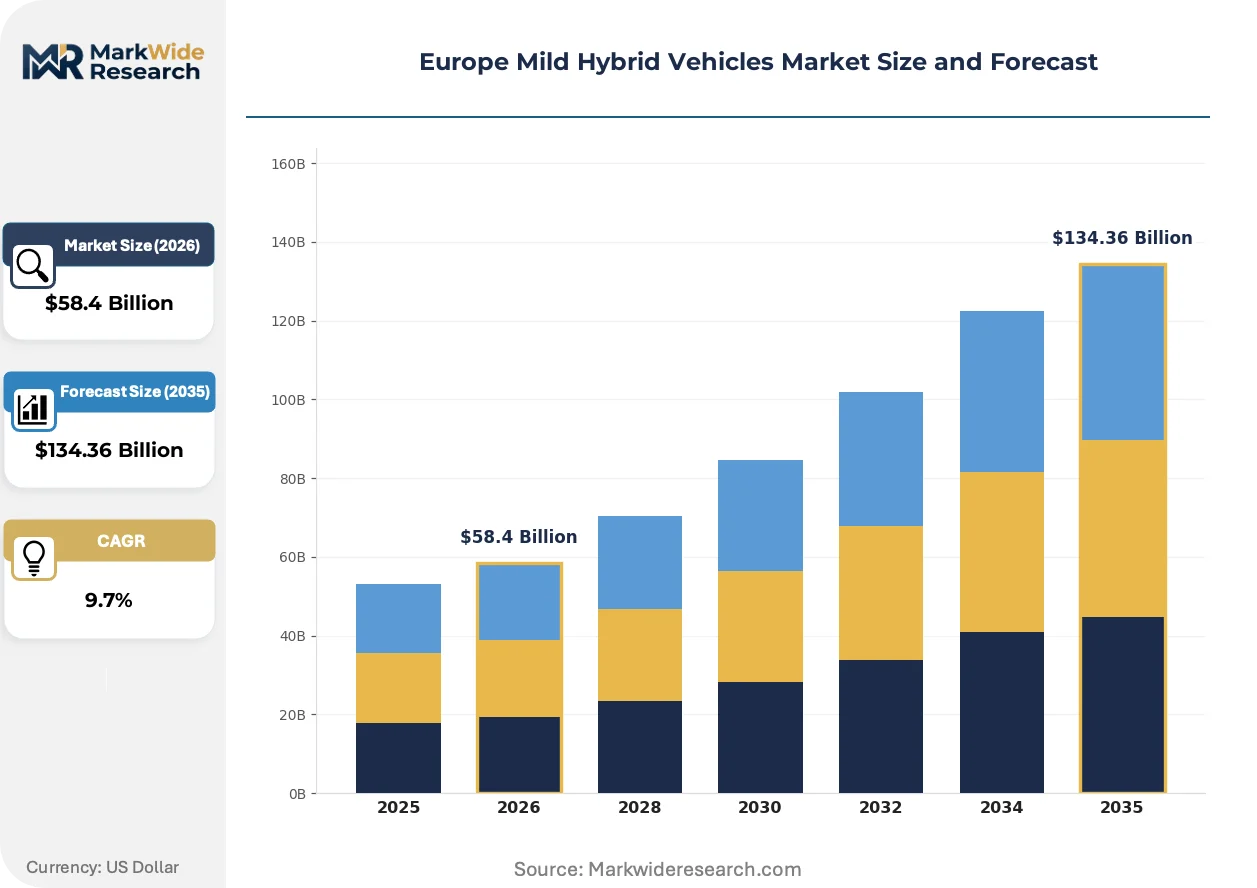
Market Dynamics
48V powertrain architectures are compressing cost boundaries between conventional combustion and full electrification, forcing OEMs to rebalance R&D portfolios across multiple electrification pathways simultaneously.
Growth Catalysts
- EU Green Deal CO2 mandates:Binding fleet-average emissions targets compel automakers to deploy mild hybrid systems across high-volume nameplates to avoid penalty payments.
- Fleet procurement centralization:Corporate mobility managers in Germany and France are consolidating vehicle orders around 48V mild hybrid sedans to satisfy sustainability reporting requirements without charging infrastructure capital expenditure.
- F-Gas Regulation phase-down:Refrigerant constraints on thermal management systems are accelerating adoption of electrically-assisted climate control compatible with mild hybrid electrical architectures.
Market Restraints
- Lithium-ion cell cost volatility:Battery module pricing fluctuations compress margin predictability for 48V system integrators serving mass-market segments.
- Power electronics supply concentration:Semiconductor fabrication for DC-DC converters and inverters clusters in East Asian foundries, exposing European assembly plants to shipping disruption risk.
- Full hybrid substitution threshold:Toyota and Hyundai full hybrid powertrains at price parity in C-segment vehicles erode the mild hybrid value proposition in cost-sensitive buyer cohorts.
Strategic Opportunities
- Italian commercial fleet underpenetration:Rome and Milan low-emission zone expansions create first-mover advantage for 48V van and light commercial offerings ahead of competitor saturation.
- Second-life battery refurbishment:Aftermarket service networks in France are developing standardized testing protocols for degraded 48V modules, unlocking circular economy revenue streams.
- EMA transport emissions standards alignment:Upcoming regulatory harmonization between automotive and heavy-duty sectors opens technology transfer opportunities for 48V mild hybrid derivatives in light trucks.
Industry Challenges
- Power electronics engineering talent scarcity:Competition with battery-electric and full hybrid programs limits availability of experienced 48V system architects in Continental European engineering centers.
- Dual powertrain validation burden:OEMs must maintain parallel homologation pipelines for mild hybrid and emerging plug-in variants under diverging Euro 7 test protocols, stretching regulatory affairs capacity.
- Dealer technical training gaps:Service networks require recertification on high-voltage safety and diagnostic equipment, creating friction in aftermarket support scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mild Hybrid Vehicles Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $134.36 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, Hatchback, SUV, Coupe, Convertible Powertrain Technology: 48V Mild Hybrid, 12V Mild Hybrid, Parallel Hybrid, Series Hybrid End User: Personal Use, Fleet Services, Car Rental, Corporate Leasing Distribution Channel: OEM Dealerships, Authorized Resellers, Online Marketplaces, Aftermarket Suppliers |
| Companies Covered | Stellantis, Audi, Volkswagen, Ford, Volvo, BMW, Renault, Peugeot, Mercedes-Benz, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mild Hybrid Vehicles Market Shifts & Advancements
Belt-integrated starter-generator systems are displacing conventional alternator architectures across European nameplates, while thermal management integration and software-defined energy recuperation reshape competitive differentiation.
Silicon carbide power semiconductors in 48V inverters are rendering obsolete traditional silicon-based switching components in next-generation mild hybrid designs. Premium German OEMs are adopting these devices for their sedan portfolios to capture higher regenerative braking efficiency. The technology is rendering obsolete legacy 12V belt alternator starter systems in vehicles above two liters displacement.
The EU Green Deal's binding CO2 reduction trajectories are forcing powertrain portfolio rationalization across European manufacturing footprints. OEMs must satisfy fleet-average targets through mild hybrid penetration or face penalty structures that erode per-unit profitability. German and French automakers are responding by standardizing 48V architectures across SUV and sedan nameplates previously served by pure combustion.
Corporate fleet managers are consolidating procurement around total-cost-of-ownership metrics that internalize carbon reporting obligations. Long-term leasing providers in France and Germany are displacing traditional outright purchase with full-service contracts bundling maintenance and compliance documentation. This behavioral shift is most visible in German Mittelstand manufacturing firms operating multi-site vehicle pools across low-emission zone jurisdictions.
Europe Mild Hybrid Vehicles Market Segmentation
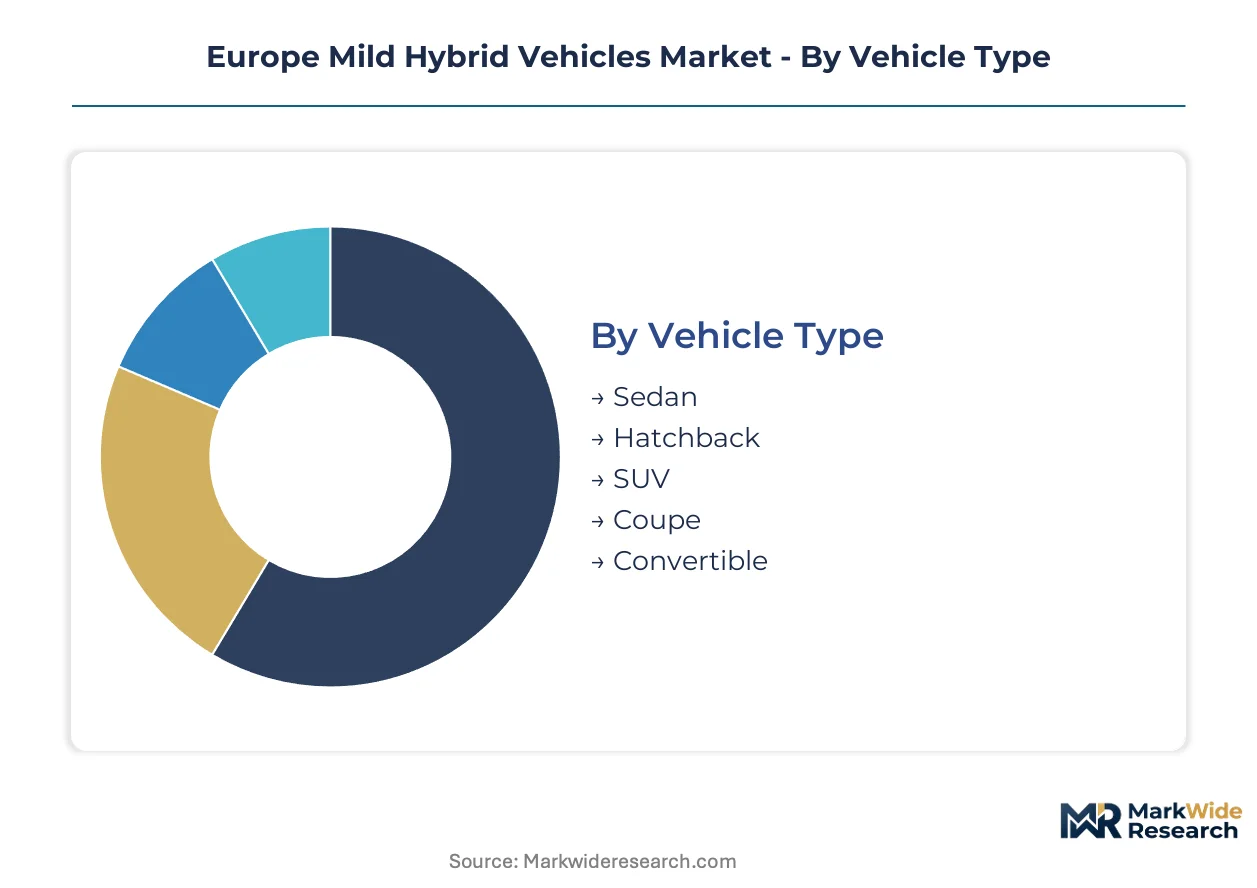
Segmentation in the Europe mild hybrid vehicles market reveals how regulatory pressure and infrastructure constraints reshape procurement patterns across vehicle categories. Fleet managers and personal buyers diverge sharply in their technology preferences, creating distinct competitive arenas within the same national markets.
Vehicle Type:
SUV and sedan segments turn inventory fastest in German and French dealership networks, while coupe and convertible mild hybrids linger longer on lots due to narrower buyer pools.
- Sedan:48V mild hybrid sedans dominate corporate fleet procurement in Germany, where CO2-based taxation favors electrified powertrains in this body style. French leasing companies standardize on mild hybrid sedans for mid-level executive mobility programs to satisfy CSRD reporting requirements without charging infrastructure investment.
- SUV:Belt-integrated starter-generator systems in compact and mid-size SUVs command premium positioning, with elevated driving positions attracting emissions-conscious personal buyers. Italian low-emission zone expansions in Rome and Milan are accelerating SUV mild hybrid adoption ahead of van and hatchback alternatives.
- Hatchback:Cost-optimized 48V architectures serve price-sensitive urban buyers in France and Italy.
- Coupe:Limited production runs of mild hybrid coupes target enthusiast segments with performance-oriented energy recuperation.
- Convertible:Seasonal demand patterns in Mediterranean markets constrain volume for open-top mild hybrid variants.
Sedan anchors the volume base while SUV gains share at the steepest rate.
Powertrain Technology:
Cost tier separation between 12V entry systems and 48V full-function architectures determines which OEMs capture fleet versus personal segments.
- 48V Mild Hybrid:Crankshaft-mounted starter-generator systems operating at 48 volts enable torque fill, regenerative braking, and coasting functionality without full electric propulsion. German automakers deploy this architecture across high-volume nameplates to satisfy EU Green Deal fleet-average CO2 mandates.
- 12V Mild Hybrid:Simplified belt-alternator-starter systems serve cost-sensitive B-segment vehicles where 48V component costs exceed buyer willingness to pay. French mass-market brands utilize 12V mild hybrid technology in entry hatchbacks to maintain price positioning against full hybrid competitors.
- Parallel Hybrid:Dual-powerpath architectures with mechanical engine coupling persist in specific Toyota and Hyundai offerings.
- Series Hybrid:Range-extender configurations remain marginal in European mild hybrid applications.
48V Mild Hybrid captures the dominant revenue share while 12V Mild Hybrid defends position in entry price tiers.
End User:
Procurement concentration varies by customer type, with centralized fleet decision-making contrasting fragmented personal buyer behavior.
- Fleet Services:Corporate mobility managers in Germany consolidate multi-site vehicle pools around 48V mild hybrid sedans and SUVs to satisfy sustainability reporting obligations without charging infrastructure capital expenditure. Long-term leasing providers bundle maintenance and compliance documentation into full-service contracts displacing traditional outright purchase.
- Personal Use:Individual buyers in Italy and France select mild hybrid SUVs for elevated driving positions combined with emissions-conscious powertrain selection. Urban low-emission zone access permissions influence purchase timing more than fuel cost savings for this cohort.
- Corporate Leasing:German Mittelstand manufacturing firms expand mild hybrid penetration across executive vehicle tiers.
- Car Rental:Short-term rental fleets add mild hybrid vehicles to satisfy airport concession sustainability requirements.
Fleet Services anchors the volume base while Personal Use climbs the fastest as low-emission zones expand.
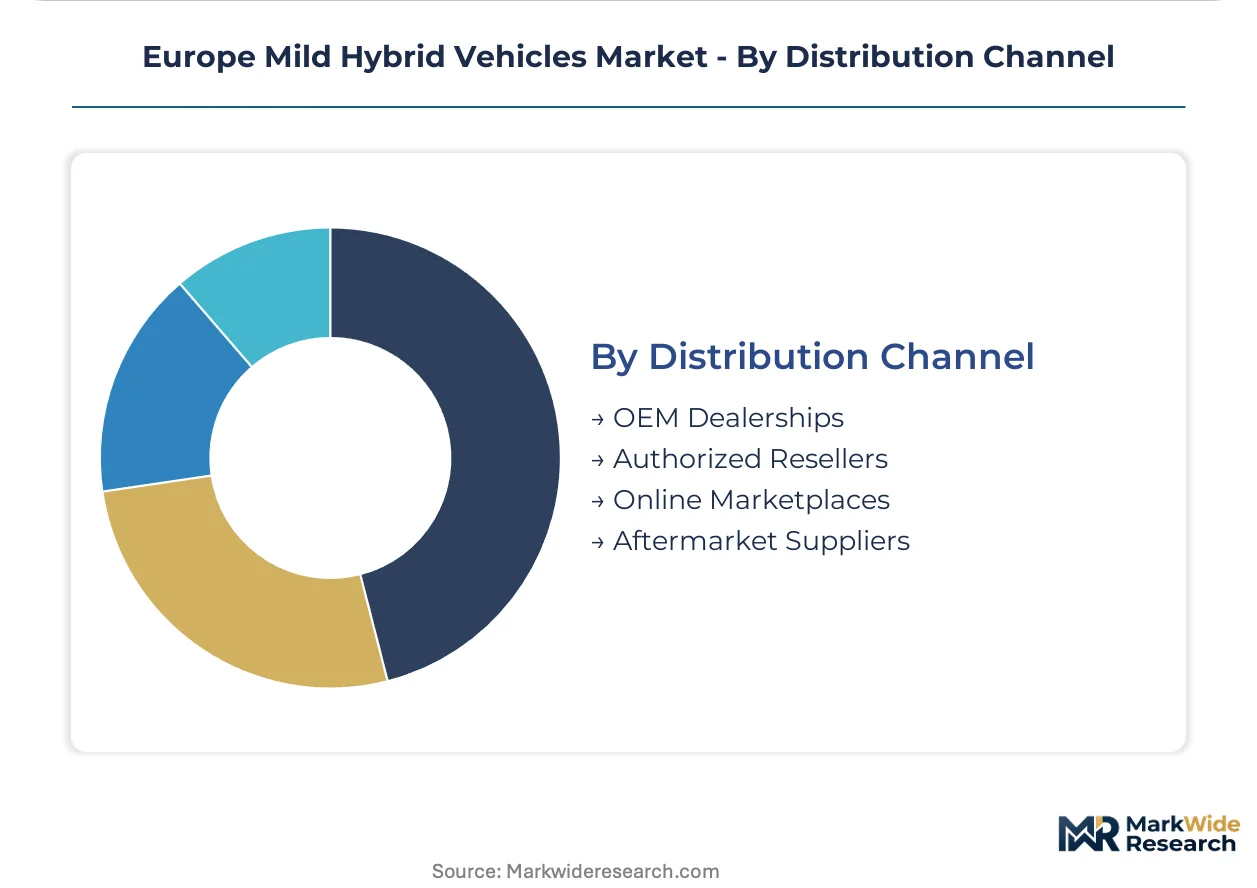
Distribution Channel:
Channel margins compress where digital price transparency confronts traditional dealership service bundling.
- OEM Dealerships:Authorized dealer networks in Germany and France deliver mild hybrid vehicles with certified technician support for high-voltage system maintenance. Manufacturer-captive finance subsidiaries integrate leasing documentation with CO2 compliance reporting for corporate fleet customers.
- Authorized Resellers:Independent distributors serve secondary markets with certified pre-owned mild hybrid inventory and extended warranty coverage.
- Online Marketplaces:Digital platforms enable price comparison across national markets for personal buyers.
- Aftermarket Suppliers:Specialized distributors serve battery refurbishment and power electronics replacement demand.
OEM Dealerships anchors the volume base while Online Marketplaces gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate fleet buyers in Germany show the lowest price elasticity, absorbing 48V mild hybrid premiums to satisfy CSRD reporting mandates. Italian personal buyers exhibit the highest sensitivity, where 12V entry systems defend market share against full hybrid alternatives.
Germany
Corporate Mittelstand firms consolidate multi-site vehicle pools around 48V sedans and SUVs to meet EU Green Deal fleet-average CO2 obligations. The KBA enforces stringent type-approval standards that accelerate powertrain electrification timelines. Berlin and Hamburg low-emission zone expansions drive procurement concentration in the Rhine-Ruhr industrial corridor.
France
Long-term leasing providers bundle mild hybrid maintenance with compliance documentation for CSRD-reporting enterprises. The F-Gas Regulation phase-down shapes thermal management specifications across Paris-based fleet operators. Auvergne-Rhône-Alpes hosts specialized power electronics fabrication serving Stellantis multi-brand standardization programs.
Italy
Urban buyers in Rome and Milan prioritize low-emission zone access permissions over fuel cost savings when selecting mild hybrid SUVs. National CO2-based vehicle taxation structures favor 48V architectures in premium segments. Lombardy manufacturing clusters concentrate belt-integrated starter-generator assembly for Fiat production lines.
United Kingdom
London's Ultra Low Emission Zone drives corporate fleet replacement cycles toward mild hybrid alternatives ahead of 2030 phase-out deadlines. The EMA transport emissions standards alignment creates technology transfer opportunities for light commercial derivatives. Midlands automotive engineering centers face talent competition from battery-electric and full hybrid programs.
Spain
Madrid and Barcelona low-emission zone expansions accelerate 48V van adoption among last-mile delivery operators. National rental fleet sustainability requirements displace conventional combustion at airport concessions. Catalonia-based component suppliers serve southern European aftermarket refurbishment networks.
Europe Mild Hybrid Vehicles Market Competitive Landscape
Capability concentration sits with premium German engineering centers; scale advantage sits with multi-brand manufacturing platforms spanning mass-market segments. The vendor structure tiers across three distinct competitive arenas: integrated OEM powertrain divisions, tier-one system integrators, and specialized semiconductor fabricators. Two dominant competitive moves define current positioning: platform standardization across brand portfolios and backward integration into power electronics design.
Within the integrated OEM tier, Stellantis anchors multi-brand 48V deployment across Peugeot and Fiat production networks. BMW occupies a position emphasizing proprietary energy recuperation software differentiation. Volvo exemplifies premium-tier standardization by specifying mild hybrid powertrains as baseline equipment across European nameplates.
| Leading Market Players |
|---|
| Stellantis |
| Audi |
| Volkswagen |
| Ford |
| Volvo |
| BMW |
| Renault |
| Peugeot |
| Mercedes-Benz |
| Others |
Supply & Pricing Matrix
Semiconductor fabrication concentration in East Asian foundries determines both margin compression trajectories across 48V system tiers and the geographic restructuring of European assembly networks. Battery module cost volatility feeds directly into OEM procurement strategies, compressing price spreads between entry-level 12V architectures and full-function 48V implementations.
Pricing Analysis
Aftermarket battery refurbishment revenue streams anchor lifetime value capture across European mild hybrid fleets. Three-tier pricing structure across premium, standard, and economy levels separates German OEM proprietary software bundles from Stellantis multi-brand standardized offerings and French mass-market 12V entry systems. Cost compression in 48V inverter modules is intensifying because silicon carbide adoption raises component sourcing expenses. Italian personal buyers exhibit highest price sensitivity, while German corporate fleet managers absorb premiums to satisfy CSRD reporting mandates.
Supply Chain Analysis
Tariff exposure between Taiwan and European automotive assembly plants dominates power electronics procurement risk for DC-DC converters and inverter modules. Lithium-ion cell supply draws from China, South Korea, and Japan, while belt-integrated starter-generator assembly concentrates in Germany and Italy. Single-source vulnerability sits with 200mm silicon wafer fabrication for automotive-grade semiconductors. Distribution runs through OEM-captive logistics networks serving authorized dealership channels with certified high-voltage technician support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe mild hybrid vehicles market sits in early-cycle expansion as EU Green Deal CO2 mandates force fleet-average compliance across high-volume nameplates before plug-in infrastructure maturity.
For Market Incumbents: Insulate margin positions by accelerating backward integration into power electronics design and securing captive battery supply agreements with Korean cell manufacturers. Toyota and Hyundai full hybrid price parity in C-segment vehicles threatens mild hybrid value propositions, requiring proprietary energy recuperation software differentiation to defend positioning. For New Entrants and Emerging Players: Pursue Italian commercial fleet underpenetration in Rome and Milan low-emission zones where 48V van and light commercial offerings face limited competitor saturation. Target aftermarket battery refurbishment standardization in France, where degraded 48V module testing protocols remain unconsolidated, using technical service partnerships with independent distributors as entry mechanism. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors specialized power electronics fabricators with automotive qualification pathways. Long-term viability hinges on silicon carbide inverter adoption trajectories across German premium OEM portfolios. Acquisition targets should demonstrate Euro 7 homologation readiness and established relationships with Stellantis or BMW platform engineering. Watch EMA transport emissions standards alignment with heavy-duty sectors as inflection signal for 48V technology transfer opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Stellantis multi-brand 48V deployment across Peugeot and Fiat production networks reduces per-unit engineering overhead. |
| Battery Supply Agreement | Korean cell manufacturer partnerships secure lithium-ion module allocation amid raw material cost volatility. |
| Software-Defined Vehicle Investment | BMW proprietary energy recuperation algorithms differentiate sedan and SUV portfolios in fleet procurement decisions. |
| Geographic Manufacturing Footprint | Lombardy belt-integrated starter-generator assembly clusters support Fiat production line integration. |
| Charging Infrastructure Partnership | Corporate leasing providers bundle mild hybrid maintenance with compliance documentation displacing outright purchase. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, EU Green Deal regulatory filings, and F-Gas Regulation implementation guidance. Bottom-up segment sizing triangulated with top-down fleet penetration modeling.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the projection horizon. CAGRs derive from regression analysis of historical powertrain mix shifts and scenario-weighted regulatory compliance cost trajectories. Silicon carbide adoption curves and Euro 7 test protocol finalization timelines feed sensitivity parameters.
Sensitivities concentrate around lithium-ion cell pricing volatility, semiconductor fabrication capacity allocation, and Euro 7 emission standard cost boundary redefinitions. Forecasts reflect documented assumptions on fleet procurement centralization rates and low-emission zone expansion schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Crossovers Market
Hybrid Vehicles
Electric and Hybrid Vehicles Driveline Market
Hybrid Vehicles
United States Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Ignition Systems for Range-Extended Hybrid Powertrains Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
Hybrid Train Market
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
Hybrid Cars Market
Hybrid Vehicles
India Hybrid Vehicles Market
Hybrid Vehicles
Hydrogen Fuel Automotive Market
Hybrid Vehicles
United Arab Emirates Hybrid and Electric Vehicles Market
Hybrid Vehicles
Hybrid Electric Self-Driving Car Market
Hybrid Vehicles
Global Hybrid-Electric Vehicle Insulation Market