
 Crossovers Market | 2026-2036
Crossovers Market Size, Share, and Industry Trends Forecast 2026-2036
Crossovers Market Analysis
Capital-intensity divergence between legacy automakers and newer entrants is redrawing competitive boundaries in crossover manufacturing. Toyota Motor Corporation leverages its hybrid powertrain depth to anchor premium positioning across multiple crossover tiers. Ford Motor Company sustains North American truck-derived crossover dominance through Super Duty platform extensions and Bronco sub-brand specialization.
Crossovers blend unibody construction with elevated ground clearance, typically riding on car-based platforms that deliver passenger-car fuel efficiency alongside SUV cargo versatility and commanding visibility. The architecture prioritizes interior packaging efficiency, with wheelbases stretched to maximize second-row legroom and flat-load floor configurations. Compact crossover and mid-size crossover segments command the largest volume pools, while electric powertrain variants within these categories are capturing disproportionate engineering investment as battery cost curves flatten. Family-oriented end users and fleet operators represent structurally distinct demand channels, with the latter prioritizing total cost of ownership and residual value over feature content.
The US EPA, California Air Resources Board, and China's Ministry of Ecology and Environment enforce diverging but equally stringent emissions frameworks that compel powertrain portfolio restructuring across all crossover manufacturers selling into these jurisdictions. European REACH compliance and evolving EU Green Deal automotive CO2 targets further constrain material selection and manufacturing location decisions. Stakeholders must monitor battery supply chain localization mandates and charging infrastructure buildout rates as determinants of electric crossover penetration trajectories.
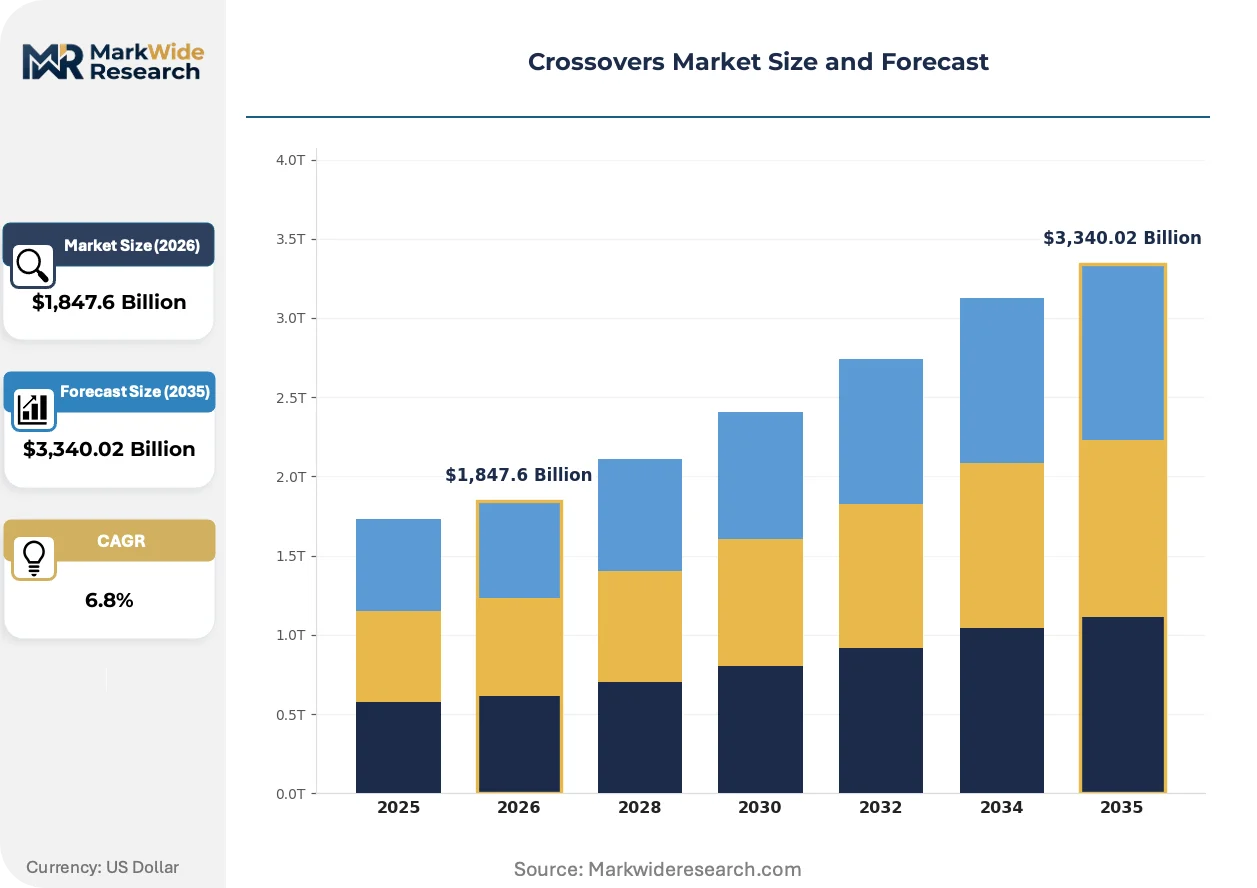
Market Dynamics
Powertrain electrification is compressing engineering timelines across crossover portfolios as battery cost curves flatten and fleet operators rewrite procurement specifications around total cost of ownership metrics.
Growth Catalysts
- China's dual carbon goals:Binding emissions targets under the Ministry of Ecology and Environment are mandating electric crossover quotas for domestic manufacturers, accelerating local battery supply chain maturation.
- Fleet electrification mandates:Last-mile logistics operators in Germany and the United States are specifying zero-emission crossovers for urban delivery routes, pulling forward volume commitments.
- Unibody platform standardization:Shared architectures between passenger cars and crossovers are reducing development costs and enabling faster powertrain variant proliferation.
Market Restraints
- Lithium supply concentration:Raw material processing bottlenecks in South American brine operations and Australian hard-rock mines are constraining battery cell availability for electric crossover ramp-ups.
- Charging infrastructure gaps:Uneven DC fast-charging deployment across rural United States corridors is limiting electric crossover appeal outside urban commuter markets.
- Residual value uncertainty:Fleet operators hesitate on battery-electric crossovers due to unproven secondary market pricing and replacement cost exposure.
Strategic Opportunities
- India's PLI scheme for automotive:Production-linked incentives for advanced chemistry cell manufacturing are opening local assembly opportunities for export-focused crossover producers.
- Vehicle-to-grid integration:Bidirectional charging capabilities are creating new revenue streams for fleet-owned electric crossovers participating in grid stabilization services.
- Subscription-based access models:Urban consumers in Germany are piloting flexible tenure programs that bundle insurance, maintenance, and charging into per-mile pricing.
Industry Challenges
- Software-defined vehicle integration:Legacy tier-one suppliers struggle to deliver over-the-air update architectures that match consumer electronics refresh cycles.
- Homologation timeline compression:Divergent crash-test protocols between the United States NHTSA and European NCAP are extending validation schedules for global crossover programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crossovers Market |
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $3,340.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crossover SUV, Compact Crossover, Mid-Size Crossover, Full-Size Crossover End User: Families, Outdoor Enthusiasts, Urban Commuters, Fleet Operators Drive Type: All-Wheel Drive, Front-Wheel Drive, Rear-Wheel Drive, Four-Wheel Drive Powertrain: Gasoline, Diesel, Hybrid, Electric |
| Companies Covered | Toyota Motor Corporation, Ford Motor Company, Volkswagen AG, Hyundai Motor Group, Kia Motors, Nissan Motor Company Ltd, Honda Motor Company, Subaru of America, Inc., Mazda Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crossovers Market Emerging Trajectories
Electrification is rewriting powertrain architecture decisions while digital retail channels and battery chemistry advances are compressing traditional product development and distribution timelines.
Silicon carbide power electronics are replacing silicon IGBTs in electric crossover inverters, enabling higher switching frequencies and reduced thermal losses. Premium and mid-size segments are adopting these modules fastest as manufacturers chase efficiency gains. The technology is miniaturizing onboard charging hardware, freeing packaging space for cabin volume expansion.
REACH compliance in the European Union is restricting hexavalent chromium and specific phthalates in interior materials, forcing upholstery and trim suppliers to reformulate coating and soft-touch compounds. Crossover interiors destined for EU markets now require full material disclosure documentation. German and French manufacturers are responding by accelerating bio-based alternative qualification programs.
Fleet procurement departments are consolidating supplier relationships and demanding standardized telematics integration for route optimization and predictive maintenance. Direct-to-fleet sales channels are bypassing traditional dealer networks in the United States and China. This concentration is most visible among national delivery services and utility field operations prioritizing uptime guarantees over feature content.
Crossovers Market Segmentation
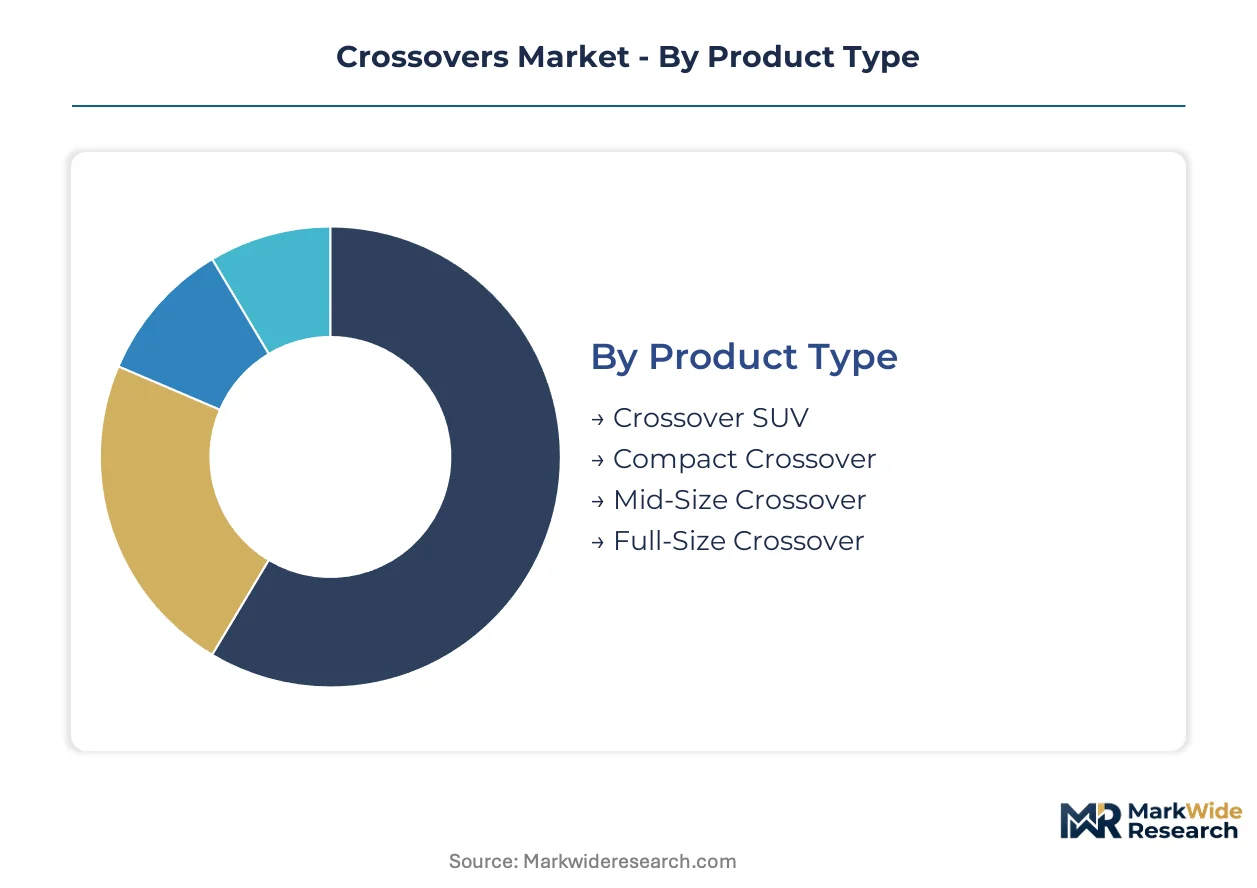
Crossover segmentation determines channel strategy, engineering investment allocation, and powertrain portfolio prioritization. Distinct buyer profiles—family haulers, fleet procurement officers, and outdoor recreation consumers—route through separate sales channels with divergent specification priorities.
Product Type:
Channel mix varies sharply by size tier, with compact crossovers dominating digital retail and full-size variants concentrated in commercial fleet direct sales.
- Compact Crossover:Unibody construction on stretched passenger-car platforms maximizes interior packaging efficiency. Urban commuters in Germany and the United States drive volume through subscription-based access models and short-cycle leasing programs.
- Mid-Size Crossover:Stretched wheelbases deliver flat-load floor configurations and expanded second-row legroom. Family-oriented buyers across China prioritize this tier for single-vehicle household solutions, pulling hybrid powertrain adoption.
- Crossover SUV:Blends elevated ground clearance with car-based fuel efficiency.
- Full-Size Crossover:Three-row configurations serve fleet operators and large households.
By volume, compact crossover leads. By growth pace, mid-size crossover is expanding most quickly.
End User:
Cost tier separation is pronounced, with fleet operators prioritizing total cost of ownership metrics and outdoor enthusiasts driving premium feature content.
- Fleet Operators:Procurement specifications center on residual value guarantees, standardized telematics, and predictive maintenance integration. Last-mile logistics providers in the United States and Germany are specifying zero-emission configurations for urban delivery routes.
- Families:Interior packaging efficiency and safety ratings dominate purchase criteria. Chinese and German buyers in this segment show strongest uptake of hybrid powertrains for school-run and intercity travel duty cycles.
- Outdoor Enthusiasts:Towing capacity and all-terrain capability command premium pricing.
- Urban Commuters:Parking footprint and charging accessibility shape selection.
Families generate the largest absolute volume. Fleet operators are climbing the fastest as electrification mandates tighten.
Drive Type:
Application context determines selection, with all-wheel drive concentrated in northern climates and recreational use cases while front-wheel drive dominates cost-sensitive urban procurement.
- All-Wheel Drive:Torque-vectoring systems and terrain management modes define technical differentiation. Demand concentrates in snow-belt United States states and German rural districts where unimproved road access is common.
- Front-Wheel Drive:Lighter weight and reduced mechanical complexity improve efficiency metrics. Fleet operators in China and urban Germany specify this configuration for last-mile delivery applications where traction demands are minimal.
- Four-Wheel Drive:Low-range gearing serves off-road recreation and utility applications.
- Rear-Wheel Drive:Performance-oriented configurations anchor premium rear-biased chassis tuning.
Front-wheel drive holds volume leadership. All-wheel drive is gaining share fastest as electrification enables simpler torque distribution.
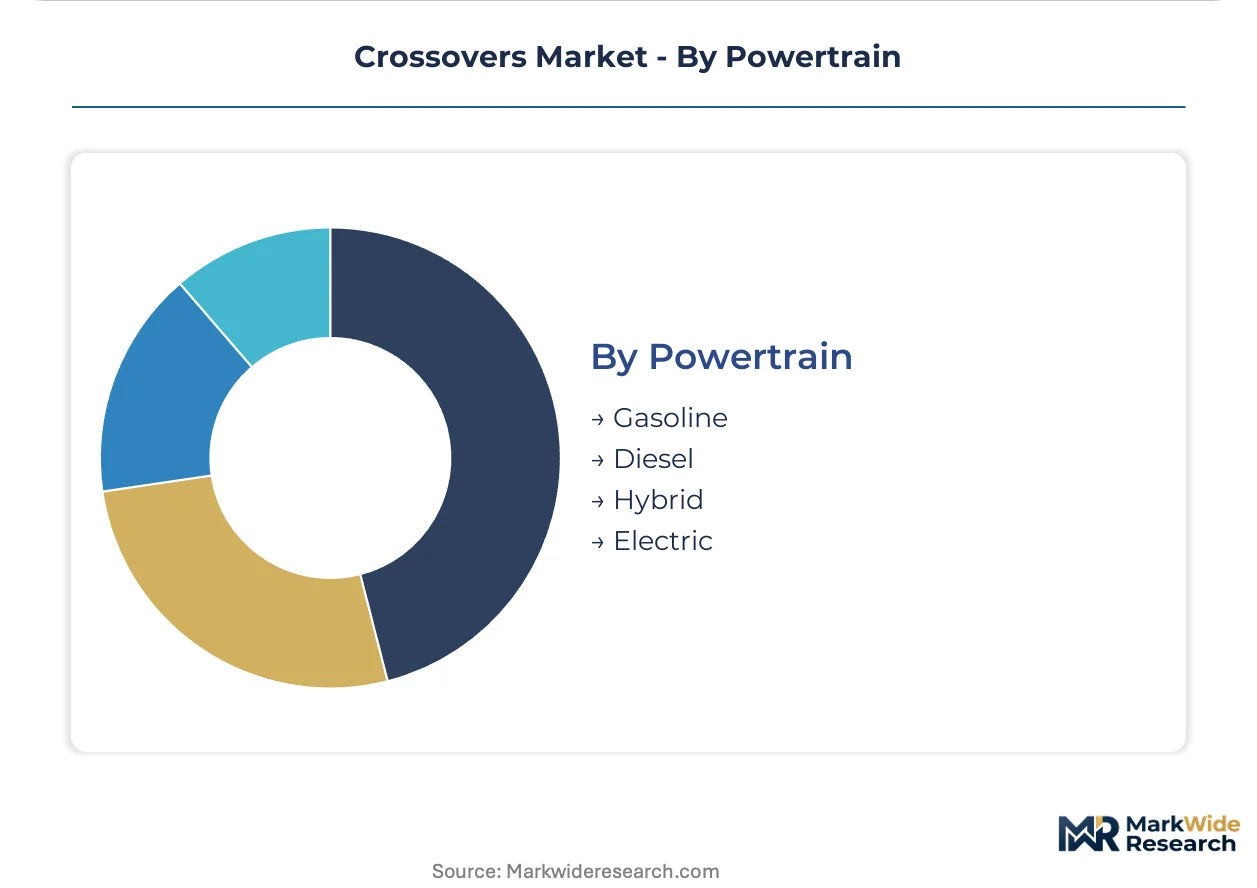
Powertrain:
Supply concentration in battery cell manufacturing is reshaping competitive positioning, with hybrid architectures leveraging Toyota's established supply base and full-electric variants dependent on localized cell production.
- Hybrid:Dual-motor systems with Atkinson-cycle engines deliver efficiency without charging infrastructure dependency. Toyota Motor Corporation's hybrid depth anchors premium positioning across multiple crossover tiers in the United States and Japan.
- Electric:Silicon carbide power electronics and flat battery pack configurations enable cabin space maximization. China's Ministry of Ecology and Environment quotas are mandating electric crossover volumes for domestic manufacturers, accelerating local supply chain maturation.
- Gasoline:Turbocharged direct-injection engines remain volume leaders in price-sensitive segments.
- Diesel:Compression-ignition variants retain fleet preference in Germany for highway fuel economy.
Gasoline retains volume dominance. Electric is climbing the fastest as battery cost curves flatten and charging infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where premium electrified crossovers command substantial markups, while Chinese manufacturers compete on volume through aggressive localization of battery supply chains.
United States
Fleet electrification mandates from the EPA and California Air Resources Board are accelerating zero-emission crossover procurement for last-mile logistics. The Inflation Reduction Act's domestic content requirements are reshaping battery sourcing strategies. Detroit's automotive corridor anchors truck-derived crossover production, with Bronco sub-brand specialization sustaining regional manufacturing depth.
China
Dual carbon goals under the Ministry of Ecology and Environment are mandating electric crossover quotas for domestic manufacturers. Production-linked incentives for advanced chemistry cell manufacturing are accelerating local battery supply chain maturation. The Yangtze River Delta cluster hosts the densest concentration of crossover assembly plants serving both domestic consumption and export markets.
Germany
EU Green Deal automotive CO2 targets and REACH compliance are constraining material selection and powertrain portfolio decisions. The KBA enforces stringent homologation protocols that extend validation schedules for electric variants. Bavaria's manufacturing belt concentrates premium crossover engineering, with Stuttgart and Munich anchoring R&D investment for electrified architectures.
Japan
METI's decarbonization roadmap is channeling investment into hybrid powertrain refinement alongside full-electric development. JIS standards govern safety and emissions compliance for domestic and export-bound crossovers. The Nagoya-Tokyo corridor maintains concentrated production of compact and mid-size crossovers leveraging established hybrid supply chain depth.
South Korea
MFDS and MOTIE regulations are accelerating battery-electric crossover certification timelines to match export market demands. Government-backed charging infrastructure buildout is addressing range anxiety in domestic consumer segments. The Seoul Capital Area and Busan-Ulsan corridor host integrated battery-to-vehicle manufacturing complexes serving global crossover programs.
Crossovers Market Vendor Landscape
Concentration sits with legacy full-line manufacturers possessing deep hybrid powertrain expertise and established fleet sales channels. The vendor base organizes into three strategic archetypes: diversified global OEMs with truck-platform heritage, Asian specialists leveraging battery supply chain proximity, and European premium brands emphasizing efficiency engineering. Dominant competitive moves include unibody platform standardization across passenger car and crossover lineups, and backward integration into battery cell manufacturing through joint ventures with Korean and Chinese suppliers.
Among diversified global OEMs, Toyota Motor Corporation and Ford Motor Company exemplify contrasting strategic anchors. Toyota's hybrid depth spans multiple crossover tiers, while Ford sustains North American dominance through truck-derived platform extensions. Volkswagen AG occupies a position bridging European efficiency mandates with scale-driven global distribution. Hyundai Motor Group and Kia Motors represent the Korean archetype, leveraging captive battery supply relationships and rapid powertrain variant proliferation.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Ford Motor Company |
| Volkswagen AG |
| Hyundai Motor Group |
| Kia Motors |
| Nissan Motor Company Ltd |
| Honda Motor Company |
| Subaru of America, Inc. |
| Mazda Motor Corporation |
| Others |
Supply Flow & Price Mechanics
EU REACH compliance gates both supplier qualification and price differentiation simultaneously, forcing upholstery and trim suppliers to reformulate coating compounds before accessing premium-tier contracts in Germany and France. Battery cell localization mandates under the Inflation Reduction Act and China's dual carbon goals create parallel certification tracks that stratify procurement costs across export and domestic-market variants.
Pricing Analysis
Configured-to-order pricing spreads 15-25% above standard SKUs, with premium-mid-economy pricing differentiation anchored by powertrain architecture and after-sales service bundling. Fleet procurement departments in the United States and Germany extract volume discounts through standardized telematics specifications, while family buyers absorb brand premiums for hybrid powertrain depth. Cost compression in compact crossover tiers intensifies because of battery cell oversupply in Chinese manufacturing clusters. Fleet operators exhibit highest price sensitivity; outdoor enthusiasts show lowest, paying towing-capability premiums.
Supply Chain Analysis
Just-in-time inventory strategies dominate final assembly, but strategic stockpiling of lithium hydroxide and silicon carbide wafers is spreading among Tier 1 suppliers hedging South American brine and Taiwanese semiconductor bottlenecks. Raw material processing draws from Chile, Australia, and Argentina; power electronics fabrication rests on South Korea and Japan; vehicle assembly concentrates in China, the United States, and Germany. Single-source vulnerability in cathode-active-material supply threatens electric crossover ramp timelines. Distribution runs through direct-to-fleet channels bypassing dealer networks in North America and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet procurement consolidation across national delivery services and utility field operations has shifted buyer power toward volume-commitment contracting, fragmenting price-setting autonomy for legacy OEMs.
For Market Incumbents: Compound hybrid powertrain expertise into adjacent crossover tiers while accelerating backward integration into battery cell manufacturing through Korean and Chinese joint ventures. Defend against Asian specialists leveraging captive supply relationships by anchoring fleet sales channels with residual value guarantees and predictive maintenance integration. Platform standardization across passenger car and crossover lineups remains the critical cost lever. For New Entrants and Emerging Players: Differentiate on vehicle-to-grid integration capabilities targeting German and United States fleet operators participating in grid stabilization services. White-space sits in subscription-based access models for urban commuters in German metropolitan areas and last-mile logistics electrification in India under PLI scheme incentives. Direct-to-fleet sales channels offer the most penetrable go-to-market angle, bypassing established dealer network moats. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across full-electric crossover programs as silicon carbide power electronics and localized cell manufacturing absorb disproportionate engineering investment. Long-term viability favors OEMs with demonstrated hybrid supply chain depth and established fleet relationships over pure-electric entrants dependent on unproven battery supply agreements. Acquisition targets should show integrated battery-to-vehicle manufacturing footprints or software-defined vehicle architectures. Monitor charging infrastructure buildout rates across rural United States corridors as the inflection signal for electric crossover penetration trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium hydroxide offtake from Chilean brine operations for electric crossover ramp-ups. |
| Platform Standardization | Reduces development costs across unibody architectures shared between passenger cars and crossovers. |
| Software-Defined Vehicle Investment | Enables over-the-air update cycles matching consumer electronics refresh expectations. |
| Charging Infrastructure Partnership | Addresses DC fast-charging gaps across rural United States corridors limiting electric appeal. |
| Geographic Manufacturing Footprint | Localizes assembly in Yangtze River Delta cluster to satisfy China's Ministry of Ecology and Environment quotas. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, fleet operations directors, and dealership operations managers anchored the qualitative base. Primary interview data combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA and California Air Resources Board filings, and customs records. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume assumptions across the analysis window.
Sensitivity analysis tested forecast robustness against battery cost curve trajectories and charging infrastructure deployment rates. The analytical framework modeled crossover demand across vehicle class, propulsion architecture, OEM tier, and regional production cluster throughout the forecast period. CAGRs derived from segment-level volume build-ups incorporating powertrain mix shifts and fleet electrification mandate timelines. Industry-specific inputs included silicon carbide adoption curves and lithium supply chain localization mandates.
Material uncertainties — battery cell availability bottlenecks, divergent crash-test protocol harmonization between NHTSA and NCAP, and residual value realization for electric variants — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding powertrain cost parity and infrastructure buildout rates. Revision becomes warranted when lithium hydroxide spot price volatility or charging network deployment shortfalls cross thresholds that alter fleet procurement commitment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hybrid Vehicles
Hybrid Vehicle Market
Hybrid Vehicles
Smart Hybrid Vehicle Market
Hybrid Vehicles
Germany Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Global Hybrid Vehicle Transmission Market
Hybrid Vehicles
Canada Hybrid Electric Vehicle Battery Market
Hybrid Vehicles
Micro-Hybrid Vehicle Market
Hybrid Vehicles
Asia-Pacific Mild-Hybrid Vehicles Market
Hybrid Vehicles
Asia-Pacific Micro-Hybrid Vehicles Market
Hybrid Vehicles
Crossover Vehicle Market
Hybrid Vehicles
Hydrogen Fuel Automotive Market
Hybrid Vehicles
Hybrid Truck Market
Hybrid Vehicles
Mild Hybrid Vehicles Market
Hybrid Vehicles
Hydrogen Vehicles Market
Hybrid Vehicles
Hybrid Drivetrain Market
Hybrid Vehicles
Hybrid Powertrain Systems Market
Hybrid Vehicles
Hypercar Market