
 Global Pediatric Electrolyte Solutions Market | 2026-2036
Global Pediatric Electrolyte Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pediatric Electrolyte Solutions Market Foresight
Buyer concentration across pediatric electrolyte channels is broadening, with hospital pharmacies losing share to retail pharmacies and online pharmacies as parents seek direct access. Abbott Laboratories leverages its pediatric nutrition infrastructure to sustain shelf presence across multiple continents. Johnson & Johnson competes through brand recognition in fever management formulations. Mead Johnson & Company specializes in infant-specific electrolyte compositions that anchor its position in specialty pharmacies.
Pediatric electrolyte solutions are sterile or non-sterile fluid preparations containing sodium, potassium, chloride, and glucose in ratios calibrated to children's physiological requirements, manufactured through aseptic filling or powder blending processes designed to restore fluid balance during acute gastroenteritis or exertional dehydration. Oral rehydration salts occupy the largest volume position due to WHO endorsement and low production cost, while ready-to-use liquids capture premium margins in emergency care settings. Effervescent tablets represent the fastest-growing product type as portability drives adoption among traveling families and school health programs.
FDA pediatric labeling requirements and EMA's Pediatric Investigation Plans shape formulation development timelines for multinational manufacturers seeking cross-border approval. India's CDSCO enforces BIS quality standards on domestic ORS production, creating compliance barriers for imported alternatives. Stakeholders must monitor evolving pharmacovigilance frameworks for pediatric excipients as regulators tighten safety thresholds for neonatal populations.
Market Dynamics
WHO's low-osmolarity ORS formulation standard is compressing regional formulation variation and forcing multinational manufacturers to consolidate production lines around a single global specification.
Growth Catalysts
- India's National Diarrheal Disease Control Programme:Government procurement of WHO-compliant ORS sachets is creating sustained volume demand that stabilizes manufacturing capacity utilization for domestic producers.
- EMA Pediatric Investigation Plans:Regulatory pathways for pediatric-specific formulations are accelerating clinical validation timelines for electrolyte solutions targeting neonatal populations.
- Effervescent tablet technology:Portable dosage forms are penetrating school health programs and travel medicine kits, expanding addressable use cases beyond acute hospital care.
Market Restraints
- Aluminum hydroxide gel supply concentration:Excipient sourcing for suspension formulations depends on limited Chinese chemical manufacturers, exposing formulators to input volatility.
- FDA pediatric labeling requirements:Extended safety studies for neonatal electrolyte products create multi-year approval bottlenecks that delay market entry for reformulated solutions.
- Home-based hydration monitoring:Parental adoption of smartphone-connected symptom trackers is reducing emergency department visits where premium ready-to-use liquids command higher margins.
Strategic Opportunities
- Sub-Saharan Africa community health worker networks:Last-mile distribution partnerships with government-trained health extension workers offer untapped penetration for powder sachet formats.
- Japan's PMDA pediatric rare disease incentives:Orphan drug designation pathways for electrolyte solutions targeting metabolic disorders provide regulatory fee waivers and priority review.
- Telehealth prescription integration:Direct-to-patient pharmacy fulfillment is bypassing traditional hospital procurement committees for recurring pediatric hydration therapy.
Industry Challenges
- Aseptic filling validation complexity:Ready-to-use liquid manufacturers face extended facility qualification timelines that strain working capital during capacity expansion.
- Cross-jurisdiction pharmacovigilance harmonization:Divergent adverse event reporting standards between FDA and EMA systems complicate post-market surveillance for multinational product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pediatric Electrolyte Solutions Market |
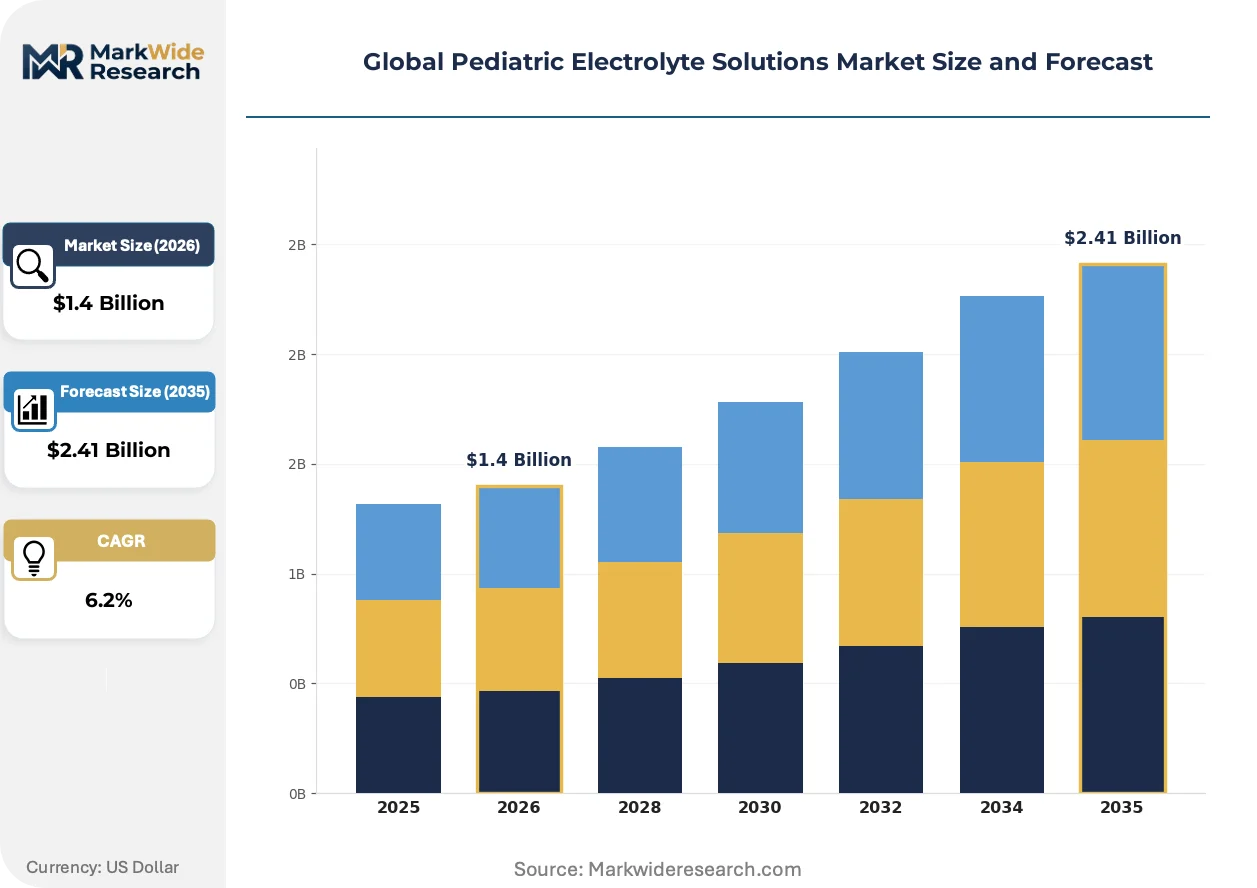
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Rehydration Salts, Intravenous Solutions, Electrolyte Powders, Ready-to-Use Liquids, Effervescent Tablets Application: Dehydration Treatment, Nutritional Supplementation, Electrolyte Imbalance Correction, Fever Management, Diarrhea Management End User: Pediatric Clinics, Specialty Pharmacies, Pediatric Nursing Centers, Home Care Providers, Community Health Centers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Medical Supply Distributors, Pediatric Hospitals |
| Companies Covered | Abbott Laboratories, Johnson & Johnson, Mead Johnson & Company, Otsuka Pharmaceutical, Cera Products, The Hain Celestial Group, Sanofi, Cipla, Monico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pediatric Electrolyte Solutions Market Shifts & Advancements
Formulation science and distribution architecture are converging to reshape how pediatric electrolyte products reach caregivers, with packaging innovation and regulatory science driving competitive differentiation.
Dissolvable film strip technology is automating dose-precision for oral rehydration therapy in ambulatory settings. Community health centers in Kenya and Bangladesh are adopting single-serve strips to eliminate reconstitution errors. This automation is compressing training requirements for frontline health workers and reducing product waste from improperly mixed solutions.
REACH restrictions on microplastic-containing packaging are forcing European manufacturers to accelerate biodegradable sachet development. The industrial consequence is a supply chain reconfiguration toward cellulose-based barrier materials with shorter shelf stability profiles. Pediatric liquid specialists serving EU markets are responding with cold-chain distribution partnerships that offset the reduced packaging protection.
Subscription-based replenishment models are displacing episodic pharmacy purchases for chronic pediatric conditions. Direct-to-consumer channels serving families managing cystic fibrosis or renal disorders are capturing recurring revenue streams. This pattern is most visible in the United States, where specialty pharmacy benefit managers are integrating electrolyte products into disease management programs.
Global Pediatric Electrolyte Solutions Market Segmentation
Pediatric electrolyte solutions fragment across formulation physics, clinical setting, and procurement pathway. Each dimension carries distinct margin structures and regulatory requirements that reshape competitive positioning.
Product Type:
Volume concentrates in low-cost powder formats while premium pools in ready-to-use liquids requiring aseptic manufacturing infrastructure.
- Oral Rehydration Salts:WHO-standard low-osmolarity powder sachets containing sodium chloride, potassium chloride, and trisodium citrate. India's National Diarrheal Disease Control Programme drives procurement volume that stabilizes domestic manufacturing capacity.
- Ready-to-Use Liquids:Pre-mixed sterile solutions in flexible pouches or bottles with calibrated osmolarity for neonatal populations. Emergency departments and pediatric intensive care units absorb premium pricing for immediate administration capability.
- Intravenous Solutions:Sterile electrolyte infusions requiring compounding pharmacy infrastructure or manufacturer-filled bags.
- Electrolyte Powders:Bulk canister formats targeting chronic condition management with flavor masking for pediatric palatability.
- Effervescent Tablets:Portable single-dose formats gaining adoption in school health programs and travel medicine kits across Japan and Germany.
Mature deployment sits with Oral Rehydration Salts. Newer deployment is concentrated in Effervescent Tablets.
Application:
Acute gastroenteritis applications dominate procurement volume while chronic metabolic conditions sustain recurring revenue streams.
- Dehydration Treatment:Acute fluid replacement protocols for viral gastroenteritis, heat exhaustion, or post-surgical recovery. Community health centers in Kenya and Bangladesh deploy single-serve formats to reduce reconstitution errors.
- Diarrhea Management:Standardized oral rehydration therapy following WHO guidelines with zinc supplementation protocols. Government procurement programs in India and Nigeria create sustained demand for low-osmolarity ORS.
- Nutritional Supplementation:Electrolyte-fortified formulations supporting cystic fibrosis or renal disorder management through specialty pharmacy channels.
- Electrolyte Imbalance Correction:Hospital-based correction of hyponatremia or hyperkalemia requiring laboratory monitoring.
- Fever Management:Adjunct hydration support during antipyretic therapy, often bundled with acetaminophen or ibuprofen products.
Volume concentration aligns with Dehydration Treatment. Margin expansion concentrates in Nutritional Supplementation.
End User:
Institutional procurement committees control high-volume purchasing while direct-to-consumer channels fragment buying authority.
- Pediatric Clinics:Outpatient settings managing acute gastroenteritis with point-of-care dispensing. Brazil's SUS network and Mexico's IMSS facilities drive regional procurement patterns.
- Home Care Providers:Visiting nurse services managing chronic pediatric conditions with recurring electrolyte therapy. Subscription models in the United States integrate these products into disease management programs.
- Community Health Centers:Government-funded facilities in sub-Saharan Africa and South Asia distributing ORS through frontline health workers.
- Specialty Pharmacies:Compounding and distribution hubs for complex metabolic conditions requiring custom formulations.
- Pediatric Nursing Centers:Residential care facilities managing long-term hydration for neurologically impaired children.
Procurement authority centralizes with Pediatric Clinics. Patient control is expanding through Home Care Providers.
Distribution Channel:
Hospital pharmacy gatekeeping is eroding as retail and digital channels capture caregiver-directed purchasing.
- Hospital Pharmacies:Formulary-controlled dispensing within acute care institutions with committee-driven generic substitution. EMA and FDA pediatric labeling requirements shape stocked inventory.
- Online Pharmacies:Direct-to-patient fulfillment bypassing traditional procurement committees for recurring prescriptions. Telehealth integration accelerates adoption in the United States and United Kingdom.
- Retail Pharmacies:Over-the-counter and pharmacist-counseled sales of ORS and ready-to-use liquids. India's Apollo Pharmacy and CVS Health in the United States anchor shelf presence.
- Medical Supply Distributors:Bulk logistics providers serving institutional accounts with cold-chain capabilities for liquid formulations.
- Pediatric Hospitals:Specialized children's medical centers with dedicated pharmacy compounding for neonatal populations.
Traditional concentration rests with Hospital Pharmacies. Channel expansion is accelerating through Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum hydroxide gel production clusters in eastern China supply suspension formulation excipients to manufacturers worldwide. Sodium chloride and potassium sourcing from Gujarat and Rajasthan feeds India's domestic ORS production. Glucose feedstock from Brazilian sugarcane mills supports Latin American formulation capacity.
United States
Pediatric specialty pharmacies in Boston and Philadelphia anchor recurring revenue for chronic condition management. FDA pediatric labeling requirements extend approval timelines for neonatal electrolyte formulations. Cold-chain distribution partnerships from Memphis logistics hubs serve institutional accounts across the Southeast.
Germany
Effervescent tablet adoption in Munich and Hamburg school health programs drives portable format demand. EMA Pediatric Investigation Plans accelerate clinical validation for metabolic disorder applications. REACH microplastic packaging restrictions force cellulose-based sachet development in the Ruhr industrial region.
India
Government procurement through the National Diarrheal Disease Control Programme stabilizes manufacturing capacity for domestic ORS producers. CDSCO enforces BIS quality standards that limit imported alternatives. Hyderabad and Ahmedabad house formulation facilities serving sub-Saharan African export markets.
Japan
PMDA orphan drug incentives attract electrolyte solutions targeting pediatric rare metabolic disorders. Tokyo-based pharmaceutical distributors integrate telehealth prescriptions into direct-to-patient fulfillment. Osaka manufacturing clusters specialize in single-serve dissolvable film strip production.
Brazil
SUS network procurement through São Paulo and Rio de Janeiro pediatric clinics drives regional volume patterns. ANVISA bioequivalence requirements shape generic substitution in hospital formularies. Sugar-based glucose sourcing from São Paulo state ethanol mills reduces raw material import dependency.
Global Pediatric Electrolyte Solutions Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue portable dosage formats and subscription-based chronic care models. The vendor base spans multinational nutrition conglomerates, regional pharmaceutical specialists, and direct-to-consumer wellness brands. Three archetypes dominate: hospital formulary incumbents with pediatric infrastructure, emerging digital health integrators, and commodity ORS manufacturers serving government tenders. Competitive moves concentrate on aseptic capacity expansion and last-mile distribution partnerships with community health networks.
Within the hospital formulary tier, Abbott Laboratories and Johnson & Johnson exemplify incumbents leveraging existing pediatric infrastructure across multiple continents. Mead Johnson & Company occupies a specialist position in infant-specific compositions. Among Asia-Pacific producers, Otsuka Pharmaceutical and Cipla represent regional pharmaceutical houses with government tender expertise. These named entities anchor competitive dynamics without exhaustive enumeration of strategic initiatives.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Johnson & Johnson |
| Mead Johnson & Company |
| Otsuka Pharmaceutical |
| Cera Products |
| The Hain Celestial Group |
| Sanofi |
| Cipla |
| Monico |
| Others |
Supply & Pricing Matrix
Sodium chloride feedstock price indices from Gujarat and Rajasthan mineral processors cascade through pediatric electrolyte manufacturing into three-tier pricing structure across premium, standard, and economy levels. WHO-compliant oral rehydration salts anchor the economy tier through government tender volumes, while aseptic ready-to-use liquids command premium positioning in emergency departments where immediate administration capability bundles with clinical service protocols.
Pricing Analysis
Warranty and cold-chain integrity guarantees differentiate premium ready-to-use liquids from unbundled powder sachets sold through retail channels. Pricing stratifies across premium, standard, and economy tiers based on aseptic certification grade and volume procurement scale. Cost compression in the standard tier is intensifying because EMA Pediatric Investigation Plans extend validation timelines for neonatal formulations. Government procurement committees in India and Nigeria exhibit lowest price sensitivity, while direct-to-consumer subscription buyers in the United States demonstrate willingness to pay for convenience bundling.
Supply Chain Analysis
Regional distribution centers in Hyderabad, Ahmedabad, and eastern China warehouse aluminum hydroxide gel and potassium chloride feedstocks for just-in-time formulation. Active pharmaceutical ingredient sourcing draws from Gujarat chemical manufacturers, Chinese excipient specialists, and Brazilian glucose refiners. Single-source vulnerability concentrates in aluminum hydroxide gel supply from limited Chinese chemical producers. Distribution runs through medical supply distributors with cold-chain capabilities for liquid formulations, supplemented by direct-to-patient pharmacy fulfillment for chronic condition management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric electrolyte manufacturing operates as a cost-of-compliance market where FDA pediatric labeling requirements and EMA Pediatric Investigation Plans erect multi-year approval barriers that protect validated incumbents from rapid competitive entry.
For Market Incumbents: Lock in aseptic filling capacity expansion in India and Brazil before CDSCO and ANVISA tighten facility qualification standards. Secure backward integration into potassium chloride sourcing from Rajasthan mineral processors to buffer against Chinese excipient volatility. Defend against effervescent tablet entrants by co-developing dissolvable film strip formats with Osaka manufacturing clusters. For New Entrants and Emerging Players: Telehealth-integrated pharmacy fulfillment offers the lowest barrier-to-entry route for recurring pediatric hydration therapy subscriptions in the United States and United Kingdom. Target nutritional supplementation for cystic fibrosis and renal disorder management through specialty pharmacy benefit managers. Deploy single-serve powder sachets through sub-Saharan African community health worker networks as the most penetrable geography. For Investors and Strategic Acquirers: Distressed-cycle entries favor aseptic liquid specialists with validated FDA master files in the United States Southeast and Midwest manufacturing corridors. Long-term viability hinges on regulatory moat durability rather than commodity ORS volume exposure. Monitor EMA-FDA pharmacovigilance harmonization progress as the critical signal for multinational portfolio scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Capacity Expansion | CDSCO and ANVISA facility qualifications in Hyderabad and São Paulo anchor regional supply security. |
| Backward Integration into Excipients | Rajasthan potassium chloride sourcing reduces dependency on Chinese aluminum hydroxide gel concentration. |
| Dissolvable Film Strip Development | Osaka manufacturing partnerships with Kenyan and Bangladeshi health programs automate dose-precision. |
| Telehealth Pharmacy Integration | Direct-to-patient fulfillment bypasses hospital procurement committees for chronic condition subscriptions. |
| Community Health Worker Partnerships | Last-mile distribution through government-trained extension workers penetrates sub-Saharan African markets. |
Research Methodology
Document review covered WHO guideline repositories, FDA pediatric labeling databases, EMA Pediatric Investigation Plan filings, and CDSCO manufacturing facility registrations, complemented by interviews with pharmaceutical regulatory affairs directors, hospital formulary managers, pediatric intensive care clinicians, and community health program procurement officers. Secondary validation drew from customs trade data, SEC 10-K pharmaceutical segment disclosures, and government tender documentation from India's National Diarrheal Disease Control Programme. Bottom-up volume modeling triangulated against top-down market sizing across formulation physics and procurement pathway dimensions.
Output generation employed multivariate segmentation across product type, application, end user, and distribution channel dimensions over the projection horizon. CAGRs derived from regression analysis of historical procurement volume patterns and regulatory approval pipeline velocity. Key inputs included WHO formulation standard adoption curves, government tender award frequencies, and cold-chain infrastructure expansion rates in target geographies.
The model holds under stable regulatory harmonization between FDA and EMA systems; deviation in pharmacovigilance reporting standard divergence or excipient supply disruption would shift capacity utilization assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Bipolar Disorder Drugs and Treatment Market
Pharmaceuticals
Asia-Pacific Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Antithrombin Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
Sleeping Medications Market