
 Unfinished Wood Furniture Market | 2026-2036
Unfinished Wood Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Unfinished Wood Furniture Market Analytics
Engineered wood substrates is recalibrating cost structures across the unfinished furniture supply chain. Vermont Furniture Designs leverages Appalachian hardwood sourcing to sustain premium positioning in the solid-wood segment. Sauder Woodworking anchors mass-market volume through integrated particleboard milling and retail distribution. Sierra Pacific Industries controls vertical timber supplies from California forests to finished-goods channels.
Unfinished wood furniture comprises solid timber or veneer-core pieces supplied without surface coatings, stains, or sealants, typically featuring joinery-grade kiln-dried stock with moisture content between 6% and 10% for dimensional stability. The category serves consumers and contractors who apply custom finishes to match interior palettes or achieve specific durability ratings. Residential end users dominate volume within the end-user taxonomy, while the hospitality segment captures expanding share as boutique hotels specify bespoke finishing programs. Oak and maple material grades command margin premiums over pine due to hardness ratings and grain consistency prized by professional finishers.
EPA TSCA Title VI limits formaldehyde emissions from composite wood substrates, pushing manufacturers toward certified low-emission glues and core materials. FSC chain-of-custody standards govern sustainable sourcing claims in North American distribution, with CARB ATCM requirements extending compliance obligations for California-bound shipments. Stakeholders must monitor evolving state-level chemical disclosure rules and certify supply chains before retailer mandates tighten procurement eligibility.
Market Dynamics
EPA TSCA Title VI formaldehyde emission limits are compressing substrate options for domestic manufacturers, forcing recalibration of engineered wood sourcing strategies and cost structures across the unfinished furniture supply chain.
Growth Catalysts
- DIY Home Renovation Surge:Residential consumers in the United States are expanding purchases of customizable pieces to match interior palettes, sustaining category momentum through home improvement cycles.
- FSC Chain-of-Custody Certification:Sustainable sourcing standards are opening retail distribution channels that mandate documented timber provenance for private-label programs.
- Boutique Hospitality Specification:Hotels are adopting bespoke finishing programs for guest room furniture, creating demand for joinery-grade kiln-dried stock with moisture content precision.
Market Restraints
- Composite Wood Compliance Costs:CARB ATCM requirements for California-bound shipments add testing and documentation burdens that compress margins on particleboard-based products.
- Appalachian Hardwood Supply Concentration:Premium solid-wood sourcing clusters in specific eastern US forest regions, creating vulnerability to regional weather disruptions and logging constraints.
- Substitute Material Competition:Metal and molded polymer furniture alternatives are capturing price-sensitive segments that prioritize immediate durability over customization potential.
Strategic Opportunities
- Underpenetrated Western States:California and Pacific Northwest markets show lower unfinished furniture penetration relative to national averages, presenting whitespace for specialized retailers.
- Online Finish-Customization Platforms:Digital visualization tools are enabling direct-to-consumer channels that guide buyers through stain selection before shipment.
- Low-Emission Adhesive Innovation:Soy-based and bio-derived glue technologies are qualifying manufacturers for emerging green building specification programs.
Industry Challenges
- Professional Finisher Skill Scarcity:The contracting pool of craftsmen proficient in traditional joinery and surface preparation is constraining quality consistency in custom applications.
- Legacy ERP Integration Friction:Inventory management systems designed for finished goods struggle to track moisture-content variations and grade-specific SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Unfinished Wood Furniture Market |
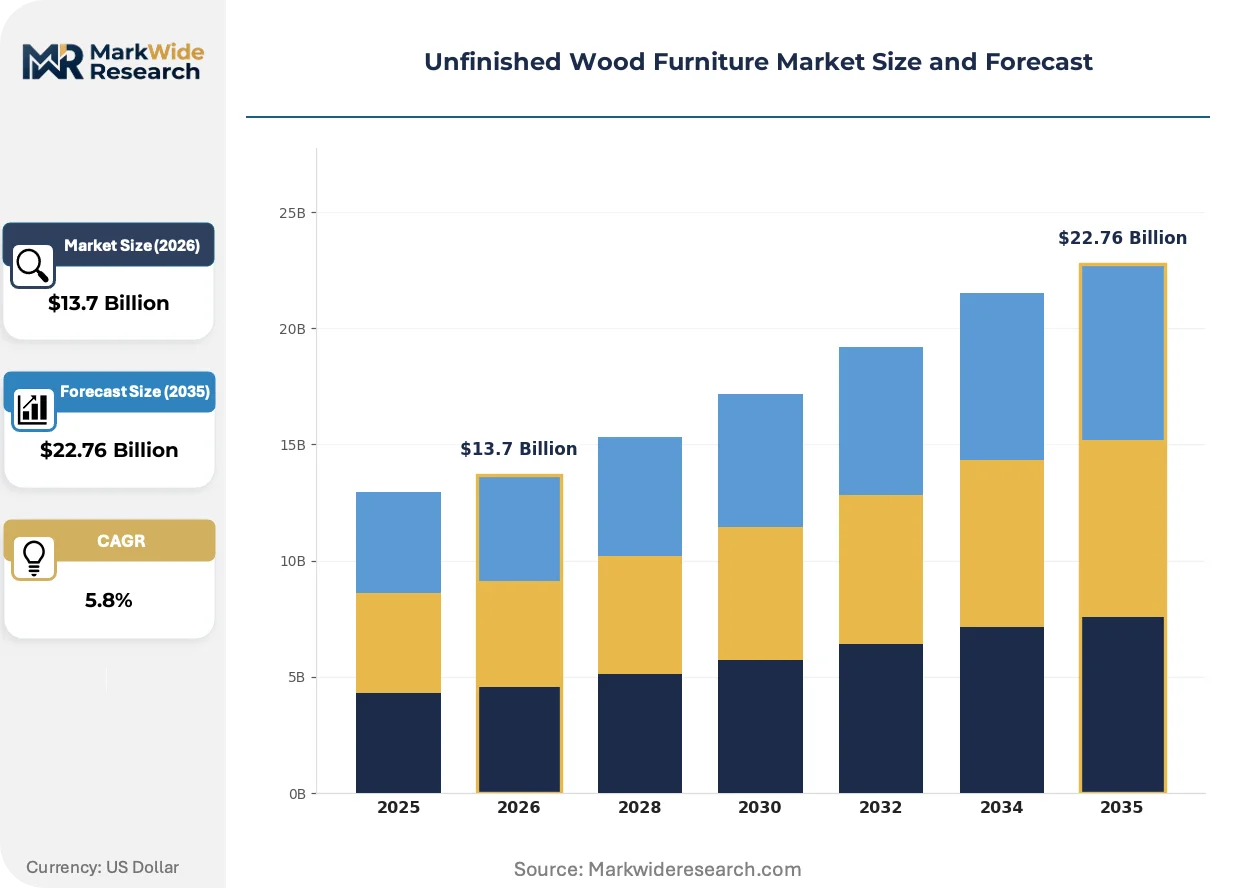
| Market Size in 2026 | $13.7 Billion |
| Market Size in 2035 | $22.76 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chairs, Tables, Cabinets, Shelves End User: Residential, Commercial, Educational, Hospitality Material: Oak, Pine, Maple, Birch Distribution Channel: Online Retail, Furniture Showrooms, Specialty Stores, Wholesale |
| Companies Covered | Vermont Furniture Designs (USA), Sauder Woodworking (USA), Unfinished Furniture (USA), West Fraser Timber Co. Ltd. (Canada), Sierra Pacific Industries (USA), Copeland Furniture (USA), Lyndon Furniture (USA), Interfor Corporation (Canada), Maple Corner Woodworks (USA), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Unfinished Wood Furniture Market Evolving Landscape
Digital finishing visualization and automated moisture monitoring are compressing the traditional gap between raw material supply and consumer-ready customization, reshaping how unfinished furniture reaches end users.
Near-infrared moisture sensors are integrating into kiln-drying operations to maintain 6% to 10% target ranges with real-time feedback loops. Large-scale distributors are adopting this technology to reduce dimensional stability claims and returns. The capability is integrating quality assurance directly into logistics workflows, compressing inspection timelines from days to hours.
EPA enforcement of TSCA Title VI is tightening documentation requirements for composite wood products entering interstate commerce. Domestic manufacturers must maintain certified low-emission glue records and third-party laboratory test results. California retailers are responding by pre-qualifying suppliers with existing CARB ATCM compliance infrastructure, creating a two-tier procurement landscape.
Contractor purchasing patterns are fragmenting as boutique finishers bypass traditional distribution to source directly from Appalachian sawmills. This disintermediation is compressing wholesale margins while rewarding suppliers with documented chain-of-custody credentials. The shift is most visible in the Mid-Atlantic region, where custom home builders specify unfinished oak and maple for high-end residential projects.
Unfinished Wood Furniture Market Segmentation
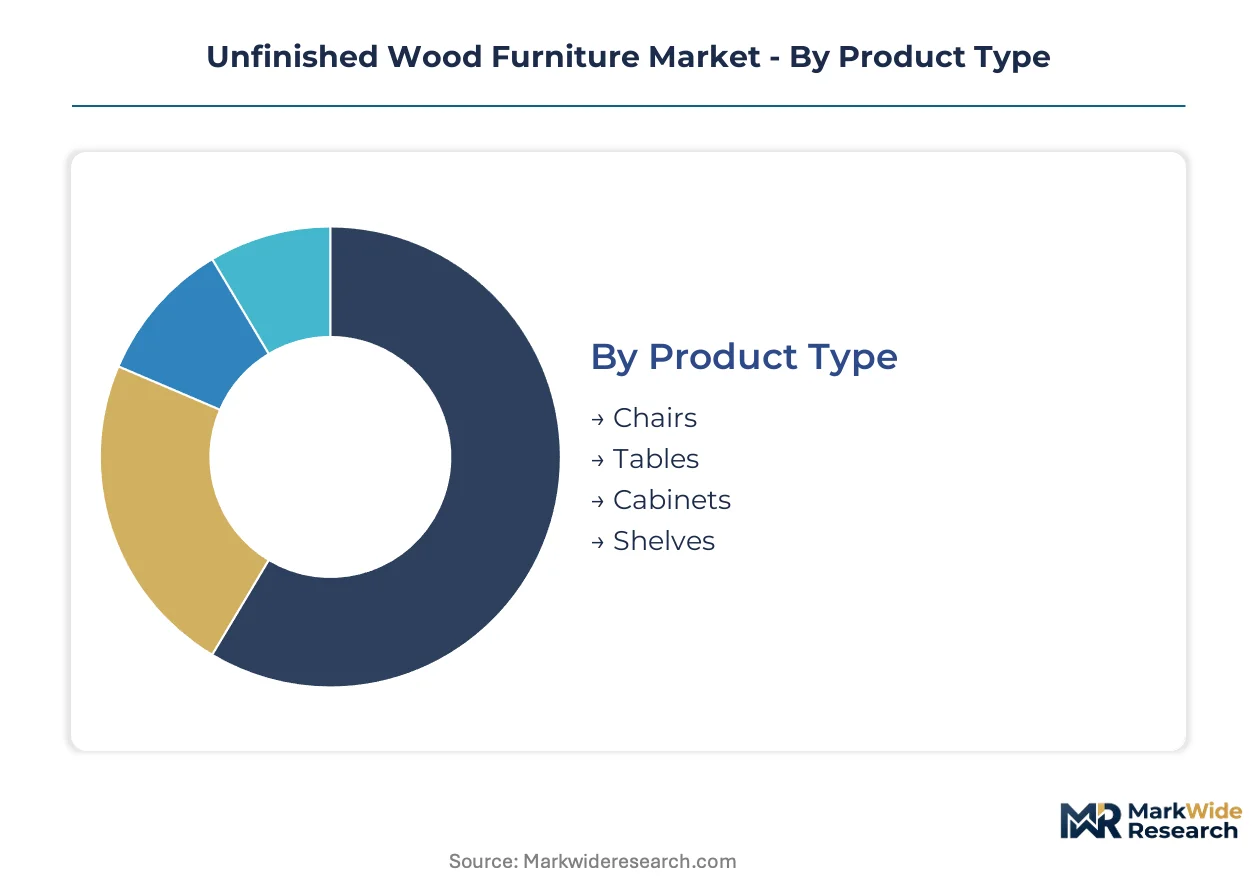
Unfinished wood furniture manufacturers configure production lines around material grades and moisture-content tolerances that vary sharply by product type. Segmentation discipline determines which SKUs warrant kiln-drying investment versus commodity outsourcing.
Product Type:
Capital intensity peaks with cabinets requiring precision joinery and dimensional stability across seasonal humidity swings.
- Chairs:Seat frames and back slats demand hardwood stock rated for repetitive stress loading. Demand clusters with residential buyers seeking heirloom-grade pieces in the United States. EPA TSCA Title VI compliance costs compress margins on composite-core dining chair production.
- Tables:Panel construction requires moisture-content uniformity between 6% and 10% to prevent warping after customer-applied finishes. Hospitality procurement teams in boutique hotel chains specify joinery-grade maple for dining surfaces. CARB ATCM documentation burdens favor domestic sawmill-direct sourcing over import channels.
- Cabinets:Box construction tolerances drive investment in CNC routing and vacuum-press veneer systems.
- Shelves:Span-load ratings determine material thickness specifications and bracket compatibility.
Most installed capacity flows through Tables. Expansion is steepest in Cabinets.
End User:
Volume concentration and margin structure diverge sharply between price-sensitive institutional buyers and customization-driven residential segments.
- Residential:DIY finishers purchase through specialty retailers seeking stain-grade oak and maple with documented kiln-drying records. Home renovation cycles in the United States sustain reorder velocity for bedroom and dining furniture. FSC chain-of-custody certification opens private-label distribution at premium home improvement chains.
- Hospitality:Boutique hotel operators specify unfinished stock for on-site finishing programs matching interior design palettes. Moisture-content precision requirements exceed residential standards to prevent guest room warranty claims. Direct sourcing from Appalachian sawmills is displacing wholesale distribution in the Mid-Atlantic corridor.
- Commercial:Office furniture procurement prioritizes immediate durability over customization potential.
- Educational:Institutional purchasing favors particleboard alternatives for cost containment in high-wear environments.
Residential captures the dominant revenue share. Hospitality is climbing the fastest as bespoke specification programs proliferate.
Material:
Hardness ratings and grain consistency determine which species command finishing-grade premiums versus construction-tier positioning.
- Oak:Open grain structure accepts stain penetration predictably, prized by professional finishers for color consistency. White oak demand concentrates in high-end residential kitchens and hospitality dining venues. Regional sourcing from Appalachian forests creates supply vulnerability to logging constraints and weather disruptions.
- Maple:Closed grain and hardness rating suit furniture subject to abrasion and moisture exposure. Hard maple specifications dominate cutting boards, work surfaces, and institutional furniture requiring durability certification. Canadian and northern United States sawmills control premium-grade supply.
- Pine:Softwood pricing penetrates mass-market channels with paint-grade applications.
- Birch:Fine, even grain serves as a stain-grade alternative at lower hardness ratings than maple.
Oak commands the highest unit margins. Maple is gaining share fastest in hospitality and commercial specifications.
Distribution Channel:
Channel selection determines documentation burdens, moisture-content liability exposure, and finish-customization support requirements.
- Specialty Stores:Staffed showrooms provide hands-on grain inspection and stain-sample matching for discerning residential buyers. These retailers demand EPA TSCA Title VI compliance documentation and FSC chain-of-custody certificates as table stakes for shelf placement. Geographic concentration in the United States Northeast and Midwest reflects historic furniture manufacturing corridors.
- Online Retail:Digital visualization tools now guide stain selection before shipment, compressing the traditional showroom dependency. Direct-to-consumer channels bypass wholesale markups but assume dimensional stability liability and return logistics costs. California and Pacific Northwest markets show underpenetration relative to national averages, presenting whitespace for specialized e-commerce entrants.
- Furniture Showrooms:Full-line retailers cross-sell unfinished pieces with finishing service referrals.
- Wholesale:Contractor-grade volume moves through distribution centers serving home builders and renovation specialists.
Specialty Stores retain the highest value throughput. Online Retail is expanding most quickly as visualization technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appalachian hardwood clusters anchor North American unfinished furniture production, with kiln-drying infrastructure concentrated in Vermont, Pennsylvania, and North Carolina. Regulatory frameworks governing formaldehyde emissions and sustainable sourcing create divergent compliance burdens across national boundaries.
United States
DIY renovation cycles in the Northeast and Midwest sustain specialty retailer demand for stain-grade oak and maple. EPA TSCA Title VI enforcement tightens documentation requirements for composite wood substrates crossing state lines. The Vermont furniture corridor maintains premium solid-wood finishing through documented Appalachian timber provenance and precision moisture-content controls.
Canada
Hard maple supply from Quebec and Ontario sawmills feeds cross-border hospitality specifications requiring abrasion-resistant surfaces. Health Canada aligns with EPA emission benchmarks for imported particleboard components. British Columbia interior manufacturers leverage coastal shipping routes to supply unfinished stock to Pacific Northwest renovation contractors.
Germany
Engineered wood technology leadership in Baden-Württemberg drives adhesive innovation qualifying for EU Green Deal procurement criteria. ECHA REACH compliance governs chemical disclosure in finishes applied to imported unfinished stock. The Black Forest furniture tradition sustains artisan-grade demand for beech and ash joinery components.
China
Mass-market unfinished furniture exports concentrate in Zhejiang and Guangdong provinces serving price-sensitive North American retail channels. GB standards for formaldehyde emissions in man-made boards lag EPA thresholds, creating certification gaps for California-bound shipments. Yangtze River Delta manufacturers invest in CARB ATCM-compliant production lines to retain US market access.
India
Teak and rosewood finishing-grade timber from Kerala and Karnataka supplies domestic hospitality renovation and limited export channels. BIS certification requirements for wood-based panel products tighten substrate quality norms for institutional procurement. Punjab furniture clusters specialize in paint-grade pine for budget residential segments.
Unfinished Wood Furniture Market Competitive Landscape
Global majors compete with regional champions across substrate technology and sustainable sourcing credentials. The vendor base organizes around three tiers: integrated timber-to-furniture operators controlling Appalachian supply chains, mass-market particleboard specialists serving big-box retail, and boutique artisan workshops commanding premium positioning. Competitive moves center on CARB ATCM pre-certification to secure California distribution and direct-to-consumer digital platforms bypassing wholesale markups.
Among North American fabricators, Vermont Furniture Designs and Sauder Woodworking exemplify divergent scale archetypes, while Sierra Pacific Industries anchors vertical timber control from California forests to finished-goods channels. Canadian operators West Fraser Timber and Interfor Corporation represent cross-border supply integration. These entities occupy positions spanning premium solid-wood heritage positioning at one extreme and engineered-substrate mass production at the other.
| Leading Market Players |
|---|
| Vermont Furniture Designs |
| Sauder Woodworking |
| Unfinished Furniture |
| West Fraser Timber Co. Ltd. |
| Sierra Pacific Industries |
| Copeland Furniture |
| Lyndon Furniture |
| Interfor Corporation |
| Maple Corner Woodworks |
| Others |
Value Network & Pricing Analysis
Family-owned Appalachian sawmill operators anchor premium-grade hardwood supply, enabling disciplined margin maintenance through direct-to-contractor channels that bypass wholesale markups. Their ownership structure supports patient capital allocation toward kiln-drying infrastructure, insulating pricing power from commodity volatility while compressing delivery timelines for stain-grade oak and maple specifications.
Pricing Analysis
Input-cost pass-through from certified low-emission adhesives and FSC chain-of-custody documentation flows unevenly across product tiers. Three-tier pricing structure across premium, standard, and economy levels separates Appalachian-sourced solid wood from particleboard alternatives and import-grade pine. Pricing pressure stems from CARB ATCM compliance burdens on composite substrates serving California-bound shipments. Residential DIY buyers exhibit highest price sensitivity, while boutique hospitality procurement teams absorb premiums for documented moisture-content precision.
Supply Chain Analysis
Regional distribution centers in Vermont, Pennsylvania, and North Carolina form a hub-and-spoke pattern radiating toward Mid-Atlantic and Northeast metro corridors. Supply draws from United States Appalachian forests, Canadian Quebec and Ontario sawmills, and limited Scandinavian birch imports. Dependencies center on kiln-dried hardwood stock, soy-based adhesive formulations, and moisture-content monitoring equipment. Single-source vulnerability concentrates in Appalachian oak supply exposed to regional weather disruptions. Distribution runs through specialty retailer networks with growing direct-to-consumer bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The unfinished wood furniture market functions as a stable compounder underpinned by durable DIY renovation cycles in United States residential construction. Home improvement expenditure patterns sustain reorder velocity across economic phases, anchoring predictable cash flow generation for positioned operators.
For Market Incumbents: Anticipate disintermediation pressure from boutique finishers sourcing direct at Appalachian sawmills by deepening captive timber holdings and pre-qualifying CARB ATCM compliance documentation ahead of retailer procurement mandates. Prioritize ERP modernization to track moisture-content SKU proliferation and grade-specific inventory positions. Vertical integration into kiln-drying infrastructure defends margin capture against wholesale compression. For New Entrants and Emerging Players: Direct-to-consumer digital platforms with integrated stain-visualization tools offer the lowest-friction entry vector. Target underpenetrated California and Pacific Northwest markets where specialty retailer density lags national benchmarks. White-space exists in hospitality-focused moisture-content certification services and contractor-grade volume aggregation for Mid-Atlantic custom home builders. For Investors and Strategic Acquirers: Private-equity firms with home improvement portfolio exposure are the most active acquirer in this space, rolling up regional sawmill operators and specialty retailers into integrated platforms. Five-to-ten year viability rests on sustainable sourcing credential scarcity and EPA enforcement tightening. Monitor CARB ATCM pre-certification penetration rates among mid-tier particleboard fabricators as inflection signal for regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Holdings | Captive Appalachian hardwood supply insulates margin pressure from logging constraint volatility. |
| Direct-to-Consumer Digital Launch | Stain-visualization platforms compress showroom dependency and capture wholesale bypass economics. |
| CARB ATCM Pre-Certification Investment | California retailer mandates create two-tier procurement eligibility favoring early compliance adopters. |
| Low-Emission Adhesive R&D Partnership | Soy-based glue innovation qualifies manufacturers for emerging green building specification programs. |
| Hospitality-Focused Certification Service | Moisture-content precision documentation commands premium positioning in boutique hotel procurement. |
Research Methodology
Direct dialogue with sawmill operations managers, specialty retailer category buyers, hospitality procurement directors, and custom home builder contractors grounded qualitative findings in operational reality. Secondary validation drew from EPA TSCA Title VI enforcement records, FSC chain-of-custody databases, United States Census Bureau furniture manufacturing shipments, and Appalachian hardwood trade association production surveys. Bottom-up SKU-level volume aggregation triangulated against top-down regional expenditure modeling.
Bottom-up demand modeling by product type, material grade, end-user segment, and distribution channel structured analytical discipline across the projection horizon. CAGRs derived from segment-level growth rate assumptions calibrated to historical renovation cycle patterns and regulatory compliance cost trajectories. Forecast inputs incorporated kiln-drying capacity expansion timelines, CARB ATCM documentation adoption curves, and digital channel penetration rates.
Regulatory enforcement intensity shifts, Appalachian weather disruption frequency, and substitute material technology advances are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Chair Hardware Market
Furniture
Entryway Furniture Market
Furniture
Spain Furniture Market
Furniture
Eco-Friendly Furniture Market
Furniture
China Home Furniture Market
Furniture
Ergonomic Chair Market
Furniture
Global Furniture Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
Pool Tables Market
Furniture
Rattan Furniture Market
Furniture
North America Home Furniture Market
Furniture
Europe Sustainable Office Furniture Market
Furniture
Piano Stools Market
Furniture
Global Home Furniture Market
Furniture
Europe Sustainable Home Furniture Market
Furniture
Global Smart Furniture Market