
 Spain Furniture Market | 2026-2036
Spain Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Furniture Market Outlook
Certified sustainable-grade upholstery is reorganizing competitive priorities across the Spain Furniture Market. Gandía Blasco leverages its Mediterranean manufacturing base to dominate outdoor and contract segments with integrated textile production. Andreu World anchors its position through in-house aluminum recycling and cradle-to-cradle certification programs. Kettal differentiates via technology leadership in weather-resistant synthetic weaving and powder-coat finishing systems.
Spain furniture encompasses movable objects designed for human support, storage, and spatial organization, typically constructed from engineered wood panels, solid timber, extruded aluminum, or thermoformed polymers with specified load-bearing tolerances and surface durability ratings. The primary commercial purpose spans residential interior fit-out, hospitality outfitting, and workplace configuration. Sofas and chairs capture the largest share of residential margin pools, while cabinets and storage systems generate steadier commercial demand through office refurbishment cycles. Wood and metal materials lead volume, though fabric-upholstered segments command premium positioning in hospitality and high-end residential channels.
Spain's national construction regulator enforces Technical Building Code provisions that affect furniture anchoring, fire resistance, and indoor air quality standards for installed fixtures. The EU Ecodesign Directive and REACH chemical restrictions shape material sourcing compliance costs for manufacturers serving public procurement channels. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and building renovation wave funding allocations to align product portfolios with regulatory and incentive trajectories.
Market Dynamics
The Spain Furniture Market faces intensifying pressure from the EU Green Deal's material disclosure mandates, which now require cradle-to-cradle documentation for all public procurement contracts exceeding threshold values. This regulatory compression is forcing manufacturers to restructure supply chains around certified sustainable inputs or forfeit access to hospitality and institutional channels.
Growth Catalysts
- Building renovation wave funding:Spain's allocation of NextGenerationEU recovery funds toward energy-efficient building retrofits is generating replacement demand for fixed and loose furnishings across residential and commercial stock.
- Technical Building Code enforcement:Fire resistance and indoor air quality standards for installed fixtures are tightening specification requirements, favoring domestic manufacturers with certified testing capabilities over import-dependent competitors.
- Hospitality procurement:Coastal tourism corridor expansion in Andalusia and the Balearic Islands is driving contract furniture volumes for hotel fit-outs and restaurant refurbishments.
Market Restraints
- Engineered wood panel cost volatility:Birch and beech veneer supply from Baltic states faces price instability due to logging restrictions and transport capacity constraints.
- Aluminum extrusion concentration:Spain's contract furniture sector relies on a limited set of European smelters for structural profiles, creating vulnerability to energy cost spikes.
- REACH compliance friction:Chemical restriction updates for flame retardants and surface coatings impose reformulation costs that disproportionately burden small-batch producers.
Strategic Opportunities
- Extended Producer Responsibility frameworks:Pending national implementation of furniture take-back mandates creates first-mover advantage for brands establishing reverse logistics networks.
- Modular workplace systems:Hybrid office configurations are driving demand for reconfigurable workstation platforms that adapt to density fluctuations without full replacement.
- Catalonia manufacturing cluster:Barcelona's concentration of textile finishing and metalworking capabilities supports integrated production of certified sustainable upholstery for export markets.
Industry Challenges
- Cradle-to-cradle certification timelines:Third-party verification cycles for material health and recyclability claims extend product development schedules by 8-14 months.
- Digital twin integration:Specifiers now require BIM-compatible product libraries, forcing legacy manufacturers to rebuild technical documentation from component-level data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Furniture Market |
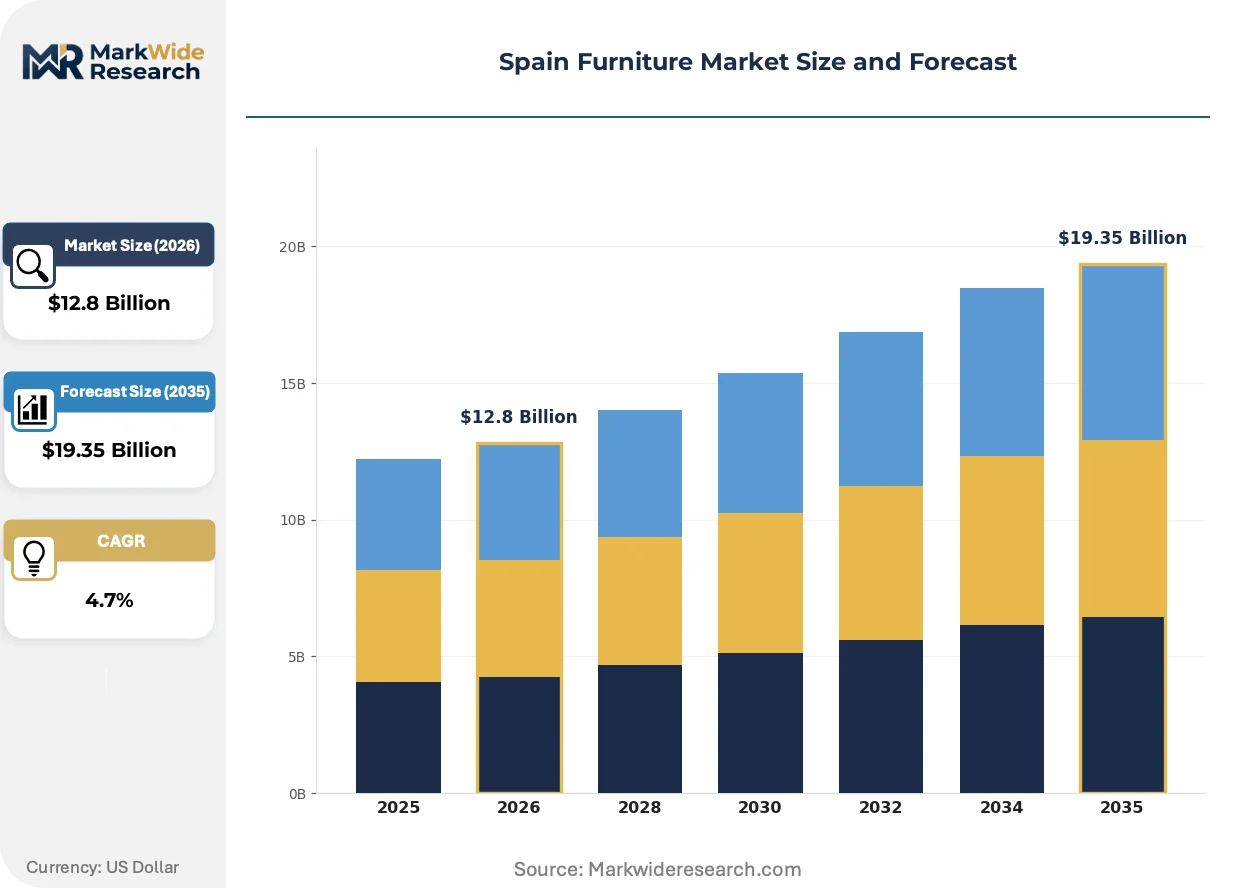
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Tables, Chairs, Cabinets Material: Wood, Metal, Plastic, Fabric End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Gandía Blasco, Capdell, Andreu World, Viccarbe, Ondarreta, Kettal, Doca, Beltá Frajumar, Sancal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Furniture Market Strategic Shifts
Spain's furniture sector is experiencing accelerated technology adoption as regulatory compliance and buyer specification requirements converge. Manufacturers are restructuring production systems around traceable material flows and digital product passports.
Thermoformed recycled polymer sheet is decomposing traditional plywood and MDF dominance in seating shells and tabletops. Hospitality specifiers in Madrid and Barcelona are specifying these materials for durability and cleanability advantages. The technology is decomposing established supply relationships with Nordic particleboard suppliers and compressing lead times for custom color matching.
Spain's national building regulator enforces updated Technical Building Code provisions aligning with EU Ecodesign Directive requirements for indoor air quality and fire performance. Manufacturers serving public procurement channels must now submit material health declarations and end-of-life handling protocols. The contract segment faces the steepest compliance burden, with municipal and healthcare buyers rejecting bids lacking third-party environmental product declarations.
Specifier buying patterns are compressing traditional distribution layers as architecture firms and procurement consortia demand direct manufacturer relationships for large-scale fit-out projects. Valencia and Seville hospitality developers are bypassing regional distributors to negotiate volume contracts with production facilities. This disintermediation concentrates margin pressure on wholesale intermediaries while rewarding vertically integrated producers with specification support capabilities.
Spain Furniture Market Segmentation
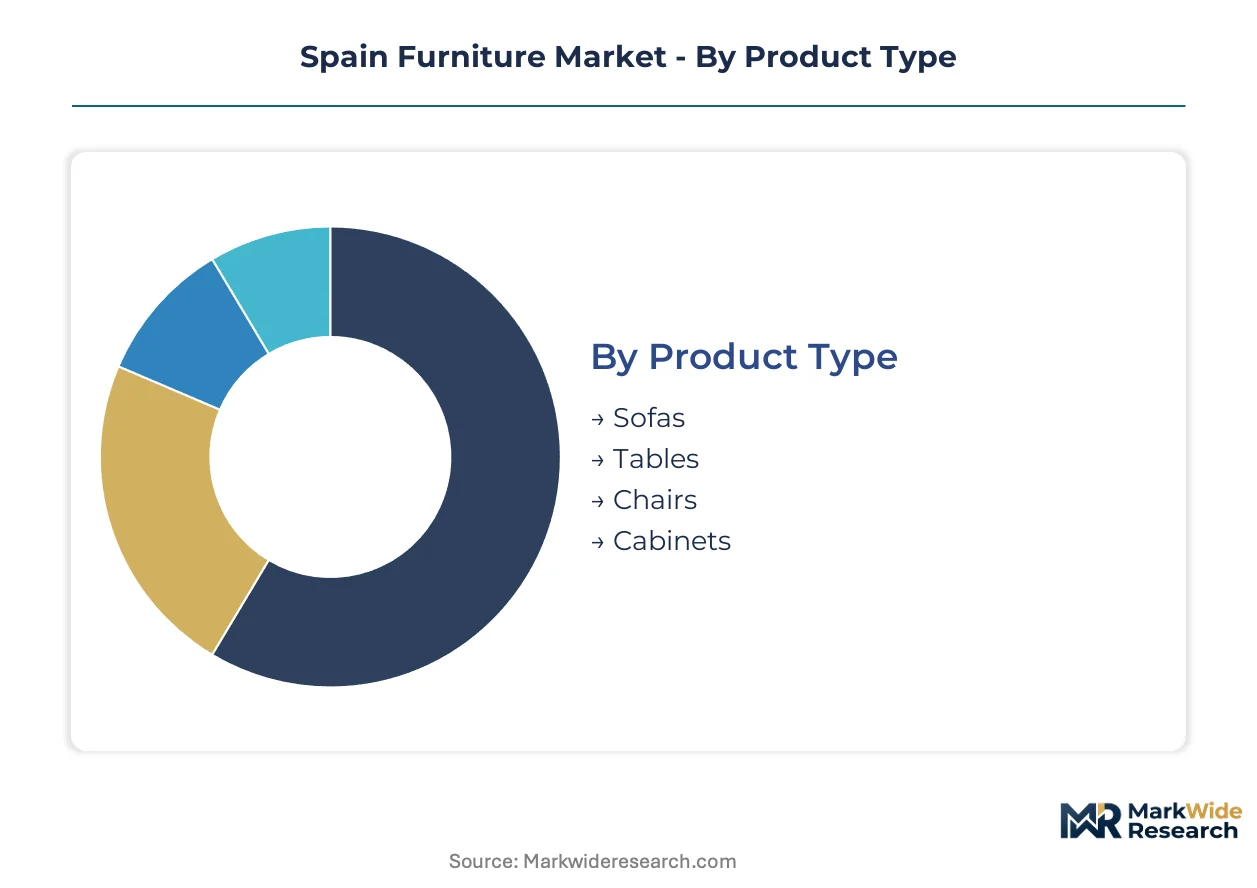
Spain's furniture market segments reflect distinct procurement pathways. Public contract channels favor certified materials with documented cradle-to-cradle credentials. Residential channels prioritize aesthetic differentiation and price accessibility across multiple touchpoints.
Product Type:
Channel mix varies sharply by product category. Sofas and chairs flow primarily through retail showrooms and direct-to-consumer platforms. Tables and cabinets concentrate in contract channels for hospitality and workplace fit-outs.
- Sofas:Multi-component upholstered systems combining engineered wood frames, suspension mechanisms, and fabric or leather coverings. Madrid and Barcelona residential developers specify these for premium apartment fit-outs where fire resistance certification is mandatory.
- Chairs:Seating products span dining, office, and outdoor configurations with load-bearing ratings from 110kg to 150kg. Hospitality procurement in Andalusia and the Balearic Islands drives demand for stackable, weather-resistant contract variants with powder-coated aluminum frames.
- Tables:Surface products for dining, work, and meeting applications.
- Cabinets:Storage systems including wardrobes, sideboards, and shelving units.
By volume, cabinets lead through wholesale and retail channels. By growth pace, sofas are ahead on hospitality refurbishment cycles.
Material:
Cost tier stratification defines material selection patterns. Premium specifications absorb certified sustainable inputs at higher price points. Standard and economy tiers rely on conventional engineered panels and commodity metals.
- Wood:Solid timber and engineered panels including particleboard, MDF, and plywood with specified density ratings. REACH compliance costs for formaldehyde emissions and surface coatings pressure small-batch producers serving residential channels.
- Metal:Extruded aluminum and steel profiles for structural frames and hardware. Spain's contract furniture sector sources these from limited European smelter networks, creating exposure to energy price volatility.
- Plastic:Thermoformed polymers and recycled polymer sheet for seating shells and tabletops.
- Fabric:Upholstery textiles including natural fibers, synthetics, and technical weaves.
Wood dominates volume across residential and commercial channels. Metal is gaining share fastest in outdoor and hospitality segments.
End User:
Application requirements dictate specification intensity. Public and commercial buyers enforce material disclosure mandates. Residential buyers prioritize finish quality and delivery speed.
- Residential:Individual and household purchasers for home interior fit-out. Barcelona and Madrid concentrate demand for premium upholstered products with customization options.
- Commercial:Corporate and institutional buyers for workplace and public space configuration. EU Green Deal disclosure mandates now require cradle-to-cradle documentation for contracts above threshold values.
- Hospitality:Hotels, restaurants, and tourism accommodation providers. Coastal corridor expansion in Valencia and Seville generates contract furniture volumes for fit-out and refurbishment cycles.
- Office:Workplace-specific procurement for workstations, meeting furniture, and storage systems.
Residential channels move the highest unit volumes. Hospitality is climbing the fastest on tourism infrastructure investment.
Distribution Channel:
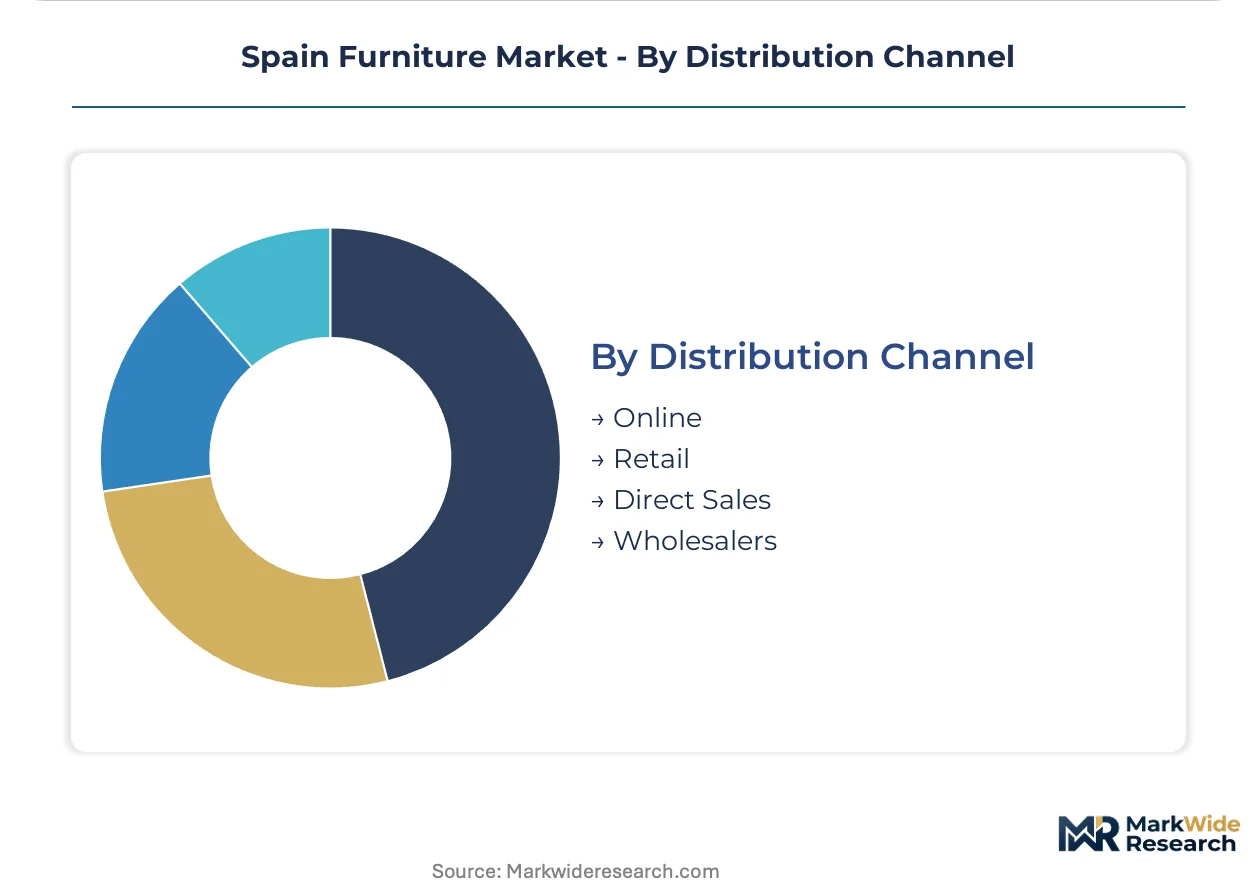
Customer type determines channel preference. Large-scale developers and architecture firms disintermediate traditional wholesale layers. Individual consumers rely on retail and digital platforms.
- Online:Digital commerce platforms and manufacturer direct-to-consumer websites. Madrid and Barcelona urban consumers use these channels for standardized products with transparent pricing.
- Retail:Physical showrooms and furniture stores with display inventory. These locations support tactile evaluation for upholstered products and material finish selection.
- Direct Sales:Manufacturer relationships with architecture firms, procurement consortia, and hospitality developers. Valencia and Seville developers bypass distributors to negotiate volume contracts with production facilities.
- Wholesalers:Intermediary distributors serving smaller retailers and regional markets.
Retail channels still lead by volume for residential segments. Direct sales are expanding most quickly as specification buyers consolidate procurement relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's furniture production clusters around Mediterranean coastal zones and northern industrial corridors. Manufacturers concentrate near textile finishing and metalworking infrastructure. Regulatory pressure from the EU Green Deal shapes regional competitive positioning.
Madrid
Commercial fit-out activity drives demand for certified contract furniture in the capital region. The Technical Building Code enforces fire resistance standards for installed fixtures across public buildings. Madrid's concentration of architecture firms and procurement consortia channels specification power toward domestic manufacturers with cradle-to-cradle documentation.
Catalonia
Barcelona anchors integrated upholstery production through textile finishing and aluminum extrusion capabilities. REACH chemical restrictions from ECHA impose reformulation costs on surface coating operations. The metropolitan manufacturing cluster supports export-oriented production of weather-resistant outdoor furniture for hospitality markets.
Andalusia
Tourism corridor expansion generates contract furniture volumes for hotel fit-outs and restaurant refurbishments. NextGenerationEU recovery funds flow toward energy-efficient building retrofits in coastal municipalities. Seville and Málaga developers negotiate direct volume contracts with production facilities, bypassing traditional distribution layers.
Valencia
Hospitality procurement concentrates in this Mediterranean port region for rapid project delivery. The EU Ecodesign Directive mandates material health declarations for public contracts above threshold values. Valencia's port infrastructure supports import of engineered wood panels from Baltic suppliers facing logging restriction pressures.
Basque Country
Metal fabrication heritage supports structural furniture component production for contract segments. Extended Producer Responsibility frameworks pending national implementation create reverse logistics opportunities. Bilbao's industrial base supplies aluminum profiles to outdoor furniture specialists serving European hospitality chains.
Spain Furniture Market Competitive Environment
Concentration sits with vertically integrated Mediterranean specialists and certified sustainable-grade producers. The market structure fragments across scale tiers, with premium positioning held by integrated manufacturers and mid-volume competition populated by regional fabricators. Two strategic archetypes dominate: integrated textile-metal producers with captive supply chains, and design-forward specialists leveraging cradle-to-cradle certification. Competitive moves center on supply chain restructuring around certified inputs and direct specification relationships with architecture firms.
Among Mediterranean-integrated specialists, Gandía Blasco and Kettal represent the outdoor-contract convergence archetype, while Andreu World anchors sustainable-grade metal recycling capabilities. These three occupy positions defined by manufacturing geography and certification depth rather than scale alone.
| Leading Market Players |
|---|
| Gandía Blasco |
| Capdell |
| Andreu World |
| Viccarbe |
| Ondarreta |
| Kettal |
| Doca |
| Beltá Frajumar |
| Sancal |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal material disclosure mandates gate both supplier qualification and price differentiation simultaneously. Manufacturers lacking cradle-to-cradle documentation forfeit access to hospitality and institutional procurement channels, compressing margins in compliant tiers while excluding non-compliant producers from premium contract segments entirely.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across Spain's furniture market. Three-tier pricing stratifies across certified sustainable, standard-grade, and economy segments, with EU Ecodesign Directive compliance costs driving wedge between certified and non-certified positioning. Price differentiation hinges on material health documentation depth and fire resistance certification grade. Cost compression in standard tiers intensifies because Baltic veneer supply instability feeds engineered wood panel volatility. Hospitality developers show least price sensitivity, while residential retail channels absorb maximum pressure.
Supply Chain Analysis
Inventory cycles for aluminum extrusions and engineered wood panels now stretch 14-20 weeks beyond pre-pandemic baselines. Spain's contract furniture sector draws structural profiles from German, Norwegian, and French smelter networks, creating single-source vulnerability to European energy price spikes. Birch and beech veneer feedstock hinges on Estonian, Latvian, and Finnish suppliers facing logging restriction pressures. Distribution runs through direct manufacturer relationships with architecture firms and procurement consortia, bypassing traditional wholesale layers for large-scale fit-out projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's furniture market rewards service-attach strategies as refurbishment lifecycle management and take-back logistics expand faster than hardware sales. Extended Producer Responsibility frameworks position reverse logistics capabilities as recurring revenue layers with superior margin profiles.
For Market Incumbents: Consolidate backward integration into textile finishing and aluminum recycling to defend against import-dependent competitors. Andreu World and Gandía Blasco demonstrate how captive supply chains buffer REACH reformulation cost spikes. Prioritize cradle-to-cradle certification depth over volume expansion in hospitality channels where specification power concentrates. For New Entrants and Emerging Players: Anchor in modular workplace systems for hybrid office reconfiguration demand. Valencia and Seville hospitality corridors offer penetrable entry points where direct sales relationships bypass entrenched distribution. Target specification support capabilities as primary go-to-market angle, matching BIM-compatible product libraries that legacy manufacturers struggle to deliver. For Investors and Strategic Acquirers: Pending national Extended Producer Responsibility implementation reshapes the acquisition landscape toward reverse logistics-enabled platforms. Five-to-ten year viability favors vertically integrated Mediterranean specialists with certified sustainable-grade positioning over import-dependent assemblers. Monitor ECHA flame retardant restriction updates as inflection signal for reformulation cost concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Cradle-to-Cradle Certification Investment | Third-party material health documentation unlocks public procurement contracts above EU threshold values. |
| Direct Specification Relationships | Architecture firm partnerships bypass wholesale intermediaries and capture hospitality fit-out margins. |
| Reverse Logistics Network Buildout | Take-back infrastructure positions first-movers for pending Extended Producer Responsibility mandates. |
| BIM-Compatible Product Libraries | Digital twin integration meets specifier requirements that legacy technical documentation cannot satisfy. |
| Integrated Textile-Metal Production | Barcelona cluster capabilities support export-oriented sustainable upholstery with shortened lead times. |
Study Parameters
Cross-validation between primary fieldwork and secondary documentation anchors the qualitative findings. Conversations with furniture manufacturing executives, hospitality procurement directors, architecture firm specification leads, and regional distribution managers informed demand-side dynamics. Secondary sources include EU Ecodesign Directive implementation records, ECHA chemical restriction updates, Spanish Technical Building Code enforcement data, and NextGenerationEU recovery fund allocation disclosures. Bottom-up channel volume estimates triangulate against top-down construction activity indices.
Sensitivity analysis around Baltic veneer supply disruption scenarios and aluminum energy cost volatility brackets the forecast range. Segmentation models incorporate product type, material grade tier, end-use application, and distribution channel across the projection horizon. CAGRs derive from fitted trend extrapolation adjusted for regulatory inflection timing. Forecast inputs include hospitality refurbishment cycle intensity and building renovation wave fund deployment velocity.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable Baltic timber supply; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Furniture & Cabinet Hardware Market
Furniture
UAE Home Furniture Market
Furniture
GCC Smart Furniture Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
Europe Furniture Market
Furniture
School Furniture Market
Furniture
Taiwan Home Furniture Market
Furniture
North America Smart Furniture Market
Furniture
UAE Luxury Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Upholstered Furniture Market
Furniture
Unfinished Wood Furniture Market
Furniture
Massive Wood Slabs Market
Furniture
UK Multifunctional Furniture Market
Furniture
UK Sustainable Home Furniture Market
Furniture
India Furniture Market