
 Wood Furniture Market | 2026-2036
Wood Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Furniture Market Analysis
Hospitality buyers is reorganizing demand patterns across the wood furniture sector as hotel operators and co-living developers scale bulk procurement of durable, design-forward furnishings. IKEA leverages its captive flat-pack logistics network to dominate cost-efficient commercial fit-outs. Ashley Furniture Industries anchors North American residential demand through vertically integrated manufacturing in Mississippi and North Carolina. Herman Miller differentiates on ergonomic seating engineering for corporate and healthcare environments.
Wood furniture encompasses solid and engineered timber products joined through machining, veneering, and finishing processes, typically specified by moisture content below 12 percent for dimensional stability in climate-controlled interiors. Its primary commercial purpose spans residential dwelling, workplace accommodation, and guest hospitality through functional storage, seating, and surface products. Cabinets and beds occupy the largest revenue pools in residential channels where replacement cycles run longest and margin structures favor hardwood construction. The hospitality end-user segment demonstrates the fastest trajectory as hotel development in Vietnam, Indonesia, and the Philippines drives teak and mahogany specification for tropical durability.
The EU Timber Regulation and EUTR due-diligence framework compel European importers to document chain-of-custody certification, reshaping supplier qualification toward FSC-traceable sources. The EPA formaldehyde emission standards under TSCA Title VI govern composite wood panel imports into the United States, creating compliance barriers for untreated MDF and particleboard substrates. India's BIS certification for furniture safety and the ECO Mark scheme now influence export readiness for South Asian manufacturers. Stakeholders must monitor evolving deforestation-free supply chain mandates across multiple jurisdictions to preserve market access and avoid stranded inventory positions.
Market Dynamics
Hospitality renovation cycles in Southeast Asia are compressing replacement timelines from seven years to four, forcing manufacturers to retool for faster-turnover, design-forward production while maintaining durability specifications for tropical climates.
Growth Catalysts
- EU Timber Regulation chain-of-custody mandates:European importers now require FSC-traceable documentation, redirecting procurement toward certified Vietnamese and Indonesian suppliers with established due-diligence systems.
- Teak and mahogany specification for tropical durability:Hotel developers in Vietnam, Indonesia, and the Philippines specify dense hardwoods for outdoor and high-humidity applications, creating premium substrate demand.
- Flat-pack logistics optimization:Container utilization rates improve through knock-down construction methods, reducing landed costs for remote hospitality projects.
Market Restraints
- Hardwood input cost volatility:Burmese teak sanctions and Myanmar export restrictions have redirected sourcing to plantation-grown alternatives with price premiums.
- EPA TSCA Title VI compliance barriers:Untreated MDF and particleboard imports face emission testing requirements, excluding smaller South Asian composite panel producers from US market access.
- Substitution by aluminum and rattan outdoor furniture:Coastal hospitality operators in the Philippines specify metal and synthetic wicker for poolside durability, displacing traditional wood in exterior applications.
Strategic Opportunities
- India BIS certification and ECO Mark readiness:Domestic manufacturers upgrading testing facilities can capture redirected European orders seeking alternatives to Chinese supply.
- CNC machining and robotic finishing convergence:Automated carving and coating systems enable mass customization for boutique hotel chains requiring unique room configurations.
- Direct-to-developer digital platforms:Online specification tools bypass traditional distributor markups for mid-scale co-living operators in Ho Chi Minh City and Jakarta.
Industry Challenges
- Master craftsman attrition in traditional joinery:Hand-cut dovetail and mortise-tenon skills are disappearing as younger workers migrate to automated production facilities.
- EUTR documentation timeline compression:European buyers now demand 72-hour custody-chain verification, straining paper-based record systems at Indonesian sawmills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Furniture Market |
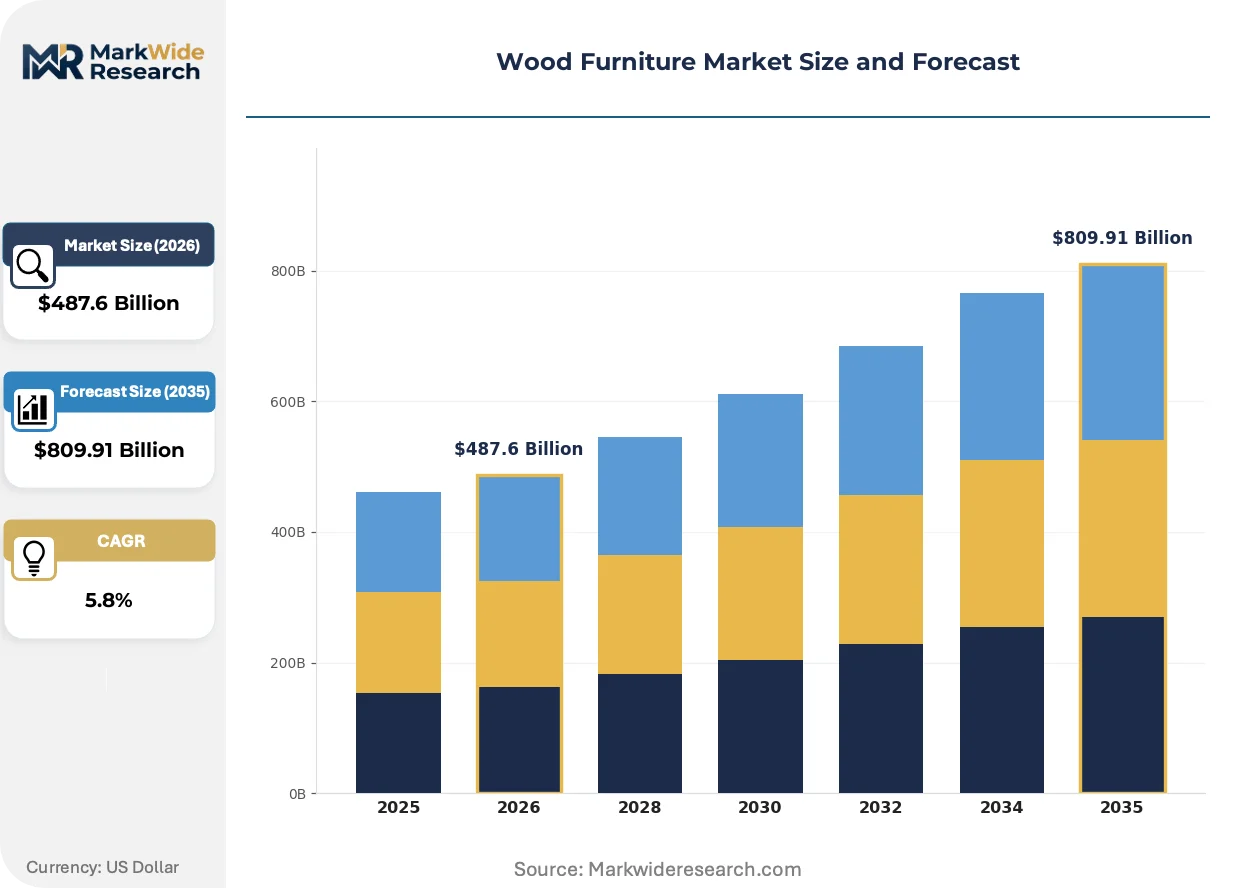
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $809.91 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tables, Chairs, Cabinets, Beds Material: Mahogany, Oak, Pine, Teak Style: Modern, Rustic, Contemporary, Traditional End User: Residential, Commercial, Hospitality, Institutional |
| Companies Covered | IKEA, Ashley Furniture Industries, Steelcase, Herman Miller, La-Z-Boy, HNI Corporation, Williams-Sonoma, Bassett Furniture Industries, Natuzzi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Furniture Market Emerging Trajectories
Digital fabrication and regulatory traceability are converging to reshape how wood furniture is specified, manufactured, and certified across hospitality and residential channels.
Cross-laminated timber and engineered bamboo composites are miniaturizing structural elements previously requiring solid hardwood sections. Boutique hotel designers in Bali and Phuket specify these materials for headboards and built-in cabinetry to reduce weight and shipping volume. The technology is miniaturizing freight costs while maintaining visual warmth that metal alternatives cannot replicate.
REACH chemical restrictions and the EU Deforestation Regulation now govern wood product market access with mandatory geolocation data. European customs authorities reject shipments lacking polygon-mapped harvest coordinates. Vietnamese exporters in Binh Duong province are investing in blockchain-integrated inventory systems to satisfy documentation depth.
Bulk procurement by co-living operators is consolidating specification authority away from individual interior designers. Jakarta-based developers now issue master purchase orders covering 500-unit portfolios, demanding standardized SKUs with regional warehousing. This concentration is visible most acutely in Vietnam's integrated manufacturing parks serving export-oriented production.
Wood Furniture Market Segmentation
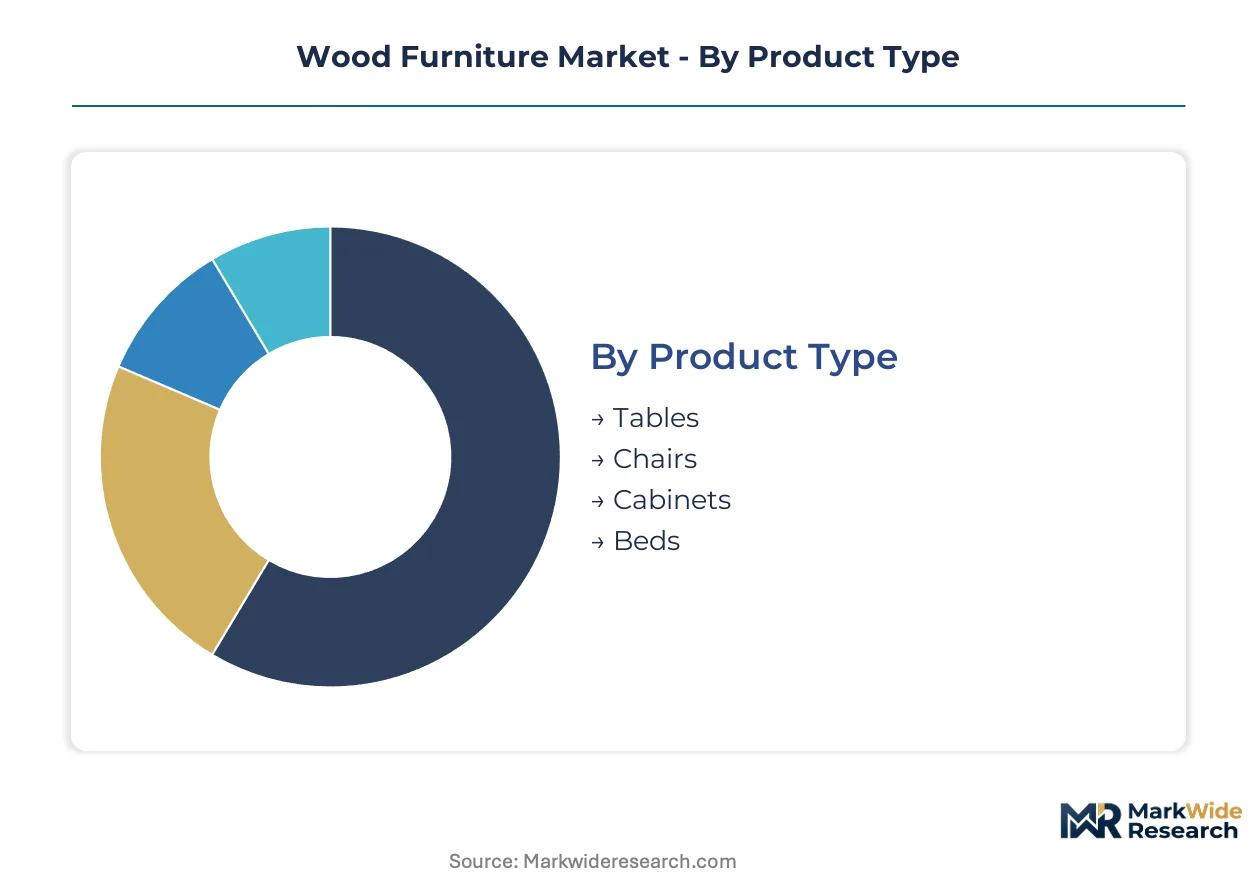
Segmentation in wood furniture reveals how procurement authority concentrates across distinct buyer archetypes and how material specifications diverge by climate exposure and end-use durability requirements. Understanding these splits enables suppliers to align certification investments and production capacity with the highest-velocity demand channels.
Product Type:
Channel flow varies sharply by product type, with bulky items demanding dedicated logistics partnerships while flat-pack categories exploit containerized freight optimization.
- Cabinets:These storage units require precision joinery and moisture-resistant finishes for dimensional stability in humid climates. Residential replacement cycles in North America and Europe sustain steady demand for hardwood-constructed kitchen and bedroom cabinetry with premium margin structures.
- Beds:Mattress support systems and headboards represent high-volume procurement for hospitality developers in Vietnam and Indonesia, where tropical durability specifications favor dense hardwood frames over softwood alternatives.
- Tables:Dining and conference surfaces span residential and commercial channels with veneer-over-substrate construction dominating mid-market specification.
- Chairs:Seating products concentrate ergonomic engineering investment for corporate and healthcare environments, with knock-down assembly methods enabling efficient container shipping.
Cabinets dominate installed base. Beds are where expansion concentrates.
Material:
Cost tier stratification runs through material selection, with plantation-grown alternatives displacing old-growth sourcing under EUTR compliance pressure.
- Teak:This dense tropical hardwood delivers natural oil content that resists moisture, decay, and insect infestation without chemical treatment. Hotel operators in the Philippines and coastal Vietnam specify teak for outdoor furniture and high-humidity interiors, paying premiums for verified plantation origin.
- Oak:Northern European and North American white oak varieties provide structural integrity for heavy-use residential furniture, with quarter-sawn grain patterns commanding specification in premium dining and bedroom collections.
- Mahogany:Rich coloration and workability sustain demand for executive office and traditional residential applications, though Burmese sourcing sanctions have redirected procurement to Central American plantation supplies.
- Pine:Softwood construction dominates economy-tier residential and rental-property furnishing, with kiln-dried treatment addressing dimensional stability concerns in climate-controlled interiors.
Teak commands the steepest price tier. Pine is climbing the fastest as co-living operators scale standardized procurement.
Style:
Customer type differentiation separates specification authority between interior designers, procurement teams, and direct consumer purchase.
- Modern:Clean lines and minimal ornamentation align with boutique hotel chains and urban co-living developers in Ho Chi Minh City and Jakarta, where space efficiency drives specification.
- Contemporary:Evolving aesthetic vocabularies blend material textures and asymmetric forms for residential environments seeking differentiation without historical reference.
- Rustic:Reclaimed timber and distressed finishes target vacation rental properties and regional hospitality concepts emphasizing authenticity narratives.
- Traditional:Ornate carving and period detailing sustain demand in heritage hospitality restoration and established residential markets with conservative aesthetic preferences.
Traditional styling retains the largest installed base. Modern is where expansion concentrates.
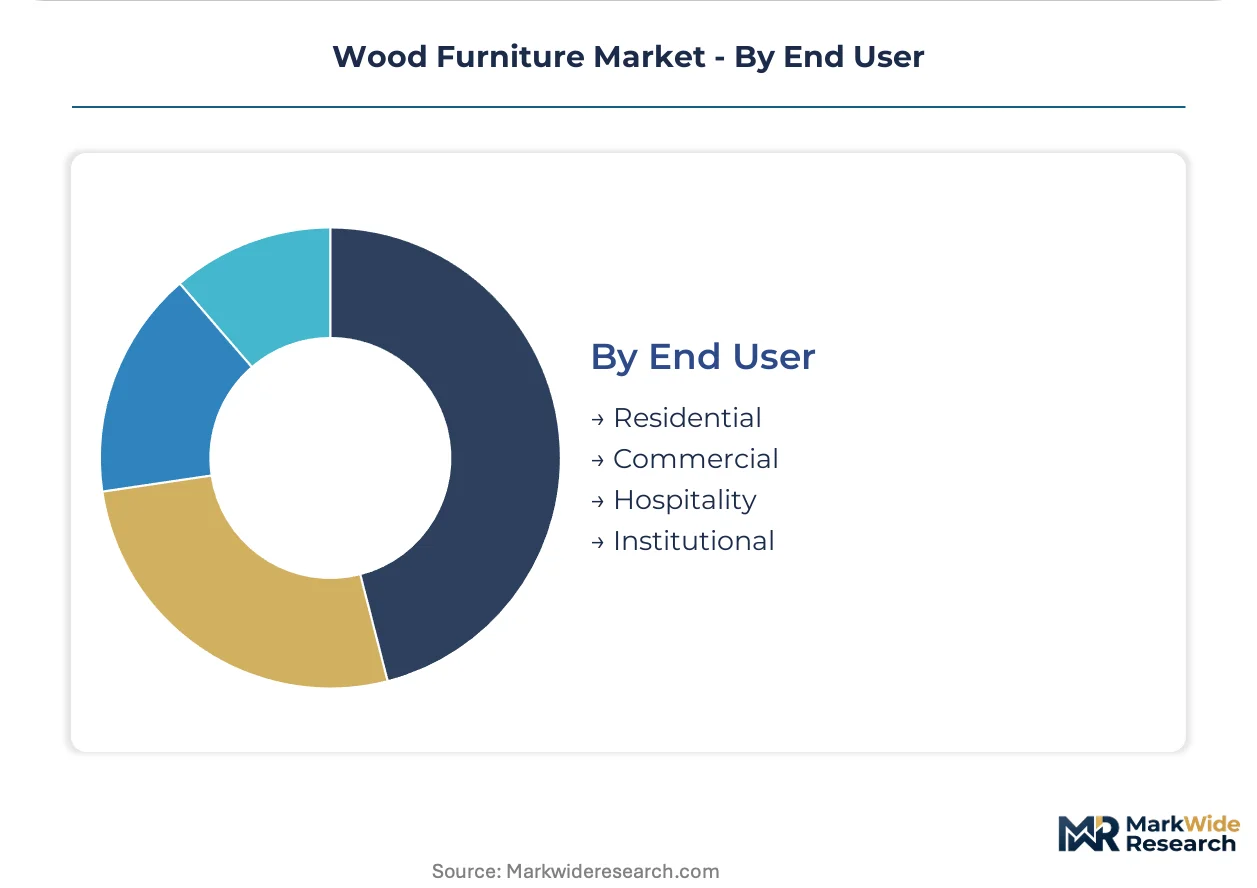
End User:
Application context determines durability specifications, replacement cycle timing, and certification documentation depth.
- Hospitality:Hotel and resort procurement teams in Southeast Asia now compress renovation timelines from seven years to four, demanding design-forward production with tropical climate resilience. This segment is expanding most quickly as development accelerates across Vietnam, Indonesia, and the Philippines.
- Residential:Owner-occupied dwelling sustains the longest replacement cycles and highest per-unit expenditure, with hardwood construction dominating master bedroom and dining room categories.
- Commercial:Corporate office and co-working space procurement prioritizes ergonomic seating and modular storage systems with rapid reconfiguration capability.
- Institutional:Healthcare, education, and government facilities impose stringent durability and safety certification requirements, with BIS and EPA compliance filtering supplier qualification.
Residential dominates installed base. Hospitality is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnamese exporters ship containerized flat-pack furniture to European hospitality developers under EUTR chain-of-custody requirements, while Indonesian suppliers redirect plantation teak to Southeast Asian hotel construction sites.
United States
Residential replacement cycles sustain demand for hardwood bedroom and dining collections. EPA TSCA Title VI emission standards filter composite panel imports, favoring domestic MDF producers with certified testing protocols. Mississippi and North Carolina manufacturing clusters anchor vertically integrated production for mass-market distribution.
Germany
EU Timber Regulation due-diligence mandates redirect procurement toward FSC-traceable Baltic and Polish suppliers. ECHA REACH chemical restrictions govern surface coatings and adhesives in imported finished goods. The North Rhine-Westphalia logistics corridor processes inbound container flows from Vietnamese integrated manufacturing parks.
Vietnam
Binh Duong province manufacturing parks serve export-oriented hospitality production with compressed four-year renovation cycles. Domestic ECO Mark alignment and BIS certification readiness position suppliers for redirected European orders. Ho Chi Minh City co-living developers consolidate bulk procurement through direct-to-developer digital platforms.
Indonesia
Plantation-grown teak and mahogany substitution accelerates under Burmese sourcing sanctions. Hotel developers in Bali and Jakarta specify dense hardwoods for tropical durability in high-humidity applications. Jepara and Surakarta clusters face EUTR documentation timeline compression as European buyers demand 72-hour custody-chain verification.
India
BIS certification for furniture safety and ECO Mark scheme adoption influence export readiness for South Asian manufacturers. Domestic co-living operators in Bengaluru and Mumbai scale standardized procurement of pine-constructed economy-tier furnishings. Gujarat and Tamil Nadu testing facility upgrades capture redirected orders seeking alternatives to Chinese supply.
Wood Furniture Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and supply chain control dimensions. The vendor base separates into scale-driven mass-market suppliers, design-forward boutique specialists, and vertically integrated raw-material controllers. Three archetypes dominate: flat-pack logistics optimizers, tropical hardwood certifiers, and ergonomic seating engineers. Competitive moves concentrate on captive raw-material sourcing and automated finishing convergence.
Among scale-driven fabricators, IKEA exemplifies flat-pack logistics optimization through container utilization engineering. Ashley Furniture Industries anchors North American residential demand through in-house production of hardwood-constructed collections. Herman Miller occupies a position within ergonomic seating engineering for corporate and healthcare environments, representing design-forward specialization.
| Leading Market Players |
|---|
| IKEA |
| Ashley Furniture Industries |
| Steelcase |
| Herman Miller |
| La-Z-Boy |
| HNI Corporation |
| Williams-Sonoma |
| Bassett Furniture Industries |
| Natuzzi |
| Others |
Supply Flow & Price Mechanics
EUTR chain-of-custody mandates gate both supplier qualification and price differentiation simultaneously, as European importers pay premiums for FSC-traceable documentation while excluding uncertified competitors from tender participation. This regulatory filter compresses margins at the economy tier while amplifying pricing power for certified plantation-teak suppliers in Vietnam and Indonesia.
Pricing Analysis
Conventional machining-versus-automated fabrication pricing gaps separate incumbent craft producers from robotic-finishing adopters across premium, standard, and economy tiers. Price differentiation rests on certification grade and volume scale, with boutique hotel chains absorbing customization premiums while co-living operators drive standardization discounts. Pricing pressure stems from Burmese teak substitution costs as plantation-grown alternatives command 15-30% premiums. Hospitality procurement teams demonstrate lowest price sensitivity due to durability specifications, whereas residential rental operators exhibit highest elasticity.
Supply Chain Analysis
Vietnam, Indonesia, and India anchor export-oriented production through Binh Duong manufacturing parks, Jepara craft clusters, and Gujarat testing facilities respectively. Raw material flows draw from plantation teak in Central Java, engineered bamboo composites in Vietnam's Mekong Delta, and kiln-dried pine from Tamil Nadu plantations. Single-source vulnerability concentrates in Myanmar-origin hardwood substitution as sanctions redirect sourcing. Distribution runs through containerized flat-pack logistics for hospitality developers and traditional wholesale channels for residential retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Master craftsman attrition in traditional joinery creates acute capability scarcity, as automated production facilities drain skilled labor pools faster than apprenticeship programs replenish them. This talent gap threatens premium-tier output quality and extends lead times for hand-finished collections.
For Market Incumbents: Fortify captive plantation-teak sourcing through backward integration into Central Java and Vietnamese Mekong Delta timber assets to hedge against Burmese supply disruption. Deepen FSC certification coverage across secondary product lines before EUDR geolocation mandates expand enforcement scope. Prioritize robotic finishing convergence in Binh Duong facilities to offset wage inflation and compress four-year hospitality renovation cycle delivery timelines. For New Entrants and Emerging Players: Anchor in India's BIS certification-ready manufacturing corridors to capture redirected European orders seeking alternatives to Chinese supply penetration. Target co-living operator procurement consolidation in Ho Chi Minh City and Jakarta through direct-to-developer digital specification platforms. Emphasize ECO Mark alignment and compressed lead-time guarantees as primary go-to-market differentiation against established Vietnamese exporters. For Investors and Strategic Acquirers: EUDR mandatory geolocation data requirements reshape the acquisition landscape toward blockchain-integrated inventory systems and polygon-mapped harvest coordinate capabilities. Long-term viability favors vertically integrated specialists with captive timber assets and automated production footprints over pure-play distributors. Monitor Indonesian sawmill EUTR documentation compression rates as the critical inflection signal for supply chain reliability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Plantation Teak Backward Integration | Captive sourcing from Central Java insulates margins against Burmese sanction volatility. |
| Blockchain Inventory System Deployment | Binh Duong exporters satisfy EUDR 72-hour custody-chain verification demands. |
| Robotic Finishing Convergence | Automated carving systems enable mass customization for boutique hotel chains. |
| BIS Certification Facility Upgrade | Gujarat and Tamil Nadu testing capabilities capture redirected European procurement. |
| Direct-to-Developer Digital Platform Launch | Online specification tools bypass distributor markups for Jakarta co-living operators. |
Methodological Framework
Operator-level perspectives from hospitality procurement directors, furniture manufacturing plant managers, timber plantation operations heads, and EUTR compliance officers anchored the qualitative base. These primary insights combined with secondary validation from customs trade databases, FSC chain-of-custody registries, EPA TSCA Title VI certification records, and BIS testing facility directories. Bottom-up production capacity assessments and top-down import flow analysis triangulated volume estimates across the analysis window.
Sensitivity analysis frameworks tested demand elasticity against hardwood input cost volatility and regulatory enforcement intensity variations. Segmentation modeling spanned product type, material grade, end-user application, and regional production hub dimensions. CAGRs derived from regression analysis of historical trade flows and forward projection of hospitality development pipelines. Plantation teak substitution rates and co-living operator procurement consolidation velocity served as industry-specific forecast inputs.
Material uncertainties — Burmese sanction duration, EUDR geolocation mandate implementation timing, and master craftsman attrition acceleration — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued Southeast Asian hospitality development momentum and stable EPA emission standard enforcement. Recalibration cycles align with material shifts in regulatory enforcement thresholds and plantation timber harvest maturation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global Home Furniture Market
Furniture
United States Home Furniture Market
Furniture
United Kingdom Furniture Market
Furniture
Canada Secondary Wood Products Market
Furniture
Asia-Pacific Home Furniture Market
Furniture
Kids and Nursery Furniture Market
Furniture
Asia-Pacific Luxury Furniture Market
Furniture
Home Furnishings Market
Furniture
Bamboo Furniture Market
Furniture
Bean Bag Chairs Market
Furniture
Global Organic Furniture Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Armchair on Casters Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
Europe Outdoor Furniture Market
Furniture
Unfinished Wood Furniture Market