
 Pool Tables Market | 2026-2036
Pool Tables Market Size, Share, and Industry Trends Forecast 2026-2036
Pool Tables Market Intelligence
Aftermarket service revenue is tilting toward professional-grade refurbishment and felt replacement programs. Brunswick Billiards leverages its century-old distribution network to sustain dealer loyalty across North American showrooms. Olhausen Billiards anchors its position through domestic manufacturing scale in Tennessee, while Diamond Billiard Products competes on tournament-specification precision tables.
A pool table is a rectangular billiards platform built on a flat bed of slate, medium-density fiberboard, or plywood, covered with woven wool-nylon felt and bounded by vulcanized rubber cushions engineered for consistent ball rebound. The structure serves competitive tournament play, commercial entertainment venues, and residential recreation by providing a standardized surface for cue sports. Slate material configurations command the highest margin pools due to dimensional stability and professional certification requirements, while outdoor-type tables represent the fastest-growing category as weather-resistant aluminum frames and synthetic surfaces penetrate patio entertainment spaces. Homeowner target audience segments dominate unit volume, though bars and clubs generate superior per-unit accessory attach rates.
EPA regulations on volatile organic compound emissions constrain lacquer and adhesive formulations used in table finishing operations, while CPSC safety standards govern tip-over stability and lead-content thresholds in consumer-facing products. ISO 9001 quality management certifications increasingly gate entry to institutional procurement channels for recreational centers and municipal clubs. Stakeholders must monitor evolving state-level furniture safety mandates and synthetic felt durability benchmarks as material substitution accelerates.
Market Dynamics
Residential basement entertainment renovations are compressing replacement cycles and elevating specification requirements for slate-bed tables, while regulatory pressure on volatile organic compound emissions constrains finishing operations across domestic manufacturing.
Growth Catalysts
- EPA Indoor Air Quality Standards:Tightening VOC thresholds for lacquers and adhesives are accelerating reformulation investments that differentiate certified manufacturers in institutional procurement channels.
- Synthetic Felt Substitution:Weather-resistant polymer surfaces are penetrating patio entertainment installations, expanding addressable square footage beyond climate-controlled interiors.
- Bar-Style Residential Spaces:Homeowner segments in the United States are driving premium slate-table procurement through dedicated recreation room construction.
Market Restraints
- Slate Supply Concentration:Dimensional stability requirements for tournament certification limit sourcing to specific geological deposits, creating input bottleneck vulnerability.
- Aluminum Frame Cost Volatility:Outdoor-type table production faces margin pressure from commodity metal price swings affecting weather-resistant frame fabrication.
- Lead-Content Thresholds:CPSC safety standards impose testing burdens on small-batch artisan producers serving heritage restoration segments.
Strategic Opportunities
- Municipal Club Procurement:ISO 9001 certification gaps among regional fabricators create white space for quality-assured entrants in recreational center installations.
- Felt Replacement Programs:Aftermarket service unbundling from original equipment sales generates recurring revenue streams through professional-grade refurbishment.
- IRA Residential Energy Credits:Climate-controlled basement finishing incentives indirectly subsidize recreation room infrastructure investment in qualifying jurisdictions.
Industry Challenges
- Vulcanized Rubber Cushion Craftsmanship:Consistent rebound engineering requires specialized artisan labor pools that are thinning across domestic manufacturing bases.
- Multi-Material Integration:Bonding slate, wood, and synthetic components demands precision tolerances that strain quality control systems during volume scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pool Tables Market |
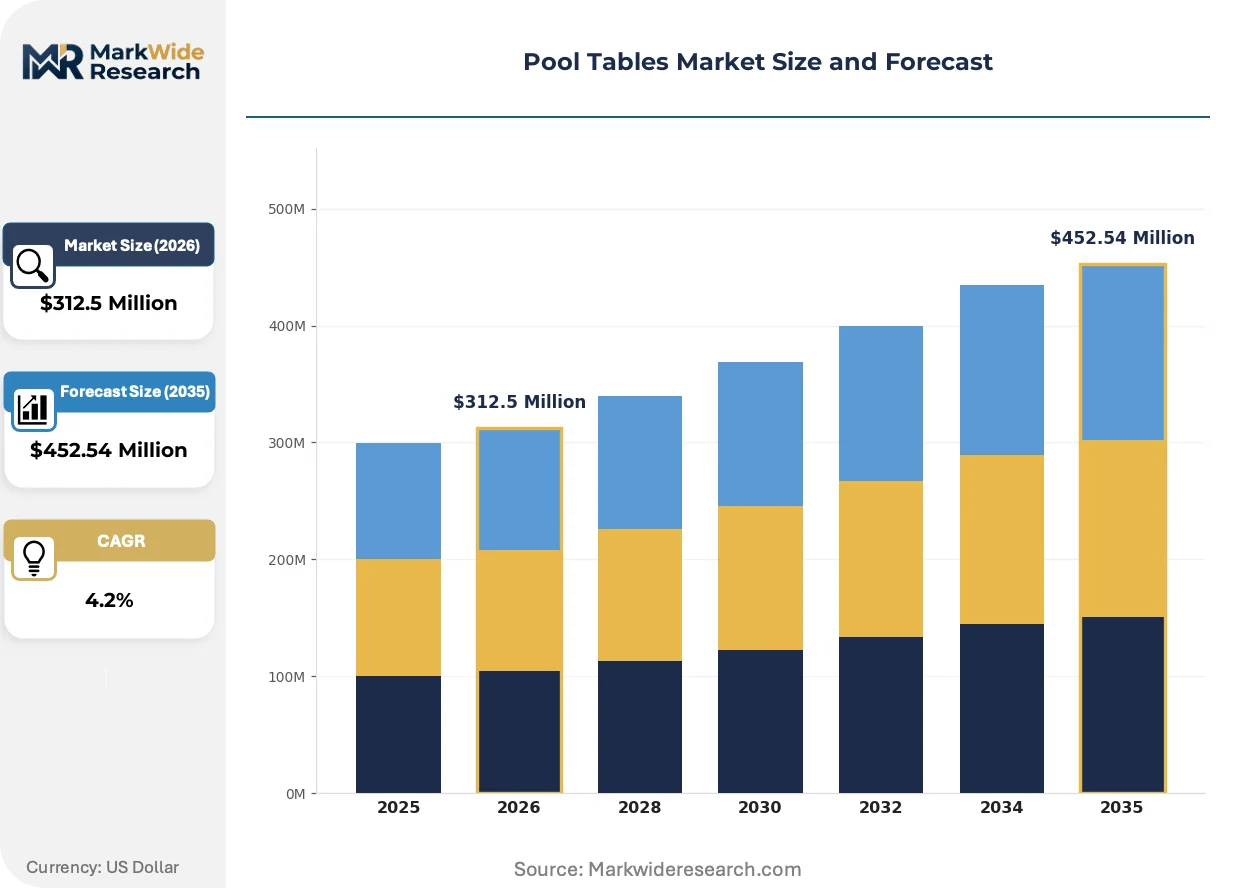
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $452.54 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Slate, MDF, Plywood, Plastic Type: Standard, Mini, Pro, Outdoor Size: 7 ft, 8 ft, 9 ft, 10 ft Target Audience: Homeowners, Bars, Recreational Centers, Clubs |
| Companies Covered | Valley-Dynamo, Imperial Billiards, Brunswick Billiards, Plank & Hide, American Heritage Billiards, Olhausen Billiards, Legacy Billiards, Rene Pierre, Diamond Billiard Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pool Tables Market Strategic Shifts & Innovations
Material science advances and regulatory compliance automation are restructuring how tables are specified, finished, and serviced across residential and commercial channels.
Wool-nylon composite felt is migrating from traditional woven constructions toward precision-calibrated synthetic blends engineered for humidity stability. Tournament operators and commercial venues are adopting these surfaces at accelerated replacement intervals. This migration is compressing maintenance windows while extending playable lifespan in variable climate conditions.
REACH chemical registration requirements in Europe are restricting certain preservative compounds historically used in wood frame treatments. Manufacturers serving export markets must maintain dual-formulation inventories or abandon affected chemistries entirely. Slate-bed producers with transatlantic distribution footprints face the steepest compliance cost absorption.
Accessory attach rate optimization is shifting from bundled retail packaging toward unbundled professional installation services. Bar and club buyers now separately procure cues, racks, and lighting through specialized dealers rather than single-source table vendors. This pattern is most pronounced in the United States where basement renovation contractors coordinate multi-vendor recreation room fit-outs.
Pool Tables Market Segmentation
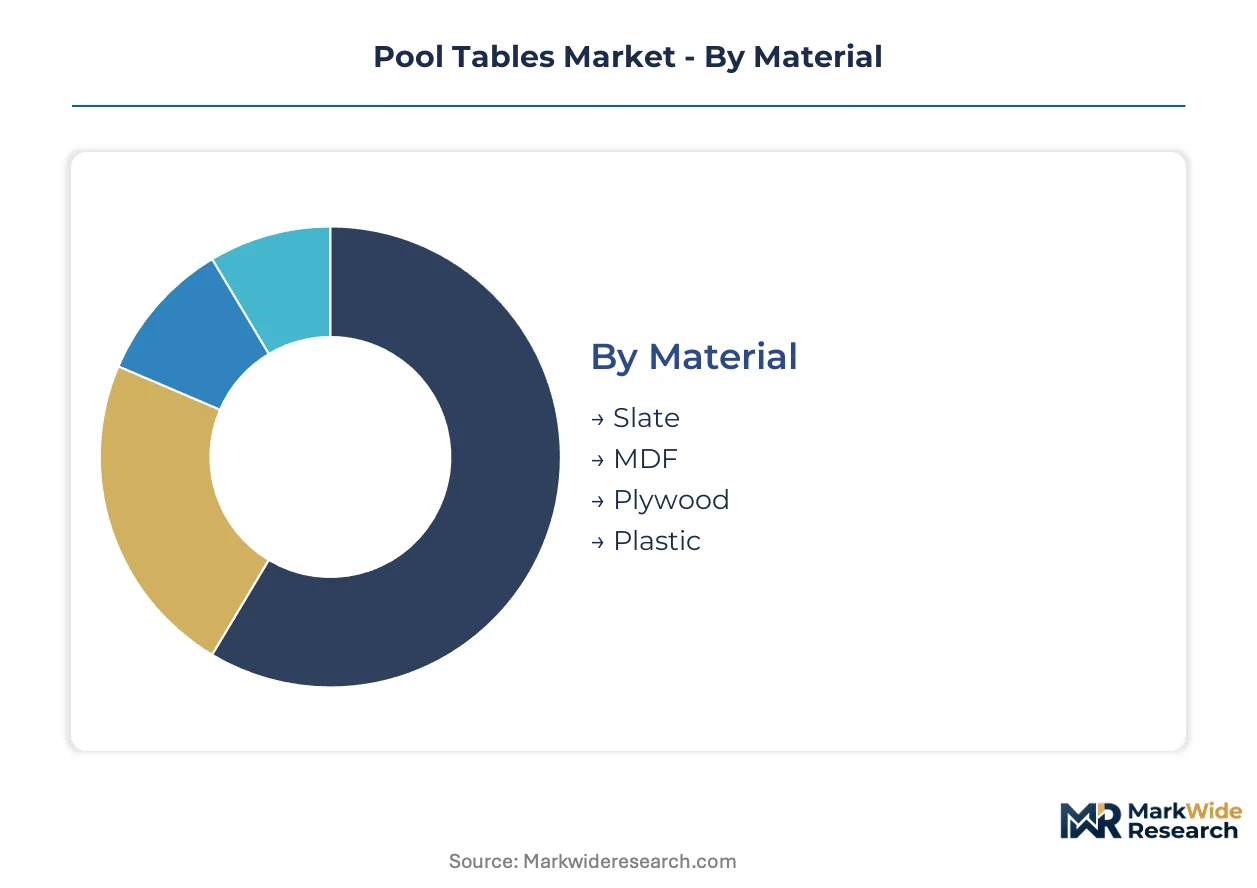
Pool table purchasing cycles vary dramatically by material durability and use intensity, with commercial venues replacing surfaces every 3-5 years while residential slate installations endure 20+ years. Segmentation reveals where refurbishment revenue concentrates versus original equipment sales.
Material:
Replacement frequency diverges sharply: slate demands minimal intervention while synthetic surfaces turn over rapidly in high-traffic commercial settings.
- Slate:Dimensional stability from metamorphic rock formations delivers tournament-grade flatness tolerance within 0.005 inches. Demand concentrates in United States basement renovations where homeowners prioritize single-purchase permanence; EPA VOC regulations on imported finishes add compliance cost but protect certified domestic fabricators.
- MDF:Engineered wood fiber panels bonded with resin provide entry-level flatness for casual play. Recreational centers in budget-constrained municipalities specify these for youth programs; humidity-induced warping limits replacement cycles to 7-10 years in uncontrolled climates.
- Plywood:Cross-laminated veneer construction offers intermediate rigidity at lower mass than slate. Apartment complexes and temporary entertainment venues favor these for elevator transportability and relocation flexibility.
- Plastic:Injection-molded polymer frames with synthetic playing surfaces enable outdoor patio installations. Weather-resistant formulations are climbing the fastest as aluminum-frame hybrid designs penetrate residential backyard entertainment spaces.
Slate anchors the volume base while plastic gains share at the steepest rate.
Type:
Margin structures stratify by certification requirements, with tournament-specification tables commanding 3-4x assembly labor intensity over recreational units.
- Standard:Regulation 8-foot and 9-foot dimensions with slate beds and wool-nylon felt satisfy most residential and commercial demand. United States bar-style basement installations drive procurement; CPSC tip-over stability standards add testing burden but reduce liability exposure.
- Mini:Compact 6-foot and 7-foot tables target space-constrained urban apartments and children's recreation rooms. Lower price points expand unit volume in multi-family housing developments where permanent installation is impractical.
- Pro:Tournament-certified precision with sub-millimeter slate seam alignment and professional cushion rebound specifications. Billiards halls and competitive venues in Texas and Florida sustain demand despite 6-month lead times from certified fabricators.
- Outdoor:Weather-sealed aluminum frames with synthetic felt and rust-resistant hardware enable patio entertainment. Synthetic surface substitution is expanding most quickly as humidity-stable polymer blends replace wool-nylon in coastal and subtropical climates.
Standard tables dominate installed base while outdoor types are expanding most quickly.
Size:
Spatial economics determine specification: ceiling height requirements and room perimeter clearance filter feasible options for each installation context.
- 7 ft:Bar box dimensions fit 14-foot by 17-foot minimum room envelopes, the practical constraint for most residential basements. United States homeowner renovations concentrate here; shorter cue stroke dynamics appeal to casual players.
- 8 ft:Home recreational standard balancing playability with space efficiency. Regional furniture dealers in Tennessee and California report strongest attach rates for accessory packages at this specification tier.
- 9 ft:Professional tournament dimensions requiring 18-foot by 14-foot clear floor space. Dedicated recreation room construction in affluent suburbs sustains demand; slate weight exceeds 700 pounds and mandates professional installation.
- 10 ft:Oversized carom billiards and snooker specifications for specialized competitive play. Institutional procurement from municipal clubs and university recreation centers supports limited production volumes.
7-foot tables anchor residential volume while 9-foot specifications gain share fastest in premium basement renovations.
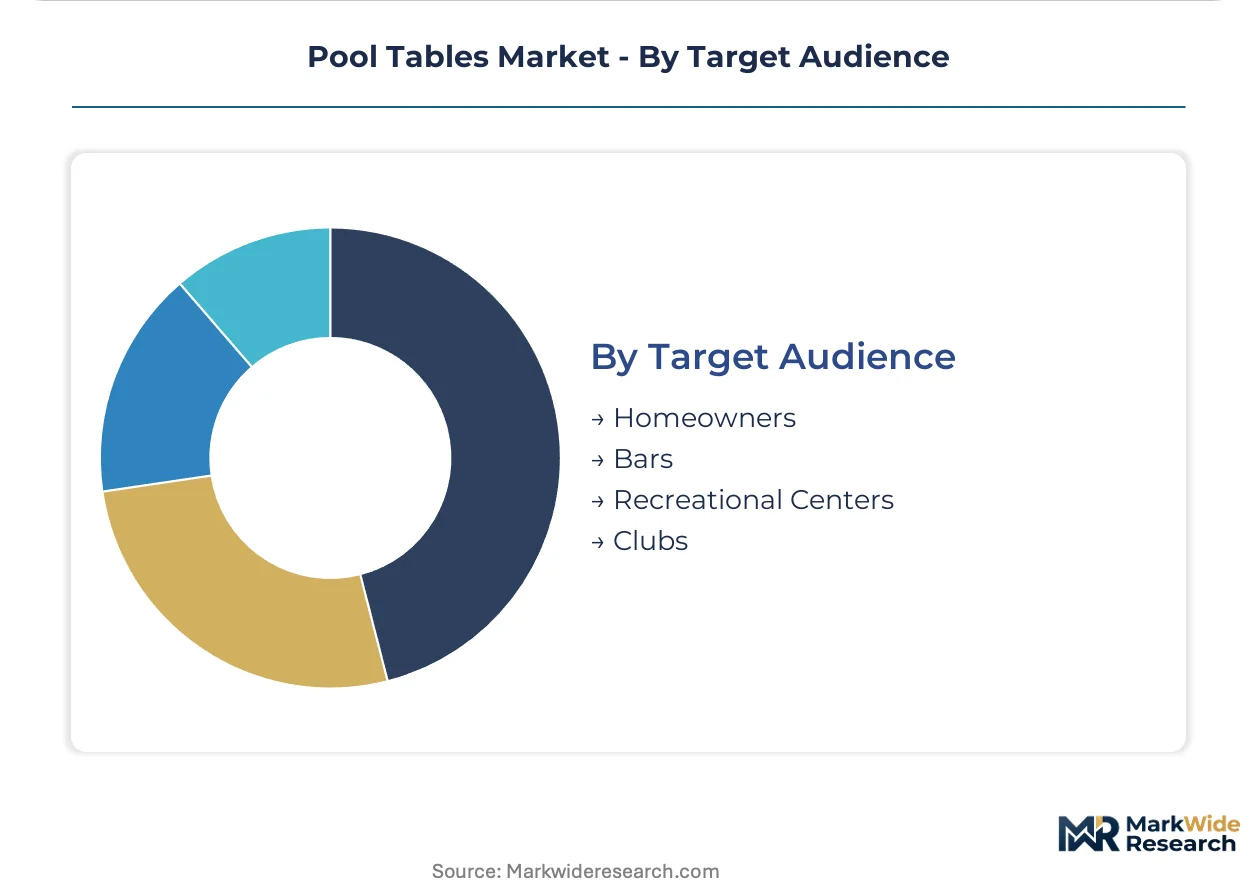
Target Audience:
Customer type dictates procurement channel and service bundling, with commercial buyers separating table purchase from accessory and maintenance contracts.
- Homeowners:Basement entertainment renovation projects coordinate through general contractors and specialized recreation room designers. IRA residential energy credits for climate-controlled finishing indirectly subsidize infrastructure investment in qualifying United States jurisdictions.
- Bars:High-traffic commercial venues generate superior per-unit accessory attach rates for cues, racks, and lighting. Felt replacement programs unbundled from original equipment sales create recurring revenue streams through professional-grade refurbishment cycles.
- Recreational Centers:Municipal and institutional procurement requires ISO 9001 quality certification that gates entry for regional fabricators. Budget constraints favor MDF and plywood specifications over slate in youth-serving facilities.
- Clubs:Private membership organizations balance prestige positioning with durability requirements. Tournament-specification pro tables with vulcanized rubber cushions satisfy competitive player expectations; artisan labor scarcity for cushion craftsmanship extends lead times.
Homeowners anchor unit volume while bars generate the highest service revenue intensity per installed table.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States homeowners prioritize permanent slate installations in basement renovations, while European buyers favor compact specifications for urban apartments, and Asia-Pacific markets are experimenting with outdoor aluminum-frame hybrids for balcony entertainment.
United States
Basement entertainment renovations drive premium slate-table procurement through dedicated recreation room construction. EPA Indoor Air Quality Standards on VOC emissions constrain lacquer and adhesive formulations, favoring certified domestic fabricators. Tennessee hosts concentrated manufacturing operations serving dealer networks across the Southeast and Midwest.
Germany
REACH chemical registration requirements restrict preservative compounds in wood frame treatments, forcing dual-formulation inventories for export-capable producers. Municipal recreational centers in Bavaria and North Rhine-Westphalia specify ISO 9001-certified tables for youth-serving facilities. Stuttgart-area fabricators specialize in tournament-specification precision engineering.
United Kingdom
Space-constrained urban apartments in London and Manchester favor compact 6-foot and 7-foot mini-table specifications. CE marking requirements govern product safety and tip-over stability standards. Birmingham-based distributors coordinate multi-vendor recreation room fit-outs through specialized contractors.
Japan
High-rise residential towers in Tokyo and Osaka drive demand for lightweight plywood and MDF configurations with elevator transportability. METI quality guidelines influence procurement specifications for commercial entertainment venues. Nagoya-area manufacturers focus on precision cushion rebound engineering for competitive play segments.
Australia
Coastal and subtropical climates in Queensland and New South Wales accelerate synthetic felt substitution for humidity-stable outdoor installations. State-level furniture safety mandates govern lead-content thresholds and structural stability. Melbourne showrooms report strongest attach rates for accessory packages at 8-foot specification tiers.
Pool Tables Market Key Industry Players
Capability concentration sits with artisan-grade precision specialists; scale advantage sits with century-old distribution networks. The vendor base stratifies across three tiers: domestic manufacturing scale players, tournament-certification precision specialists, and outdoor aluminum-frame innovators. Dominant competitive moves include professional-grade refurbishment program unbundling and weather-resistant material formulation investments.
Among North American fabricators, Brunswick Billiards, Olhausen Billiards, and Diamond Billiard Products occupy distinct positioning vectors. Brunswick represents the distribution-network archetype with century-old dealer loyalty across showroom channels. Olhausen exemplifies domestic manufacturing scale concentration. Diamond sits within the tournament-specification precision tier, serving competitive venues with sub-millimeter slate alignment requirements.
| Leading Market Players |
|---|
| Valley-Dynamo |
| Imperial Billiards |
| Brunswick Billiards |
| Plank & Hide |
| American Heritage Billiards |
| Olhausen Billiards |
| Legacy Billiards |
| Rene Pierre |
| Diamond Billiard Products |
| Others |
Cost & Logistics Intelligence
Tennessee manufacturing clusters anchor slate-bed production capacity, concentrating premium-table pricing power among domestic fabricators certified under EPA VOC standards while import-dependent competitors absorb compliance cost premiums.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement from municipal recreational centers, while spot-market transactions govern residential basement renovations through dealer showrooms. Three-tier pricing structure across tournament-certified pro tables, standard residential slate beds, and entry-level MDF configurations reflects certification grade and assembly labor intensity. Cost compression in outdoor aluminum-frame segments intensifies due to commodity metal price volatility. Recreational centers exhibit highest price sensitivity; affluent homeowners in dedicated renovation projects demonstrate lowest sensitivity.
Supply Chain Analysis
Extended payment terms from Tennessee fabricators to Appalachian slate quarries stabilize input flows for dimensional stability-critical tournament tables. Slate sourcing concentrates in Italy, Brazil, and domestic Appalachian deposits; wool-nylon felt draws from textile mills in Belgium and South Carolina. Single-source vulnerability runs through certified vulcanized rubber cushion artisans. Distribution runs through century-old dealer networks and direct-to-contractor channels for basement renovation coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward general contractors coordinating multi-vendor recreation room fit-outs, fragmenting procurement decisions away from single-source table vendors.
For Market Incumbents: Pre-empt synthetic felt substitution momentum by certifying proprietary polymer blends under updated EPA indoor air quality standards. Secure backward integration into Tennessee slate finishing capacity to defend margin position against import-dependent competitors facing VOC compliance premiums. Channel control through exclusive dealer loyalty programs remains critical as contractor-led procurement fragments traditional showroom traffic. For New Entrants and Emerging Players: Build out weather-resistant outdoor table offerings targeting coastal Australian and subtropical United States patio entertainment spaces, the fastest-expanding addressable category. Municipal recreational centers present the most penetrable institutional segment due to ISO 9001 certification gaps among regional fabricators. Go-to-market execution should prioritize direct contractor relationships over traditional dealer network establishment. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because artisan-grade cushion craftsmanship scarcity and thinning domestic labor pools favor scaled precision engineering acquisitions. Target fabricators with tournament-certification credentials and transatlantic REACH compliance capabilities. Watch synthetic felt durability benchmarks as the inflection signal determining material substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Professional-Grade Refurbishment Program Launch | Captures recurring revenue from bar and club felt replacement cycles unbundled from original equipment sales. |
| Weather-Resistant Material Formulation Investment | Penetrates outdoor patio entertainment spaces in coastal Queensland and subtropical Florida climates. |
| ISO 9001 Certification Pathway Completion | Gates municipal recreational center procurement in Bavaria and North Rhine-Westphalia youth-serving facilities. |
| Dealer Network Loyalty Program Expansion | Defends showroom traffic against contractor-coordinated multi-vendor basement renovation procurement. |
| Dual-Formulation Inventory for REACH Compliance | Maintains European export market access as ECHA restrictions eliminate historical wood preservative compounds. |
Research Approach
Operator-level perspectives from recreation room contractors, municipal procurement officers, slate quarry operations managers, and dealer network principals anchored the qualitative base. These insights combined with secondary validation from EPA enforcement records, CPSC safety standard filings, customs trade data on slate imports, and SEC disclosures from recreational equipment manufacturers. Bottom-up unit demand modeling triangulated against top-down spending pattern analysis across residential renovation and commercial entertainment verticals.
Scenario-bracketing around regulatory enforcement intensity and material substitution velocity framed the projection horizon. Segmentation dimensions modeled include material substrate, table type certification tier, size specification, and target audience procurement channel. CAGRs derived from installed base turnover rates, replacement cycle compression in commercial venues, and expansion coefficients for outdoor category penetration. Industry-specific inputs incorporated IRA residential energy credit eligibility patterns and artisan labor pool attrition rates.
Stress conditions across slate supply disruption, aluminum commodity price spikes, and REACH chemical registration expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory stability and material science advancement trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Asia-Pacific Free Standing Electrical Height-Adjustable Tables Market
Furniture
Kids Table and Chair Market
Furniture
Massive Wood Slabs Market
Furniture
North America Smart Furniture Market
Furniture
Europe Smart Furniture Market
Furniture
Contract Furniture Market
Furniture
Wooden Furniture Market
Furniture
Russia Home Furniture Market
Furniture
Bar Stools Market
Furniture
Europe Sustainable Furniture Market
Furniture
China Home Furniture Market
Furniture
Unfinished Wood Furniture Market
Furniture
North America Free Standing Electrical Height-Adjustable Tables Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Study Carrels Market
Furniture
Europe and Middle East Demountable Partitions Market