
 Global Home Furniture Market | 2026-2036
Global Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Furniture Market Analysis
Multi-family housing developers and build-to-rent operators is consolidating procurement volumes, shifting bargaining power toward institutional buyers. IKEA leverages its captive supply chain and flat-pack logistics to anchor cost leadership across mass-market segments. Williams-Sonoma differentiates through direct-to-consumer channel control and design-led positioning in premium upholstery. Ashley Furniture Industries sustains manufacturing scale across North American production footprints, competing on delivery speed and SKU breadth.
Home furniture encompasses movable objects designed for residential interior spaces, typically constructed from engineered wood substrates, solid timber, metal framing, or foam-cushioned upholstery systems finished with textiles or leather, serving functional seating, storage, surface, and sleep purposes. Sofas and upholstered chairs command the largest share of consumer spending within product type segments, while cabinets capture higher margins through customization complexity and installation services. Wood materials dominate volume production, though metal frames are gaining share in modern and contemporary style categories where minimalism and durability intersect with urban density constraints.
The EPA regulates formaldehyde emissions from composite wood products under TSCA Title VI, while the EU ECHA enforces REACH restrictions on flame retardants and volatile organic compounds in furniture coatings. California's Air Resources Board maintains the most stringent state-level emission standards, effectively shaping national product specifications for US manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and chemical disclosure mandates, as compliance costs will increasingly separate certified suppliers from informal competitors.
Market Dynamics
Residential real estate developers are consolidating procurement volumes across multi-unit housing projects, shifting bargaining power toward institutional buyers and compressing margins for fragmented component suppliers.
Growth Catalysts
- EU Green Deal compliance requirements:The EU Green Deal and F-Gas Regulation are tightening material standards for foam and adhesive suppliers, accelerating certified supplier consolidation.
- Urban household formation in India:India's PLI scheme for wood processing is accelerating domestic production capacity to serve concentrated demand from new urban households.
- Flat-pack logistics optimization:Engineered packaging systems are reducing last-mile delivery costs for mass-market retailers serving density-constrained metropolitan areas.
Market Restraints
- Formaldehyde emission compliance costs:The EPA's TSCA Title VI and California Air Resources Board standards impose testing and certification burdens that informal competitors cannot absorb.
- Solid timber supply concentration:Sustainable hardwood sourcing concentrates in certified forestry operations across limited geographies, constraining volume flexibility.
- Flame retardant substitution complexity:ECHA REACH restrictions on halogenated compounds force reformulation cycles that delay product launches by 12-18 months.
Strategic Opportunities
- Build-to-rent operator procurement consolidation:Institutional landlords across the United States and United Kingdom are centralizing furniture specification for standardized unit fit-outs.
- Metal frame urban furniture systems:Minimalist metal framing is expanding into contemporary residential segments where durability requirements intersect with space constraints.
- Extended producer responsibility frameworks:European Union circular economy mandates are creating closed-loop service revenue models for take-back and refurbishment operations.
Industry Challenges
- Multi-material certification coordination:Composite products combining wood, metal, foam, and textiles require parallel compliance tracks across EPA, ECHA, and BIS jurisdictions.
- SKU proliferation complexity:Customization demands for cabinet and storage systems fragment production runs, compressing equipment utilization rates at manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Furniture Market |
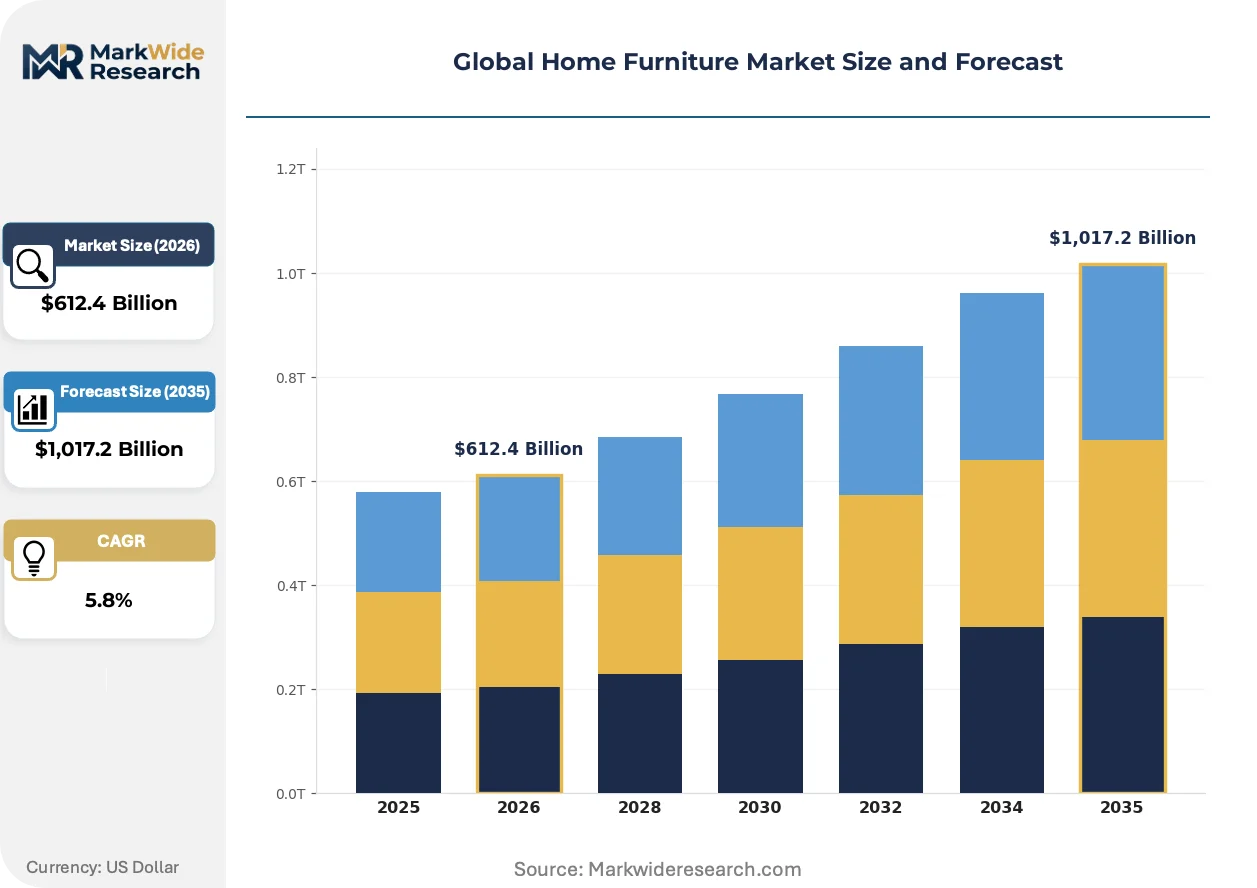
| Market Size in 2026 | $612.4 Billion |
| Market Size in 2035 | $1,017.2 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Metal, Upholstery, Glass Style: Modern, Traditional, Rustic, Contemporary Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Ashley Furniture Industries, MillerKnoll, IKEA, Okamura Corporation, HNI Corporation, Wayfair, Steelcase, Hobby Lobby, Williams-Sonoma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Furniture Market Emerging Trajectories
Digital configuration tools and sustainable material substitution are compressing traditional design-to-delivery cycles while reshaping supplier qualification criteria across residential furniture procurement.
Cross-laminated timber and engineered wood substrates are expanding into structural and semi-structural furniture applications previously dominated by solid timber. Multi-family housing developers in Germany and Austria are specifying these materials for built-in storage and seating systems to meet embodied carbon targets. The technology is expanding into premium residential segments as certification schemes validate performance equivalence.
REACH restrictions on volatile organic compounds in furniture coatings are forcing water-based and UV-cured system adoption across European manufacturing footprints. Suppliers serving IKEA and regional retailers are retrofitting spray lines to maintain market access. Upholstery and cabinet segments face the steepest compliance timelines due to surface area exposure calculations.
Direct-to-consumer channel control is displacing traditional wholesale showroom networks in premium upholstery and bedroom furniture categories. Williams-Sonoma and comparable operators are capturing full margin stacks while reducing inventory risk through made-to-order production models. This pattern concentrates in United States and United Kingdom metropolitan markets where digital-native purchase behavior dominates household formation cohorts.
Global Home Furniture Market Segmentation
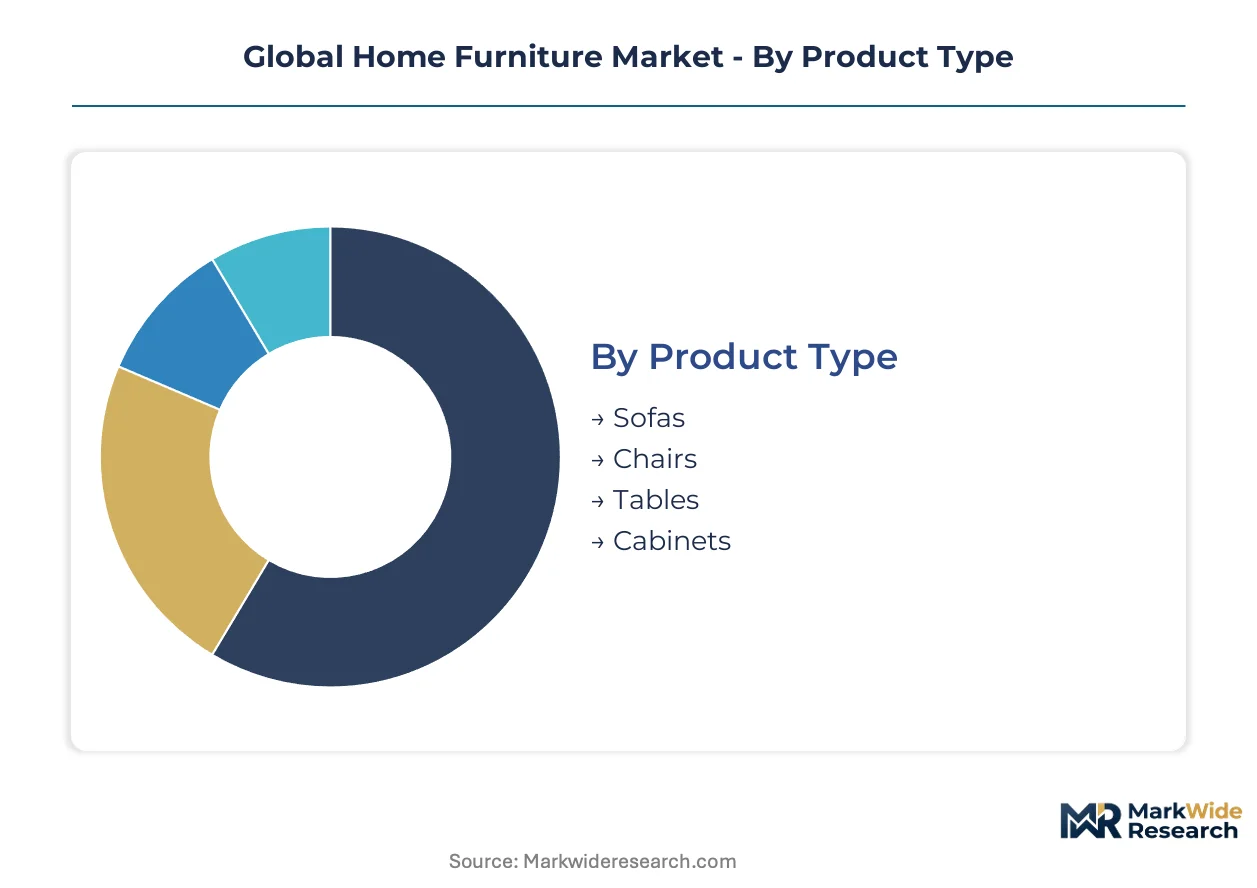
Segmentation in home furniture reveals divergent replacement cycles and margin structures across product categories. Material specifications and distribution economics create distinct competitive arenas that reward different capabilities. Understanding these divisions clarifies where procurement power concentrates and where supplier differentiation holds value.
Product Type:
Replacement cycles stretch from 3-5 years for seating to 15-20 years for storage systems, creating tiered revenue predictability across manufacturer portfolios.
- Sofas:Multi-seat upholstered systems with foam cushioning and textile or leather coverings. Demand concentrates in build-to-rent operator procurement across the United Kingdom and United States, where standardized unit fit-outs require durable fabric specifications and modular configurations.
- Chairs:Single-seat variants spanning dining, accent, and recliner configurations. Dining chair demand clusters in Indian urban household formation, driven by apartment-scale space constraints and PLI scheme support for domestic wood processing capacity.
- Tables:Surface systems for dining, work, and occasional use. Metal frame variants gain share in contemporary residential segments where durability intersects with space efficiency.
- Cabinets:Storage and display systems with higher customization complexity. Installation service requirements and bespoke dimensions protect margin structures against mass-market commoditization.
Volume placements concentrate in Sofas; the faster expansion belongs to Cabinets.
Material:
Cost tier stratification separates certified sustainable supply from informal sourcing, with compliance burdens reshaping competitive viability across material categories.
- Wood:Engineered substrates and solid timber dominate volume production. Cross-laminated timber expands into German and Austrian multi-family housing specifications as developers target embodied carbon reduction in built-in storage applications.
- Metal:Framing systems for contemporary and minimalist designs. Urban density constraints in Indian and Chinese metropolitan markets accelerate adoption for space-efficient, durable residential furniture.
- Upholstery:Foam-cushioned systems with textile or leather coverings. ECHA REACH restrictions on halogenated flame retardants force 12-18 month reformulation cycles that delay product launches for European market access.
- Glass:Surface and accent applications in contemporary styling. Higher freight fragility limits sourcing radius, concentrating supply near major consumption clusters.
Wood captures the largest volume placement; Metal is climbing the fastest as urban residential density intensifies.
Style:
Application context determines style selection, with residential versus commercial end-use creating divergent specification requirements and margin profiles.
- Modern:Clean lines and minimal ornamentation with functional priority. Metal and engineered wood material combinations dominate specifications for metropolitan apartment markets in India and China.
- Traditional:Ornamented designs referencing historical forms. Solid timber requirements and craft-intensive production concentrate supply in certified forestry operations with limited volume flexibility.
- Rustic:Distressed finishes and natural material emphasis. Smaller production scale and regional aesthetic variation fragment supplier concentration across North American and European markets.
- Contemporary:Current trend-responsive designs blending multiple influences. Fastest product turnover creates inventory risk that direct-to-consumer channels mitigate through made-to-order production models.
Modern styling holds the deepest volume placement; Contemporary is gaining share fastest through channel innovation.
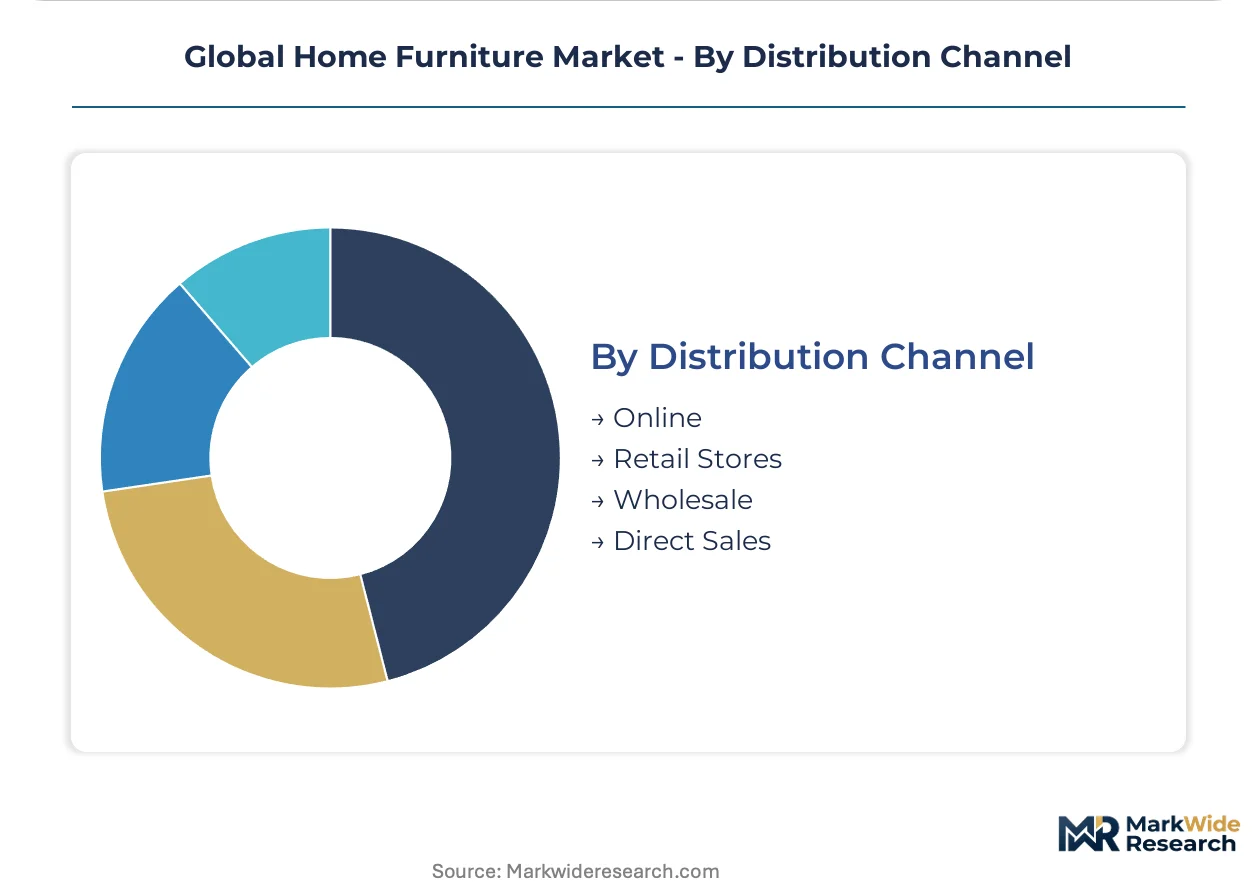
Distribution Channel:
Customer type and purchase behavior split channel economics, with digital-native cohorts forcing structural repositioning across wholesale networks.
- Online:Digital-native purchase journeys with configuration tools and home delivery. Flat-pack logistics optimization reduces last-mile costs for density-constrained metropolitan areas served by mass-market retailers.
- Retail Stores:Physical showrooms with tactile evaluation and immediate fulfillment. Premium upholstery and bedroom categories retain showroom dependency where material quality assessment drives purchase decisions.
- Wholesale:B2B procurement for multi-unit housing and hospitality fit-outs. Institutional buyer consolidation shifts bargaining power toward volume aggregators and compresses margins for fragmented component suppliers.
- Direct Sales:Manufacturer-controlled channels capturing full margin stacks. Williams-Sonoma and comparable operators concentrate in United States and United Kingdom metropolitan markets with made-to-order production reducing inventory risk.
Retail Stores maintain the largest volume placement; Direct Sales shows the steepest expansion trajectory as premium brands capture margin control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand acceleration through urban household formation and domestic production incentives. Procurement patterns across major economies diverge between institutional volume buyers and premium direct-to-consumer channels.
United States
Build-to-rent operators centralize furniture specification for standardized unit fit-outs across metropolitan markets. The EPA's TSCA Title VI formaldehyde emission standards shape national product specifications through California Air Resources Board stringency. North Carolina's manufacturing corridor anchors upholstered furniture production serving eastern seaboard distribution networks.
Germany
Multi-family housing developers specify cross-laminated timber for built-in storage systems targeting embodied carbon reduction. ECHA REACH restrictions on volatile organic compounds in furniture coatings accelerate water-based and UV-cured system adoption. The Baden-Württemberg industrial cluster retrofits spray lines to maintain supply relationships with mass-market retailers.
India
Urban household formation drives apartment-scale furniture demand concentrated in space-efficient configurations. The PLI scheme for wood processing accelerates domestic production capacity expansion across organized manufacturing. Gujarat and Maharashtra host expanding fabrication clusters serving Delhi-Mumbai corridor consumption density.
China
Metropolitan density constraints accelerate metal frame furniture adoption for durability and space efficiency. SAMR enforces GB standards for composite wood product safety alongside dual carbon goals for manufacturing emissions reduction. The Pearl River Delta maintains concentration in export-oriented production serving international retail procurement.
United Kingdom
Institutional landlords consolidate procurement volumes for standardized residential unit fit-outs across London and regional cities. ECHA REACH flame retardant restrictions force reformulation cycles affecting upholstery import compliance. The Midlands manufacturing belt supplies build-to-rent operators with volume production capabilities.
Global Home Furniture Market Vendor Landscape
North American producers anchor one tier; European and Asian specialists hold differentiated positions through material certification and logistics optimization. The vendor base stratifies across mass-market scale operators, premium design-led houses, and component-focused fabricators. Three archetypes dominate: captive supply chain integrators, direct-to-consumer channel controllers, and manufacturing-scale delivery specialists. Consolidation concentrates through multi-unit housing procurement volume aggregation and certified supplier qualification barriers.
Among North American fabricators, Ashley Furniture Industries and Williams-Sonoma occupy positions at opposite ends of the pricing and channel spectrum. IKEA exemplifies the captive supply chain archetype through flat-pack logistics integration. These three entities represent the structural divergence between scale-driven manufacturing, premium direct-to-consumer control, and global retail logistics optimization that defines competitive positioning across residential furniture procurement.
| Leading Market Players |
|---|
| Ashley Furniture Industries |
| MillerKnoll |
| IKEA |
| Okamura Corporation |
| HNI Corporation |
| Wayfair |
| Steelcase |
| Hobby Lobby |
| Williams-Sonoma |
| Others |
Supply Flow & Price Mechanics
Build-to-rent operator procurement consolidation across the United States and United Kingdom is compressing component supplier margins and forcing certified manufacturers to absorb compliance costs that informal competitors cannot shoulder, widening the price-performance gap between qualified and unqualified supply tiers.
Pricing Analysis
Volume placements in mass-market seating run on thin margins while cabinet and storage systems retain pricing power through customization complexity and installation service bundling. Three-tier pricing structure across premium, standard, and economy levels separates Williams-Sonoma's direct-to-consumer positioning from IKEA's flat-pack cost leadership and Ashley Furniture's manufacturing-scale delivery model. Price differentiation hinges on certification grade and channel control, with EPA TSCA Title VI compliance acting as a gatekeeper that informal suppliers cannot cross. Pricing pressure stems from institutional buyer volume aggregation, with build-to-rent operators extracting concessions through standardized specification contracts that fragment component supplier bargaining power.
Supply Chain Analysis
Certification requirements under EPA TSCA Title VI, ECHA REACH, and India's BIS standards are consolidating qualified supplier pools and raising entry barriers for new manufacturing entrants. Production gravity centers on China, Vietnam, and India, with the Pearl River Delta maintaining export-oriented concentration and Gujarat-Maharashtra clusters expanding domestic capacity under PLI scheme support. Raw material sourcing draws from certified forestry operations for sustainable hardwood, engineered wood substrate facilities for volume production, and petrochemical supply chains for foam cushioning systems. Single-source vulnerability concentrates in halogenated flame retardant alternatives where ECHA reformulation timelines lag substitution demand. Distribution runs through flat-pack logistics networks for mass-market retailers, direct-to-consumer fulfillment for premium upholstery, and wholesale procurement channels for multi-unit housing developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-laminated timber and engineered wood substrates are displacing solid timber in structural furniture applications, creating a technology-transition phase where material certification and embodied carbon compliance reshape supplier qualification criteria.
For Market Incumbents: To counter informal competitor price erosion in mass-market seating, Ashley Furniture Industries and comparable manufacturers should deepen backward integration into engineered wood substrate production and secure captive supply of certified sustainable timber through long-term forestry partnerships. Channel control investments in direct-to-consumer platforms offer margin protection against wholesale buyer consolidation. For New Entrants and Emerging Players: EU Green Deal and F-Gas Regulation compliance requirements in Europe open a window for certified foam and adhesive specialists to capture share from reformulation-lagged incumbents. Metal frame urban furniture systems for Indian and Chinese metropolitan density constraints represent the most penetrable white space, with made-to-order production models reducing inventory risk against fast-turnover contemporary styling demands. For Investors and Strategic Acquirers: The window for entry favors mid-scale fabricators with existing certification infrastructure and regional logistics optimization. Acquisition targets should demonstrate qualified supplier status across EPA, ECHA, and BIS jurisdictions with production footprints in India or Southeast Asia. Watch for ECHA REACH restriction expansion into additional halogenated compounds as an inflection indicator that would accelerate certified supplier consolidation and strand non-compliant manufacturing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Laminated Timber Certification | Baden-Württemberg cluster retrofits enable German multi-family housing carbon compliance. |
| Flat-Pack Logistics Optimization | IKEA's packaging density reduces last-mile costs for density-constrained metropolitan delivery. |
| Direct-to-Consumer Channel Launch | Williams-Sonoma's made-to-order model captures full margin stacks in premium upholstery. |
| Flame Retardant Reformulation | ECHA REACH compliance delays 12-18 month product launches for European market access. |
| PLI Scheme Capacity Expansion | Gujarat fabrication clusters serve Delhi-Mumbai corridor household formation demand. |
Methodological Framework
Multi-period observation of urban household formation rates, institutional procurement contract awards, and regulatory compliance timelines anchored the trend analysis, supplemented by interviews with residential real estate development executives, furniture procurement managers at build-to-rent operators, foam and adhesive supplier technical directors, and certified forestry operations managers. Secondary validation drew from EPA TSCA Title VI filing databases, ECHA REACH restriction announcements, India's PLI scheme disbursement records, and customs trade data for engineered wood substrate flows. Bottom-up production capacity assessments triangulated against top-down consumption estimates across the analysis window.
Input-output matrix modeling connected raw material supply constraints, manufacturing capacity utilization, and distribution channel economics to project segment-level volume and value trajectories. Segmentation dimensions included product type, material specification, styling category, and distribution channel, with additional modeling of certification tier stratification. CAGRs were derived from regression analysis of historical replacement cycle patterns and forward projection of regulatory compliance cost absorption rates. Cross-laminated timber adoption curves and metal frame penetration in urban residential segments provided industry-specific forecast inputs.
The model assumes a particular technology adoption path for engineered wood substrates; alternative pathways for solid timber certification or bio-based foam alternatives would alter the outlook for material cost structures and supplier competitive positioning. Forecasts reflect assumptions regarding ECHA REACH enforcement intensity, PLI scheme continuation, and build-to-rent operator procurement expansion that may shift with policy or macroeconomic conditions. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
Study Carrels Market
Furniture
North America Smart Furniture Market
Furniture
US Multifunctional Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Outdoor Furniture and Grills Market
Furniture
Europe Free Standing Electrical Height-Adjustable Tables Market
Furniture
Poland Home Furniture Market
Furniture
France Furniture Market
Furniture
Bar Stools Market
Furniture
Europe Luxury Furniture Market
Furniture
Ready-To-Assemble (RTA) Furniture Market
Furniture
China Home Furniture Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
Europe Multifunctional Furniture Market
Furniture
Bean Bag Chairs Market