
 Middle East and Africa Wood Based Panel Market | 2026-2036
Middle East and Africa Wood Based Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Wood Based Panel Market Foresight
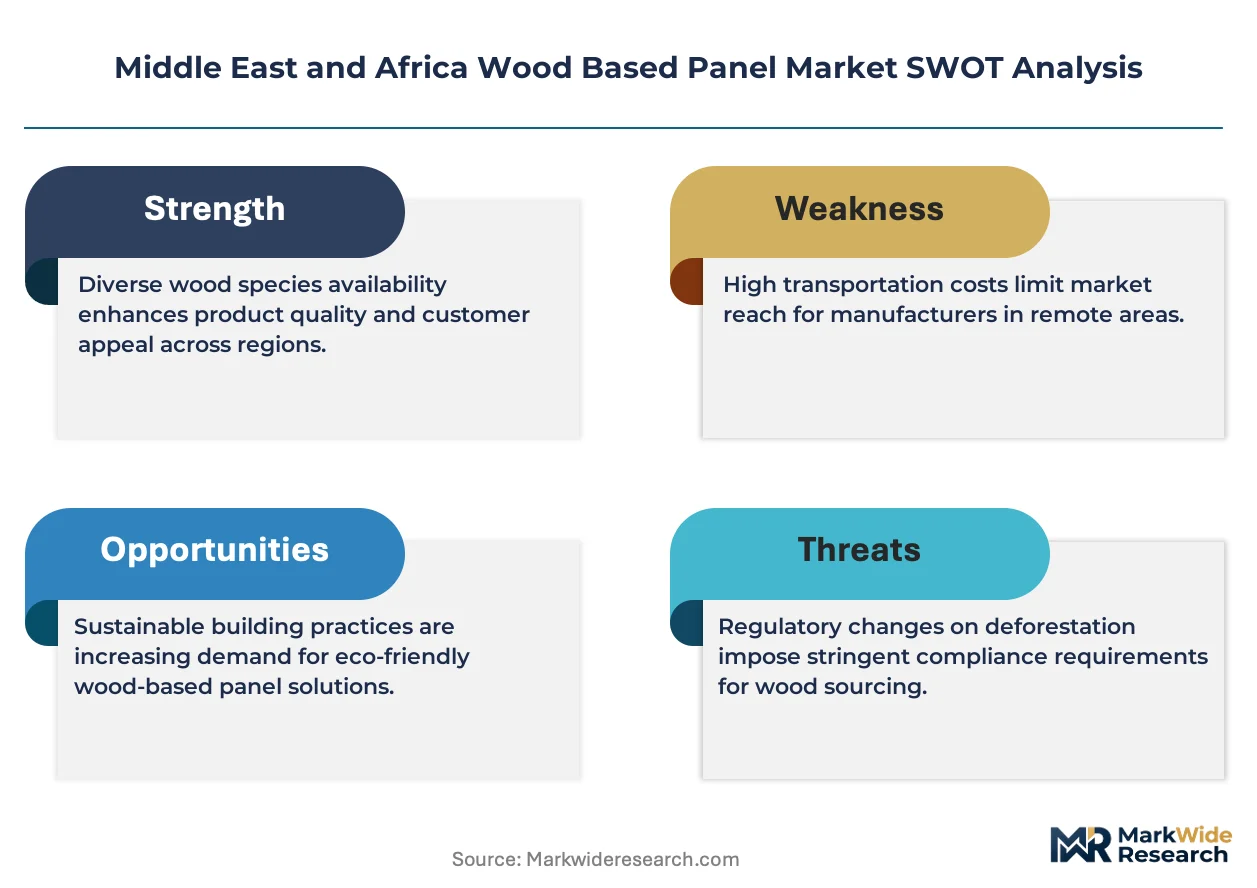
Saudi Arabia's industrial zone expansions near Jeddah and Riyadh is rewriting regional supply geography for engineered wood products. Kronospan anchors its Middle East footprint through large-format particle board and MDF capacity serving Gulf construction markets. Kastamonu Entegre leverages Turkish manufacturing proximity to compete on logistics cost into North African and Levantine markets. Georgia-Pacific sustains brand recognition among Saudi contractors specifying certified structural panels for hospitality and mixed-use developments.
Middle East and Africa wood based panels comprise engineered sheet materials manufactured from wood fibers, particles, or veneers bonded under heat and pressure with formaldehyde-based or bio-based resins, typically achieving densities between 600 and 800 kg/m³ for MDF and bending strengths exceeding 30 MPa for structural plywood grades. These products primarily serve as dimensionally stable substrates for furniture manufacturing, structural sheathing in light-frame construction, and finished flooring systems across commercial and residential builds. MDF captures premium margin pools in furniture and interior fit-out applications where surface smoothness enables direct lamination and paint finishing. Plywood dominates structural applications in the construction segment across Egypt and Nigeria where established carpentry trades favor familiar handling characteristics. OSB remains an emerging category with fastest-growing adoption in South African residential framing as builders transition from solid-sawn lumber to engineered systems.
Saudi Arabia's SABER platform and UAE Civil Defense fire-rated material mandates shape product certification pathways and import clearance protocols for panel suppliers entering Gulf markets. Egypt's GOEIC import inspection regime and South Africa's NRCS compulsory specifications for formaldehyde emissions create layered compliance obligations that filter market access by documentation capability and testing investment. Nigeria's SON product registration requirements add further procedural depth for West African market penetration. Stakeholders must monitor evolving Gulf green building rating systems and potential harmonization of VOC limits across EAC and SADC trade blocs to anticipate specification shifts before tender cycles close.
Market Dynamics
Saudi Arabia's megaproject pipeline and the UAE's fire-rated material mandates are compressing product certification timelines and concentrating procurement decisions among tier-one contractors capable of navigating multi-jurisdictional compliance.
Growth Catalysts
- SABER conformity platform:Saudi Arabia's mandatory product registration system is filtering import channels toward documented suppliers with in-country testing partnerships, elevating compliance capability as a competitive barrier.
- Levantine furniture manufacturing:Turkish producers are expanding MDF offtake for export-oriented cabinetry, pulling regional particle board demand toward higher-density engineered substrates.
- Formaldehyde-free resin chemistry:Bio-based adhesive systems are penetrating premium interior fit-out specifications in Dubai and Riyadh hospitality developments where LEED-equivalent ratings apply.
Market Restraints
- Softwood fiber cost volatility:Russian birch veneer supply disruptions have elevated raw material costs for Egyptian and Turkish plywood mills dependent on Black Sea log flows.
- Import concentration risk:Jeddah and Jebel Ali port clusters handle over 60% of Gulf panel volume, creating single-point vulnerability for landlocked Saudi interior projects.
- Structural OSB performance gaps:African carpentry trades in Nigeria and Kenya continue favoring plywood familiarity over OSB nail-withdrawal resistance in humid coastal construction.
Strategic Opportunities
- South African residential framing transition:Builders in Gauteng and Western Cape are adopting light-frame engineered systems, opening OSB sheathing penetration in a plywood-dominant market.
- UAE green building rating convergence:Estidama Pearl and Al Safat mandates are creating specification pull for low-emission MDF in commercial interior packages.
- Direct contractor procurement platforms:Digital tendering systems are disintermediating traditional distributor layers for large-format particle board in Saudi giga-project material packages.
Industry Challenges
- Multi-jurisdictional certification timelines:Suppliers must sequence SABER registration, UAE Civil Defense fire testing, and Egypt GOEIC inspection without standardized mutual recognition.
- Skilled resin formulation chemists:The shift from urea-formaldehyde to MDI and bio-based binders has outpaced technical training pipelines in North African manufacturing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Wood Based Panel Market |
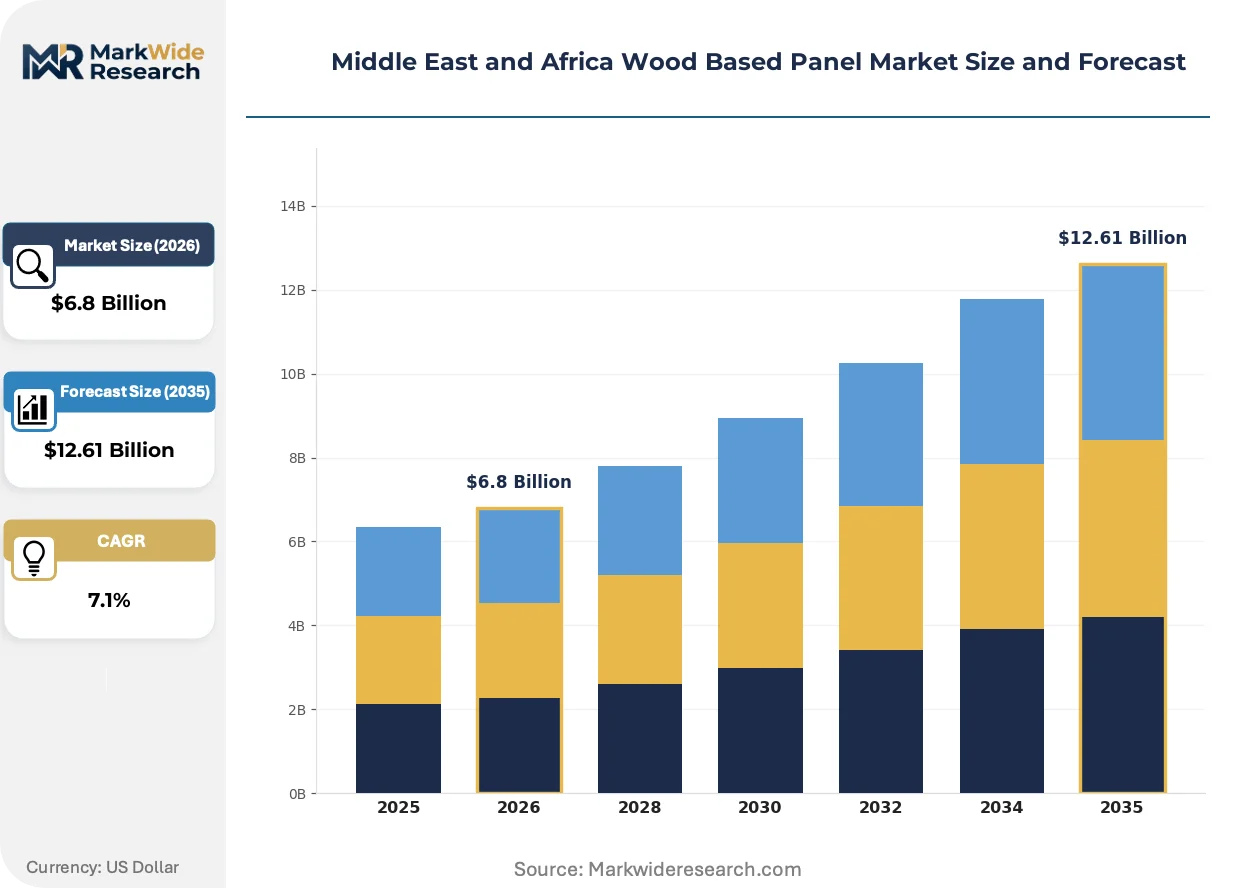
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.61 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plywood, Particle Board, MDF, OSB Application: Furniture, Flooring, Packaging, Construction End User: Manufacturers, Retailers, Designers, Contractors Distribution Channel: Direct Sales, Distributors, Online Sales, Retail Outlets |
| Companies Covered | Arauco, Georgia-Pacific, Kronospan, Sonae Arauco, Duratex, Kastamonu Entegre, Norbord Inc., West Fraser Timber Co. Ltd., EGGER Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Wood Based Panel Market Shifts & Advancements
Panel manufacturing across the Middle East and Africa is integrating digital process control and alternative binder chemistry while procurement patterns fragment between traditional distribution and project-direct supply.
Industrial IoT sensor networks are digitizing press temperature and resin spread monitoring in Saudi and UAE particle board plants. Large-format producers are retrofitting continuous presses with real-time density profiling to reduce raw fiber consumption per panel. This precision is digitizing quality assurance documentation required for SABER platform upload, compressing batch release cycles from days to hours.
Saudi Arabia's SFDA and SASO have tightened formaldehyde emission thresholds under revised technical regulations mirroring E1-grade European benchmarks. Panel importers must now submit third-party laboratory testing from SASO-accredited facilities before customs clearance. Egyptian manufacturers serving Gulf markets are responding by retrofitting press ventilation systems and switching to lower-emitting resin formulations.
Contractor procurement in the UAE and Saudi Arabia is fragmenting between traditional distributor relationships and direct mill partnerships for giga-project volumes. Large developers are establishing captive supply agreements with Kronospan and regional Turkish producers, bypassing wholesale layers. This bifurcation is most visible in Riyadh's Diriyah and Qiddiya developments where material packages are sourced through centralized procurement offices rather than specification-driven distributor channels.
Middle East and Africa Wood Based Panel Market Segmentation
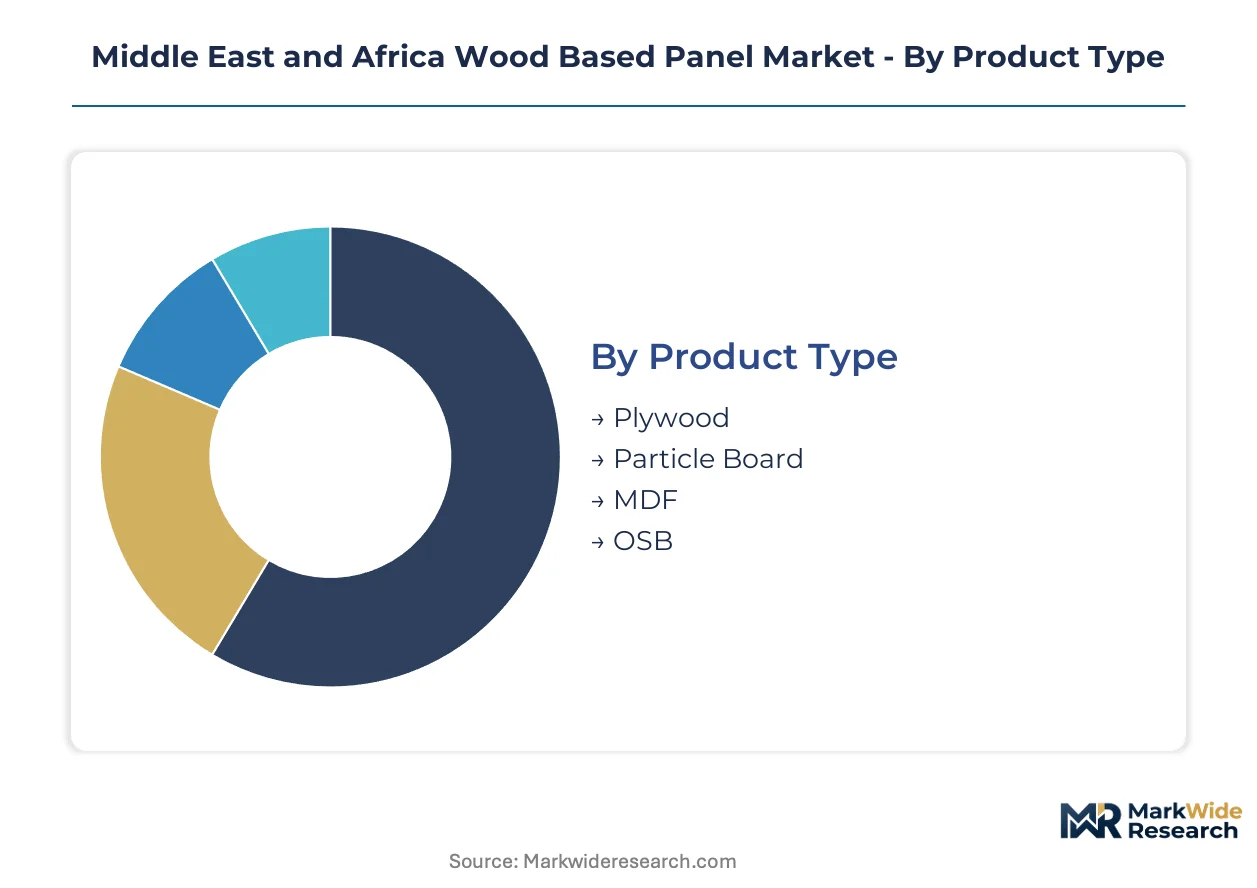
Segmentation in Middle East and Africa wood based panels reflects divergent performance requirements across humid coastal construction, precision furniture manufacturing, and fire-rated commercial interiors. Specification standards from Saudi SASO, UAE Civil Defense, and Egypt GOEIC create compliance-driven purchasing patterns that fragment demand by product chemistry and certification depth.
Product Type:
Use-case spectrum spans structural load-bearing through precision surfacing, with resin chemistry and density grading determining specification fit.
- MDF:Medium-density fiberboard achieves homogeneous surface smoothness through refined wood fiber refinement and continuous pressing, enabling direct lamination without sanding. Saudi hospitality developers specify low-emission MDF for interior fit-outs under Estidama Pearl ratings, with procurement consolidating through direct mill partnerships for giga-project volumes.
- Plywood:Cross-laminated veneer construction delivers bending strength exceeding 30 MPa in structural grades, with Egyptian and Nigerian carpentry trades favoring familiar handling over engineered alternatives. Black Sea birch supply disruptions have elevated raw material costs for Turkish and Egyptian mills dependent on Russian log flows.
- Particle Board:Wood particle and resin composites serve cost-sensitive furniture substrates and non-structural applications across North African manufacturing.
- OSB:Oriented strand board delivers dimensional stability through aligned wood flake layering, with South African residential framers in Gauteng and Western Cape adopting the category fastest as builders transition from solid-sawn lumber.
Established volume favors plywood; emerging adoption favors OSB.
Application:
Application mix tracks construction cycle intensity and furniture export manufacturing expansion across Turkish and Levantine production zones.
- Construction:Structural sheathing, concrete formwork, and interior wall systems consume fire-rated and moisture-resistant grades. UAE Civil Defense mandates compress certification timelines for multi-jurisdictional project supply.
- Furniture:Cabinetry, case goods, and fixture manufacturing pull premium MDF and particle board into Turkish export-oriented production serving European retail channels.
- Flooring:Underlayment and finished surface applications specify density-graded panels with moisture resistance for Gulf climate conditions.
- Packaging:Industrial crating and pallet manufacturing absorb lower-grade particle board and softwood plywood in Egyptian and Nigerian logistics sectors.
Construction commands procurement scale; furniture manufacturing drives margin capture.
End User:
Customer type determines specification authority and certification documentation burden.
- Contractors:Tier-one Saudi and UAE construction firms navigate SABER registration and Civil Defense fire testing directly, establishing captive supply agreements that disintermediate traditional distribution.
- Manufacturers:Turkish and Egyptian furniture producers specify substrate grades based on export market emission standards and surface finish requirements.
- Retailers:Big-box and specialty channels stock commodity grades for consumer DIY and small contractor pickup in South African and Nigerian urban centers.
- Designers:Interior specification consultants in Dubai and Riyadh hospitality projects drive low-emission and bio-based resin selection through LEED-equivalent rating compliance.
Contractors consolidate volume; designers influence premium specification.
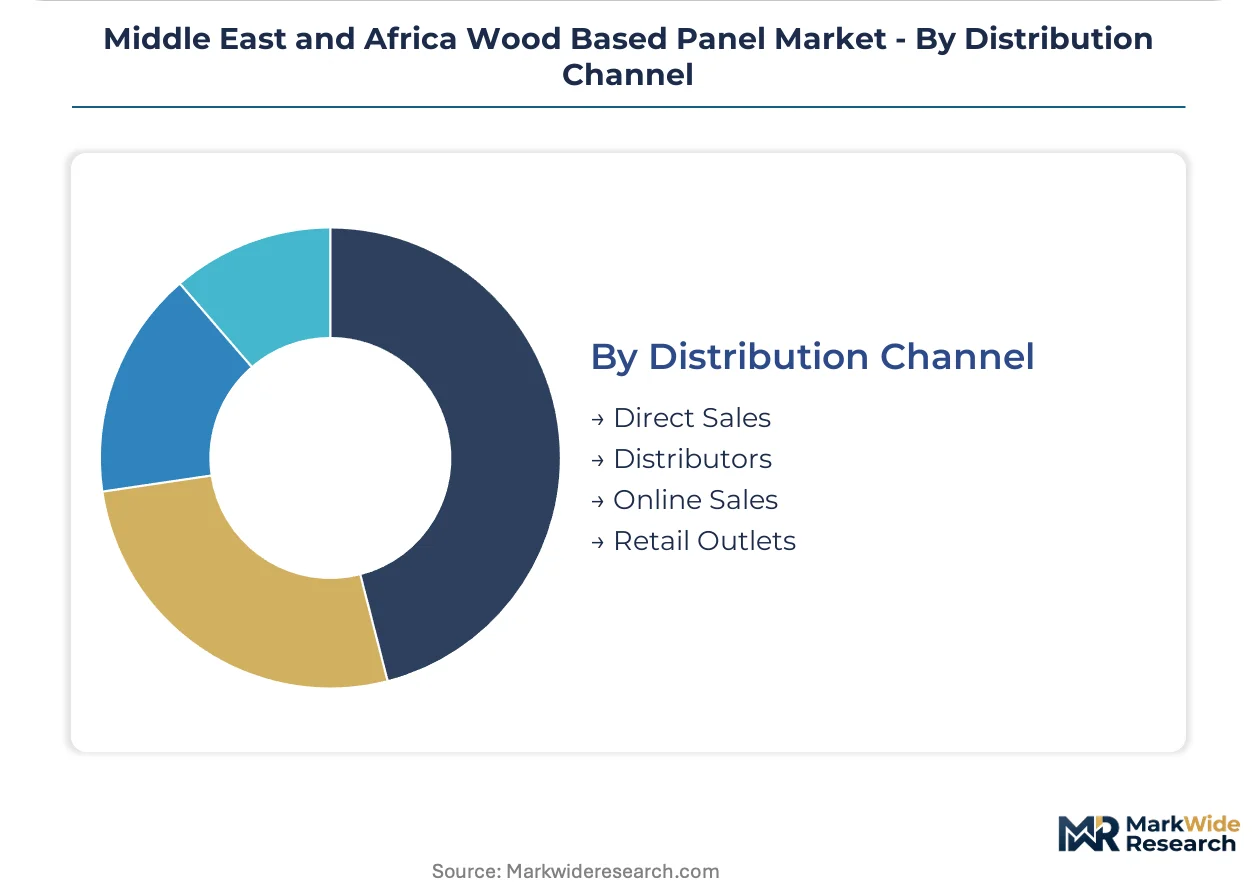
Distribution Channel:
Channel structure bifurcates between project-direct procurement and traditional wholesale layers.
- Direct Sales:Mill-to-developer agreements for Saudi giga-projects bypass distributor margins, with centralized procurement offices in Riyadh handling material packages for Diriyah and Qiddiya developments.
- Distributors:Traditional wholesale networks maintain inventory positions in Jeddah and Jebel Ali port clusters, serving mid-tier contractors and regional fabricators with documented SASO-compliant stock.
- Online Sales:Digital tendering platforms and B2B marketplaces are penetrating specification-grade procurement for standardized panel dimensions and certified grades.
- Retail Outlets:Physical storefronts in Lagos, Cairo, and Johannesburg serve small-scale builders and furniture makers with immediate availability of commodity thicknesses.
Direct sales capture giga-project volume; distributors retain fragmented demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO anchors compliance architecture across Gulf markets, compressing certification timelines for panel suppliers serving Saudi Arabia's construction acceleration. The region fragments into distinct regulatory zones where SABER, UAE Civil Defense, and Egypt GOEIC create non-overlapping entry requirements.
Saudi Arabia
Diriyah and Qiddiya megaprojects pull giga-scale particle board and MDF volumes through centralized procurement offices. SABER platform mandates third-party laboratory testing from SASO-accredited facilities before customs clearance. Riyadh industrial zones near the capital host expanding engineered wood capacity serving interior fit-out specifications.
United Arab Emirates
Dubai hospitality developments specify low-emission MDF under Estidama Pearl ratings for LEED-equivalent compliance. UAE Civil Defense fire-rated material mandates shape product certification pathways for commercial interior packages. Jebel Ali port clusters handle concentrated import volume, creating single-point vulnerability for material flows.
Egypt
Cairo and Alexandria furniture manufacturing zones absorb cost-sensitive particle board for domestic cabinetry and export-oriented production. GOEIC import inspection regime filters market access by documentation capability and testing investment. Egyptian mills retrofit press ventilation systems to meet Gulf market formaldehyde thresholds.
South Africa
Gauteng and Western Cape residential framers adopt light-frame engineered systems, opening OSB sheathing penetration in plywood-dominant construction. NRCS compulsory specifications for formaldehyde emissions create compliance obligations for local manufacturing. Cape Town distribution networks serve mid-tier contractors with documented stock.
Turkey
Kastamonu and Turkish manufacturing zones leverage proximity to compete on logistics cost into North African and Levantine markets. Export-oriented cabinetry production pulls regional particle board demand toward higher-density engineered substrates. Istanbul-based producers navigate multi-jurisdictional certification for Gulf market access.
Middle East and Africa Wood Based Panel Market Competitive Landscape
Pan-regional multinationals and Turkish proximity players split the market across Gulf megaproject supply and Levantine manufacturing feedstock. Tier-one contractors consolidate procurement through captive supply agreements, disintermediating traditional wholesale layers. Two strategic archetypes dominate: large-format continuous-press operators serving giga-project volume, and regional specialists competing on logistics cost into fragmented North African markets. Capacity expansion and direct mill-to-developer partnerships represent the dominant competitive vectors.
Within the large-format operator tier, Kronospan anchors Middle East footprint through substantial particle board and MDF capacity. Kastamonu Entegre exemplifies Turkish proximity-based competition into Levantine and North African markets. Georgia-Pacific occupies a position among contractors specifying certified structural panels for hospitality and mixed-use developments.
| Leading Market Players |
|---|
| Arauco |
| Georgia-Pacific |
| Kronospan |
| Sonae Arauco |
| Duratex |
| Kastamonu Entegre |
| Norbord Inc. |
| West Fraser Timber Co. Ltd. |
| EGGER Group |
| Others |
Supply & Pricing Matrix
Overcapacity in Turkish particle board mills is compressing export pricing into Egyptian and North African markets while elevating margin pressure on Gulf-proximate suppliers. This utilization gap drives divergent supplier behavior: Turkish producers prioritize volume throughput to cover fixed costs, whereas Saudi and UAE mills emphasize certification depth to defend premium positioning.
Pricing Analysis
Price spreads between Jeddah-port-delivered MDF and Alexandria-port particle board exceed transport-cost differentials alone, reflecting SASO-accredited testing premiums. Pricing stratifies across premium, standard, and economy tiers keyed to formaldehyde emission certification and fire-rating depth. Cost compression in Egyptian plywood runs through Black Sea birch supply disruptions, with Turkish mills absorbing fiber cost volatility. Tier-one Saudi contractors show lowest price sensitivity due to giga-project procurement centralization; Egyptian furniture manufacturers remain most price-sensitive.
Supply Chain Analysis
Export-control restrictions on Russian birch veneer have disrupted established raw material flows to Turkish and Egyptian plywood mills, forcing supply chain reconfiguration. Manufacturing concentrates in Turkey, Saudi Arabia, and Egypt, with Turkish capacity serving Levantine and North African offtake. Raw material dependencies center on Black Sea softwood logs, formaldehyde-based resins, and MDI binders. Single-source vulnerability sits with Jebel Ali and Jeddah port clusters handling concentrated Gulf import volume. Distribution runs through direct mill-to-developer agreements for Saudi megaprojects and traditional wholesale layers for fragmented North African demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat: SABER certification requirements and multi-jurisdictional testing obligations create switching costs that protect incumbent positions while filtering new entrants.
For Market Incumbents: Pre-empt margin erosion in Egyptian plywood by securing alternative birch veneer supply from Nordic or Baltic sources before Turkish competitors consolidate alternative fiber relationships. Deepen captive supply agreements with Riyadh and Dubai developers to lock out distributor-dependent challengers. Prioritize MDI resin formulation capability as bio-based adhesive demand accelerates under Estidama Pearl specifications. For New Entrants and Emerging Players: Kenyan and Nigerian OSB penetration remains structurally underpenetrated relative to South African adoption curves, offering white-space expansion for cost-positioned strand board producers. Target Gauteng residential framing contractors with nail-withdrawal performance documentation to overcome plywood familiarity bias. Enter through direct contractor procurement platforms disintermediating traditional Jebel Ali distributor layers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Turkish MDF producers serving European export-oriented cabinetry manufacturers through long-term offtake arrangements. Long-term viability hinges on resin chemistry transition capability and Gulf certification infrastructure. Acquisition targets should demonstrate SASO-accredited laboratory partnerships and established SABER platform navigation. The signal to watch is harmonization of VOC emission limits across EAC and SADC trade blocs, which would force portfolio reconfiguration toward low-emission capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive MDI supply secures margin control as bio-based adhesive specifications tighten under SASO and UAE Civil Defense mandates. |
| SASO-Accredited Laboratory Partnership | In-country testing capability compresses SABER registration timelines from weeks to days for Gulf market clearance. |
| Direct Mill-to-Developer Supply Agreement | Centralized procurement offices in Riyadh and Dubai favor bypassing traditional Jeddah and Jebel Ali distributor margins. |
| Continuous Press Digital Retrofit | Real-time density profiling reduces fiber consumption per panel while generating batch documentation for automated SABER upload. |
| Alternative Fiber Sourcing Program | Nordic and Baltic softwood supply diversification insulates Turkish and Egyptian mills from Black Sea birch disruption. |
Research Methodology
Initial hypotheses were tested against primary input from panel plant operations managers, Gulf procurement directors at tier-one construction firms, Turkish furniture manufacturing executives, and Egyptian GOEIC compliance officers, then refined through secondary validation. Primary fieldwork drew from customs and trade flow databases, SASO technical regulation filings, UAE Civil Defense fire-testing protocols, and SEC filings from publicly traded wood products multinationals. Bottom-up volume estimates by product grade and application were cross-checked against top-down construction spending and furniture export data.
Demand-supply balance modeling across the analysis window incorporated capacity utilization at Turkish continuous-press facilities, Saudi giga-project material take-off schedules, and South African residential framing transition rates. Segmentation dimensions included product chemistry, density grading, certification tier, end-use construction versus furniture manufacturing, and procurement channel structure. CAGRs were derived from regression analysis of historical consumption patterns against projected construction cycle intensity and export manufacturing expansion.
Practitioners should monitor Russian birch veneer supply restoration, Gulf green building rating harmonization, and EAC-SADC emission standard convergence for early signals of forecast deviation. Material shifts in resin feedstock cost structures or SABER platform procedural changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Upholstered Furniture Market
Furniture
Global OFF-THE-SHELF Second Hand Furniture Market
Furniture
North America Secondary Wood Products Market
Furniture
Europe School Furniture Market
Furniture
Bar Stools Market
Furniture
Europe Home Furniture Market
Furniture
North America Furniture Market
Furniture
Global Free Standing Electrical Height-Adjustable Tables Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Global Multifunctional Furniture Market
Furniture
Study Carrels Market
Furniture
Recliner Chair Market
Furniture
United States Home Furniture Market
Furniture
Asia-Pacific Contract Furniture Market
Furniture
Bamboo Furniture Market
Furniture
Global Folding Furniture Market