
 Piano Stools Market | 2026-2036
Piano Stools Market Size, Share, and Industry Trends Forecast 2026-2036
Piano Stools Market Insights
ISO 9001 quality management certification is rotating as a baseline gate for OEM partnerships with institutional buyers. Yamaha leverages its captive piano ecosystem to bundle stools with instrument sales, sustaining channel control across music education verticals. Roland competes through ergonomic R&D integration, while On-Stage anchors the mid-tier segment with cost-optimized folding designs for rental and touring applications.
A piano stool is a height-adjustable or fixed seating apparatus engineered to position a pianist's forearms parallel to the keyboard plane, typically constructed from hardwood frames with foam-padded upholstery and steel or wooden leg assemblies joined by mortise-and-tenon or bolted construction. Its primary commercial purpose centers on enabling proper posture during extended practice or performance sessions, reducing repetitive strain risk while accommodating player anthropometric variation. Adjustable stools command premium positioning due to mechanical complexity and institutional procurement specifications, whereas fixed wooden variants dominate heritage restoration and traditional conservatory segments where aesthetic authenticity governs selection. Upholstered materials face margin compression from synthetic leather substitution, even as genuine leather sustains share in professional performance contexts.
EPA formaldehyde emission standards under TSCA Title VI govern composite wood components in U.S.-distributed products, while EU REACH restrictions on chromium-tanned leathers redirect upholstery sourcing toward vegetable-tanned alternatives. FSC chain-of-custody certification increasingly gates European retail placement, compelling Asian manufacturers to document sustainable timber provenance. Stakeholders must monitor evolving chemical disclosure thresholds across multiple jurisdictions, as diverging material compliance requirements threaten to fragment sourcing strategies and inflate testing overhead for cross-border suppliers.
Market Dynamics
REACH compliance deadlines and FSC timber certification requirements are restructuring supplier qualification protocols across European distribution channels, forcing Asian manufacturers to rebuild documentation systems or exit institutional procurement pipelines entirely.
Growth Catalysts
- Post-pandemic conservatory enrollment:Music education institutions in Germany and the United States are replacing aging seating inventories as student numbers stabilize, triggering replacement cycles for adjustable-height models.
- Dual carbon goals:China's MIIT timber sourcing directives are accelerating domestic FSC-equivalent certification adoption, opening previously restricted export pathways to European retailers.
- Ergonomic R&D integration:Biomechanical seating research from physical therapy programs is reshaping institutional procurement specifications toward lumbar-support designs.
Market Restraints
- Hardwood input cost volatility:Beech and maple price fluctuations from Eastern European sawmills are compressing margins for fixed-wooden-stool manufacturers.
- Supply concentration risk:Chromium-tanned leather upholstery sourcing clusters in Italy and Spain face ECHA substitution mandates, creating single-source vulnerability.
- Technical limitation:Pneumatic height-adjustment mechanisms require precision machining capabilities scarce among mid-tier Chinese suppliers.
Strategic Opportunities
- Underpenetrated home studio segment:Remote music production growth in Brazil and Mexico presents white space for collapsible, freight-optimized designs.
- EU Green Deal procurement incentives:Public tender scoring bonuses for circular-economy-certified products favor remanufacturable steel-frame constructions.
- Technology convergence:Integration of pressure-mapping sensors with practice-room digital systems enables posture-feedback subscription revenue models.
Industry Challenges
- Certification timeline compression:ISO 9001 audit backlogs at accredited bodies are delaying OEM partnership approvals by six to nine months.
- Skill gap in vegetable-tanning:Leather upholstery suppliers lack trained craftspeople for REACH-compliant tanning processes, constraining European production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piano Stools Market |
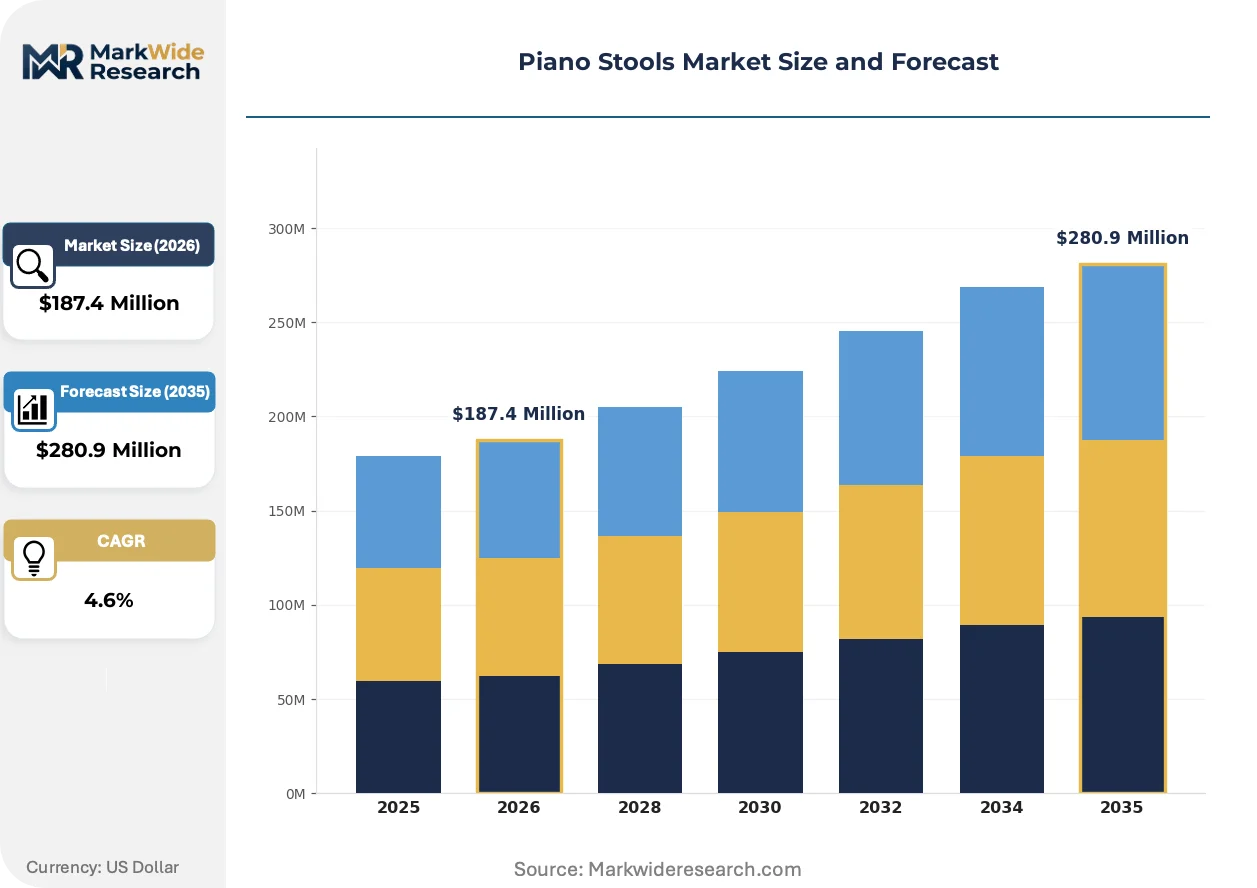
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Stools, Adjustable Stools, Padded Stools, Folding Stools Material: Wood, Metal, Upholstered, Plastic Style: Traditional, Contemporary, Vintage, Modern Usage: Practice, Performance, Studio, Home Use |
| Companies Covered | Jansen Piano Benches, Roland, Yamaha, Neewer, On-Stage, SONGMICS, George Hennessy, Griffin, VEVOR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piano Stools Market Trends and Innovations
Synthetic upholstery materials and sensor-integrated seating are displacing traditional construction methods, while regulatory disclosure requirements are fragmenting sourcing strategies across jurisdictions.
High-density polyurethane foam with silicone-coated fabric surfaces is displacing genuine leather in mid-tier institutional procurement. German conservatory buyers are adopting these materials at accelerated rates to meet budget constraints. This substitution is compressing premium upholstery margins while expanding addressable volume in price-sensitive segments.
EPA formaldehyde emission standards under TSCA Title VI now govern composite wood components in U.S.-distributed piano stools. Manufacturers must reconfigure particleboard and MDF sourcing to certified suppliers or face import detention. Products targeting the American home piano segment are responding by shifting to solid-wood frame constructions entirely.
Direct-to-institution procurement platforms are consolidating purchase authority previously dispersed through music retailer networks. Conservatory procurement offices in China are bypassing traditional distributors to negotiate volume contracts with OEMs. This disintermediation is most visible in Shanghai and Beijing, where municipal education bureaus centralize equipment acquisition.
Piano Stools Market Segmentation
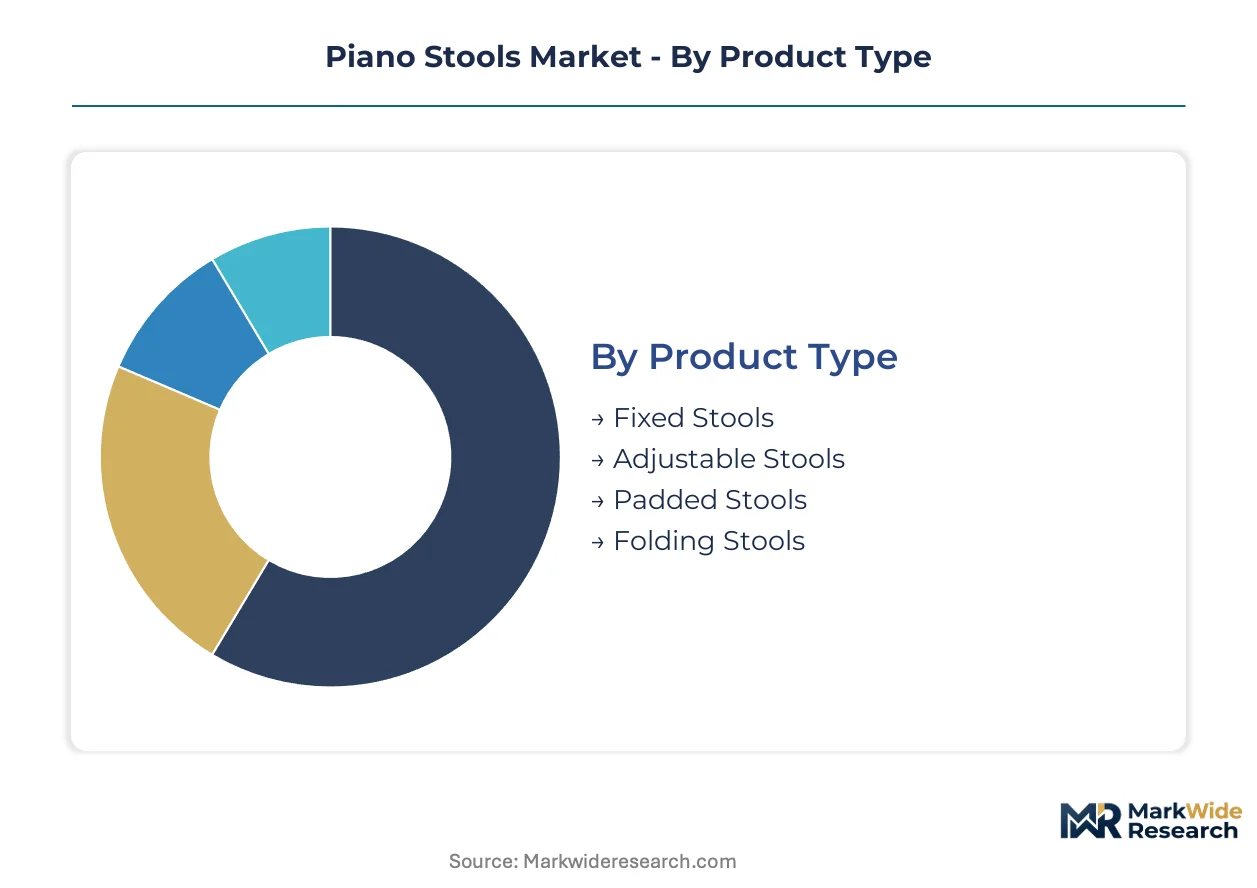
Piano stool procurement patterns diverge sharply between institutional buyers seeking durability certifications and home users prioritizing space efficiency. Segment boundaries increasingly blur as manufacturers engineer hybrid constructions—adjustable mechanisms with traditional aesthetics—to capture cross-category demand.
Product Type:
Domestic consumption in Germany and China favors fixed and adjustable stools for conservatory infrastructure, while export demand from Brazil and Mexico concentrates on folding variants for touring musicians.
- Adjustable Stools:Pneumatic or screw-driven height mechanisms accommodate player anthropometric variation from 16 to 22 inches. German and United States conservatories specify these for institutional procurement, driven by biomechanical research linking proper seat height to repetitive strain prevention.
- Fixed Stools:Mortise-and-tenon hardwood construction delivers aesthetic authenticity for heritage instrument pairings. Traditional conservatory segments in Vienna and Prague sustain demand despite limited height flexibility, constrained by budget compression in Eastern European markets.
- Padded Stools:Foam-upholstered fixed-height seating targets home practice environments with moderate session duration.
- Folding Stools:Collapsible steel-frame designs serve rental fleets and touring applications where freight optimization governs selection.
Fixed stools command the established base. The steepest expansion runs through adjustable stools.
Material:
Cost tiers separate premium timber constructions from mid-tier metal and synthetic alternatives, with upholstery materials experiencing the most volatile sourcing constraints.
- Wood:Beech and maple frames dominate heritage restoration and professional performance contexts. FSC chain-of-custody requirements are redirecting European retail procurement toward certified Eastern European and North American sawmills.
- Upholstered:Genuine leather sustains share in professional performance venues, while high-density polyurethane with silicone-coated fabric displaces it in German institutional buying.
- Metal:Steel and aluminum leg assemblies enable weight reduction for portable applications.
- Plastic:Injection-molded polypropylene targets entry-level home studio segments in price-sensitive emerging markets.
Wood retains volume leadership across premium tiers. Upholstered materials are gaining share fastest in institutional retrofit cycles.
Style:
Application context dictates aesthetic selection, with performance venues and educational institutions maintaining divergent authenticity requirements.
- Traditional:Ornate turned legs and hand-rubbed finishes align with classical instrument pairings in Vienna, Paris, and historic East Coast United States conservatories.
- Contemporary:Clean lines and neutral upholstery serve modern practice room installations where institutional branding overrides period matching.
- Vintage:Reproduction designs target restoration of pre-1950 instruments in private collections.
- Modern:Minimalist geometric forms appeal to home studio producers integrating seating into multipurpose residential spaces.
Traditional styling anchors conservatory procurement. Contemporary designs climb the fastest in municipal education bureau tenders.
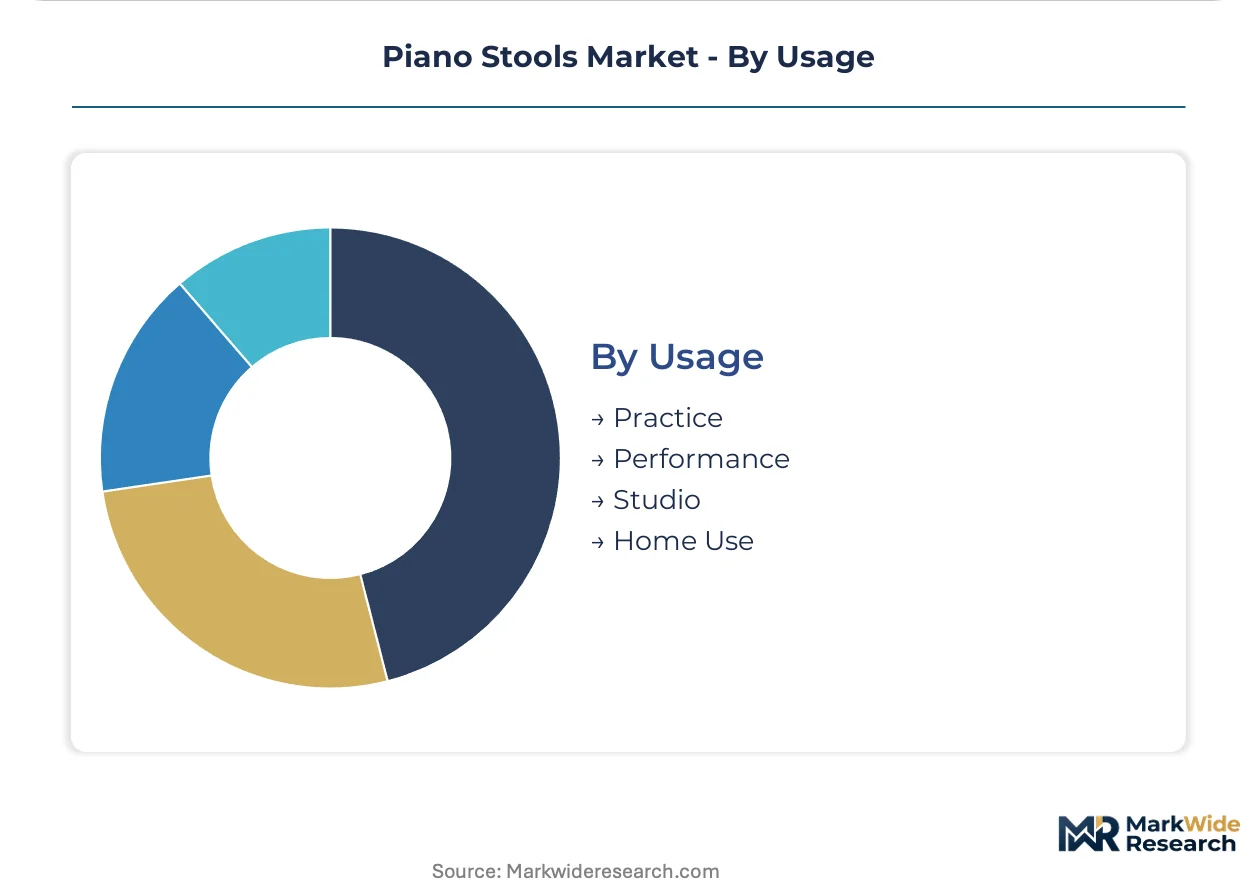
Usage:
Customer type fragmentation separates heavy-cycle institutional buyers from intermittent home users, with divergent durability specifications and replacement timelines.
- Practice:Extended daily use in educational settings demands reinforced joinery and replaceable upholstery components. United States university music programs drive specification tightening for lumbar support integration.
- Performance:Visibility requirements elevate aesthetic finish quality, with genuine leather and hand-polished wood sustaining premium positioning in concert hall procurement.
- Studio:Commercial recording facilities in Los Angeles, Nashville, and London prioritize adjustable mechanisms to accommodate session musician variation.
- Home Use:Space constraints and intermittent usage patterns favor folding or compact fixed designs in residential piano ownership segments.
Practice applications command the established base. Home use represents the steepest expansion trajectory as remote music production proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional buyers concentrate in Germany, the United States, and China, where conservatory infrastructure and home piano ownership sustain replacement cycles for adjustable and fixed seating configurations.
Germany
Conservatory enrollment stabilization drives adjustable stool procurement in Berlin and Leipzig. REACH compliance deadlines from ECHA force upholstery suppliers toward vegetable-tanned leather alternatives. Bavarian timber processors in Rosenheim document FSC chain-of-custody certification for export qualification.
United States
University music programs in Boston and New York specify lumbar-support designs for practice room retrofits. EPA formaldehyde emission standards under TSCA Title VI govern composite wood components in domestic distribution. Nashville recording studios anchor demand for adjustable mechanisms accommodating session musician variation.
China
MIIT timber sourcing directives accelerate domestic FSC-equivalent certification adoption for European export pathways. Municipal education bureaus in Shanghai and Beijing centralize equipment acquisition through direct OEM negotiation. Pearl River Delta manufacturers rebuild documentation systems to meet EU institutional procurement gates.
Japan
Heritage instrument restoration sustains fixed wooden stool demand in Tokyo and Osaka conservatories. METI quality standards influence institutional procurement specifications for hardwood frame durability. Nagoya-based piano manufacturers bundle seating with instrument sales to maintain channel control.
United Kingdom
Royal Academy of Music procurement drives premium upholstered specifications in London. EU Green Deal procurement incentives favor remanufacturable steel-frame constructions in municipal tender scoring. Birmingham manufacturing clusters adapt REACH-compliant tanning processes for European upholstery supply.
Piano Stools Market Competitive Landscape
Player mix skews toward diversified musical instrument manufacturers with captive seating divisions. Tiered competition separates premium ergonomic specialists from mid-tier folding specialists and entry-level mass fabricators. Strategic archetypes include instrument-integrated bundlers, ergonomic R&D integrators, and cost-optimized rental suppliers. Dominant competitive moves center on direct-to-institution platform development and compliance-forward material certification.
Among instrument-integrated manufacturers, Yamaha exemplifies the bundling archetype through its captive piano ecosystem. Roland occupies a position within the ergonomic specialization tier. On-Stage anchors the mid-tier segment with cost-optimized designs for rental and touring applications. These three represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| Jansen Piano Benches |
| Roland |
| Yamaha |
| Neewer |
| On-Stage |
| SONGMICS |
| George Hennessy |
| Griffin |
| VEVOR |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Eastern European beech and maple sawmills shapes both supply concentration and price floors for fixed wooden stool manufacturers. Scale economies in FSC-certified timber processing concentrate bargaining power among Bavarian and Polish suppliers, while mid-tier Asian metal fabricators compete on volume without comparable vertical control over raw material costs.
Pricing Analysis
Cost-plus contracts indexed to LME steel prices and FSC timber premiums dominate institutional procurement agreements. Three-tier pricing structure across premium, standard, and economy levels separates pneumatic adjustable stools with lumbar support from fixed wooden heritage designs and entry-level folding variants. Price differentiation hinges on ISO 9001 certification tier and after-sales service bundling. Cost compression in the mid-tier upholstered segment is intensifying as high-density polyurethane foam displaces genuine leather in German conservatory buying. Home studio buyers in Brazil and Mexico exhibit the highest price sensitivity, while Vienna and Paris heritage restoration clients accept substantial premiums for aesthetic authenticity.
Supply Chain Analysis
Italian and Spanish chromium-tanned leather clusters face ECHA substitution mandates that threaten single-source upholstery supply. Manufacturing draws from Chinese Pearl River Delta metal fabrication, Polish FSC-certified sawmills, and German pneumatic component specialists. Raw material dependencies include Eastern European beech and maple timber, Italian vegetable-tanned leather alternatives, and precision-machined steel gas springs from German suppliers. Tariff exposure on Chinese steel components into European markets elevates landed cost volatility. Distribution runs through direct-to-institution procurement platforms consolidating purchase authority previously held by music retailer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The piano stools market sits in early-cycle expansion as remote music production adoption in Latin America creates first-time buyer penetration in home studio segments previously served by improvised seating.
For Market Incumbents: Shield premium positioning by deepening FSC chain-of-custody documentation and captive piano bundling relationships against direct-to-institution platform disintermediation. Accelerate ISO 9001 audit scheduling to preempt six-to-nine-month partnership approval delays. Vertical integration into pneumatic mechanism sourcing mitigates single-source vulnerability from German precision machining suppliers. For New Entrants and Emerging Players: Differentiate on collapsible freight-optimized designs targeting underpenetrated home studio demand in São Paulo and Mexico City. Brazil and Mexico represent the most penetrable geographies given touring musician rental fleet expansion and residential piano ownership growth. A direct e-commerce go-to-market angle bypasses consolidated distributor networks that favor established OEM volume contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ergonomic R&D integrators with sensor-embedded seating patent pipelines over commodity metal fabricators. Long-term viability over the next decade hinges on posture-feedback subscription revenue models converging with practice-room digital systems. The signal to watch is municipal education bureau tender scoring shifts toward circular-economy-certified remanufacturable steel-frame constructions.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification Investment | Documents sustainable timber provenance for EU retail placement gates. |
| Direct-to-Institution Procurement Platform Development | Bypasses music retailer networks consolidating in Shanghai and Beijing. |
| Ergonomic R&D Integration with Biomechanical Research | Reshapes institutional specifications toward lumbar-support designs. |
| Vegetable-Tanned Leather Supply Partnership | Secures REACH-compliant upholstery alternatives from Italian suppliers. |
| Sensor-Integrated Seating Technology Launch | Enables posture-feedback subscription revenue in practice-room segments. |
Research Methodology
Desk research of trade customs data, conservatory procurement records, and FSC certification databases preceded structured interviews with piano manufacturer procurement directors, music education equipment buyers, pneumatic component suppliers, and hardwood timber traders. Secondary validation drew from MIIT timber sourcing directives, ECHA REACH compliance filings, and EPA TSCA Title VI certification registries. Bottom-up volume modeling triangulated against top-down market sizing from instrument shipment correlations.
Variance decomposition across product type, material tier, end-use application, and regional regulatory cluster informed the analytical framework over the projection horizon. CAGRs derived from replacement cycle analysis in conservatory infrastructure and penetration modeling in home studio segments. Forecast inputs included post-pandemic enrollment stabilization trajectories and evolving FSC-equivalent certification adoption rates in Chinese export manufacturing.
Material uncertainties — hardwood input cost volatility, REACH compliance timeline compression, and pneumatic mechanism supply concentration — sit outside the modeled envelope. Forecasts reflect assumptions regarding institutional procurement specification continuity and regulatory disclosure threshold stability. Practitioners should keep alternative scenarios live as ECHA substitution mandates and MIIT timber directives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
UK Sustainable Home Furniture Market
Furniture
UAE Home Furniture Market
Furniture
Canada Secondary Wood Products Market
Furniture
United Kingdom Kitchen Furniture Market
Furniture
North America RTA Furniture Market
Furniture
School Furniture Market
Furniture
Pedicure Chair Market
Furniture
Europe Bamboo Furniture Market
Furniture
France Furniture Market
Furniture
North America School Furniture Market
Furniture
India Upholstered Furniture Market
Furniture
Sanded Plywood Market
Furniture
Italy Furniture Retail Market
Furniture
US Secondary Wood Products Market
Furniture
North America High-End Furniture Market
Furniture
Mexico Home Furniture Market