
 Global Video Surveillance Systems Market | 2026-2036
Global Video Surveillance Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Video Surveillance Systems Market Foresight
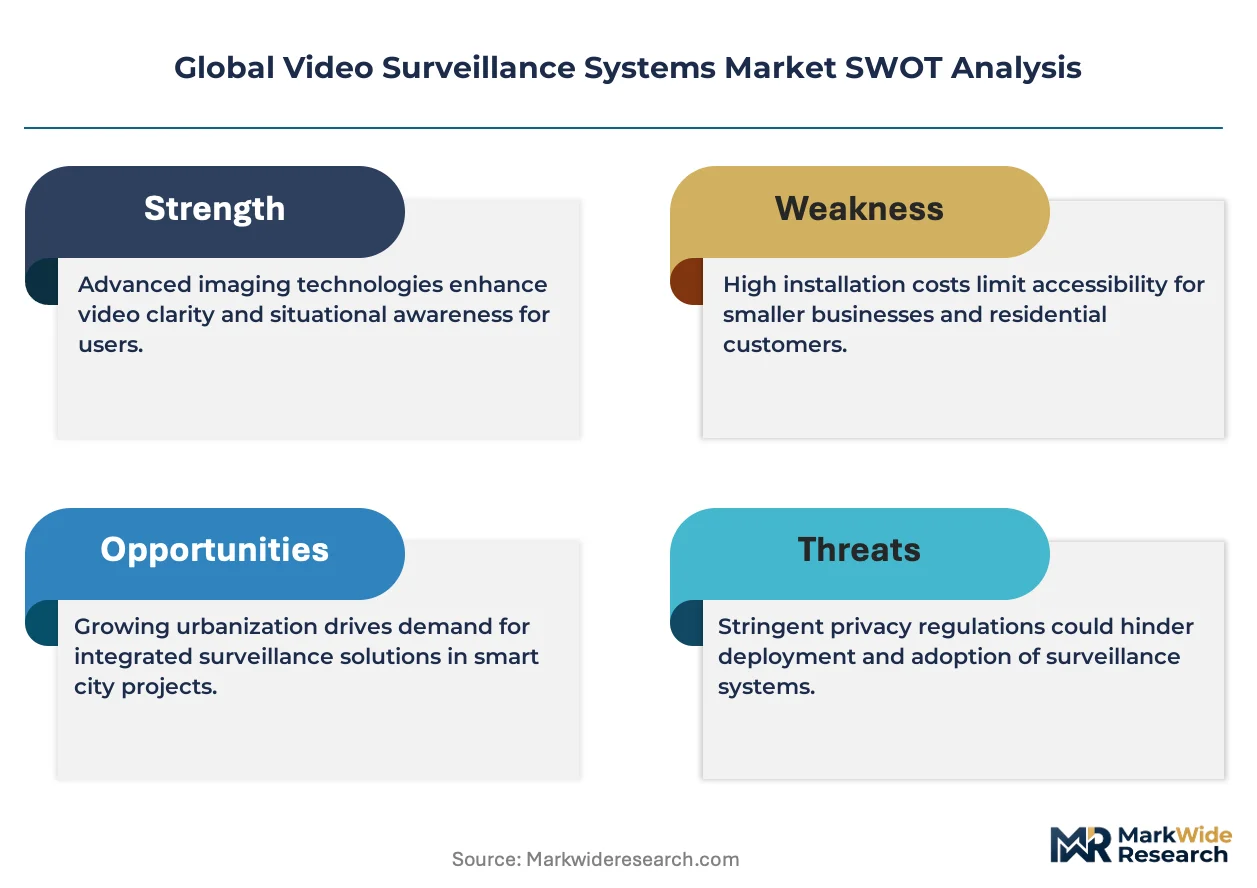
Resolution-tier migration from 1080p to 4K and 8K imaging is unwinding legacy infrastructure refresh cycles across enterprise and municipal buyers. Hangzhou Hikvision Digital Technology leverages integrated sensor-to-cloud architectures that compress deployment timelines for large-scale safe-city projects. Axis Communications AB anchors premium network camera segments through open-platform software ecosystems that reduce vendor lock-in. Bosch Security Systems differentiates on cybersecurity-hardened firmware that meets IEC 62443 industrial security standards.
Video surveillance systems encompass camera hardware, video management software, storage infrastructure, and analytics platforms engineered to capture, transmit, and analyze visual data for security and operational intelligence; modern IP cameras integrate CMOS sensors with H.265 compression to reduce bandwidth loads while maintaining forensic-grade image fidelity for incident reconstruction. IP cameras dominate hardware value pools as analog installations phase out across developed economies. Artificial intelligence and video analytics represent the fastest-expanding technology layers, with edge-computing deployments shifting processing from centralized servers to camera-local chipsets that enable real-time anomaly detection without cloud latency. Cloud-based architectures are maturing in mid-market commercial buildings where subscription models replace capital-intensive on-premise storage.
FCC equipment authorization rules govern wireless transmission modules in US-deployed systems, while EU GDPR and the EU AI Act impose strict limits on biometric data retention and automated identification in public spaces. China's GB/T 28181 standard mandates interoperability protocols for network video devices deployed in government projects. India's BIS certification requirements for electronic safety equipment create compliance gates for imported camera hardware. Stakeholders must monitor diverging data-sovereignty regimes when architecting multi-country deployment strategies.
Market Dynamics
Resolution-tier migration from 1080p to 4K and 8K imaging is forcing infrastructure refresh cycles across enterprise and municipal buyers, compressing replacement timelines from seven years to three-to-four-year cycles as forensic-grade evidence standards tighten.
Growth Catalysts
- Smart city infrastructure mandates:Government agencies in China, India, and Brazil are expanding camera deployments in urban centers as part of integrated public safety programs.
- EU AI Act compliance requirements:Biometric data retention limits and automated identification restrictions are accelerating demand for privacy-preserving edge analytics architectures in European deployments.
- Edge-computing chipset maturation:Camera-local processing capabilities enable real-time anomaly detection without cloud latency, reducing bandwidth costs for large-scale installations.
Market Restraints
- CMOS sensor supply concentration:Taiwan and South Korea fabs control critical semiconductor inputs, exposing hardware manufacturers to geopolitical disruption risks.
- GDPR biometric data friction:Strict retention limits and purpose-limitation requirements increase compliance costs for facial recognition deployments across European public spaces.
- Cloud storage subscription fatigue:Mid-market commercial buyers face escalating operational expenditures as on-premise capital expenditure models phase out.
Strategic Opportunities
- Underpenetrated Indian municipal markets:BIS certification requirements create compliance gates that favor early entrants establishing local testing partnerships.
- Healthcare facility safety mandates:Patient monitoring and elder care applications are expanding video analytics beyond traditional security into operational intelligence.
- 5G private network convergence:Ultra-reliable low-latency communication enables wireless camera deployments in mining, ports, and logistics yards previously unreachable with fiber.
Industry Challenges
- Cybersecurity firmware expertise scarcity:IEC 62443 industrial security standard compliance requires embedded systems engineers with scarce cross-domain skills in video and network hardening.
- Legacy analog-to-IP integration complexity:Hybrid environments demand middleware platforms that bridge coaxial infrastructure with modern VMS architectures without full rip-and-replace.
- Multi-jurisdiction data sovereignty navigation:Divergent retention rules across China, EU, and US deployments force redundant system architectures or geographically siloed cloud instances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Video Surveillance Systems Market |
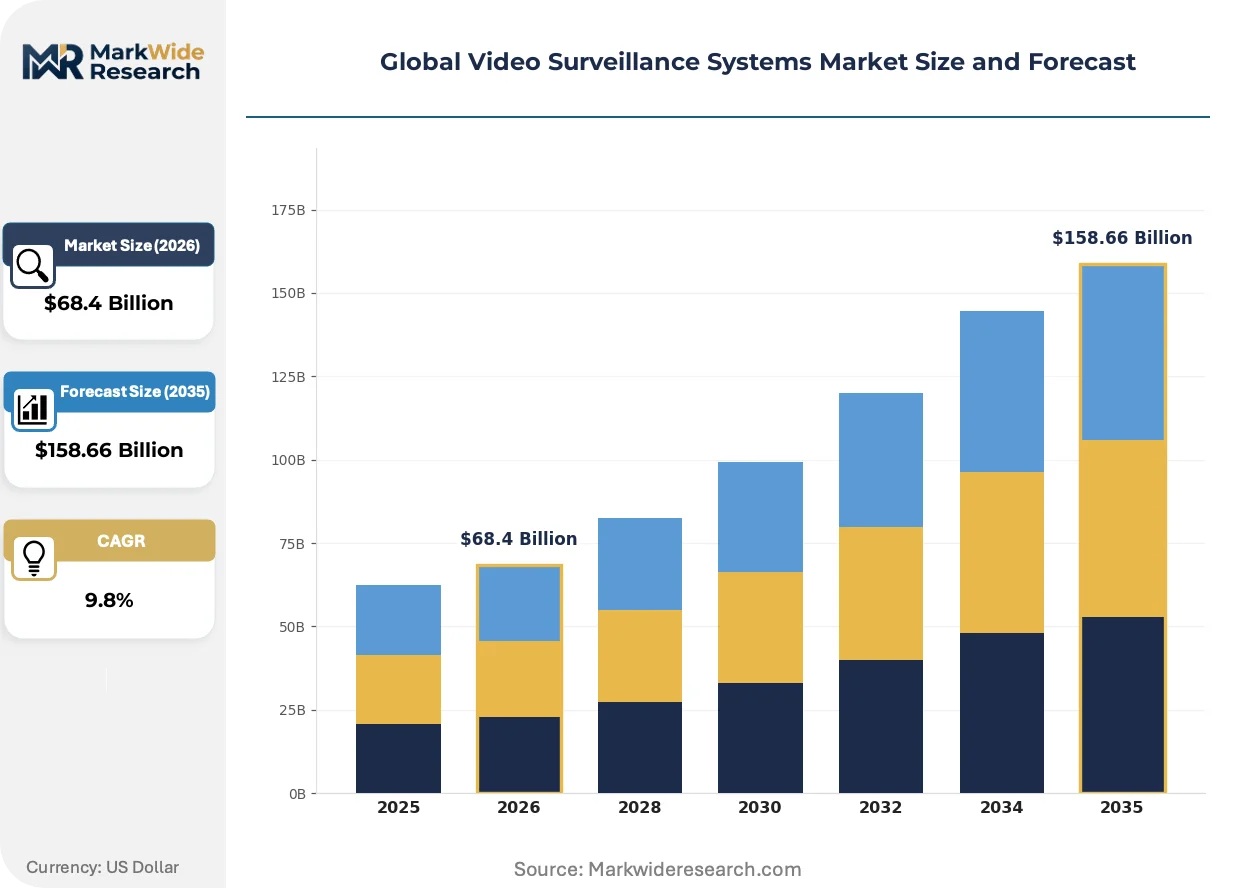
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $158.66 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IP Cameras, Analog Cameras, Thermal Cameras, PTZ Cameras, Network Video Recorders Technology: Artificial Intelligence, Video Analytics, Cloud-Based, Edge Computing, Wireless Transmission Application: Public Safety, Transportation, Commercial Buildings, Critical Infrastructure, Event Management End User: Government Agencies, Educational Institutions, Retail Chains, Manufacturing Plants, Hospitality Operators |
| Companies Covered | Hangzhou Hikvision Digital Technology Co., Ltd, Zhejiang Dahua Technology Co., Ltd, Axis Communications AB, Bosch Security Systems, Hanwha Vision Co., Ltd., Honeywell International Inc., Motorola Solutions, Inc., Teledyne FLIR LLC, Genetec Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Video Surveillance Systems Market Shifts & Advancements
Video surveillance technology is fragmenting across multiple architectural pathways simultaneously—edge, cloud, and hybrid—each optimized for distinct latency, cost, and compliance profiles rather than converging on a single dominant design.
Edge AI inference is fragmenting hardware procurement patterns as system-on-chip designs from Qualcomm and Ambarella displace general-purpose server GPUs for real-time video analytics. Large-scale safe-city operators in China and the UAE are deploying ten-thousand-camera networks with localized processing nodes that compress incident response from minutes to seconds. This architectural shift is fragmenting vendor ecosystems into specialized edge-hardware suppliers distinct from traditional camera manufacturers.
The EU AI Act's prohibition on real-time biometric identification in publicly accessible spaces is forcing European deployments toward behavioral analytics that infer threats from movement patterns rather than facial recognition. Hardware vendors are redesigning firmware to disable prohibited functions by default, with activation requiring documented lawful basis under GDPR. Municipal buyers in Germany and France are prioritizing open-platform VMS architectures that allow rapid reconfiguration as regulatory interpretations evolve.
Subscription-based video-surveillance-as-a-service is displacing capital-intensive ownership models among mid-market commercial property managers in the United States and United Kingdom. Channel partners are bundling hardware, installation, cloud storage, and remote monitoring into per-camera monthly fees that convert fixed costs to operational expenditures. This restructuring is most visible in multi-tenant office buildings and retail strip centers where property managers lack internal IT security expertise.
Global Video Surveillance Systems Market Segmentation
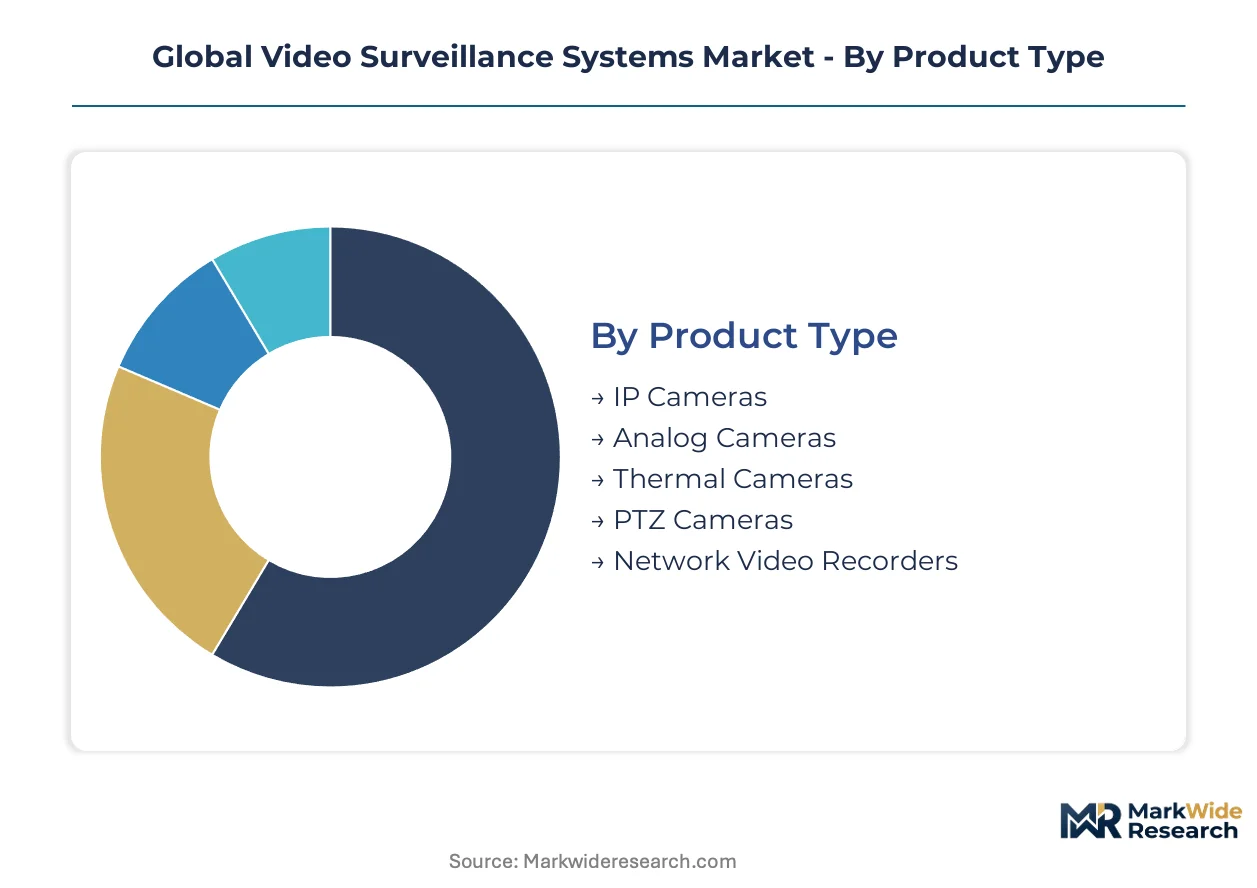
Segmentation in video surveillance systems determines procurement pathways, with enterprise buyers favoring integrated platforms while municipal purchasers prioritize interoperability certifications. Channel strategy diverges sharply across hardware, software, and service layers.
Product Type:
IP cameras flow through systems integrators and direct enterprise sales, while analog and thermal variants concentrate in retrofit specialists and defense contractors respectively.
- IP Cameras:CMOS sensors with H.265 compression reduce bandwidth loads while maintaining forensic-grade image fidelity. Demand concentrates in Chinese safe-city projects and US commercial buildings, driven by infrastructure refresh cycles compressing from seven years to three-to-four years.
- Analog Cameras:Coaxial-based legacy infrastructure persists in cost-constrained emerging markets and hybrid deployment scenarios. Educational institutions in India and Brazil retain analog systems where full IP migration exceeds capital budgets.
- Thermal Cameras:Uncooled microbolometer arrays detect heat signatures for perimeter security in critical infrastructure.
- PTZ Cameras:Pan-tilt-zoom mechanisms enable operator-controlled tracking in transportation hubs and event venues.
- Network Video Recorders:On-premise storage appliances bridge local retention with cloud archival for compliance-heavy industries.
By volume, IP cameras lead. By growth pace, thermal cameras are climbing the fastest.
Technology:
Cost tiers separate these segments, with AI and edge computing commanding premium pricing against commoditized wireless transmission modules.
- Artificial Intelligence:Deep learning models enable facial recognition, behavior prediction, and automated alert generation. Government agencies in the UAE and Singapore deploy AI-enabled analytics for real-time threat detection in dense urban environments.
- Video Analytics:Rules-based and machine-vision algorithms process motion detection, object classification, and crowd density estimation. Retail chains in the United Kingdom and Germany adopt video analytics for loss prevention and customer flow optimization.
- Cloud-Based:Subscription storage and remote management replace capital-intensive on-premise infrastructure.
- Edge Computing:Camera-local chipsets from Qualcomm and Ambarella displace server-side processing for latency-sensitive applications.
- Wireless Transmission:Wi-Fi and cellular modules enable rapid deployment in mining, agriculture, and temporary event infrastructure.
By installed base, wireless transmission leads. By margin expansion, edge computing is gaining share fastest.
Application:
Customer type shapes these segments, with public safety and critical infrastructure demanding hardened cybersecurity while commercial buildings prioritize cost efficiency.
- Public Safety:Municipal camera networks integrate with emergency dispatch and forensic evidence management systems. Smart city investments in Hangzhou, Dubai, and São Paulo anchor demand for interoperable command-and-control platforms.
- Transportation:Airports, seaports, and rail networks require continuous monitoring with specialized environmental hardening. Indian Railways and German Autobahn operators deploy video surveillance for incident reconstruction and traffic flow management.
- Commercial Buildings:Multi-tenant offices and retail centers adopt video-surveillance-as-a-service models.
- Critical Infrastructure:Power plants, water treatment facilities, and telecommunications sites mandate IEC 62443-compliant cybersecurity firmware.
- Event Management:Temporary deployments for sports venues, concerts, and political gatherings demand rapid-install wireless systems.
By deployment scale, public safety leads. By contract value, critical infrastructure shows the steepest expansion trajectory.
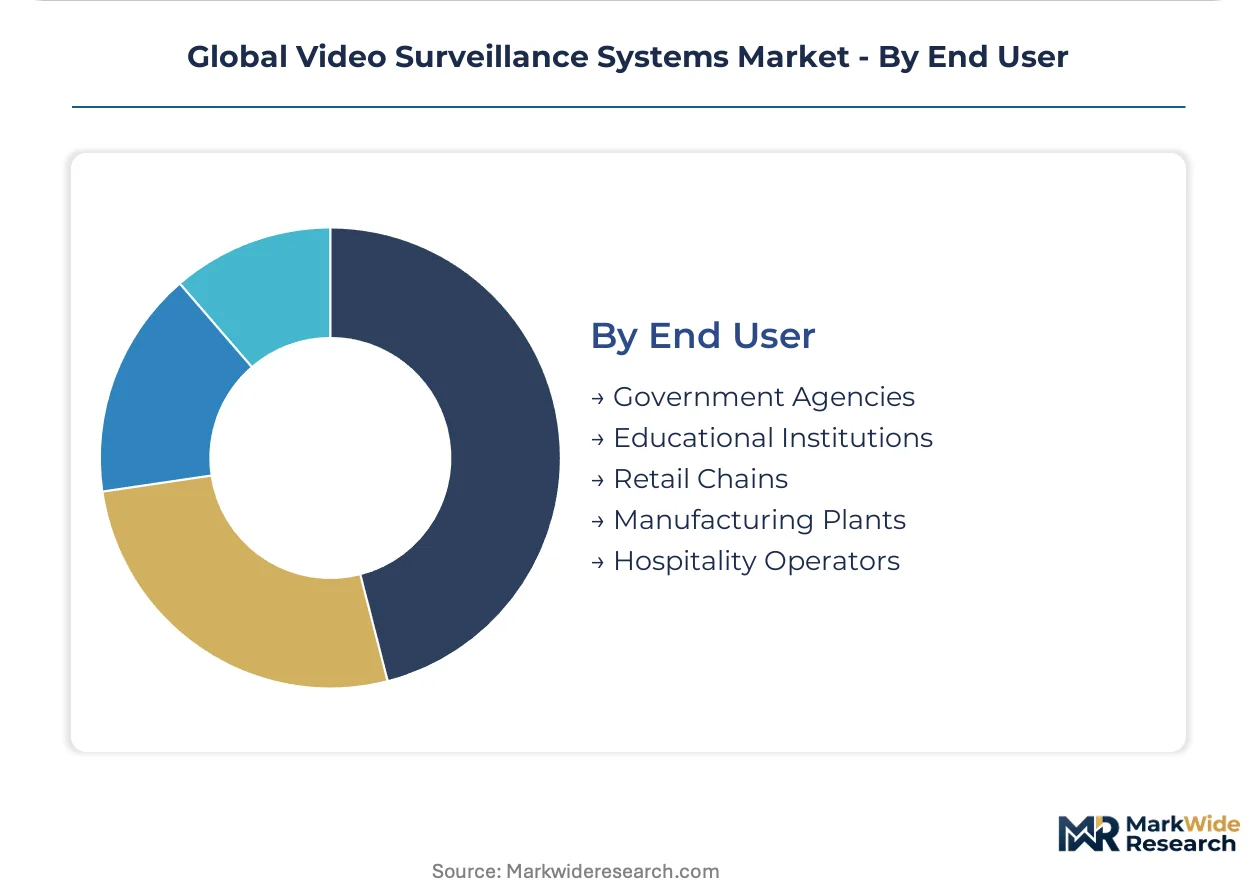
End User:
Supply concentration varies across these segments, with government agencies consolidating procurement through framework agreements while retail chains fragment orders across thousands of locations.
- Government Agencies:National and municipal buyers mandate GB/T 28181 or ONVIF interoperability standards for multi-vendor compatibility. China's Ministry of Public Security and India's Ministry of Home Affairs drive volume through centralized safe-city tenders.
- Educational Institutions:K-12 schools and universities prioritize campus safety with budget-constrained hybrid analog-IP architectures. US school districts and UK universities balance security mandates against limited IT staffing.
- Retail Chains:Loss prevention and operational analytics drive camera density in stores and warehouses.
- Manufacturing Plants:Process monitoring, safety compliance, and quality control extend video surveillance beyond security into operational intelligence.
- Hospitality Operators:Hotels and resorts balance guest privacy expectations with liability protection and staff safety requirements.
By unit volume, retail chains lead. By technology sophistication, government agencies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in video surveillance hardware tilt toward net exporters in East Asia and net importers across Europe and North America. Component trade flows concentrate CMOS sensors and edge-computing chipsets through Taiwan and South Korea fabs, while finished camera systems ship from Chinese manufacturing clusters to municipal buyers worldwide.
China
Domestic safe-city investments and Belt and Road infrastructure exports drive demand for integrated sensor-to-cloud architectures. GB/T 28181 interoperability standards mandate protocol compliance for government tenders. Hangzhou anchors the Yangtze River Delta cluster where Hikvision and Dahua coordinate massive production volumes for Asia-Pacific municipal networks.
United States
Commercial building retrofits and critical infrastructure hardening sustain procurement of cybersecurity-compliant systems. FCC equipment authorization rules govern wireless transmission modules in federally funded deployments. Texas and California data centers host cloud-based video-surveillance-as-a-service platforms serving mid-market property managers.
Germany
Industrial facility automation and railway safety upgrades generate demand for IEC 62443-certified firmware. GDPR biometric retention limits and EU AI Act restrictions reshape procurement toward privacy-preserving edge analytics. Bavaria's manufacturing corridor concentrates system integrators serving automotive and chemical plant security.
India
Smart city missions and railway modernization programs expand camera deployments across tier-1 and tier-2 urban centers. BIS certification requirements for electronic safety equipment create compliance gates favoring local testing partnerships. Maharashtra's Mumbai-Pune industrial belt hosts assembly operations for imported CMOS modules.
United Arab Emirates
Mega-event security preparations and port automation projects sustain premium-tier procurement of thermal and PTZ systems. MOHAP and local data sovereignty frameworks require in-country storage for government surveillance data. Dubai's logistics free zones concentrate regional distribution hubs serving Saudi and Egyptian buyers.
Global Video Surveillance Systems Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and customer segment coverage. The market exhibits tiered concentration where scale-driven hardware manufacturers coexist with cybersecurity-focused system integrators and subscription-based service platforms. Three archetypes dominate: integrated sensor-to-cloud providers, open-platform software specialists, and firmware-hardened security vendors. M&A activity concentrates on analytics software acquisitions, while geographic expansion through local certification partnerships secures municipal framework agreements.
Within the integrated hardware tier, Hangzhou Hikvision Digital Technology Co., Ltd and Zhejiang Dahua Technology Co., Ltd represent Chinese scale-driven manufacturers serving domestic safe-city and export markets. Axis Communications AB occupies a position among open-platform specialists reducing vendor lock-in through software ecosystem architectures. Bosch Security Systems exemplifies the cybersecurity-hardened archetype with industrial security standard compliance positioning for European critical infrastructure buyers.
| Leading Market Players |
|---|
| Hangzhou Hikvision Digital Technology Co., Ltd |
| Zhejiang Dahua Technology Co., Ltd |
| Axis Communications AB |
| Bosch Security Systems |
| Hanwha Vision Co., Ltd. |
| Honeywell International Inc. |
| Motorola Solutions, Inc. |
| Teledyne FLIR LLC |
| Genetec Inc. |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day CMOS sensor lead times concentrate pricing power with Taiwan and South Korea foundries, while municipal buyers in China and India face compressed procurement windows as safe-city deployment schedules accelerate. This inventory tightness feeds into tiered hardware margins where cybersecurity-certified firmware commands substantial premiums over commodity IP camera modules.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with IEC 62443 certification and edge-AI chipset integration serving as primary price differentiation drivers. Pricing pressure stems from subscription-based video-surveillance-as-a-service models displacing capital ownership among mid-market commercial property managers in the United States and United Kingdom. Government agencies in China and the UAE demonstrate lowest price sensitivity due to framework procurement mandates, while educational institutions in India and Brazil face acute budget constraints.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for CMOS image sensors and edge-computing chipsets, while China concentrates final camera assembly and system integration. The supply chain draws from specialized semiconductor inputs including Sony and OmniVision sensor dies, Ambarella and Qualcomm system-on-chip designs, and precision optical lens assemblies from Japanese and German manufacturers. Single-source vulnerability around advanced node fabrication exposes hardware vendors to geopolitical disruption risks. Distribution runs through systems integrators serving enterprise and municipal verticals, with direct OEM relationships dominating large-scale safe-city tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware cybersecurity expertise scarcity defines competitive moats in this market, with embedded systems engineers possessing cross-domain video and network hardening skills commanding decisive positioning advantages across European critical infrastructure bids.
For Market Incumbents: Fortify IEC 62443 certification portfolios and deepen backward integration into edge-computing chipsets to defend against Ambarella and Qualcomm displacing general-purpose server GPUs. Incumbents should prioritize captive supply of camera-local processing modules and establish redundant CMOS sensor sourcing partnerships beyond Taiwan and South Korea fabs to mitigate geopolitical exposure. For New Entrants and Emerging Players: BIS certification fast-tracks through Maharashtra testing partnerships offer entry gates into Indian smart city missions and railway modernization programs. New entrants should target tier-2 municipal markets in India and Brazil where incumbent presence remains fragmented, deploying channel partnerships with local systems integrators rather than direct enterprise sales. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergent data-sovereignty regimes across China, EU, and US deployments force geographically siloed cloud architectures that favor specialized regional platform providers. Acquisition targets should display open-platform VMS software ecosystems and established GDPR compliance workflows. The signal to watch is EU AI Act enforcement intensity around real-time biometric identification prohibitions, which would accelerate demand for behavioral analytics alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chipset Integration | Camera-local processing from Qualcomm and Ambarella reduces cloud latency for municipal safe-city networks. |
| GDPR-Compliant Firmware Redesign | Hardware vendors disabling prohibited biometric functions by default meet EU AI Act requirements for German and French deployments. |
| Cloud-Based Subscription Models | Per-camera monthly fees convert fixed costs to operational expenditures for UK and US commercial property managers. |
| 5G Private Network Convergence | Ultra-reliable low-latency communication enables wireless deployments in Australian mining and UAE port logistics. |
| Healthcare Facility Safety Expansion | Patient monitoring and elder care applications extend video analytics beyond security into operational intelligence for hospital systems. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with municipal procurement officers, systems integrators, cybersecurity firmware engineers, and cloud platform architects; and secondary validation through FCC equipment authorization filings, EU GDPR enforcement notices, BIS certification registries, and GB/T 28181 interoperability documentation. Bottom-up camera deployment tallies across China, India, Germany, and the United Arab Emirates were triangulated against top-down safe-city budget allocations from national ministries of public security.
Across the projection horizon, the analytical framework modeled segmentation dimensions including resolution tier, deployment architecture, application vertical, and regional regulatory cluster. CAGRs were derived from infrastructure refresh cycle compression observations and edge-computing adoption curves. Forecast inputs incorporated CMOS sensor supply constraints, EU AI Act implementation timelines, and 5G private network rollout schedules for industrial verticals.
Underlying assumptions cover sustained government smart city investment commitments and stable semiconductor foundry capacity, with deviation risk concentrated in geopolitical export restrictions and GDPR enforcement intensity variations. Recalibration cycles align with material shifts in CMOS sensor lead times, EU AI Act regulatory interpretations, and municipal procurement framework renegotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
Latin America Surveillance Camera Market
Video Surveillance Systems
Homeland Security Surveillance Camera Market
Video Surveillance Systems
Night Vision (IR) Surveillance Cameras Market
Video Surveillance Systems
Mini Security Camera Market
Video Surveillance Systems
3D Surveillance Software Market
Video Surveillance Systems
United Kingdom Surveillance IP Camera Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
Global Body Worn Cameras Market
Video Surveillance Systems
Mexico Video Surveillance Market
Video Surveillance Systems
Mexico Surveillance Analog Camera Market
Video Surveillance Systems
Canada Surveillance IP Camera Market
Video Surveillance Systems
India Surveillance IP Cameras Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
Asia-Pacific Surveillance Storage Market
Video Surveillance Systems
Smart Security Camera Market