
 United Kingdom Surveillance IP Camera Market | 2026-2036
United Kingdom Surveillance IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Surveillance IP Camera Market Insights
Edge-based AI analytics is reconfiguring how surveillance IP cameras process video at the device level rather than transmitting raw feeds to central servers. Hikvision leverages its vertically integrated sensor-to-software stack to dominate price-competitive municipal tenders across English local authorities. Axis Communications differentiates through open-architecture platforms that integrate with third-party video management systems favoured by UK enterprise buyers. Bosch Security Systems anchors its position in premium critical infrastructure segments where cybersecurity certification determines procurement eligibility.
A surveillance IP camera is a network-connected digital video capture device that transmits compressed H.265 or H.264 streams over Ethernet or wireless protocols, typically incorporating Power-over-Ethernet for simplified cabling and ONVIF interoperability for multi-vendor system integration. Its primary commercial purpose is to enable real-time monitoring, forensic review, and automated event detection for security operations across physical premises. Dome cameras lead volume in UK retail deployments where discreet aesthetics and vandal-resistant housings address storefront requirements, while thermal cameras represent the fastest-growing product category as port authorities and energy facilities adopt perimeter detection without visible-light dependency. The government end-user segment commands the highest project values through national security frameworks, though residential demand is accelerating fastest driven by subscription-based cloud storage models.
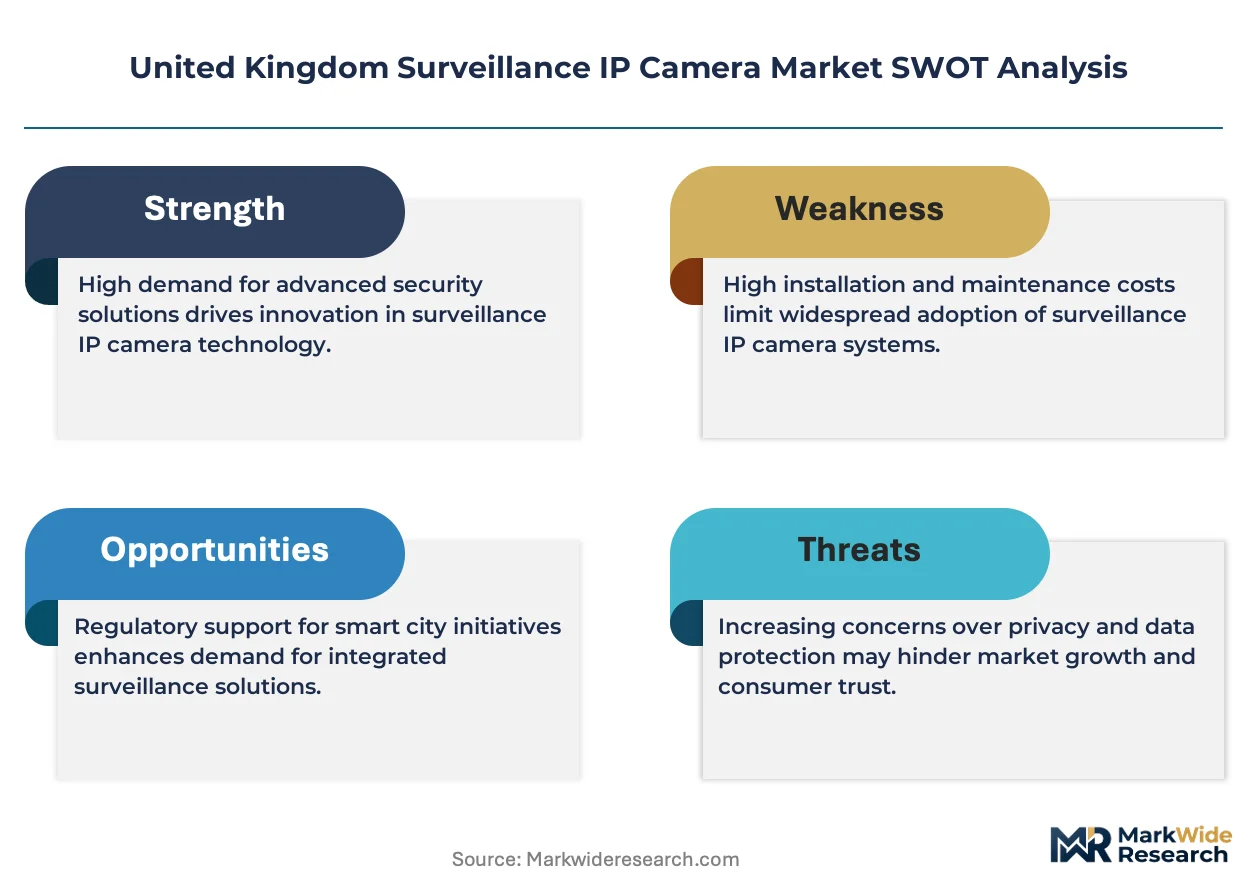
The UK Surveillance Camera Commissioner enforces the Surveillance Camera Code of Practice under the Protection of Freedoms Act, mandating privacy impact assessments and data retention limits that shape product feature roadmaps for vendors serving public sector buyers. BSI Kitemark certification for cybersecurity resilience is becoming a de facto gate for NHS trusts and educational institutions evaluating procurement shortlists. Stakeholders must monitor how the UK Information Commissioner's Office interprets biometric data processing through automated facial recognition, as enforcement actions against non-compliant deployments could redirect investment toward privacy-preserving analytics architectures.
Market Dynamics
Edge AI inference at the camera level is compressing bandwidth requirements and forcing vendors to redesign silicon architectures for Greater London's smart city deployments.
Growth Catalysts
- Transport Network Modernisation:British rail operators are mandating onboard IP video systems for passenger safety compliance across intercity routes.
- BSI Kitemark Certification:NHS trusts now require cybersecurity resilience marks for surveillance procurement, expanding addressable vendor pools.
- West Midlands Transport Corridor:Bus rapid transit expansion is driving platform surveillance upgrades across Birmingham and Coventry metropolitan zones.
Market Restraints
- Silicon Supply Concentration:Image sensor fabrication concentrates in East Asian foundries, exposing UK integrators to lead time volatility.
- GDPR-DPA Friction:The Information Commissioner's Office biometric enforcement creates compliance uncertainty for facial recognition deployments.
- Power-over-Ethernet Infrastructure:Legacy copper cabling in Victorian-era buildings limits 90W PoE++ upgrade feasibility without electrical rewiring.
Strategic Opportunities
- Privacy-Preserving Analytics:Edge-based differential privacy techniques enable public sector deployment without centralised biometric storage.
- Residential Cloud Subscriptions:Ring and Nest-style monthly storage models are penetrating suburban Manchester and Leeds housing stock.
- Critical Infrastructure Cyber Mandates:The National Cyber Security Centre's surveillance guidance creates premium certification tiers for nuclear and energy facilities.
Industry Challenges
- ONVIF Profile T Fragmentation:Advanced streaming protocol support varies across VMS platforms, complicating multi-vendor integration timelines.
- Edge AI Talent Scarcity:Embedded computer vision engineering skills concentrate in Cambridge and London, constraining regional system integrator expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Surveillance IP Camera Market |
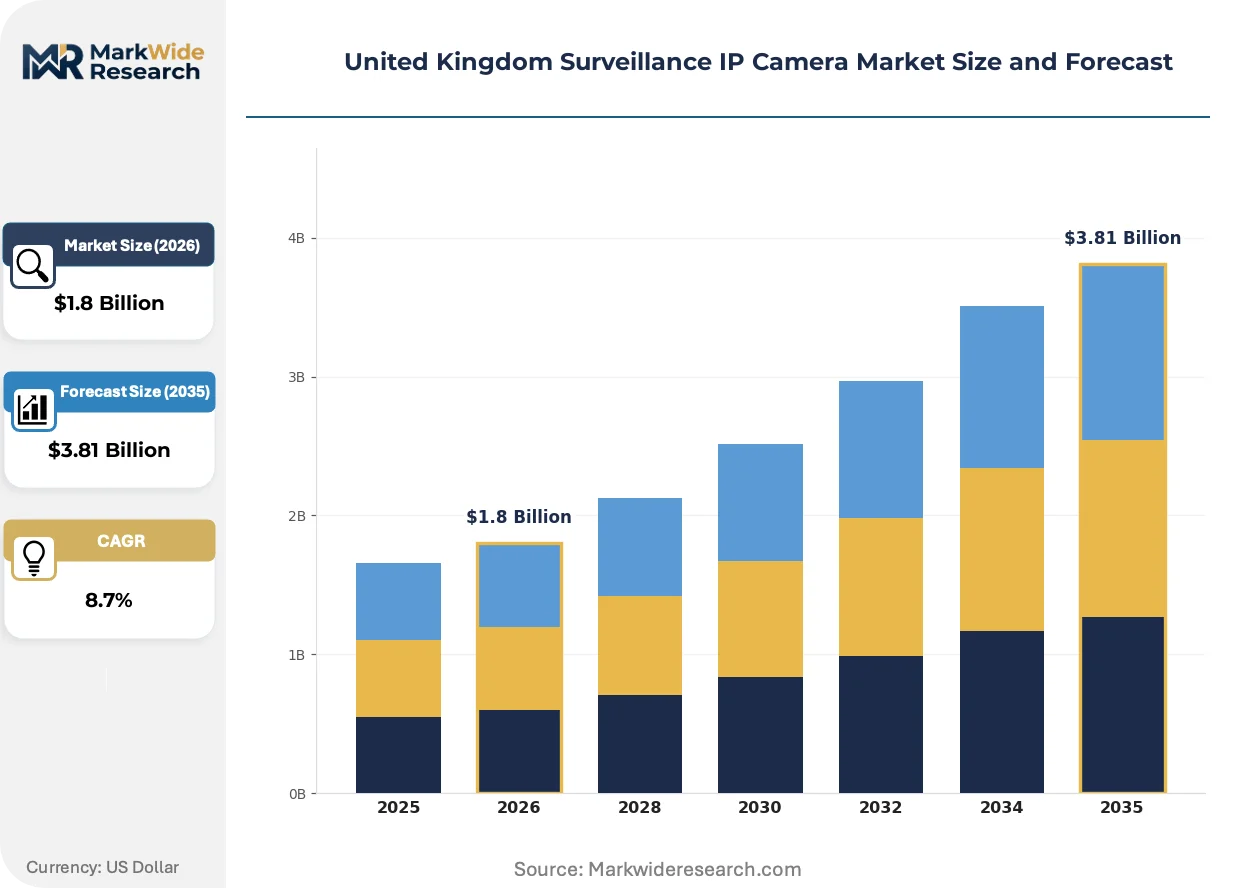
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Cameras, PTZ Cameras, Thermal Cameras, Dome Cameras Technology: Analog, IP, Wireless, PoE End User: Retail, Transportation, Government, Residential Installation: Indoor, Outdoor, Wall-Mounted, Ceiling-Mounted |
| Companies Covered | Hikvision, Axis Communications, Dahua Technology, Hanwha Vision, Bosch Security Systems, Motorola Solutions, Teledyne FLIR, Honeywell, IDIS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Surveillance IP Camera Market Trends and Innovations
Video analytics architectures are migrating processing loads from central servers to camera-edge silicon, compressing latency and reshaping vendor competitive vectors.
Multi-sensor fusion technology is hybridizing visible-light and thermal imaging streams into unified detection pipelines. Port authorities at Felixstowe and Grangemouth are deploying these systems for perimeter intrusion detection without auxiliary lighting infrastructure. The convergence is hybridizing procurement specifications, forcing single-sensor vendors to partner or exit maritime security tenders.
The Surveillance Camera Code of Practice under the Protection of Freedoms Act is tightening privacy impact assessment requirements for public space deployments. Local authorities in England and Wales must now publish deployment rationales and retention schedules before camera activation. Police and crime commissioners are redirecting capital toward transparent analytics architectures that satisfy Commissioner audit protocols.
Subscription-based cloud storage is displacing on-premise NVR ownership among SME retail operators. Dixons Carphone and independent security installers are unbundling hardware from recurring service fees, shifting margin capture toward multi-year contracts. This model concentrates fastest in Greater London convenience retail and quick-service restaurant chains seeking remote monitoring without dedicated IT staffing.
United Kingdom Surveillance IP Camera Market Segmentation
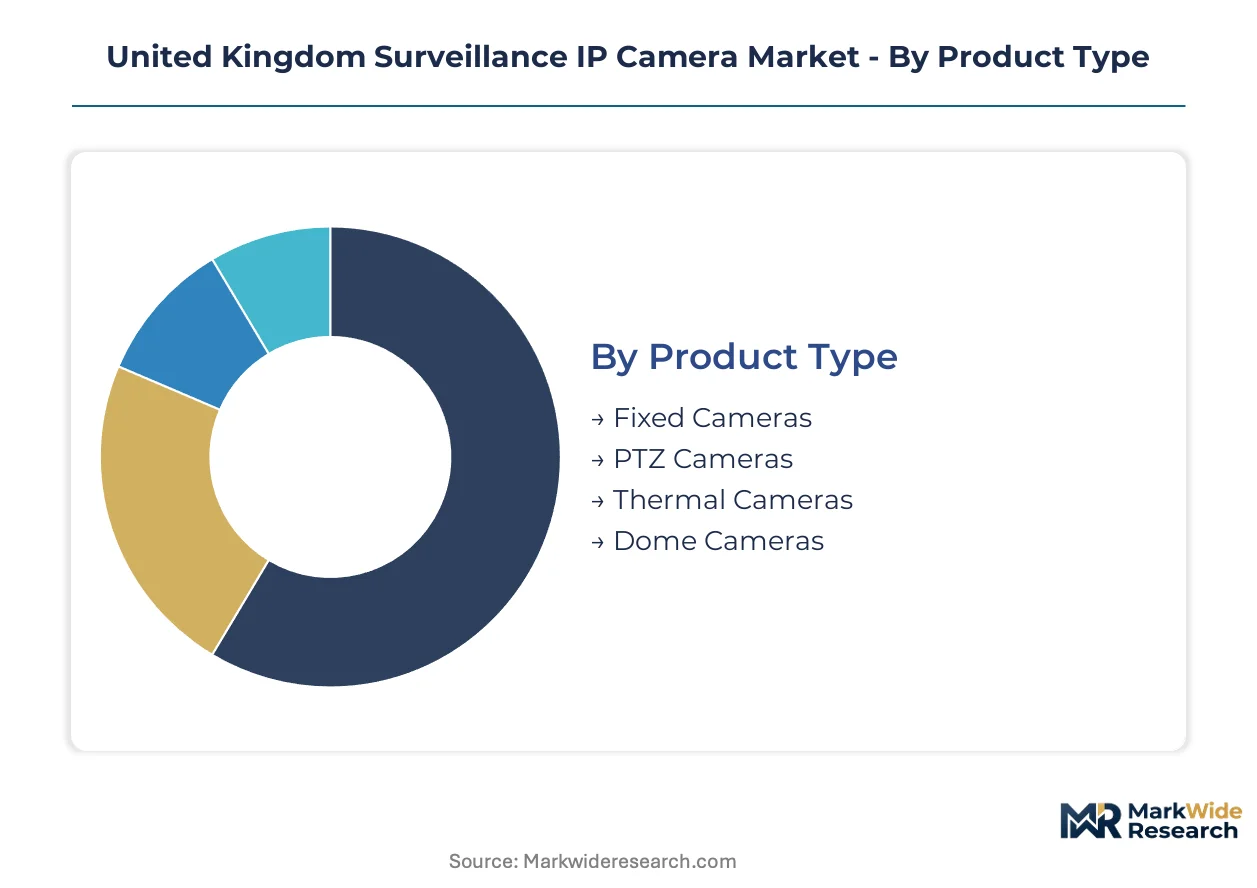
Segmentation in the United Kingdom Surveillance IP Camera Market reveals how procurement patterns diverge across technical specifications and deployment contexts. Understanding these divides helps vendors calibrate service models and pricing architectures to match distinct buyer workflows and compliance burdens.
Product Type:
After-sales-service intensity varies sharply across camera form factors, with dome and PTZ units demanding more frequent lens calibration and mechanical maintenance than fixed alternatives.
- Dome Cameras:Vandal-resistant housings with hemispherical enclosures conceal lens positioning from observers. Retail storefronts across Greater London and Birmingham metropolitan zones specify these units for discreet interior monitoring where aesthetics and tamper resistance outweigh pure resolution metrics.
- Thermal Cameras:Uncooled microbolometer sensors detect infrared radiation independent of visible illumination. Port authorities at Felixstowe and Grangemouth are accelerating thermal perimeter deployments for intrusion detection without auxiliary lighting infrastructure, driven by energy facility security mandates and maritime cargo protection requirements.
- Fixed Cameras:Stationary lens assemblies with fixed focal lengths dominate cost-sensitive municipal tendering where coverage breadth matters more than operator steerability.
- PTZ Cameras:Pan-tilt-zoom mechanisms enable remote operator control over field of view, commanding premium positioning in transport hubs requiring real-time incident response.
Dome cameras hold the largest share; momentum sits with thermal cameras.
Technology:
Technology selection determines infrastructure retrofit costs and cybersecurity exposure, with PoE and wireless architectures reshaping deployment economics in heritage building stock.
- IP:Network-addressable devices transmitting H.265 or H.264 streams over Ethernet infrastructure. NHS trusts and educational institutions mandate IP connectivity for centralized video management integration, constrained by BSI Kitemark cybersecurity certification requirements that filter non-compliant vendors from procurement shortlists.
- PoE:Power-over-Ethernet delivers electrical power and data through single cable runs. Victorian-era commercial buildings across Manchester and Leeds face upgrade feasibility constraints where legacy copper cabling cannot support 90W PoE++ standards without electrical rewiring.
- Wireless:Wi-Fi or cellular backhaul eliminates cabling runs in temporary deployments or heritage structures where fabric preservation restricts drilling.
- Analog:Coaxial-based legacy systems persist in budget-constrained small retail and residential retrofit scenarios where full IP migration is deferred.
IP connectivity dominates installed value; wireless is expanding most quickly in heritage-constrained deployments.
End User:
End-user category shapes procurement route-to-market, with government frameworks demanding extended warranty terms and audit documentation absent from residential channels.
- Government:National security frameworks and local authority deployments governed by the Surveillance Camera Commissioner's Code of Practice. Police and crime commissioners in England and Wales redirect capital toward transparent analytics architectures that satisfy mandatory privacy impact assessments and published retention schedules.
- Residential:Subscription-based cloud storage models are penetrating suburban Manchester and Leeds housing stock. Ring and Nest-style monthly service fees displace on-premise NVR ownership, shifting margin capture toward multi-year recurring contracts.
- Transportation:British rail operators mandate onboard IP video systems for passenger safety compliance across intercity routes, while West Midlands bus rapid transit expansion drives platform surveillance upgrades.
- Retail:SME convenience operators and quick-service restaurant chains seek remote monitoring without dedicated IT staffing, favoring bundled hardware-service packages.
Government commands the highest project values; residential demand is climbing the fastest.
Installation:
Installation topology determines environmental sealing ratings and mounting hardware specifications, with outdoor deployments carrying steepest total-cost-of-ownership premiums.
- Outdoor:Weather-sealed enclosures with IP66 or IP67 ratings resist moisture and particulate ingress. Critical infrastructure operators at nuclear and energy facilities reference National Cyber Security Centre guidance for hardened physical protection tiers.
- Indoor:Unsealed housings for climate-controlled environments dominate volume in retail and office deployments where vandal resistance requirements relax.
- Wall-Mounted:Bracket assemblies for vertical surfaces optimize sightlines in corridor and perimeter applications.
- Ceiling-Mounted:Recessed or surface-mounted fixtures for suspended tile systems predominate in commercial interior fit-outs.
Outdoor installations carry the steepest specification burden; ceiling-mounted configurations lead volume in commercial retrofit activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration across British transport operators, NHS trusts, and local authorities is pulling procurement toward compliance-heavy frameworks in England's metropolitan cores and devolved administrations.
Greater London
Transport for London mandates onboard IP video across bus and underground networks for passenger safety compliance. The Surveillance Camera Commissioner's Code of Practice requires published retention schedules before camera activation. Smart city infrastructure programmes in Camden and Westminster are deploying edge-AI analytics for real-time crowd monitoring.
West Midlands
Bus rapid transit expansion across Birmingham and Coventry is driving platform surveillance upgrades with thermal perimeter detection. The region's police and crime commissioner redirects capital toward transparent analytics architectures satisfying mandatory privacy impact assessments. Manufacturing facilities in Solihull are adopting BSI Kitemark-certified systems for cybersecurity resilience.
Scotland
Scottish Government transport agencies specify onboard IP systems for intercity rail routes under passenger safety frameworks. The Scottish Biometrics Commissioner imposes additional oversight layers on automated facial recognition deployments. Aberdeen's energy facilities reference National Cyber Security Centre guidance for hardened physical protection tiers.
Wales
Transport for Wales accelerates procurement of platform surveillance for valley lines modernization. Welsh local authorities must publish deployment rationales under the Surveillance Camera Code of Practice. Cardiff Bay commercial developments are specifying vandal-resistant dome cameras for retail and hospitality interiors.
North England
Leeds and Manchester housing stock is absorbing Ring-style cloud subscription models fastest among UK metropolitan areas. Northern Powerhouse rail integration programmes mandate interoperable IP connectivity across station networks. Liverpool port authorities deploy thermal cameras for maritime cargo protection without auxiliary lighting infrastructure.
United Kingdom Surveillance IP Camera Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Vertically integrated manufacturers with captive sensor production dominate municipal tendering through price-competitive positioning. Open-architecture platform vendors capture enterprise buyers prioritizing multi-vendor integration flexibility. Premium critical infrastructure specialists anchor cybersecurity-certified segments where procurement eligibility hinges on resilience certification. Consolidation pressure is driving strategic partnerships between single-sensor vendors and analytics software providers, while geographic expansion into devolved administrations accelerates among scale players.
Within the vertically integrated tier, Hikvision and Dahua Technology represent price-competitive positioning for English local authority tenders. Axis Communications exemplifies open-architecture differentiation favored by UK enterprise buyers requiring third-party video management system interoperability. Bosch Security Systems anchors the premium critical infrastructure segment where National Cyber Security Centre guidance determines procurement eligibility for nuclear and energy facilities.
| Leading Market Players |
|---|
| Hikvision |
| Axis Communications |
| Dahua Technology |
| Hanwha Vision |
| Bosch Security Systems |
| Motorola Solutions |
| Teledyne FLIR |
| Honeywell |
| IDIS |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on East Asian image sensor fabrication determines both the three-tier pricing structure across premium, standard, and economy levels and the elongated supply chain shape facing UK integrators. Procurement officers at English local authorities and NHS trusts navigate this concentration through cost-plus contracts with semiconductor indexation clauses that transfer commodity volatility risk.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate public sector procurement frameworks, insulating NHS trusts and transport operators from raw material swings. Price differentiation rests on BSI Kitemark cybersecurity certification grade and bundled after-sales service intensity. Cost compression in the standard tier is intensifying because municipal tendering favors price-competitive bids from vertically integrated manufacturers. SME retail operators show highest price sensitivity, while nuclear energy facilities demonstrate lowest sensitivity due to cyber-resilience mandates.
Supply Chain Analysis
Export-control regimes limiting advanced semiconductor flows to Chinese manufacturers reshape procurement strategies for UK system integrators. Image sensor production concentrates in Taiwan, South Korea, and Japan, with UK assembly drawing from uncooled microbolometer arrays and edge-AI silicon. Single-source vulnerability runs through Taiwan Strait logistics chokepoints. Distribution runs through authorized distributor networks serving security installers and direct enterprise contracts for critical infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Surveillance IP Camera Market represents a high-growth disruption as edge-AI inference mandates and the Surveillance Camera Commissioner's tightening privacy protocols force architectural pivots across vendor roadmaps.
For Market Incumbents: Build certification moats around BSI Kitemark cybersecurity tiers and National Cyber Security Centre guidance compliance to lock out price-competitive challengers from NHS and energy facility tenders. Deepen backward integration into edge-AI silicon design to reduce dependency on East Asian foundry allocations. Channel control through exclusive distribution agreements with Manchester and Leeds security installers defends against direct-to-enterprise disintermediation. For New Entrants and Emerging Players: Scotland's energy corridor and Welsh valley lines transport modernization present underpenetration opportunities where incumbent presence remains thin. Target Aberdeen's offshore facility security segment with thermal-multisensor fusion bundles that bypass established vendor relationships. A hardware-as-a-service go-to-market angle with bundled cloud analytics penetrates suburban Leeds residential stock faster than capital-intensive NVR sales cycles. For Investors and Strategic Acquirers: The Surveillance Camera Commissioner's anticipated biometric enforcement actions reshape the acquisition landscape toward privacy-preserving analytics architectures. Five-to-ten-year viability favors targets with differential privacy IP and edge-based processing capabilities rather than centralized facial recognition dependencies. Acquisition target archetype: mid-scale computer vision software houses with Scottish or Welsh public sector reference contracts. Watch for Information Commissioner's Office enforcement patterns against non-compliant facial recognition deployments as the signal triggering accelerated consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| BSI Kitemark Certification Investment | Unlocks NHS trust and educational institution procurement shortlists under mandatory cybersecurity frameworks. |
| Edge-AI Silicon Partnership | Reduces bandwidth costs for Greater London smart city deployments while compressing latency. |
| Privacy-Preserving Analytics Development | Aligns product roadmaps with Surveillance Camera Commissioner audit protocols and ICO enforcement direction. |
| Scottish Energy Corridor Expansion | Captures Aberdeen offshore facility security spend referencing National Cyber Security Centre guidance tiers. |
| Residential Cloud Subscription Launch | Replicates Ring-style recurring revenue models across Manchester and Leeds housing stock penetration. |
Research Methodology
A standing panel of transport safety officers, NHS trust procurement managers, security system integrators, and local authority compliance leads provided ongoing calibration across the research window. Primary interviews with these stakeholders combined with secondary validation against Surveillance Camera Commissioner guidance documents, BSI certification registries, and National Cyber Security Centre surveillance advisories. Bottom-up installation volume estimates triangulated with top-down public sector capital expenditure tracking.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, technology architecture, end-user category, and installation topology. CAGRs derived from fitted growth curves applied to disclosed procurement frameworks and transport network modernization schedules. Edge-AI adoption curves and thermal camera penetration rates in port security applications served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in sterling exchange rates against East Asian currencies or semiconductor foundry utilization rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and transport infrastructure spend commitments. Material shifts in UK-EU data transfer regimes or Surveillance Camera Commissioner interpretive guidance would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Surveillance Systems
China Surveillance Analog Camera Market
Video Surveillance Systems
Security and Surveillance Storage Market
Video Surveillance Systems
Cellular Interception Market
Video Surveillance Systems
US Video Surveillance Market
Video Surveillance Systems
India Surveillance Camera Market
Video Surveillance Systems
France Surveillance Analog Camera Market
Video Surveillance Systems
Middle East and Africa Surveillance IP Cameras Market
Video Surveillance Systems
Global Trade Surveillance Systems Market
Video Surveillance Systems
Inspection Camera System Market
Video Surveillance Systems
Asia-Pacific Surveillance Analog Camera Market
Video Surveillance Systems
Germany Surveillance Analog Camera Market
Video Surveillance Systems
Coastal Surveillance Systems Market
Video Surveillance Systems
In-Vehicle Video Surveillance Market
Video Surveillance Systems
United States Surveillance Storage Market
Video Surveillance Systems
United Kingdom Surveillance Camera Market
Video Surveillance Systems
Crawler Camera System Market