
 Reprographic Paper Market | 2026-2036
Reprographic Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Reprographic Paper Market Analytics
Recycled pulp fiber is repositioning virgin pulp economics across reprographic paper supply chains. International Paper leverages its North American fiber network to sustain cost advantages in bond paper production. Stora Enso anchors its competitive stance through integrated Nordic forestry operations that control raw material quality from harvest to finished reel. UPM-Kymmene Corporation differentiates via specialized coating technologies for laser-compatible surfaces.
Reprographic paper denotes wood-pulp-based substrates engineered for high-speed digital duplication, typically calibrated to 75–90 grams per square meter basis weight with controlled moisture content between 4.5% and 5.5% to prevent jamming in laser and inkjet equipment. Its primary commercial purpose centers on producing sharp, consistent printed output for business documents, marketing collateral, and educational materials. Laser paper commands the largest volume share due to universal office printer compatibility, while specialty paper segments carry the widest margin pools through customized finishes for artistic applications and archival storage. Eco-friendly grade production is accelerating fastest as procurement policies at educational institutions and government offices mandate recycled content thresholds.
The US EPA administers recycled fiber content guidelines under Comprehensive Procurement Guidelines that shape institutional purchasing requirements for reprographic materials. The EU Ecolabel and Forest Stewardship Council chain-of-custody standards govern market access for European suppliers, with REACH compliance required for optical brightening chemistries used in premium grades. Japan's METI enforces JIS standards for paper dimensional stability that affect export eligibility. Stakeholders must monitor how tightening deforestation regulations in key pulp-source countries reshape long-term fiber security and certification costs.
Market Dynamics
Recycled fiber mandates from institutional buyers are compressing virgin pulp demand curves while forcing mills to reconfigure furnish recipes without sacrificing laser-print compatibility. The EU Green Deal's chain-of-custody requirements now filter through to municipal procurement offices, redirecting volume toward certified sources.
Growth Catalysts
- EU Green Deal certification mandates:Public sector procurement policies now require Forest Stewardship Council documentation, pulling volume toward mills with integrated forestry assets.
- Educational institutional purchasing:University system bulk contracts specify minimum recycled content thresholds, creating anchored demand for eco-grade reels.
- German commercial print clusters:Concentrated graphic arts hubs around Stuttgart and Hamburg sustain premium-grade consumption despite digital displacement elsewhere.
Market Restraints
- Pulp price volatility:Hardwood fiber costs swing with Brazilian eucalyptus harvest cycles, squeezing margin on standard-grade bond paper.
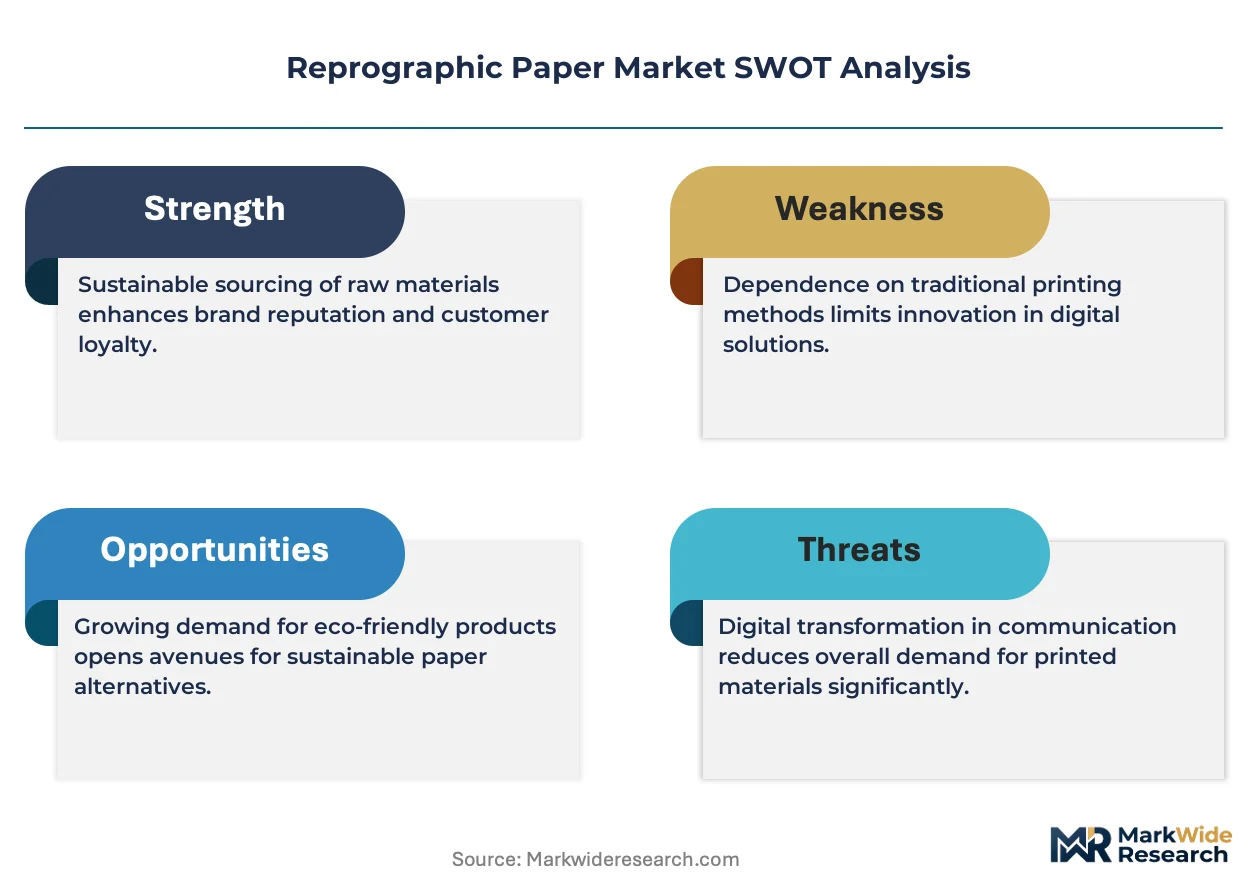
- Substitution by electronic document systems:Enterprise content management platforms eliminate physical archival copies, eroding base-load office consumption.
- REACH compliance friction:Optical brightening agent restrictions force reformulation of premium white grades, extending qualification timelines for European export.
Strategic Opportunities
- India educational publishing expansion:State textbook procurement programs create volume anchors for 70-80 gsm uncoated woodfree grades in vernacular print runs.
- Archival-grade specialty positioning:Museums and government record repositories require acid-free substrates with extended permanence ratings, commanding price premiums over commodity laser paper.
- Direct mill-to-institution contracting:Bypassing merchant distribution layers allows customized roll widths and just-in-time delivery schedules for large university systems.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for laser-compatible surface treatments concentrates among retiring specialists at Nordic integrated mills.
- Multi-certification audit burden:Simultaneous EU Ecolabel, FSC chain-of-custody, and national recycled content verification creates documentation overhead for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reprographic Paper Market |
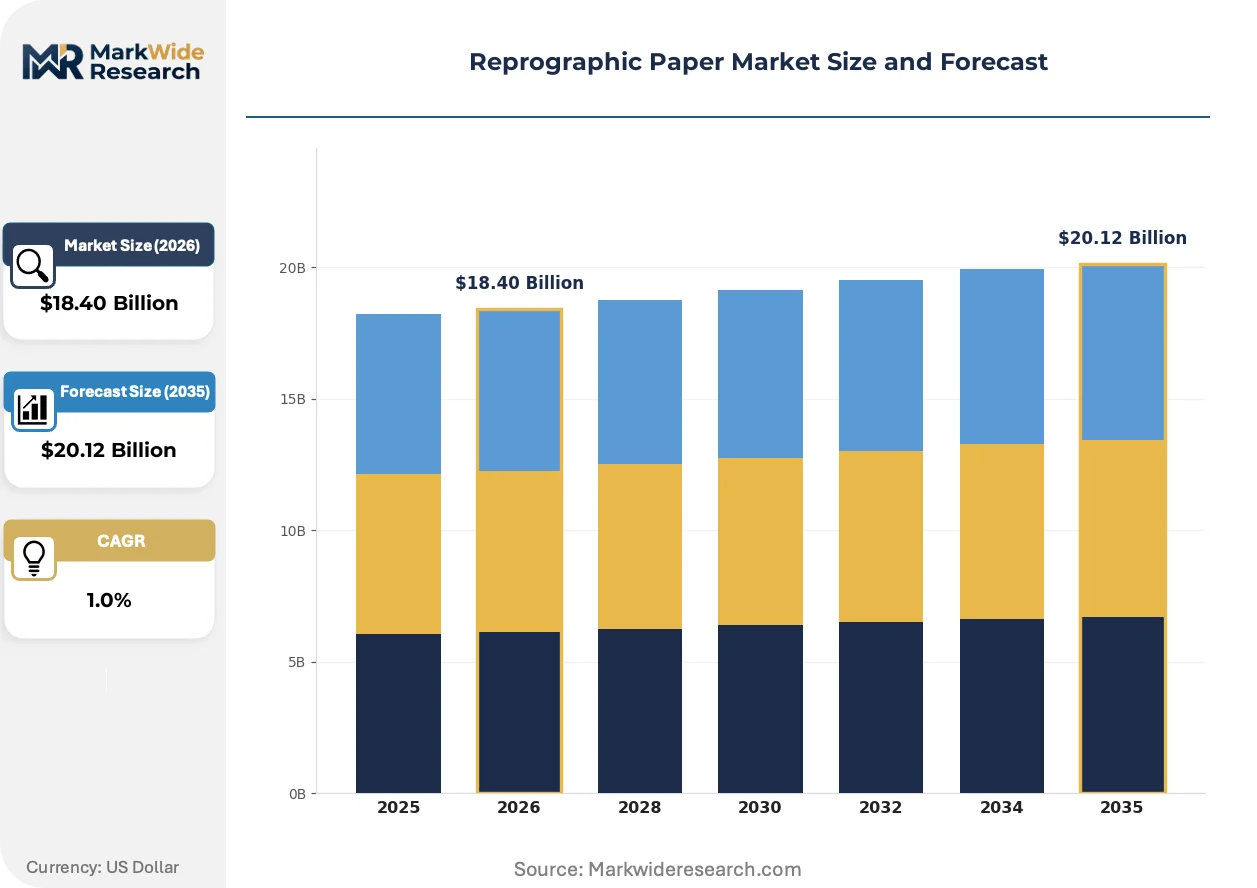
| Market Size in 2026 | $18.40 Billion |
| Market Size in 2035 | $20.12 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Paper, Laser Paper, Bond Paper, Specialty Paper End Use: Commercial Printing, Office Use, Educational Institutions, Artistic Applications Quality Grade: Standard Grade, Premium Grade, Eco-friendly Grade, Archive Quality Packaging Type: Reams, Sheets, Rolls, Pallets |
| Companies Covered | International Paper, WestRock, Stora Enso, UPM-Kymmene Corporation, Sappi, Oji Holdings Corporation, Nippon Paper Industries, Mondi Group, Domtar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reprographic Paper Market Evolving Landscape
Paper engineering is converging with digital printing physics as mills optimize substrates for toner adhesion and inkjet absorption rather than legacy offset compatibility. Surface chemistry and fiber furnish now determine competitive positioning more than basis weight alone.
Precision coating technology is modularizing production flexibility across reprographic paper lines. Mills serving hybrid print environments now apply micro-layered surface treatments that switch between laser toner receptivity and inkjet absorption without reel changes. Commercial printers in the Netherlands and Belgium are adopting these convertible stocks to reduce inventory SKUs. The technology is modularizing what were previously separate product categories into unified substrate platforms.
Japan's METI has tightened JIS standards for dimensional stability under humidity cycling, effective for export eligibility certification. European suppliers must now demonstrate sub-0.4% expansion rates across 20-80% relative humidity ranges to maintain access to Japanese commercial print houses. Specialty-grade producers with Nordic pulp sourcing are investing in extended conditioning tunnels to meet the specification, while commodity mills are ceding share in that geography.
Consolidated buying by multi-campus university systems is compressing supplier rosters and extending contract durations. Procurement offices in California and Texas now negotiate three-year framework agreements with single-source mill commitments, replacing the previous pattern of quarterly spot purchasing through paper merchants. This concentration is most visible in public higher education systems where state-level sustainability mandates align with volume leverage objectives.
Reprographic Paper Market Segmentation
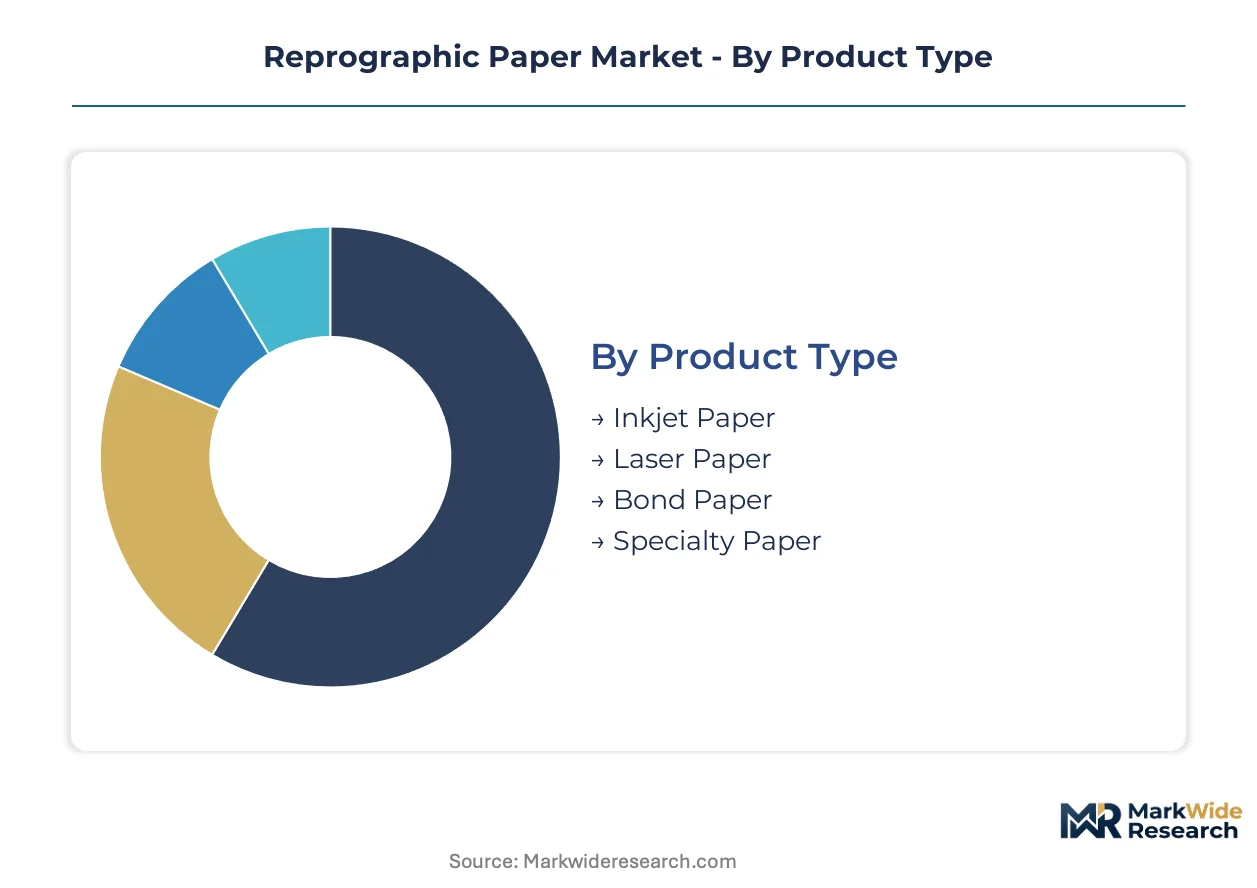
Reprographic paper supply chains calibrate manufacturing assets to distinct technical specifications across product categories. Segmentation reveals where capital concentrates and which specifications command procurement premiums.
Product Type:
Mills configure coating lines and fiber furnishes around dominant print technologies, with supply clustering where equipment compatibility drives repeat purchasing.
- Laser Paper:Calibrated to 75–90 gsm with controlled moisture content between 4.5% and 5.5% to prevent jamming in high-speed laser equipment. German commercial print clusters around Stuttgart and Hamburg sustain premium-grade consumption for corporate document production despite digital displacement elsewhere.
- Bond Paper:Wood-pulp-based substrate engineered for sharp, consistent output with higher cotton fiber content in premium variants. International Paper leverages its North American fiber network to sustain cost advantages in bond paper production for institutional contracts.
- Inkjet Paper:Absorbent surface chemistry optimized for aqueous ink penetration without feathering. Precision coating technology is modularizing production flexibility across hybrid print environments in the Netherlands and Belgium.
- Specialty Paper:Customized finishes for artistic applications and archival storage. UPM-Kymmene Corporation differentiates via specialized coating technologies for laser-compatible surfaces in this segment.
Laser paper absorbs the bulk of installed capacity; eco-friendly grade production is expanding most quickly as procurement policies mandate recycled content thresholds.
End Use:
Demand patterns diverge sharply between institutional buyers with multi-year frameworks and spot purchasers in fragmented commercial channels.
- Office Use:Steady consumption across developed economies drives base-load volumes. Consolidated buying by multi-campus university systems in California and Texas now negotiates three-year framework agreements with single-source mill commitments.
- Commercial Printing:Concentrated graphic arts hubs require just-in-time delivery schedules and customized roll widths. Direct mill-to-institution contracting is bypassing merchant distribution layers for large university systems.
- Educational Institutions:State textbook procurement programs in India create volume anchors for 70-80 gsm uncoated woodfree grades in vernacular print runs.
- Artistic Applications:Museums and government record repositories require acid-free substrates with extended permanence ratings.
Office use commands the largest volume share; educational institutional purchasing is climbing the fastest as recycled fiber mandates compress virgin pulp demand curves.
Quality Grade:
Certification requirements and performance specifications stratify pricing and procurement eligibility across institutional buyers.
- Eco-friendly Grade:Production is accelerating fastest as procurement policies at educational institutions and government offices mandate recycled content thresholds. The EU Ecolabel and Forest Stewardship Council chain-of-custody standards govern market access for European suppliers.
- Premium Grade:Optical brightening chemistries and specialized surface treatments command widest margin pools. REACH compliance requirements force reformulation timelines for European export.
- Standard Grade:Hardwood fiber cost volatility with Brazilian eucalyptus harvest cycles squeezes margin on commodity bond paper.
- Archive Quality:Acid-free substrates with extended permanence ratings for government record repositories.
Premium grade captures the highest margin pools; eco-friendly grade is gaining share fastest under EU Green Deal certification mandates.
Packaging Type:
Logistics economics and equipment compatibility determine format preferences across customer segments.
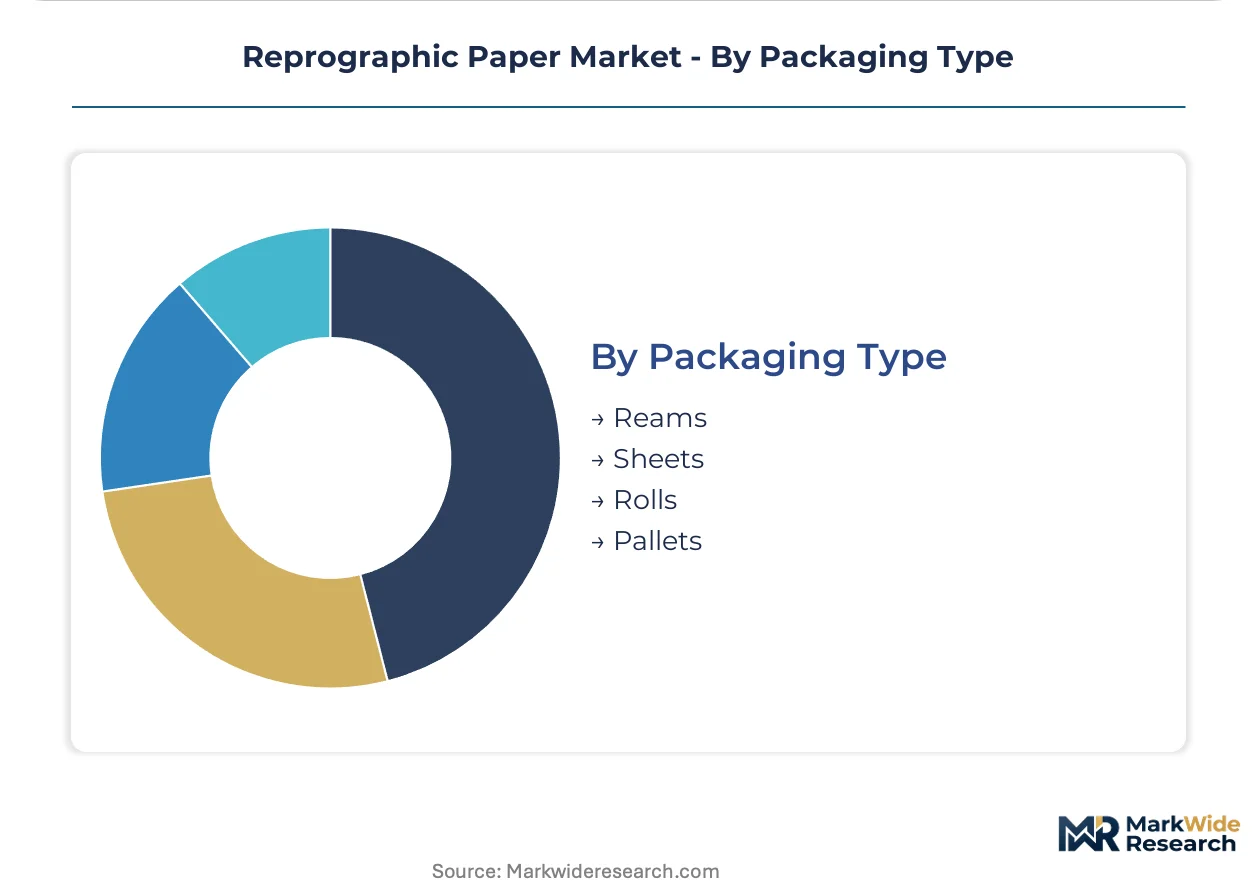
- Reams:Standard 500-sheet packaging for retail and small-office procurement.
- Sheets:Cut-size formats for specific equipment requirements in commercial print houses.
- Rolls:Continuous web supply for high-volume digital presses; customized roll widths anchor direct mill contracts.
- Pallets:Bulk shipment format for large institutional buyers with warehouse receiving infrastructure.
Reams dominate retail and small-office channels; rolls are expanding most quickly as direct mill contracting bypasses merchant distribution layers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German commercial print clusters sustain the densest premium-grade consumption per capita, while Indian state textbook programs and Japanese export certification standards reshape procurement geography across three continents.
Germany
Stuttgart and Hamburg anchor concentrated graphic arts demand for 75–90 gsm laser-calibrated reels. The EU Green Deal's Forest Stewardship Council mandates filter through municipal procurement offices, redirecting volume toward certified integrated mills. Corporate headquarters clusters in Bavaria and Baden-Württemberg maintain base-load consumption despite enterprise digitization.
United States
Multi-campus university systems in California and Texas negotiate three-year framework agreements with single-source mill commitments. EPA Comprehensive Procurement Guidelines shape institutional purchasing requirements for recycled fiber content. The Pacific Northwest fiber network sustains cost advantages in bond paper production for federal and state contracts.
India
State textbook procurement programs create volume anchors for 70–80 gsm uncoated woodfree grades in vernacular print runs. Bureau of Indian Standards specifications govern paper dimensional stability for educational materials. Maharashtra and Gujarat host expanding commercial print capacity serving domestic educational publishers.
Japan
METI-enforced JIS standards for dimensional stability under humidity cycling determine export eligibility for European suppliers. Commercial print houses in Tokyo and Osaka demand sub-0.4% expansion rates across 20–80% relative humidity ranges. Nordic pulp-sourcing specialty producers invest in extended conditioning tunnels to maintain market access.
Netherlands
Hybrid print environments in Amsterdam and Rotterdam drive adoption of convertible stocks with micro-layered surface treatments. REACH compliance requirements for optical brightening chemistries extend qualification timelines for premium white grades. Belgian and Dutch commercial printers reduce inventory SKUs through unified substrate platforms.
Reprographic Paper Market Competitive Landscape
Capacity reconfiguration dominates the current landscape as mills adapt furnish recipes to recycled fiber mandates without sacrificing laser-print compatibility. The vendor base stratifies between Nordic integrated forestry operators, North American fiber network holders, and Asian specialty coating specialists. Three archetypes anchor positioning: upstream-controlled integrated producers, scale-driven commodity suppliers, and precision-coating technology licensors. M&A consolidation and backward integration into captive pulp sourcing represent the two dominant competitive vectors reshaping supply security.
Within the integrated forestry tier, Stora Enso and UPM-Kymmene Corporation exemplify upstream-controlled positioning through Nordic fiber asset ownership. International Paper occupies a scale-driven position leveraging North American fiber network density for institutional contract cost advantages. These three entities represent divergent strategic anchors: geographic fiber control, coating technology specialization, and continental distribution scale.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Stora Enso |
| UPM-Kymmene Corporation |
| Sappi |
| Oji Holdings Corporation |
| Nippon Paper Industries |
| Mondi Group |
| Domtar |
| Others |
Value Network & Pricing Analysis
Precision coating technology is modularizing production flexibility across reprographic paper lines while simultaneously concentrating cost advantages among mills with in-house formulation expertise. This dual shift is compressing margins for commodity producers while rewarding integrated operators with captive pulp sourcing and surface chemistry capabilities.
Pricing Analysis
Volume concentrates in standard-grade bond paper while premium-grade specialty and eco-friendly certified reels capture the widest margin pools. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and recycled fiber content thresholds rather than basis weight alone. Price differentiation separates Forest Stewardship Council-certified reels from commodity grades, with EU Ecolabel compliance commanding procurement premiums from institutional buyers. Cost compression in standard grades is intensifying because hardwood fiber volatility from Brazilian eucalyptus harvest cycles squeezes producer margins. Educational institutions exhibit the highest price sensitivity due to bulk procurement frameworks, while archival-grade specialty buyers demonstrate the lowest sensitivity given extended permanence requirements.
Supply Chain Analysis
Coating chemist talent scarcity in Nordic integrated mills and German commercial print clusters is constraining surface treatment innovation capacity. Geographic supply concentrates in Finland, Sweden, and Germany where integrated forestry operations control raw material quality from harvest to finished reel. Raw material dependencies draw from Brazilian eucalyptus hardwood, Nordic softwood pulp, and optical brightening chemistries subject to REACH compliance. Single-source vulnerability runs through specialty coating formulation expertise concentrated among retiring specialists. Distribution runs through direct mill-to-institution contracting for large university systems, bypassing traditional merchant layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive pulp sourcing and in-house coating formulation capabilities determine long-term supply security. Players are pursuing upstream control over certified fiber assets as the decisive lever.
For Market Incumbents: Extend certification coverage by securing Forest Stewardship Council chain-of-custody documentation across all furnish sources to defend against EU Green Deal procurement mandates. Deepen backward integration into Nordic or North American fiber networks to insulate margin from Brazilian eucalyptus price swings. Lock in three-year framework agreements with multi-campus university systems in California and Texas before competitors establish single-source mill commitments. For New Entrants and Emerging Players: Enter via archival-grade specialty positioning where acid-free substrate expertise commands price premiums and incumbent coating chemist scarcity creates white space. Target Indian state textbook procurement programs for 70-80 gsm uncoated woodfree grades where Bureau of Indian Standards compliance barriers are lower than Japanese or European certification requirements. Pursue direct contracting relationships with vernacular educational publishers bypassing established merchant distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated forestry operators seeking coating technology capabilities. Long-term viability favors mills with combined captive pulp sourcing and precision surface treatment expertise. Acquisition target archetype: mid-scale producers with established EU Ecolabel certification and underutilized coating line capacity. Watch for inflection when Japanese METI tightens JIS dimensional stability standards further, forcing commodity mills to cede export share.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fiber Assets | Captive pulp sourcing insulates margin from Brazilian eucalyptus harvest volatility. |
| Precision Coating Technology Licensing | Modular surface treatments enable hybrid laser-inkjet compatibility for Dutch and Belgian printers. |
| Direct Mill-to-Institution Contracting | Three-year framework agreements with California and Texas university systems replace spot purchasing. |
| EU Ecolabel Certification Investment | Chain-of-custody documentation unlocks municipal procurement under EU Green Deal mandates. |
| Archival-Grade Specialty Capacity Expansion | Acid-free substrates with extended permanence ratings command premiums from museum repositories. |
Research Methodology
Multi-period observation of pulp price indices, certification adoption rates, and institutional procurement contract structures anchored the trend analysis, supplemented by interviews with mill operations directors, paper merchant category managers, university procurement officers, and coating formulation specialists. Secondary validation drew from customs trade data, Forest Stewardship Council certification databases, EPA Comprehensive Procurement Guidelines documentation, and SEC filings of publicly traded forestry operators. Bottom-up volume modeling across product grades triangulated against top-down macroeconomic demand indicators.
Input-output matrices mapped fiber furnish costs, coating chemistry formulations, and energy inputs to finished reel pricing across laser, bond, inkjet, and specialty product categories. Segmentation dimensions modeled included print technology compatibility, end-use application, quality certification tier, and geographic production hub. CAGRs were derived through regression analysis of historical consumption patterns against projected institutional purchasing growth. Forecast inputs incorporated EU Green Deal implementation timelines and Japanese METI standard revision schedules.
Revisions become necessary when Brazilian eucalyptus harvest disruptions, REACH regulatory tightening on optical brightening agents, or accelerated enterprise digitization beyond baseline assumptions materialize. Forecasts reflect documented assumptions about fiber substitution rates and certification cost trajectories. Material deviation in pulp price volatility or institutional recycled content mandate timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
North America Decor Paper Market
Paper Products
Overlay Paper Market
Paper Products
Global Molded Pulp Products Market
Paper Products
White Top Testliner Market
Paper Products
Woodfree Paper Market
Paper Products
Paper and Board Technologies Market
Paper Products
Softwood Pulp Market
Paper Products
BPA Free Thermal Paper Market
Paper Products
Graphic Paper Market
Paper Products
Pulp and Paper Market
Paper Products
Billing Paper Market
Paper Products
Global Electrical Insulation Paper Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Compressed Fiberboard Market
Paper Products
Printing and Writing Papers Market