
 Uncaria Tomentosa Market | 2026-2036
Uncaria Tomentosa Market Size, Share, and Industry Trends Forecast 2026-2036
Uncaria Tomentosa Market Analytics
The capability gap between vertically integrated extractors and commodity traders is collapsing as certification requirements intensify. Nature's Way leverages its long-standing relationships with Peruvian harvester cooperatives to secure supply continuity. NOW Foods sustains competitive positioning through rigorous third-party testing protocols that satisfy German and U.S. pharmacopeial standards. Gaia Herbs differentiates via its vertically controlled supply chain from cultivation through finished capsule production.
Uncaria tomentosa, commonly called cat's claw, is a woody vine native to Amazonian rainforests whose bark contains alkaloids including pentacyclic oxindole and tetracyclic oxindole compounds used for immunomodulatory and anti-inflammatory applications. Standardized extracts typically specify minimum 3% total alkaloid content for nutraceutical-grade material, with hot-water or ethanol extraction methods determining final marker compound profiles. Capsules and extracts command the dominant share of current revenue as health enthusiasts and nutritional companies prioritize convenient, dose-standardized delivery formats over traditional teas and loose powders. The online retail distribution channel is expanding fastest as direct-to-consumer brands bypass conventional pharmacy and specialty store intermediaries.
The U.S. FDA maintains botanical drug development guidelines that influence clinical trial investment decisions, while Germany's BfArM Commission E monographs shape reimbursement and prescription patterns across European herbal medicine markets. Peru's national biodiversity authority, INRENA, enforces wild-harvesting permits and export quotas that constrain raw material availability. Stakeholders must monitor evolving novel food authorization pathways in the European Union and traceability mandates that will determine which suppliers retain market access.
Market Dynamics
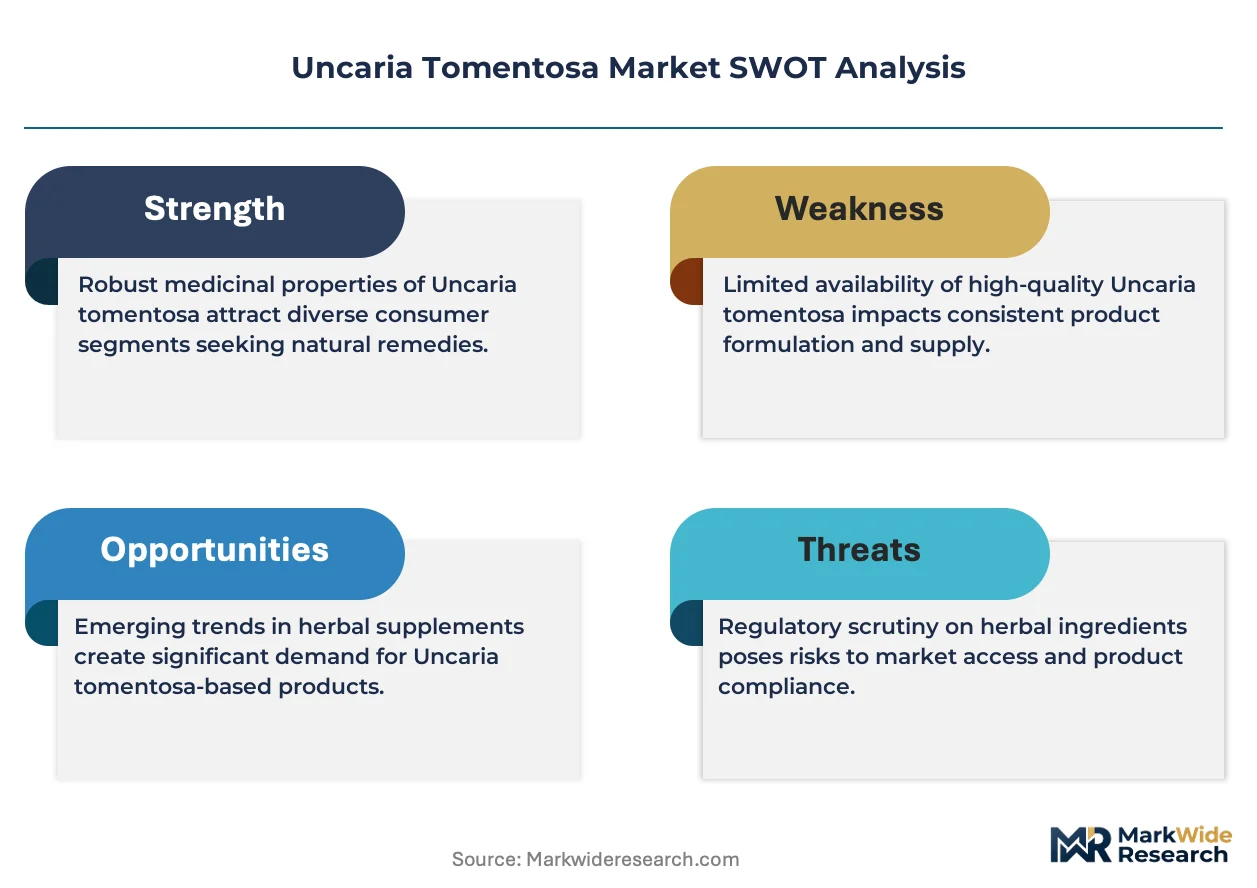
Certification requirements for botanical ingredients are collapsing the capability gap between vertically integrated extractors and commodity traders, forcing procurement consolidation around verified supply chains.
Growth Catalysts
- EU Novel Food tightening:Germany's BfArM Commission E monographs create reimbursement pathways that reward pharmacopeial-grade extracts, pulling investment into standardized alkaloid production.
- Immunomodulatory applications:Pentacyclic oxindole compounds are gaining traction in functional food formulations as manufacturers seek alternatives to synthetic immune modulators.
- Peruvian Amazon concentration:INRENA-permitted wild-harvesting cooperatives supply premium bark to European extractors, creating geographic lock-in for compliant raw material.
Market Restraints
- Wild-harvest quota constraints:INRENA export permits limit annual bark availability, creating input volatility for non-vertically integrated processors.
- Alkaloid standardization costs:Hot-water and ethanol extraction methods require capital-intensive HPLC validation to achieve 3% total alkaloid certification.
- Synthetic immunomodulator competition:Pharmaceutical-grade synthetic compounds compete for anti-inflammatory indications, compressing price ceilings in medical-grade segments.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online retail bypasses pharmacy intermediaries, enabling margin capture for brands with traceability storytelling.
- Capsule format premiumization:Dose-standardized delivery formats command price premiums over loose powders in North American wellness markets.
- EU traceability mandates:Incoming supply chain transparency requirements favor early movers with blockchain-verified Peruvian cooperative relationships.
Industry Challenges
- Phytochemical analytical talent scarcity:Qualified chromatography specialists for alkaloid profiling remain concentrated in German and Swiss contract labs.
- Novel food authorization timelines:EFSA submission-to-approval cycles stretch 18-24 months, freezing product launch schedules for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uncaria Tomentosa Market |
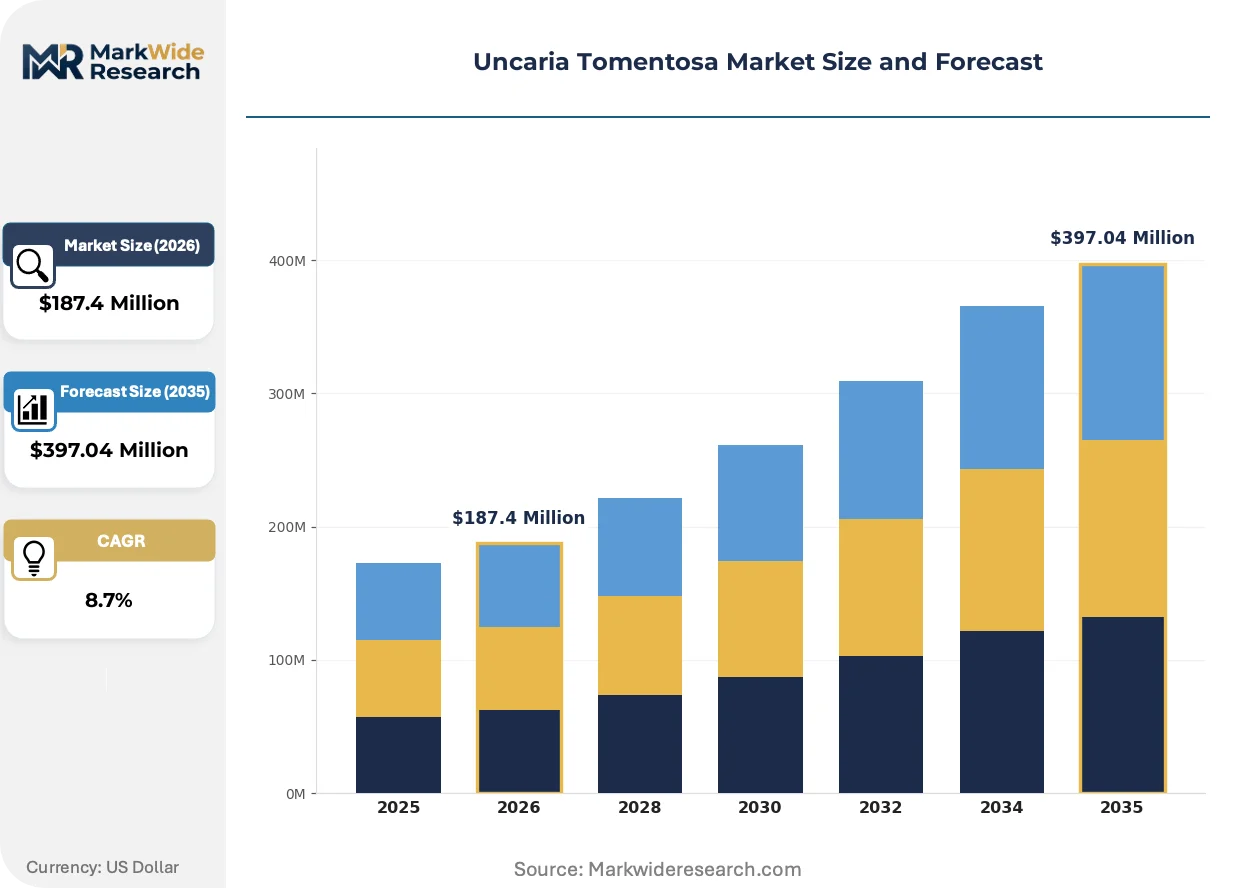
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Extracts, Powders, Teas Application: Herbal Supplements, Nutraceuticals, Infusions, Traditional Medicine End User: Health Enthusiasts, Nutritional Companies, Herbalists, Pharmacies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Nature's Way, NOW Foods, Solgar, Gaia Herbs, Herb Pharm, Swanson Health Products, Pure Encapsulations, Himalaya Herbal Healthcare, Thorne Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uncaria Tomentosa Market Evolving Landscape
Extraction technology and regulatory verification systems are reshaping how alkaloid standardization gets delivered, with implications for cost structures and competitive moats.
Supercritical CO2 extraction is miniaturizing from industrial-scale systems to pilot-plant configurations accessible to mid-sized processors. German nutraceutical contract manufacturers are adopting these units to reduce solvent residue compliance costs. The technology is miniaturizing capital barriers, enabling regional processors to achieve pharmacopeial-grade output without centralized facility investments.
EFSA's evolving novel food guidance on botanical substances is forcing reformulation of legacy capsule products. Manufacturers must resubmit dossiers with expanded toxicological data, diverting R&D budgets from line extensions. Standardized extract suppliers serving German pharmacy channels face the steepest compliance ramps.
Health enthusiasts are bypassing retail intermediaries entirely, purchasing directly from extractor-brands with harvest-to-capsule traceability. This channel compression disintermediates traditional supplement distributors in North American markets. Peruvian cooperative-processor partnerships with QR-coded batch tracking capture disproportionate loyalty in this segment.
Uncaria Tomentosa Market Segmentation
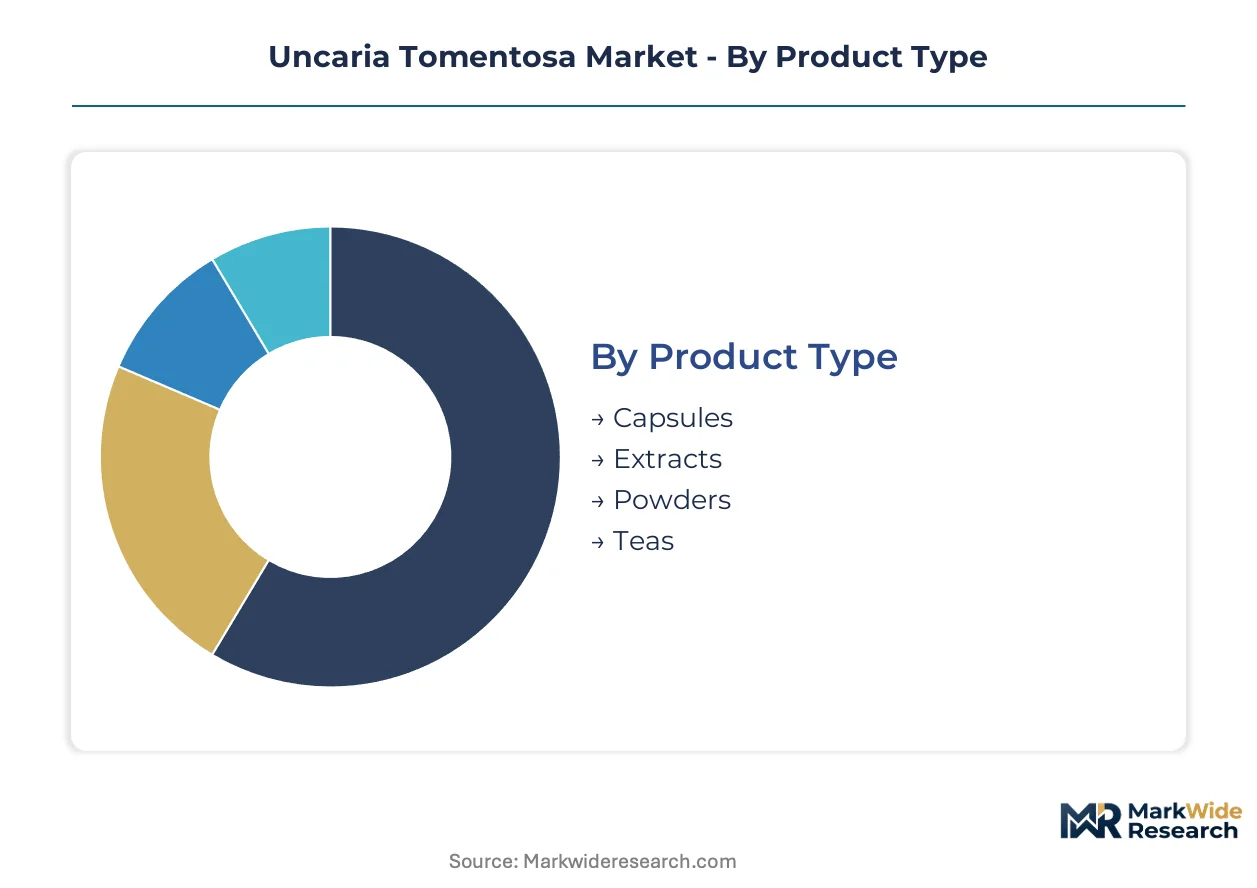
Segmentation in the Uncaria tomentosa market reveals how alkaloid standardization requirements reshape procurement patterns across delivery formats and buyer categories. Suppliers must align extraction capabilities with the diverging compliance thresholds of pharmacy channels versus direct-to-consumer wellness markets.
Product Type:
Capsules and extracts dominate export-oriented production serving German pharmacy and North American nutraceutical channels, while powders and teas concentrate in domestic Peruvian and regional Latin American consumption.
- Capsules:Dose-standardized gelatin or vegetable cellulose shells containing 300-500mg of powdered bark extract. German BfArM Commission E reimbursement pathways pull demand toward pharmacopeial-grade capsule formats that guarantee 3% total alkaloid content. Health enthusiasts in North America favor this convenience-driven delivery for daily immunomodulatory regimens.
- Extracts:Liquid or standardized powder concentrates produced via hot-water or ethanol extraction methods, with HPLC-validated alkaloid profiles. NOW Foods and comparable manufacturers prioritize these for third-party testing protocols that satisfy U.S. and German pharmacopeial standards. The format commands premium positioning in clinical and wellness applications requiring precise dosing.
- Powders:Coarsely ground raw bark or spray-dried extract suitable for bulk formulation. Peruvian domestic markets and traditional medicine practitioners in Amazonian communities sustain localized demand.
- Teas:Dried bark pieces or bagged preparations for aqueous extraction. Regional consumption in Latin American markets persists despite limited alkaloid bioavailability versus standardized extracts.
Capsules command the established base. The steepest expansion runs through extracts.
Application:
Cost tier differentiation separates premium-priced nutraceutical applications with full certification documentation from economy-positioned traditional preparations lacking standardized alkaloid validation.
- Herbal Supplements:Capsule and tablet formulations targeting immune support and anti-inflammatory wellness positioning. Gaia Herbs and vertically integrated brands leverage harvest-to-capsule traceability to capture margin in this segment. German novel food compliance requirements increasingly filter which suppliers retain shelf access.
- Nutraceuticals:Functional food and beverage integrations requiring water-soluble extract forms with validated pentacyclic oxindole compound stability. Pentacyclic oxindole compounds are gaining traction as manufacturers seek alternatives to synthetic immune modulators. EFSA authorization timelines stretch 18-24 months for new entrants.
- Infusions:Aqueous preparations from loose bark or tea bags with variable alkaloid extraction efficiency. Traditional consumption patterns in Peruvian and broader Andean markets sustain volume without premium pricing.
- Traditional Medicine:Uncertified bark preparations used by herbalists and indigenous practitioners. INRENA wild-harvest permits constrain raw material flows to this segment as export quotas prioritize certified channels.
Herbal supplements anchor current revenue. Nutraceuticals are climbing the fastest as functional food manufacturers seek botanical immunomodulators.
End User:
Volume concentration varies sharply between institutional procurement by nutritional companies and fragmented individual purchasing by health enthusiasts.
- Health Enthusiasts:Direct-to-consumer buyers prioritizing traceability storytelling and QR-coded batch verification. Online retail expansion enables extractor-brands to bypass pharmacy intermediaries and capture loyalty through Peruvian cooperative partnerships.
- Nutritional Companies:Contract manufacturers and finished goods brands requiring certified extracts with validated alkaloid content. German nutraceutical manufacturers are expanding procurement of certified extracts as EU novel food regulations tighten compliance requirements.
- Herbalists:Practitioners sourcing raw bark or minimally processed materials for custom preparations. Demand concentrates in regions with established traditional medicine frameworks.
- Pharmacies:German and select European pharmacy channels dispensing Commission E-monographed products. BfArM reimbursement pathways reward pharmacopeial-grade extracts with documented standardization.
Nutritional companies dominate procurement volume. Health enthusiasts are gaining share fastest through direct-to-channel purchasing.
Distribution Channel:
Margin capture potential diverges between traceability-enabled online retail and intermediated specialty store networks with higher working capital requirements.
- Online Retail:Direct-to-consumer platforms enabling extractor-brands to bypass traditional supplement distributors. QR-coded batch tracking from Peruvian cooperatives captures disproportionate loyalty in this compressed channel.
- Specialty Stores:Health food and natural product retailers carrying curated supplement selections. NOW Foods and comparable brands sustain positioning through rigorous testing protocols visible on shelf packaging.
- Supermarkets:Mass-market retail with limited SKU depth and price-driven selection criteria. Standardized extracts struggle to communicate value proposition in low-interaction purchase environments.
- Direct Sales:Practitioner and multi-level marketing channels emphasizing educational content. Herbalists and wellness coaches drive adoption through personal recommendation networks.
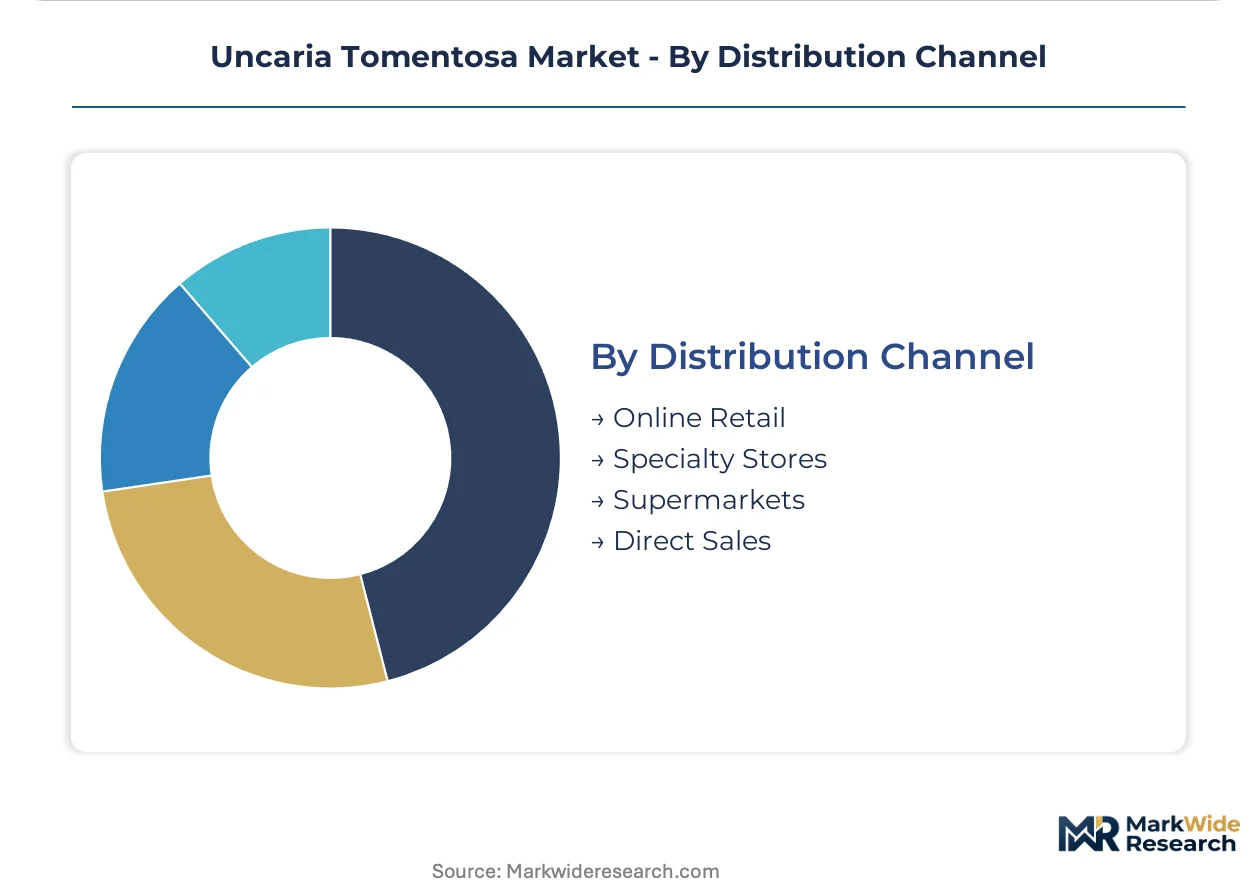
Specialty stores maintain the established footprint. Online retail shows the steepest expansion trajectory as traceability storytelling displaces intermediary markups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in German pharmacy channels absorb steep certification premiums, while Peruvian domestic consumers purchase uncertified bark at fractions of export prices. This elasticity gap concentrates investment in pharmacopeial-grade extraction capacity serving affluent markets.
Peru
INRENA-permitted wild-harvesting cooperatives in the Amazon basin supply premium raw bark to European extractors. The national biodiversity authority enforces export quotas that constrain annual availability. Iquitos and Pucallpa serve as consolidation hubs where cooperatives grade bark by alkaloid density before international shipment.
Germany
BfArM Commission E monographs create reimbursement pathways for pharmacopeial-grade extracts. The country's nutraceutical manufacturers are expanding procurement of certified extracts as EU novel food regulations tighten compliance requirements. Hamburg and Frankfurt host contract labs performing HPLC validation for alkaloid standardization.
United States
Health enthusiasts drive direct-to-consumer demand for traceable capsules with QR-coded batch verification. FDA botanical drug development guidelines influence clinical trial investment decisions. Utah and Colorado house supplement brands emphasizing third-party testing protocols visible on shelf packaging.
Canada
Health Canada and PMRA oversight shapes import requirements for botanical ingredients entering the natural health product channel. British Columbia and Ontario retailers curate selections emphasizing pharmacopeial-grade extracts. Vancouver serves as a West Coast entry point for Peruvian cooperative shipments.
Switzerland
Swissmedic regulations and proximity to German pharmacy markets position the country as a high-margin distribution node. Zurich and Basel house traders specializing in certified alkaloid extracts. Swiss contract manufacturers perform final formulation steps for EU-bound capsule products.
Uncaria Tomentosa Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capability gaps collapsing as certification requirements intensify. The structure rewards backward integration into Peruvian cooperative relationships and penalizes commodity traders lacking traceability documentation. Three archetypes dominate: harvester-integrated extractors, testing-intensive contract manufacturers, and direct-to-consumer brands with storytelling capabilities. Competitive moves concentrate on securing INRENA-permitted supply quotas and achieving pharmacopeial-grade alkaloid certification.
Within the integrated extractor tier, Nature's Way and Gaia Herbs exemplify archetypes built on Peruvian cooperative relationships and harvest-to-capsule traceability. NOW Foods occupies a position among testing-intensive specialists emphasizing third-party validation protocols. These three names anchor the competitive map without exhausting its diversity.
| Leading Market Players |
|---|
| Nature's Way |
| NOW Foods |
| Solgar |
| Gaia Herbs |
| Herb Pharm |
| Swanson Health Products |
| Pure Encapsulations |
| Himalaya Herbal Healthcare |
| Thorne Research |
| Others |
Value Network & Pricing Analysis
Pharmacopeial-grade alkaloid extracts displacing commodity bark shipments are redrawing procurement geography from Peruvian cooperatives toward German contract labs, compressing margins for traders lacking HPLC validation capabilities while rewarding vertically integrated processors with INRENA quota access.
Pricing Analysis
After-sales certification documentation and extended laboratory validation contracts drive lifetime value for extractors serving BfArM-monographed pharmacy channels. Three-tier pricing structure across pharmacopeial-grade extracts, wellness-grade capsules, and uncertified raw bark separates German reimbursement pathways from North American direct-to-consumer positioning and Peruvian domestic consumption. Cost compression in commodity bark tiers is intensifying because INRENA export quotas constrain supply volume available to non-integrated traders. Nutritional companies exhibit the highest price sensitivity due to margin pressure from synthetic immunomodulator competition, while pharmacy channels absorb premium pricing for documented alkaloid standardization.
Supply Chain Analysis
Peru and Germany anchor the Uncaria tomentosa supply chain through INRENA-permitted Amazonian harvesting and BfArM-influenced extraction validation. Raw material flows draw from wild-harvested bark, ethanol and hot-water processing solvents, and HPLC reference standards for alkaloid quantification. Single-source vulnerability concentrates in INRENA quota administration, where permit allocation decisions determine annual export availability. Distribution runs through extractor-brands with direct-to-consumer platforms, specialty store networks with third-party testing visibility, and pharmacy channels requiring Commission E monograph compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU novel food authorization timelines stretching 18-24 months are compressing launch windows for new entrants while rewarding early movers with validated dossiers, creating a regulatory inflection that favors incumbent investment in toxicological data generation.
For Market Incumbents: Consolidate INRENA-permitted cooperative relationships through long-term offtake agreements that lock in raw material quota ahead of tightening export restrictions. Invest in supercritical CO2 extraction capacity to reduce solvent residue compliance costs and defend margin position against mid-sized German contract manufacturers adopting miniaturized pilot-plant configurations.
For New Entrants and Emerging Players: Lead with direct-to-consumer traceability storytelling targeting North American health enthusiasts, where QR-coded batch verification from Peruvian cooperatives captures loyalty without pharmacy intermediary markups. Target online retail channel expansion as the most penetrable white space, leveraging blockchain-verified supply chain documentation as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed nutraceutical contract manufacturers lacking backward integration into Peruvian harvesting cooperatives. Five-to-ten-year viability hinges on securing captive raw material supply before INRENA quota constraints intensify. Watch EFSA novel food authorization grant velocity as the critical inflection signal distinguishing compliant extractors from stranded legacy product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peruvian Cooperatives | INRENA quota access secures raw material supply continuity for pharmacopeial-grade extraction. |
| Supercritical CO2 Extraction Adoption | German contract manufacturers reduce solvent residue compliance costs through miniaturized pilot-plant configurations. |
| Blockchain Traceability Implementation | QR-coded batch tracking captures disproportionate loyalty among direct-to-consumer health enthusiasts. |
| EFSA Novel Food Dossier Investment | Expanded toxicological data generation preserves shelf access in tightening EU regulatory environment. |
| Direct-to-Consumer Channel Expansion | Online retail platforms disintermediate traditional supplement distributors and capture margin through traceability storytelling. |
Research Methodology
Desk research of INRENA export permit databases, BfArM Commission E monograph archives, and EFSA novel food submission records preceded structured interviews with Peruvian cooperative managers, German nutraceutical procurement leads, and U.S. supplement brand supply chain directors. Secondary validation drew from customs trade data, pharmacopeial standard publications, and clinical trial registries. Bottom-up volume estimates from extraction capacity and quota allocations were triangulated against top-down demand projections from pharmacy reimbursement data and direct-to-consumer sales channels.
Variance decomposition across product type, application tier, end-user category, and distribution channel shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Modeled inputs included INRENA permit issuance trends, EFSA authorization cycle durations, and supercritical CO2 extraction technology adoption curves in German contract manufacturing.
Forecasts assume regulatory continuity in EU novel food frameworks and Peruvian biodiversity export controls; material policy shifts would require re-modeling. Specific risks that could revise projections include INRENA quota allocation changes, EFSA botanical substance guidance revisions, and synthetic immunomodulator pricing pressure in medical-grade segments. Recalibration cycles align with material shifts in regulatory authorization timelines and extraction technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Australia Lime Market
Agriculture and Agri Products
Sophora Japonica Market
Agriculture and Agri Products
Africa Compound Feed Market
Agriculture and Agri Products
Ghana Agriculture Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
South Africa Alfalfa Hay Market
Agriculture and Agri Products
Mushroom Substrate Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
India Agriculture Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Italy Animal Protein Market
Agriculture and Agri Products
Feed Grade Oils Market
Agriculture and Agri Products
Animal Derivatives Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Aquatic Feed Ingredients and Products Market