
 Africa Animal Protein Market | 2026-2036
Africa Animal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Animal Protein Market Outlook
Project finance for integrated feedlot-to-abattoir operations is reshaping competitive entry in the Africa Animal Protein Market. Cargill Incorporated leverages its grain-trading infrastructure to secure captive cattle supply in Southern Africa. Arla Foods anchors dairy-derived protein streams through its East African processing partnerships. Kerry Group competes on ingredient formulation for ready-to-eat meat products aimed at urban retail channels.
Africa animal protein encompasses muscle tissue, collagen, and derived fractions from livestock and aquatic species, typically processed under HACCP-aligned temperature controls to preserve microbiological integrity for human nutrition. Poultry leads product type volume due to shorter production cycles and lower feed conversion ratios relative to beef. The food service end user segment commands premium pricing through contracted slaughter-to-delivery schedules. Free-range and organic production methods attract margin pools from health-conscious consumers in South African supermarkets.
South Africa's Department of Agriculture enforces meat safety standards through the Meat Safety Act, while Nigeria's National Agency for Food and Drug Administration and Control regulates protein import quality. Kenya's Kenya Bureau of Standards mandates labelling and traceability for packaged animal products. Stakeholders must monitor how harmonized standards across the African Continental Free Trade Area reshape cross-border meat trade eligibility.
Market Dynamics
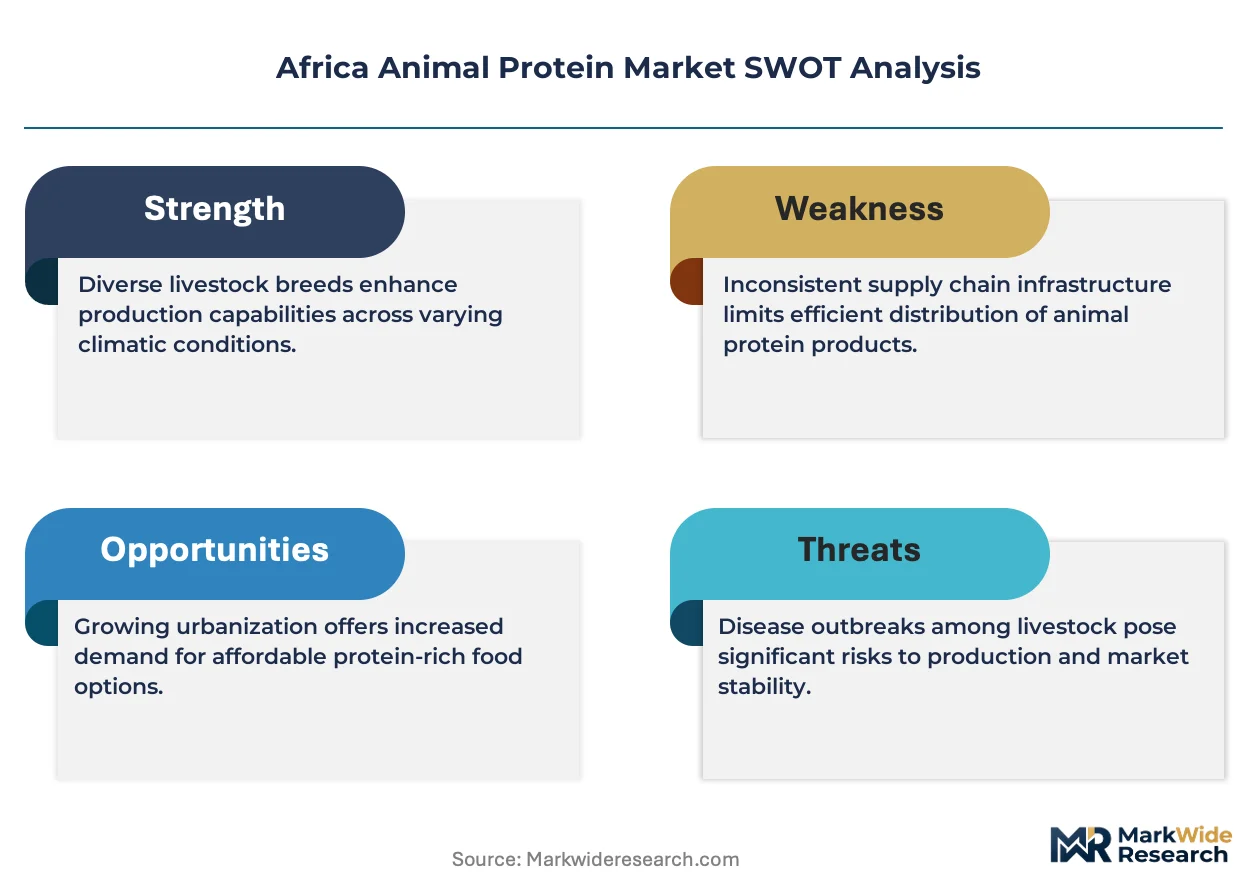
Cold-chain infrastructure gaps between urban demand centers and rural production zones are forcing capital reallocation toward integrated logistics networks, compressing traditional broker margins while elevating processor-processor direct contracting.
Growth Catalysts
- Urban food service expansion:Quick-service restaurant chains across Nigeria's Lagos-Abuja corridor are locking in multi-year protein procurement contracts, creating predictable offtake for integrated feedlot operators.
- East African dairy processing partnerships:Arla Foods' technical assistance programs are upgrading local chilling capacity, extending shelf life for fluid milk and derived protein fractions reaching Nairobi retail.
- South Africa's Meat Safety Act enforcement:Tightened cold-chain compliance rules are accelerating consolidation among licensed abattoirs, privileging capitalized players with HACCP-aligned temperature controls.
Market Restraints
- Feed input cost volatility:Maize and soybean meal prices in Southern Africa fluctuate with regional rainfall patterns, squeezing feedlot margins during drought cycles.
- Generator-dependent cold storage:Unreliable grid electricity across Nigerian processing clusters forces diesel generator reliance, adding structural cost premiums to domestic beef.
- Poultry's feed conversion advantage:Shorter production cycles and lower feed conversion ratios relative to beef constrain cattle investment returns in price-sensitive segments.
Strategic Opportunities
- Kenya's packaged meat traceability mandate:Kenya Bureau of Standards labelling requirements are creating first-mover advantages for processors investing in RFID-enabled lot tracking.
- Free-range certification premiums:Health-conscious consumers in South African supermarkets are paying margin premiums for organic production methods, opening specialty positioning.
- African Continental Free Trade Area harmonization:Cross-border meat trade eligibility rules are reshaping, enabling regional scale for compliant processors.
Industry Challenges
- Veterinary cold-chain technician scarcity:Qualified personnel for HACCP-aligned temperature monitoring are concentrated in South Africa and Nigeria, limiting expansion elsewhere.
- Abattoir certification timelines:South Africa's Department of Agriculture inspection backlogs delay licensing for new entrants, extending capital lockup periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Animal Protein Market |
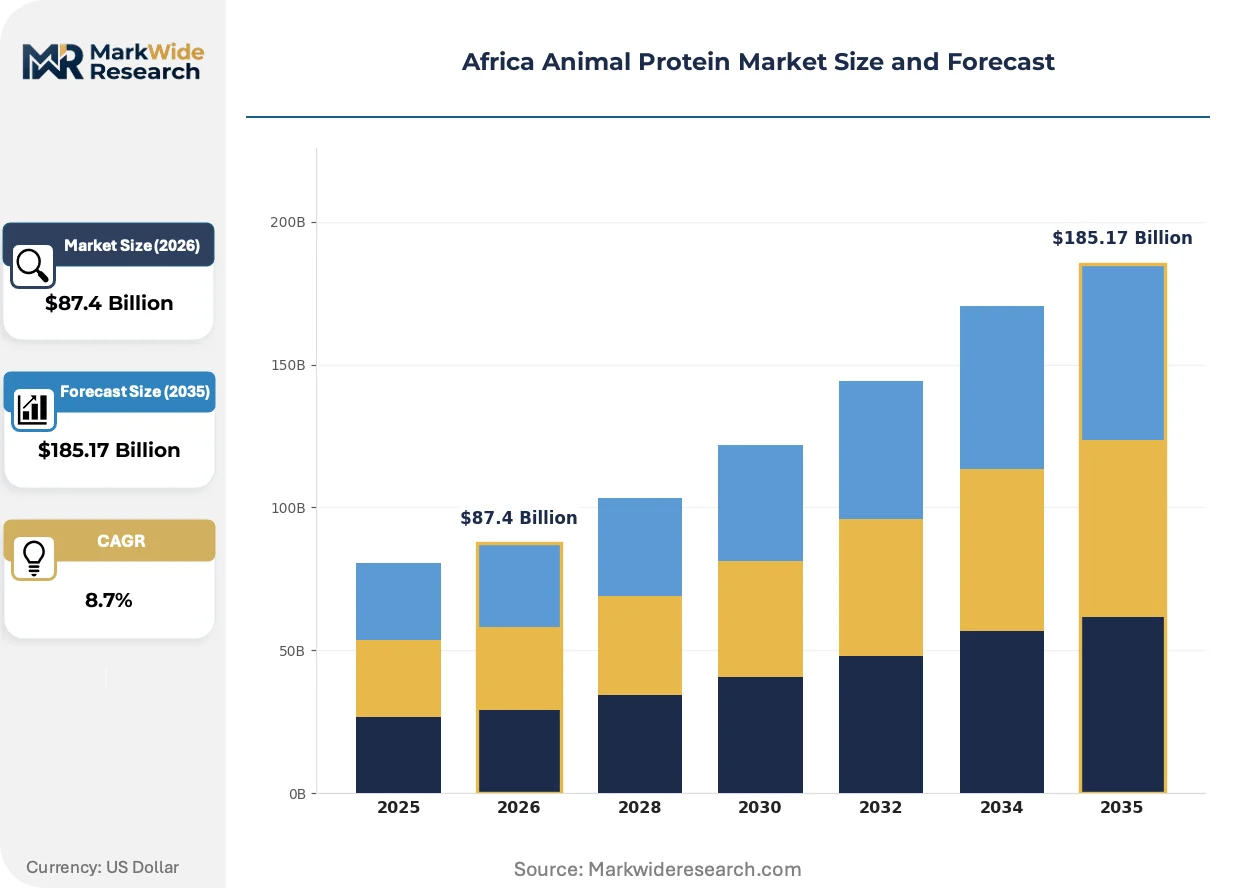
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Poultry, Pork, Goat End User: Food Service, Retail, Wholesale, Direct Consumer Distribution Channel: Supermarkets, Local Markets, Online Retail, Butcheries Production Method: Free-Range, Organic, Intensive Farming, Aquaculture |
| Companies Covered | Fonterra Co-operative Group Limited, Royal FrieslandCampina, Kerry Group, Hilmar Cheese Company, Lactoprot Deutschland, Prolactal, Amesi Group, Arla Foods, Cargill Incorporated, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Animal Protein Market Strategic Shifts
Digital traceability systems and alternative protein formulations are compressing traditional supply chain hierarchies while regulatory pressure on safety documentation accelerates technology adoption across East and Southern African processing corridors.
Blockchain-enabled livestock provenance tracking is digitizing custody records from farm gate to retail shelf. Kenyan beef exporters serving UAE halal markets are piloting distributed ledger verification to satisfy MOHAP import documentation requirements. This transparency layer is digitizing previously paper-based broker relationships, compressing information asymmetry premiums.
South Africa's Department of Agriculture, Land Reform and Rural Development has tightened cold-chain compliance rules for meat processors. The regulation mandates continuous temperature logging and third-party audit trails for licensed abattoirs. Medium-scale processors in Gauteng and Western Cape provinces are responding by retrofitting IoT sensor networks to avoid licence suspension.
Quick-service restaurant chains in Nigeria's Lagos-Abuja corridor are consolidating protein procurement through contracted slaughter-to-delivery schedules. This buyer concentration is displacing spot-market purchasing at municipal abattoirs. The procurement shift is most visible in poultry, where KFC and local equivalents now source directly from integrated breeder-to-processor operations rather than wholesale wet markets.
Africa Animal Protein Market Segmentation
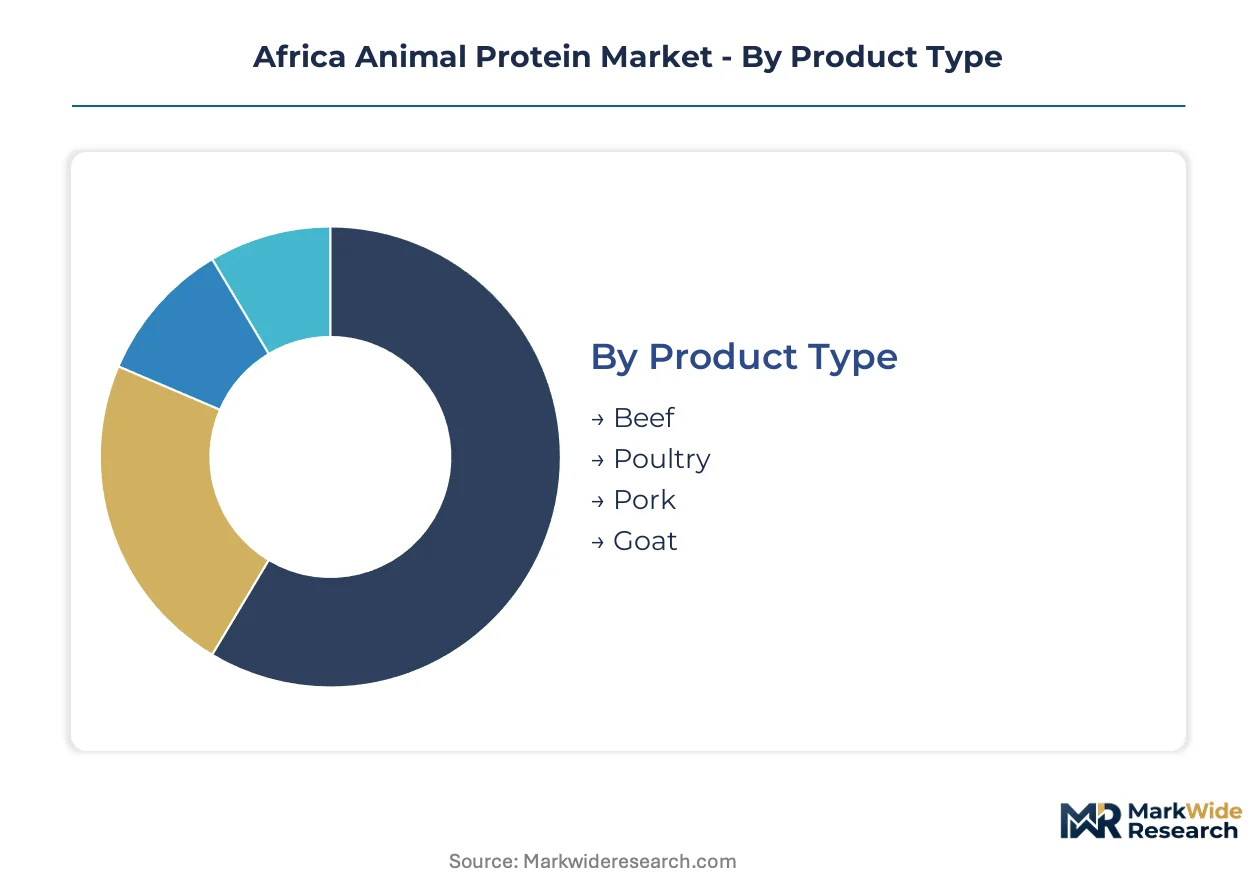
Protein sourcing strategies diverge sharply across African markets based on production cycle economics, cold-chain reach, and buyer concentration. Understanding these segment boundaries clarifies where capital deploys for margin capture versus volume play.
Product Type:
Protein selection tracks feed conversion efficiency, slaughter infrastructure maturity, and religious dietary compliance across the continent's major consumption corridors.
- Poultry:Shorter production cycles and superior feed conversion ratios make this the default protein for price-sensitive urban populations. Quick-service restaurant chains across Nigeria's Lagos-Abuja corridor lock in multi-year procurement contracts with integrated breeder-to-processor operations, displacing spot-market purchasing at municipal abattoirs.
- Beef:Muscle tissue and collagen fractions require HACCP-aligned temperature controls from slaughter through retail. South Africa's Department of Agriculture enforcement of the Meat Safety Act privileges capitalized feedlot-to-abattoir operators with continuous cold-chain logging capabilities.
- Pork:Consumption concentrates in non-Muslim majority regions of Southern Africa where religious restrictions do not apply.
- Goat:Preferred protein for ceremonial and traditional consumption across East African markets with limited commercial scale.
The dominant share belongs to Poultry, while Beef is closing the gap fastest through integrated feedlot investment.
End User:
Buyer concentration determines contract structure, with formal channels extracting predictability premiums from processors.
- Food Service:Contracted slaughter-to-delivery schedules command premium pricing through volume commitments and specification consistency. KFC and local quick-service equivalents in Nigeria now source directly from integrated operations rather than wholesale wet markets.
- Retail:Packaged meat traceability mandates from Kenya Bureau of Standards create first-mover advantages for processors investing in RFID-enabled lot tracking systems.
- Wholesale:Traditional broker margins compress as processor-processor direct contracting displaces spot-market intermediation.
- Direct Consumer:Municipal abattoir sales persist where cold-chain infrastructure gaps prevent packaged product penetration.
Food Service captures the steepest expansion trajectory as urban quick-service restaurant penetration deepens.
Distribution Channel:
Channel selection reflects electricity reliability, consumer packaging preferences, and traceability compliance capabilities.
- Supermarkets:Free-range and organic certification premiums attract health-conscious consumers in South African urban centers with consistent cold-chain maintenance.
- Local Markets:Wet market dominance persists where generator-dependent cold storage adds structural cost premiums to domestic beef.
- Online Retail:Digital traceability systems enable direct farm-to-consumer provenance verification for premium positioning.
- Butcheries:Traditional skilled cutting and custom preparation retain share in peri-urban communities.
Supermarkets lead value capture, while Online Retail gains share fastest through blockchain-enabled livestock provenance tracking.
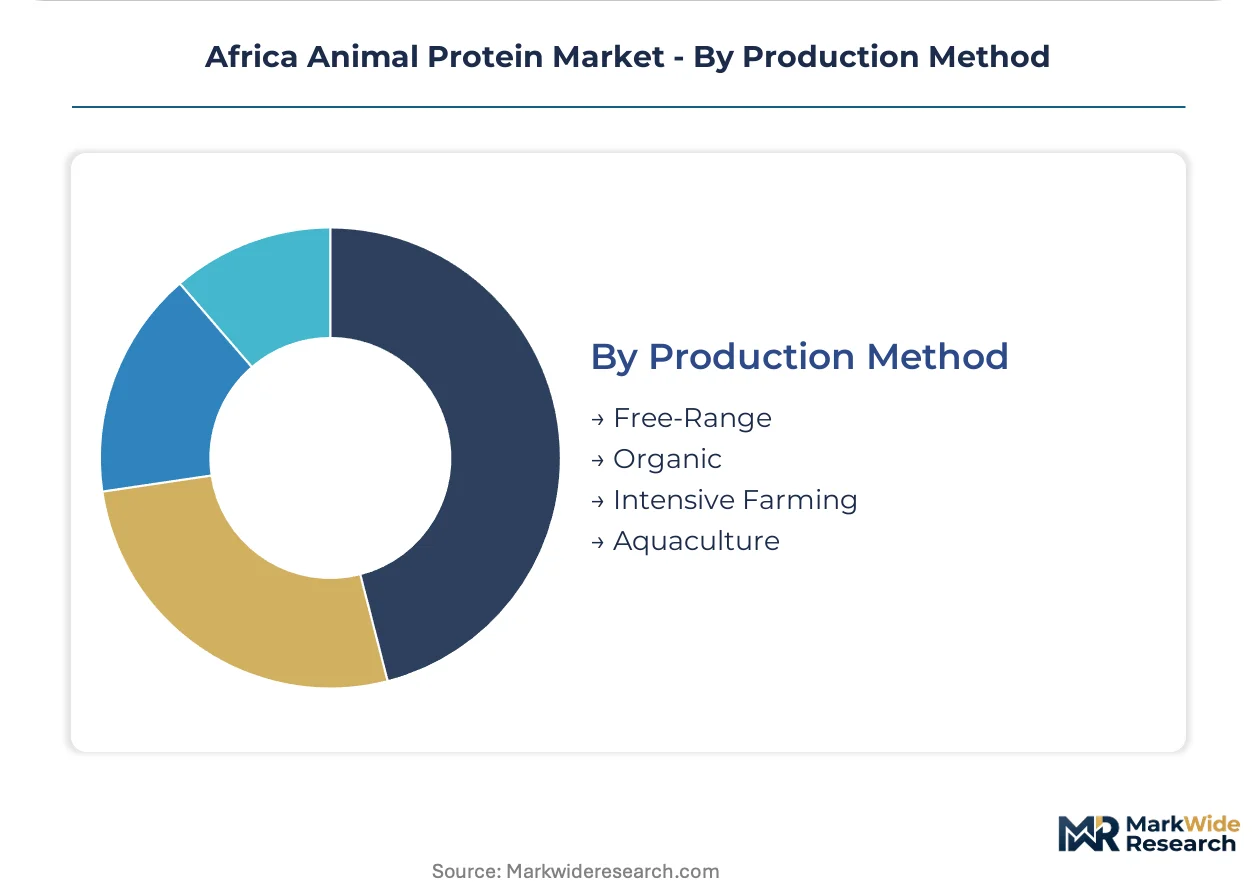
Production Method:
Method selection balances capital intensity, certification premiums, and veterinary compliance requirements.
- Intensive Farming:Confined feeding operations achieve scale economies through controlled nutrition and disease management, dominating supply to formal food service channels.
- Free-Range:Health-conscious consumers in South African supermarkets pay margin premiums for production methods with perceived welfare and nutritional advantages.
- Organic:Certification requirements limit supply to specialty positioning with restricted geographic penetration.
- Aquaculture:Aquatic protein fractions from farmed species supplement terrestrial supply in coastal East African markets.
Intensive Farming holds volume leadership, while Free-Range is expanding most quickly through supermarket premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows across African animal protein corridors reflect divergent cold-chain maturity and regulatory enforcement intensity. South Africa maintains net exporter status for beef and dairy derivatives, while Nigeria and Kenya remain import-dependent for high-value protein fractions. Cross-border trade eligibility under AfCFTA harmonization protocols is redirecting procurement networks toward compliant regional hubs.
Nigeria
Quick-service restaurant chains along the Lagos-Abuja corridor are locking in multi-year poultry procurement contracts, displacing spot-market purchasing at municipal abattoirs. The National Agency for Food and Drug Administration and Control regulates protein import quality through port-of-entry inspection protocols. Lagos processing clusters face generator-dependent cold storage costs that add structural premiums to domestic beef.
South Africa
Capitalized feedlot-to-abattoir operators with HACCP-aligned temperature controls capture consolidation benefits from tightened Meat Safety Act enforcement. The Department of Agriculture, Land Reform and Rural Development mandates continuous temperature logging and third-party audit trails for licensed facilities. Gauteng and Western Cape provinces concentrate retrofitting activity as medium-scale processors deploy IoT sensor networks to avoid licence suspension.
Kenya
Beef exporters serving UAE halal markets pilot blockchain-enabled livestock provenance tracking to satisfy MOHAP import documentation requirements. The Kenya Bureau of Standards mandates RFID-enabled lot tracking for packaged meat products, creating first-mover advantages for compliant processors. Nairobi retail channels benefit from Arla Foods technical assistance programs upgrading local chilling capacity for fluid milk and derived protein fractions.
Egypt
Poultry consumption dominates urban protein intake due to shorter production cycles aligning with price-sensitive household budgets. The country's national food safety regulator enforces slaughterhouse licensing requirements that privilege integrated breeder-to-processor operations over fragmented wet-market suppliers. Cairo-Alexandria corridor distribution networks concentrate cold-chain investment as supermarket penetration deepens.
Ethiopia
Live cattle exports to Middle Eastern markets compete with domestic value-addition initiatives in emerging industrial parks. The Ministry of Agriculture promotes feedlot development through credit facilities targeting integrated operations with export certification capability. Addis Ababa and surrounding highland zones concentrate preliminary processing infrastructure as regional trade corridors mature.
Africa Animal Protein Market Competitive Environment
On the supply side, the industry is consolidating around capitalized operators with captive feedlot capacity and licensed cold-chain infrastructure. Traditional broker margins compress as processor-processor direct contracting displaces spot-market intermediation. Three archetypes dominate: grain-trading conglomerates leveraging agricultural input networks, dairy cooperatives anchoring fluid milk and fraction processing, and ingredient formulators serving ready-to-eat product channels. Competitive moves concentrate on backward integration into captive cattle supply and strategic partnerships for chilling capacity upgrades.
Within the grain-trading tier, Cargill Incorporated occupies a position exemplifying upstream control over feed inputs and livestock procurement networks. Arla Foods and Kerry Group represent divergent specialization vectors—dairy-derived protein streams versus ingredient formulation for urban retail channels—each anchoring distinct margin pools in East and Southern African processing corridors. These three entities illustrate how supply-side structure privileges players with integrated infrastructure over fragmented spot-market participants.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Royal FrieslandCampina |
| Kerry Group |
| Hilmar Cheese Company |
| Lactoprot Deutschland |
| Prolactal |
| Amesi Group |
| Arla Foods |
| Cargill Incorporated |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Nigeria's generator-dependent processing clusters compresses supplier margins while elevating spot-market premiums for domestic beef. Lagos-Abuja corridor processors pass diesel-reliant cold storage costs downstream, tightening price discipline across food service procurement channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Africa Animal Protein Market. Three-tier pricing structure across premium, standard, and economy levels separates HACCP-certified cold-chain products from municipal abattoir supply and wet-market intermediation. Cost compression in standard-tier poultry intensifies as integrated breeder-to-processor operations displace fragmented spot purchasing. Wholesale brokers exhibit highest price sensitivity, while quick-service restaurant chains lock in volume commitments that secure specification consistency.
Supply Chain Analysis
Feed input volatility between South Africa and Zambia dominates supply chain risk exposure across Southern African feedlot operations. Geographic supply concentration centers on South Africa, Nigeria, and Kenya as the three primary processing hubs with licensed cold-chain infrastructure. Raw material dependencies rest on maize, soybean meal, and veterinary cold-chain equipment. Single-source vulnerability in qualified HACCP technician pools limits expansion beyond established corridors. Distribution runs through processor-processor direct contracting that displaces traditional broker intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa Animal Protein Market is cycling through drought-recovery dynamics as regional rainfall patterns stabilize feed input costs. Capital deployment timing favors positions taken before the next El Niño cycle compresses margins.
For Market Incumbents: Pre-empt consolidation opportunities in Kenya's traceability-mandate environment by acquiring RFID-enabled processors ahead of Kenya Bureau of Standards enforcement deadlines. Backward integration into captive maize and soybean supply in Zambia and Tanzania insulates feedlot margins from rainfall-driven price spikes. Channel control through direct contracting with quick-service restaurant chains locks out emerging competitors from predictable offtake volumes.
For New Entrants and Emerging Players: Ethiopia's live cattle export corridors present underpenetration in domestic value-addition infrastructure, with emerging industrial parks offering credit-facilitated feedlot development. Target packaged meat traceability compliance as the most penetrable segment, since Kenya Bureau of Standards mandates create first-mover advantages for new RFID-enabled entrants. Go-to-market positioning through blockchain-enabled halal provenance for Middle Eastern export markets bypasses established South African competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated feedlot-to-abattoir operators with multi-year food service contracts spanning the Lagos-Abuja corridor. Long-term viability over a five-to-ten-year window favors capitalized players with HACCP-aligned temperature controls and licensed cold-chain infrastructure. Acquisition target archetype: medium-scale processors in Gauteng and Western Cape provinces retrofitting IoT sensor networks to meet South Africa's Department of Agriculture compliance rules. Monitor veterinary cold-chain technician scarcity as the signal indicating where regulatory bottlenecks will constrain supply expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Supply | Cargill Incorporated leverages grain-trading infrastructure to secure captive cattle supply in Southern Africa. |
| RFID-Enabled Traceability Investment | Kenya Bureau of Standards mandates create first-mover advantages for compliant processors in Nairobi retail channels. |
| Blockchain Provenance Pilot | Kenyan beef exporters serving UAE halal markets satisfy MOHAP import documentation through distributed ledger verification. |
| Direct Food Service Contracting | Quick-service restaurant chains in Nigeria's Lagos-Abuja corridor displace spot-market purchasing at municipal abattoirs. |
| Cold-Chain Compliance Retrofit | Medium-scale processors in Gauteng deploy IoT sensor networks to avoid South Africa's Department of Agriculture licence suspension. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with feedlot managers, abattoir licensing officers, quick-service restaurant procurement heads, cold-chain logistics coordinators, and veterinary compliance specialists. Secondary validation drew from South Africa's Meat Safety Act enforcement records, Nigeria's National Agency for Food and Drug Administration and Control import inspection protocols, Kenya Bureau of Standards traceability mandates, customs and trade data for regional protein flows, and African Continental Free Trade Area harmonization documentation. Bottom-up capacity assessments across licensed processing facilities were triangulated against top-down consumption estimates from urban food service expansion metrics.
Calibration against historical capacity utilization and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user, distribution channel, production method, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints. Industry-specific forecast inputs encompass feed conversion ratio trends and cold-chain infrastructure investment pipelines.
Practitioners should monitor drought-cycle recurrence, AfCFTA harmonization implementation delays, and veterinary technician training program outputs for early signals requiring forecast reassessment. Forecasts reflect assumptions regarding rainfall pattern stability and regulatory enforcement continuity. Macroeconomic currency volatility, regulatory inspection backlog extensions, or alternative protein technology breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Greenhouse Market
Agriculture and Agri Products
Feed Grade Oils Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Compound Feed Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
LAMEA Artificial Humus Market
Agriculture and Agri Products
North America Eggs Market