
 Australia Lime Market | 2026-2036
Australia Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Lime Market Analysis
Project finance tied to infrastructure build-outs is reshaping competitive access for mid-tier lime suppliers across Australia. Adelaide Brighton Ltd leverages its integrated quarry-to-kiln network along the southern coast to sustain cost advantages in construction-grade quicklime. Boral Limited anchors its position through dense rail-linked distribution into Sydney and Melbourne metropolitan concrete markets. Graymont Limited differentiates via specialized high-calcium lime products serving Western Australian mining processing circuits.
Lime encompasses calcium oxide (quicklime) and calcium hydroxide (hydrated lime) produced by thermal decomposition of limestone at temperatures exceeding 900 degrees Celsius, serving primarily as a chemical reagent, pH modifier, and fluxing agent across industrial processes. Quicklime dominates volume flows through construction and steel fluxing applications where margin pools remain deepest despite energy-intensive kiln requirements. Hydrated lime captures faster expansion in water treatment and environmental remediation segments as TGA-aligned purity standards tighten across municipal procurement contracts. Agricultural limestone maintains stable tonnage through direct supply relationships with Queensland and New South Wales farming cooperatives.
TGA standards intersect with state-level EPA licensing to govern product purity, dust emissions, and kiln fuel sources across Australian lime manufacturing. The Australian Competition and Consumer Commission monitors bulk supply contracting practices affecting construction and mining end users. Stakeholders must track evolving carbon border adjustment mechanisms and biofuel kiln retrofit economics to preserve margin structures under tightening federal emissions frameworks.
Market Dynamics
Carbon capture retrofit economics at lime kilns is concentrating capital allocation among Australian producers as TGA-aligned emissions frameworks tighten operational requirements nationwide.
Growth Catalysts
- Western Australian Mining Expansion:Gold and lithium processing circuits are pulling record volumes of high-calcium quicklime into Kalgoorlie and Pilbara refining corridors. Kiln operators are prioritizing metallurgical-grade output to capture this demand surge.
- Queensland Agricultural Amendment Mandates:Sugar cane soil pH correction requirements across the Burdekin and Mackay regions are expanding hydrated lime offtake through cooperative supply contracts. Seasonal application windows are lengthening as climate patterns shift.
- TGA Environmental Compliance Standards:Federal purity specifications for water treatment lime are locking out marginal producers and consolidating procurement toward certified suppliers. Municipal contracts now require documented kiln fuel sourcing and dust emission controls.
Market Restraints
- Natural Gas Price Volatility:Kiln fuel costs constitute the dominant variable in quicklime production economics. Australian east coast gas pricing swings are compressing margin pools for non-integrated operators unable to secure long-term supply agreements.
- Limestone Reserve Concentration:High-grade calcium carbonate deposits cluster along the southern coast and selected Queensland formations. Transport costs from these nodes to remote mining and agricultural demand centers erode competitiveness for regional entrants.
- Alternative Fluxing Agents:Dolomitic lime and synthetic slag conditioners are displacing standard quicklime in select steel refining applications. Substitution pressure intensifies where metallurgical performance tolerances allow material flexibility.
Strategic Opportunities
- Carbon Border Adjustment Preparation:Export-oriented lime producers can front-run EU and Asian carbon tariff implementation by certifying low-emission kiln operations. Biofuel retrofit investments position suppliers for premium pricing into environmentally screened supply chains.
- Hydrated Lime in Water Treatment:Municipal pH stabilization and heavy metals precipitation applications are outpacing construction-grade growth. TGA purity standards are creating a certified-product tier with superior margin capture.
- Rail-Linked Distribution Networks:Bulk logistics integration into Sydney and Melbourne concrete markets enables volume scaling without proportional fleet expansion. Dense terminal networks are compressing delivered cost versus truck-dependent competitors.
Industry Challenges
- Kiln Operator Skill Scarcity:Thermal process engineering expertise required for 900-plus degree limestone calcination is aging out of the workforce. Technical training pipelines have not kept pace with retirement-driven attrition.
- Emissions Monitoring Integration:Continuous kiln exhaust analysis systems must interface with legacy plant control architectures. Retrofit complexity is delaying compliance timelines for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Lime Market |
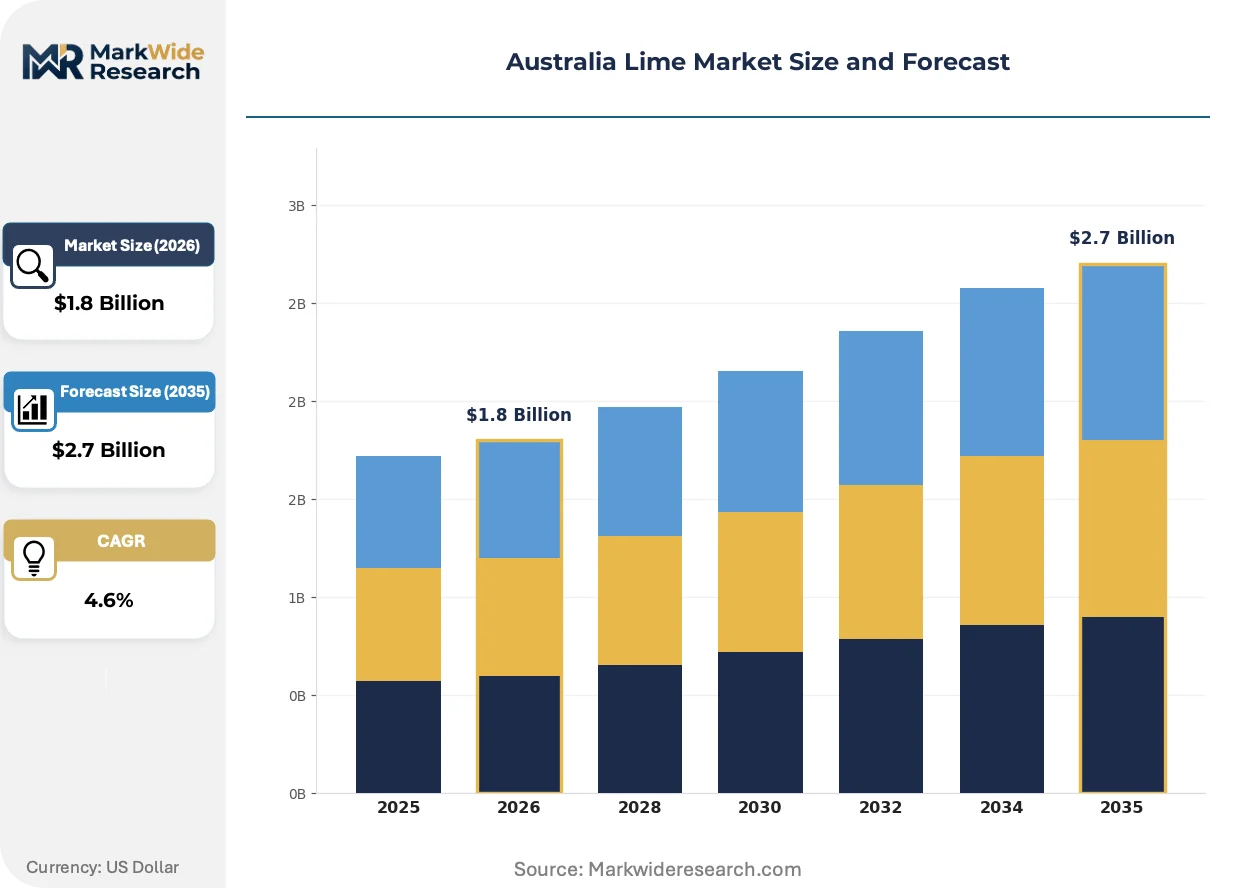
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quicklime, Hydrated Lime, Limestone, Pulverized Lime Application: Construction, Agriculture, Water Treatment, Chemical Manufacturing End User: Food Industry, Environmental Agencies, Mining Sector, Manufacturing Distribution Channel: Online Sales, Direct Supply, Wholesale, Retail |
| Companies Covered | Adelaide Brighton Ltd, Boral Limited, Graymont Limited, Sibelco Australia Limited, Omya Australia Pty Ltd, Lime Group Australia, Wagners, Cockburn Cement Limited, Swan Cement Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Lime Market Emerging Trajectories
Kiln technology and procurement patterns are diverging sharply as Australian lime producers split between carbon-intensive legacy assets and low-emission retrofit pathways.
Calcium looping carbon capture systems are hybridizing traditional rotary kiln operations with post-combustion CO2 separation. Mining sector buyers in Western Australia are specifying low-carbon quicklime for lithium hydroxide production. The technology is compressing allowable emission intensity thresholds in contract specifications.
TGA environmental compliance standards now mandate documented fuel provenance and dust capture efficiency across all lime categories. Procurement officers at municipal water treatment facilities are disqualifying uncertified suppliers from tender processes. High-calcium hydrated lime for potable water applications faces the tightest purity verification requirements.
Long-term offtake contracting is displacing spot market purchases among construction and mining end users. Major concrete producers in Sydney and Melbourne are locking in three-to-five-year supply agreements with rail-linked distributors. Queensland agricultural cooperatives remain the holdout segment, maintaining seasonal spot purchasing for soil amendment applications.
Australia Lime Market Segmentation
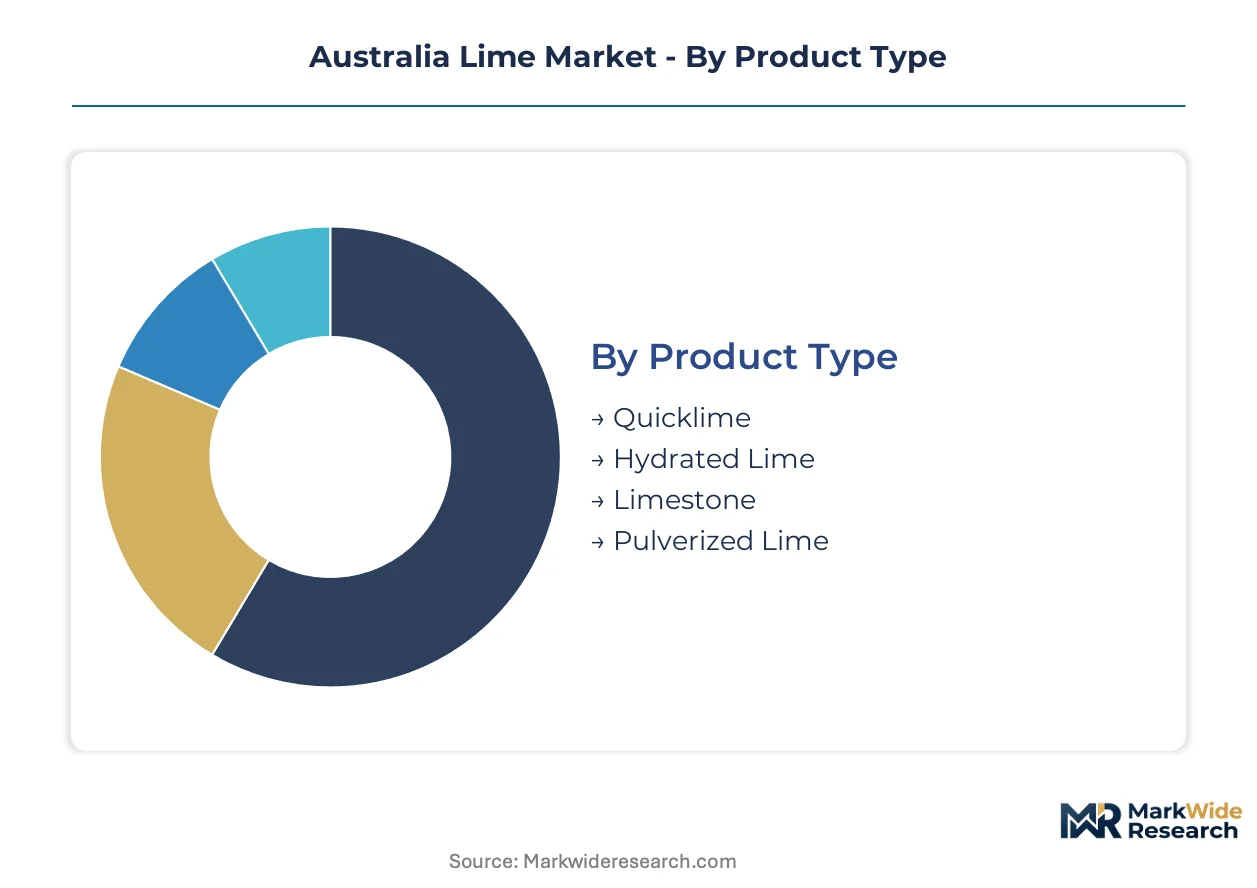
Australian lime producers must align kiln output specifications with distinct purity and reactivity requirements across mining, agricultural, and municipal procurement channels. Product differentiation by calcium oxide content and particle sizing determines contract eligibility for TGA-certified water treatment applications versus standard construction-grade supply.
Product Type:
Use-case spectrum spans metallurgical fluxing requiring 95%+ calcium oxide reactivity through soil amendment applications tolerating broader specification bands.
- Quicklime:Calcium oxide produced at kiln temperatures exceeding 900 degrees Celsius delivers the highest reactivity grade for steel fluxing and gold processing circuits. Western Australian mining operators specify quicklime for lithium hydroxide precipitation and cyanide detoxification in Kalgoorlie refining corridors. TGA emission documentation now accompanies most metallurgical-grade contracts.
- Hydrated Lime:Calcium hydroxide formed through controlled quicklime slaking offers superior handling safety and precise pH modulation for water treatment facilities. Municipal procurement across Queensland and New South Wales is concentrating on certified hydrated lime as TGA purity standards disqualify uncertified kiln output from potable water tenders.
- Limestone:Raw calcium carbonate feedstock serves agricultural pH correction with lower reactivity requirements than calcined products.
- Pulverized Lime:Finely ground limestone accelerates soil neutralization response times in sugar cane districts around Mackay and the Burdekin.
The dominant share belongs to quicklime, while hydrated lime is closing the gap fastest.
Application:
Customer investment cycles vary from three-to-five-year infrastructure contracts through seasonal agricultural purchasing windows.
- Construction:Quicklime stabilizes subgrade soils and accelerates concrete curing in Sydney and Melbourne metropolitan build-outs. Rail-linked distributors capture volume through long-term supply agreements with major concrete producers.
- Agriculture:Soil pH amendment drives hydrated lime consumption across Queensland sugar cane cooperatives where seasonal application patterns are lengthening.
- Water Treatment:TGA-certified hydrated lime precipitates heavy metals and stabilizes municipal pH levels. Purity verification requirements are tightening fastest in this segment.
- Chemical Manufacturing:High-calcium quicklime serves as a chemical reagent in diverse industrial processes with exacting specification demands.
Construction commands the largest volume position, though water treatment exhibits the steepest specification escalation trajectory.
End User:
Procurement sophistication diverges sharply between compliance-driven municipal buyers and price-sensitive agricultural cooperatives.
- Mining Sector:Western Australian gold and lithium processors specify metallurgical-grade quicklime with documented carbon intensity. Contract terms now incorporate emissions thresholds alongside traditional purity metrics.
- Environmental Agencies:TGA-aligned municipal water authorities mandate certified hydrated lime with full kiln fuel provenance documentation.
- Food Industry:Food-grade lime applications require specialized purity certification beyond standard industrial specifications.
- Manufacturing:Steel producers and chemical processors drive consistent bulk demand for standardized quicklime grades.
Mining sector procurement is expanding most quickly, while environmental agency contracting is tightening certification requirements fastest.
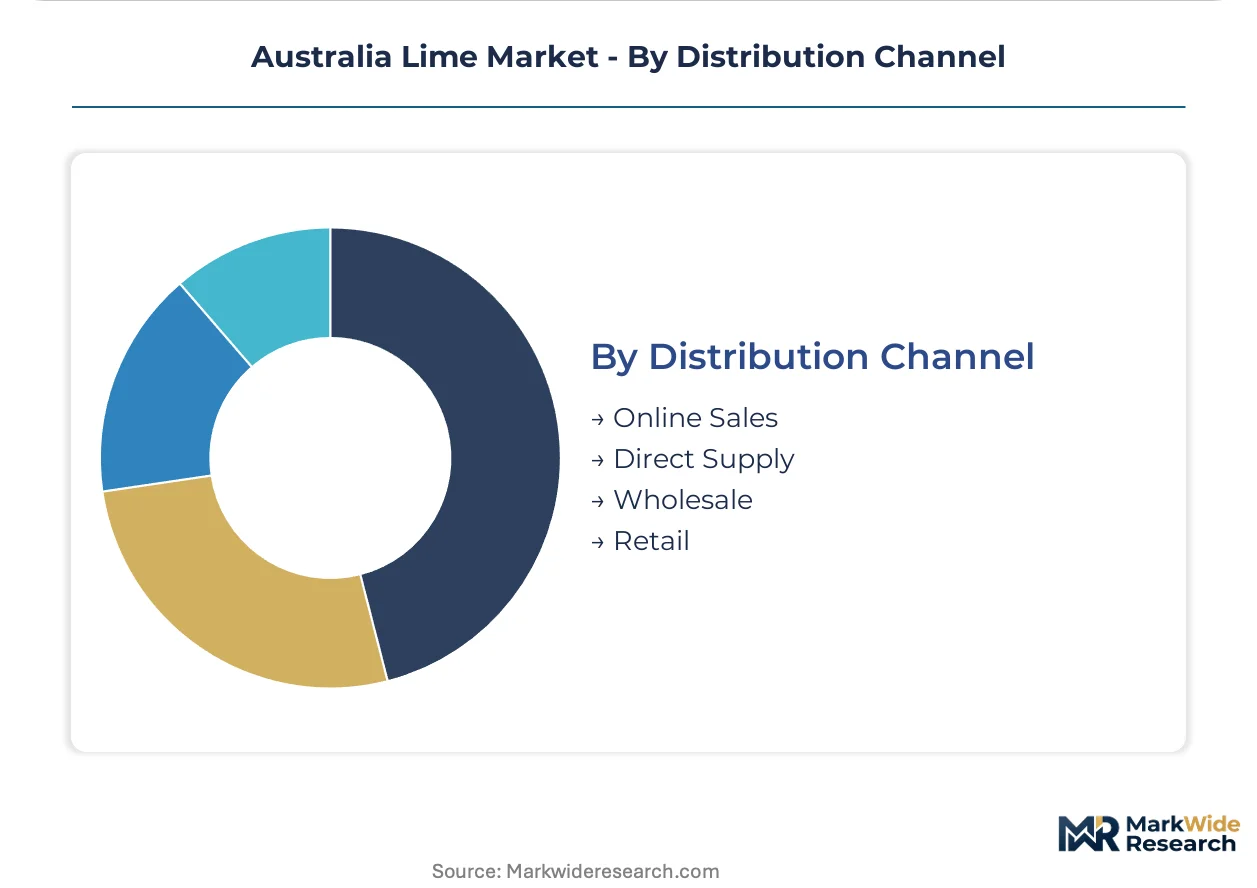
Distribution Channel:
Logistics integration intensity separates capital-intensive rail terminal operators from flexible truck-based competitors.
- Direct Supply:Kiln operators with captive limestone reserves deliver bulk quicklime under long-term offtake agreements to mining and construction end users. Adelaide Brighton's southern coast quarry-to-kiln network exemplifies this model.
- Wholesale:Regional distributors aggregate construction-grade volumes for concrete batching plants across Sydney and Melbourne metropolitan zones.
- Online Sales:Agricultural lime moves through digital platforms serving Queensland farming cooperatives with seasonal spot purchasing patterns.
- Retail:Small-volume hydrated lime for specialty applications reaches end users through building supply merchants.
Direct supply captures the dominant contract value, with wholesale channels gaining share in metropolitan construction markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's lime production flows predominantly to domestic mining and construction sectors, with limited export volumes constrained by high transport costs and concentrated limestone reserve geography. Import dependency remains minimal due to coastal kiln networks serving eastern population centers.
Western Australia
Kalgoorlie gold processors and Pilbara lithium refiners pull metallurgical-grade quicklime through dedicated supply corridors. The state's Environmental Protection Authority enforces dust emission thresholds at kiln operations. Kwinana industrial zone hosts calcination capacity serving both mining fluxing and alumina refining demand.
Queensland
Sugar cane cooperatives across the Burdekin and Mackay regions drive seasonal hydrated lime consumption for soil pH correction. The Department of Environment and Science regulates agricultural lime purity under state biosecurity frameworks. Brisbane-Gladstone logistics corridors channel construction-grade volumes into southeast infrastructure projects.
New South Wales
Sydney metropolitan concrete markets absorb bulk quicklime through rail-linked distribution terminals. The EPA's clean air licensing mandates continuous emissions monitoring at lime kilns. Newcastle industrial corridor maintains calcination assets serving both construction and water treatment procurement.
Victoria
Melbourne construction sector demand stabilizes through long-term supply agreements with major concrete batching networks. WorkSafe Victoria enforces occupational exposure limits at hydrated lime handling facilities. Geelong manufacturing zone processes quicklime for steel fluxing and chemical manufacturing applications.
South Australia
Adelaide Brighton's integrated quarry-to-kiln network along the southern coast anchors regional supply security. The state's Planning Commission oversees limestone extraction licensing under native vegetation protection protocols. Port Adelaide bulk terminals enable cost-competitive distribution into domestic construction markets.
Australia Lime Market Vendor Landscape
On the supply side, the industry is consolidating around integrated producers with captive limestone reserves and coastal kiln positions. Three strategic archetypes dominate: vertically integrated quarry-to-kiln operators, rail-linked metropolitan distributors, and specialized metallurgical-grade suppliers. Competitive moves center on biofuel kiln retrofits for carbon compliance and long-term offtake contracting with mining and construction end users.
Among Australian-based operators, Adelaide Brighton Ltd, Boral Limited, and Graymont Limited exemplify the integrated-reserve archetype. Adelaide Brighton anchors southern coast production networks. Boral occupies metropolitan distribution positioning through dense terminal infrastructure. Graymont represents specialized high-calcium output targeting Western Australian mining circuits. These three firms collectively illustrate how reserve proximity and logistics integration separate sustainable margin pools from truck-dependent regional competitors.
| Leading Market Players |
|---|
| Adelaide Brighton Ltd |
| Boral Limited |
| Graymont Limited |
| Sibelco Australia Limited |
| Omya Australia Pty Ltd |
| Lime Group Australia |
| Wagners |
| Cockburn Cement Limited |
| Swan Cement Limited |
| Others |
Supply Flow & Price Mechanics
Brisbane-Gladstone rail corridors transmit fuel cost volatility directly into delivered quicklime pricing, compressing margins for truck-dependent regional operators while rewarding coastal kiln networks with captive limestone reserves and direct bulk loading access to mining and agricultural demand centers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across Australian lime markets. Three-tier pricing structure across TGA-certified premium, construction-grade standard, and agricultural economy levels separates metallurgical quicklime for Western Australian lithium processors from hydrated lime for municipal water treatment and pulverized limestone for Queensland sugar cooperatives. Cost compression in the standard tier is intensifying as natural gas price swings erode kiln operator margins. Agricultural cooperatives exhibit the highest price sensitivity, while mining sector procurement teams prioritize carbon intensity documentation over unit cost.
Supply Chain Analysis
Tariff exposure between Australian producers and emerging Asian carbon border adjustment regimes dominates supply chain risk planning across the sector. Geographic supply concentrates in coastal Western Australia, South Australia, and Queensland where high-grade calcium carbonate deposits cluster. Production draws from limestone reserves, natural gas fuel inputs, and specialized refractory kiln linings. Single-source vulnerability runs through the Kwinana industrial zone for Pilbara mining fluxing demand. Distribution runs through direct bulk supply agreements for major mining and construction end users, supplemented by wholesale aggregation for metropolitan concrete batching networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon certification and kiln fuel provenance documentation represent the fastest-expanding service-attach layers, outpacing base product margins as TGA-aligned municipal procurement mandates lock in recurring compliance verification revenue streams.
For Market Incumbents: Build captive limestone reserve moats through strategic quarry acquisitions along the southern coast and selected Queensland formations. Secure long-term natural gas supply agreements to insulate kiln operations from east coast pricing volatility. Expand TGA certification capabilities to capture municipal water treatment contracts disqualifying uncertified competitors. Prioritize biofuel kiln retrofit investments to front-run federal emissions framework tightening.
For New Entrants and Emerging Players: Establish a beachhead in Queensland agricultural lime distribution where seasonal spot purchasing patterns and cooperative supply relationships remain fragmented. Target hydrated lime for regional water treatment facilities facing TGA compliance deadlines without captive kiln capacity. Deploy digital procurement platforms to aggregate small-volume agricultural demand across the Burdekin and Mackay districts.
For Investors and Strategic Acquirers: Rail-linked distribution specialists with dense Sydney and Melbourne terminal networks offer the strongest acquisition profile for infrastructure-linked volume scaling. Long-term viability hinges on carbon capture retrofit economics and biofuel transition pathways across the projection horizon. Watch for EU carbon border adjustment implementation timelines as the critical inflection signal for premium pricing into environmentally screened supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Kiln Retrofit | Positions producers for TGA emission thresholds and EU carbon tariff compliance. |
| Backward Integration into Limestone Reserves | Adelaide Brighton's southern coast quarry-to-kiln model demonstrates margin protection. |
| Rail-Linked Distribution Expansion | Boral's dense terminal networks compress delivered cost versus truck-dependent competitors. |
| TGA Certification Investment | Locks out marginal producers from municipal water treatment procurement. |
| Long-Term Offtake Contracting | Mining sector buyers now specify carbon intensity alongside traditional purity metrics. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Australian Bureau of Agricultural and Resource Economics reports, state EPA licensing databases, and TGA regulatory filings. Primary interviews encompassed kiln operations managers at coastal calcination facilities, procurement leads at Western Australian gold and lithium processing circuits, and municipal water treatment contract officers across Queensland and New South Wales. Secondary validation drew from Australian Competition and Consumer Commission bulk supply monitoring reports, customs trade data on lime and limestone flows, and SEC filings of listed construction materials firms. Bottom-up volume modeling triangulated against top-down sectoral demand aggregation.
Forecast inputs span quicklime and hydrated lime grade tiers, mining versus construction versus agricultural end-use industries, and direct supply versus wholesale versus digital distribution channels. CAGRs derive from regression analysis of historical production volumes, capacity utilization rates at major kiln facilities, and projected mining sector expansion corridors. Industry-specific inputs include natural gas price trajectory assumptions and TGA compliance timeline enforcement probability.
Sensitivities concentrate around carbon border adjustment mechanism implementation schedules and biofuel kiln retrofit capital cost trajectories. Forecasts reflect documented assumptions regarding federal emissions framework tightening and mining sector investment cycles. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Tanzania Cashew Market
Agriculture and Agri Products
Fish Feed Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Residential Organic Compost Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Marine Algae Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
North America Compound Feed Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Cambodia Agriculture Market
Agriculture and Agri Products
South America Feed Binders Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Italy Alfalfa Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Post-Harvest Treatment Market