
 Aquatic Feed Ingredients and Products Market | 2026-2036
Aquatic Feed Ingredients and Products Market Size, Share, and Industry Trends Forecast 2026-2036
Aquatic Feed Ingredients and Products Market Analysis
A shortage of qualified aquaculture nutritionists is unwinding capacity expansion at several major compounders. Cargill leverages its integrated oilseed processing network to secure consistent soy protein supply for aquatic formulations. BioMar anchors its competitive position through specialized R&D centers focused on marine species diets. Nutreco competes by controlling distribution channels across Nordic salmon farming regions.
Aquatic feed ingredients and products encompass formulated nutritional inputs designed for fish, shellfish, and other water-cultured species, typically comprising protein meals, lipid sources, carbohydrates, vitamins, and minerals balanced to specific growth-stage requirements. These formulations are manufactured through extrusion, pelleting, or cold-pressing processes to achieve targeted digestibility coefficients and water stability for various culture systems. Pellets and functional feeds command premium positioning as aquaculture intensification drives demand for species-specific nutrition that minimizes feed conversion ratios. Fish meal retains structural importance in marine carnivore diets even as algae and soy protein formulations gain share in omnivorous species segments.
EFSA establishes maximum residue limits and feed safety standards that constrain ingredient portfolios across European aquaculture supply chains. REACH chemical registration requirements affect novel additive introductions including alternative protein sources and functional micronutrients. The EU Green Deal's Farm to Fork strategy tightens sustainability criteria for marine-derived raw materials, reshaping procurement patterns for fish meal and oil. Stakeholders must monitor evolving certification schemes and ingredient traceability mandates that will determine market access for feed compounders and their supplier networks.
Market Dynamics
Intensification of aquaculture operations in Southeast Asia and the EU Green Deal's sustainability mandates are restructuring ingredient sourcing priorities toward certified marine and plant-based alternatives.
Growth Catalysts
- Fish meal substitution protocols:Formulators are accelerating algae protein and insect meal adoption to reduce dependency on wild-capture marine inputs. Vietnam's Mekong Delta intensive shrimp clusters drive species-specific complete feed demand.
- EU Green Deal Farm to Fork strategy:Sustainability criteria tightening for marine-derived raw materials redirects procurement toward certified supply chains. European salmon farming regions now require full traceability documentation.
- Precision nutrition technologies:Computer-formulated extrusion processes optimize digestibility coefficients for carnivorous marine species. Automated feeding systems in Norwegian fjord operations enable real-time diet adjustment.
Market Restraints
- Fish oil price volatility:Peruvian anchovy harvest fluctuations transmit directly to omega-3 concentrate costs for marine broodstock diets.
- Soy protein supply concentration:North American oilseed processing infrastructure limits alternative origin diversification for high-volume aquatic formulations.
- REACH registration barriers:Novel alternative protein sources and functional micronutrients face extended chemical safety assessment timelines before EU market entry.
Strategic Opportunities
- Indonesian archipelago expansion:Underdeveloped mariculture zones in Sulawesi and Maluku present greenfield sites for integrated feed mill and grow-out operations.
- Recirculating aquaculture system (RAS) feed specialization:Closed-loop salmon and trout facilities require distinct nutritional matrices with modified phosphorus excretion profiles.
- EU CSRD reporting alignment:Sustainability disclosure mandates create premium positioning for feed compounders with verified Scope 3 emission reductions across ingredient networks.
Industry Challenges
- Aquaculture nutritionist scarcity:Qualified formulators capable of balancing amino acid profiles for tropical marine species remain concentrated at established R&D centers.
- Multi-certification complexity:Simultaneous ASC, BAP, and organic compliance requires parallel documentation systems that extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquatic Feed Ingredients and Products Market |
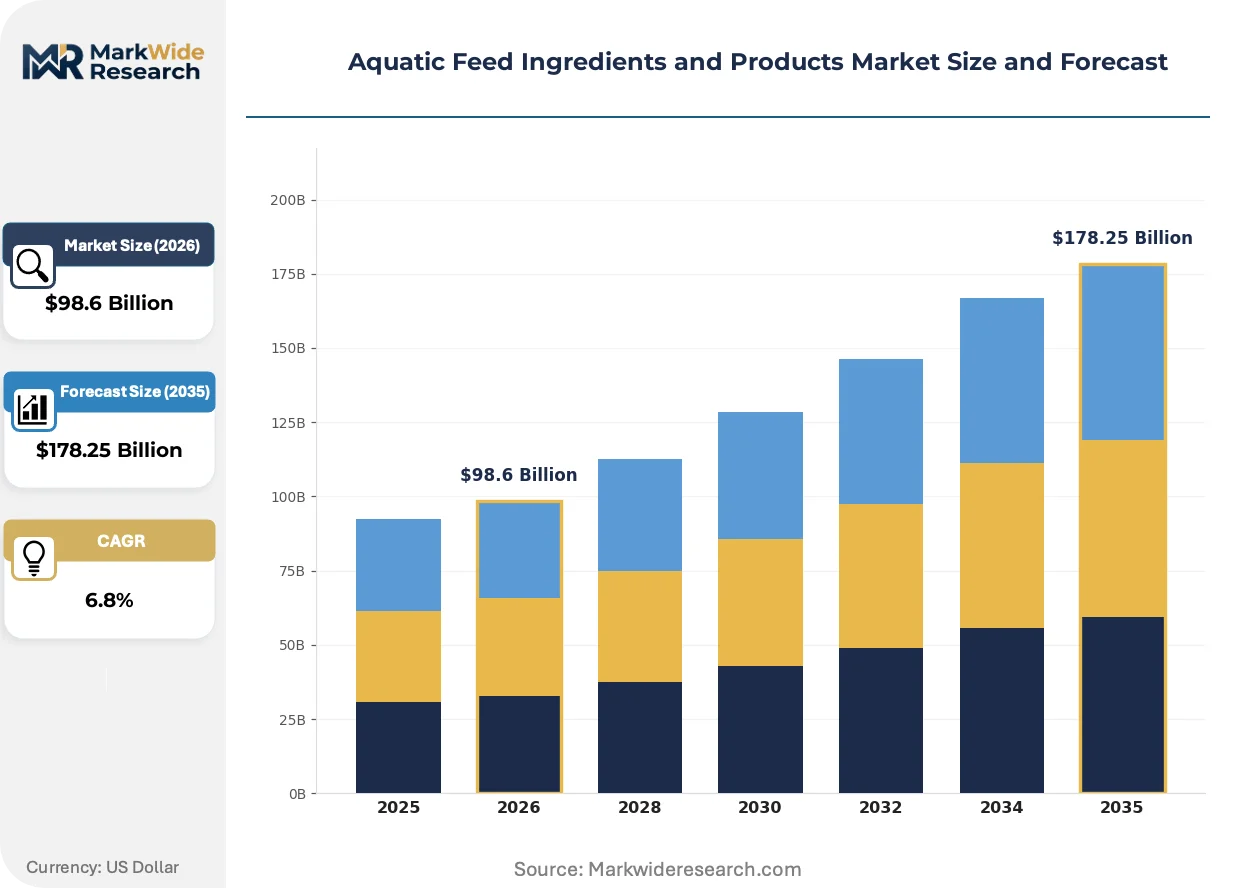
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Meal, Crumbles, Granules Ingredient Type: Fish Meal, Soy Protein, Wheat Gluten, Algae Formulation: Complete Feed, Supplementary Feed, Functional Feed, Custom Formulations End User: Aquaculture Farms, Fish Hatcheries, Recreational Fishing, Research Institutions |
| Companies Covered | Cargill, BioMar, Alltech, Archer Daniels Midland, Nutreco, Ridley, BASF, DSM, Evonik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquatic Feed Ingredients and Products Market Emerging Trajectories
Formulation science is converging with digital agriculture and alternative protein biotechnology to redefine nutritional performance benchmarks across marine and freshwater culture systems.
Single-cell protein derived from methane-oxidizing bacteria is miniaturizing the minimum viable scale for on-site feed ingredient production. Norwegian salmon integrators are piloting containerized bioreactor units at individual farm sites. This distributed manufacturing model is compressing transportation costs and cold-chain requirements for high-value marine grower diets.
REACH chemical registration requirements are constraining novel additive introductions across European aquaculture supply chains. EFSA maximum residue limits now cover previously unregulated functional micronutrient classes. Marine carnivore feed compounders are reformulating to pre-registered ingredient portfolios while awaiting novel substance approvals.
Buyer consolidation among Vietnamese and Thai integrated shrimp operators is shifting procurement toward long-term offtake agreements with volume-tiered pricing. Smallholder cooperatives are losing direct supplier relationships as processing-scale feed mills consolidate distribution channels. This concentration is most visible in the Mekong Delta, where three compounders now control bulk complete feed supply to intensive pond clusters.
Aquatic Feed Ingredients and Products Market Segmentation
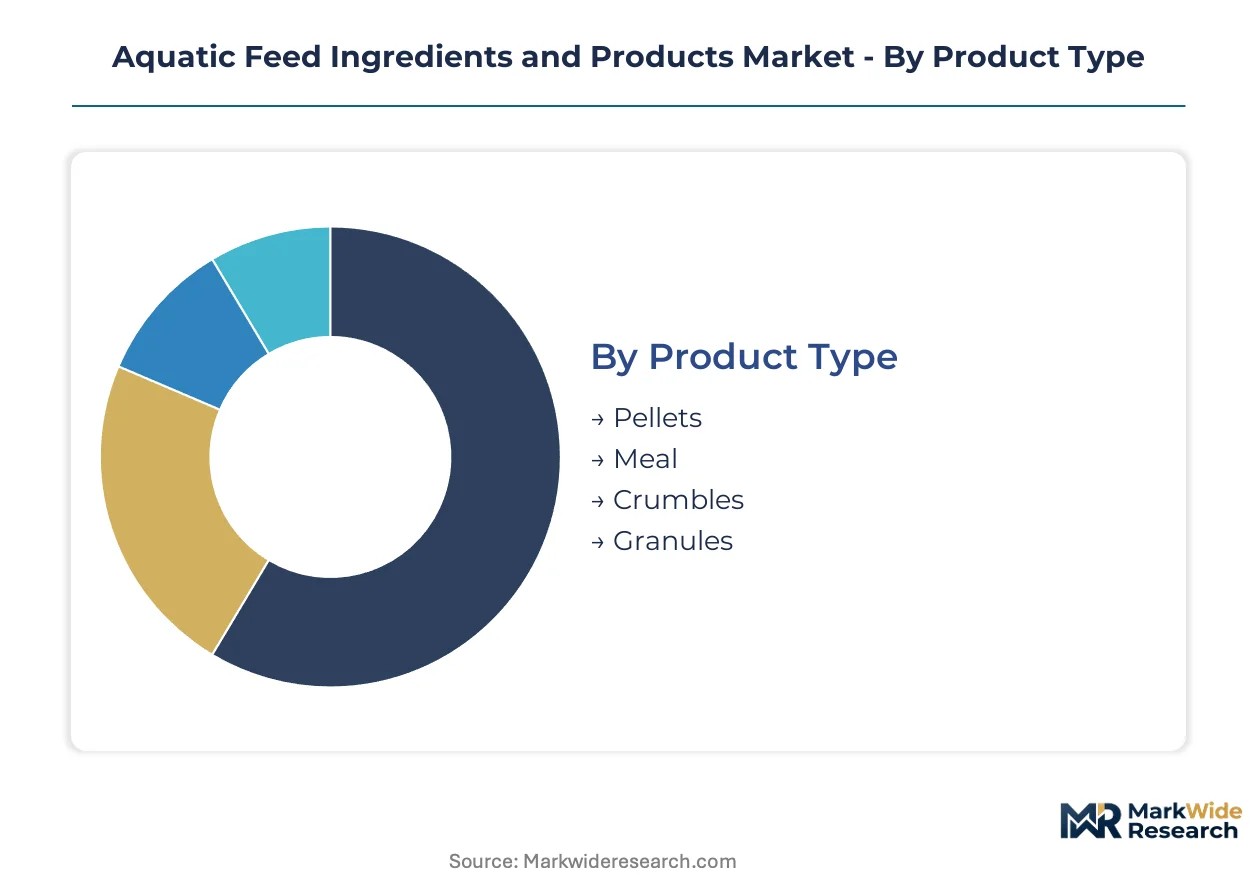
Aquatic feed segmentation reflects divergent regulatory pressures across protein sourcing, formulation complexity, and end-use certification requirements. Each category maps distinct technical specifications to species-specific nutritional mandates and geographic production clusters.
Product Type:
EFSA water stability standards and species-specific feeding behaviors differentiate physical form requirements across European and Southeast Asian aquaculture operations.
- Pellets:Extruded cylindrical formulations with controlled buoyancy profiles for salmonids and marine finfish. Norwegian fjord operations and Vietnamese shrimp ponds drive specification divergence toward sinking versus floating variants.
- Meal:Ground powder feeds for larval stages and filter-feeding species requiring high surface-area nutrient absorption. Demand concentrates at Mediterranean seabass hatcheries and Indonesian milkfish nurseries constrained by particle size distribution mandates.
- Crumbles:Intermediate particle size for juvenile transition diets.
- Granules:Compressed slow-sinking forms for bottom-feeding carp and catfish species.
Established volume favors Pellets; emerging adoption favors Crumbles as weaning protocols extend across more species.
Ingredient Type:
Cost tier stratification separates commodity proteins from premium functional inputs, with certification premiums widening spread between origin-verified and conventional supplies.
- Fish Meal:Peruvian anchovy and North Atlantic reduction fisheries supply high-digestibility protein with complete amino acid profiles for marine carnivore diets. EU Green Deal traceability requirements are restructuring procurement toward Marine Stewardship Council-certified origins, concentrating demand among Scottish and Norwegian salmon integrators.
- Soy Protein:Dehulled, toasted, and extruded oilseed meal providing cost-efficient amino acid balance for omnivorous species. Brazilian and US Gulf Coast crushing capacity anchors supply for Southeast Asian shrimp compounders facing deforestation-free sourcing mandates.
- Wheat Gluten:European milling byproduct with binding properties for extruded feed durability.
- Algae:Photosynthetic and fermentation-derived proteins offering omega-3 and pigmenting carotenoids for high-value marine species.
Cost efficiency favors Soy Protein; functional premium positioning favors Algae as DHA enrichment requirements tighten.
Formulation:
Customer maturity and technical capability determine whether operations procure turnkey nutrition or self-blend ingredient streams.
- Complete Feed:Fully balanced diets delivering all required nutrients in single-product form. Vietnamese Mekong Delta intensive shrimp clusters and Chilean salmon sea sites drive specification toward species-life-stage precision with guaranteed analysis certificates.
- Supplementary Feed:Partial nutrition inputs requiring on-farm blending with locally available ingredients. Smallholder cooperatives in Bangladesh and Nigeria rely on these lower-cost options despite variable conversion efficiency.
- Functional Feed:Enhanced formulations with probiotics, immunostimulants, or pigment precursors for specific performance outcomes.
- Custom Formulations:Bespoke diets compounded to individual farm specifications for unique water chemistry or genetic lines.
Scale concentration favors Complete Feed; performance differentiation favors Functional Feed as disease pressure intensifies.
End User:
Volume scale and technical sophistication create distinct procurement patterns across production-oriented and non-commercial demand segments.
- Aquaculture Farms:Commercial grow-out operations purchasing bulk complete feeds through volume-tiered contracts. Indonesian and Ecuadorian shrimp producers dominate procurement with consolidated offtake agreements.
- Fish Hatcheries:Specialized larval and broodstock nutrition requiring micronutrient precision and live feed substitutes. Mediterranean and Japanese seed production facilities drive demand for artemia replacement formulations.
- Recreational Fishing:Small-quantity ornamental and sport fish feed purchases.
- Research Institutions:Experimental diets with defined composition for nutritional studies.
Commercial volume favors Aquaculture Farms; technical specification intensity favors Fish Hatcheries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between European salmon integrators demanding traceability-certified marine inputs and Southeast Asian shrimp operators prioritizing volume-scaled complete feeds. Norwegian fjord operations source through Marine Stewardship Council-verified supply chains. Vietnamese Mekong Delta clusters procure through consolidated compounder networks.
Norway
Atlantic salmon broodstock diets drive demand for fish oil concentrates with guaranteed omega-3 profiles. The country's national food safety authority enforces strict maximum residue limits on feed additives. Bergen and Trondheim host specialized R&D centers developing precision extrusion technologies for fjord-based grow-out sites.
Vietnam
Intensive whiteleg shrimp ponds in the Mekong Delta consume bulk complete feeds through volume-tiered procurement contracts. The Ministry of Agriculture and Rural Development implements traceability mandates for export-oriented aquaculture. Can Tho and An Giang provinces concentrate feed mill capacity serving consolidated pond clusters.
Indonesia
Napoleon wrasse and grouper mariculture expansion in Sulawesi and Maluku creates demand for high-performance grower diets. The national standardization agency enforces halal certification requirements for feed ingredients entering domestic supply chains. Makassar anchors distribution networks for eastern archipelago grow-out operations.
United States
Catfish pond operations in the Mississippi Delta and RAS trout facilities in Idaho drive divergent formulation requirements. The Food and Drug Administration regulates medicated feed claims and veterinary feed directives. Auburn, Alabama hosts university-linked research programs advancing channel catfish nutrition protocols.
Chile
Pacific salmon sea sites in the Los Lagos and Aysén regions require species-specific diets with optimized feed conversion ratios. The national fisheries service encloses sanitary regulations governing pathogen-free feed production. Puerto Montt concentrates compounder blending facilities serving southern fjord concessions.
Aquatic Feed Ingredients and Products Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in aquatic feed manufacturing. The upper tier controls oilseed processing infrastructure and marine ingredient supply chains. The specialist tier concentrates on species-specific formulation R&D and regional distribution networks. Dominant competitive moves include backward integration into alternative protein cultivation and geographic expansion through joint venture feed mill construction.
Among integrated agribusiness conglomerates, Cargill and Archer Daniels Midland exemplify the oilseed-processing archetype with captive soy protein supply for aquatic formulations. Nutreco occupies a position within the specialized nutrition tier, anchoring competitive presence across Nordic salmon farming regions through distribution channel control. BioMar represents the marine species specialist archetype, with R&D center investments supporting differentiated positioning in high-value carnivore diets.
| Leading Market Players |
|---|
| Cargill |
| BioMar |
| Alltech |
| Archer Daniels Midland |
| Nutreco |
| Ridley |
| BASF |
| DSM |
| Evonik |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for Peruvian fish meal anchor pricing power among Southeast Asian compounders while compressing margin buffers for European buyers facing EFSA traceability mandates. This lead-time asymmetry concentrates procurement leverage with vertically integrated oilseed processors and marine reduction-fishery operators.
Pricing Analysis
Long-term offtake agreements dominate Vietnamese shrimp feed procurement, with volume-tiered contracts separating integrated pond operators from spot-market-dependent smallholders. Price differentiation rests on Marine Stewardship Council certification premiums and deforestation-free soy verification. Cost compression in standard-grade formulations is intensifying as Indonesian and Ecuadorian buyers consolidate purchasing. Smallholder cooperatives exhibit highest price sensitivity, while Norwegian salmon integrators absorb premium tiers for omega-3 guaranteed profiles.
Supply Chain Analysis
Port congestion at Callao and container tightness on Asia-Pacific trade lanes elevate inbound logistics costs for Peruvian fish meal destined for Mekong Delta feed mills. Raw material supply concentrates in Peru, Brazil, and Vietnam, drawing from anchovy reduction fisheries, soy crushing complexes, and domestic rice bran streams. Single-source vulnerability runs through Peruvian anchovy harvest fluctuations. Distribution runs through compounder-owned silo networks and third-party aquafeed distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aquatic feed formulation is approaching a platform-economics inflection as precision nutrition protocols and automated feeding systems demand interoperable data standards across Norwegian fjord operations and Vietnamese pond clusters.
For Market Incumbents: Secure backward integration into algae protein cultivation to deflect fish oil price volatility, while anchoring channel control through exclusive distribution agreements in Indonesia's underdeveloped Sulawesi mariculture zones. Certification investment in ASC and BAP parallel documentation systems extends product development cycles but locks out regional challengers. For New Entrants and Emerging Players: Custom formulation services for recirculating aquaculture system operators represent a service-layer gap where incumbents under-serve phosphorus-excretion-optimized diet requirements. Target Indonesian Napoleon wrasse and grouper hatcheries with artemia replacement formulations. Partner with university-linked research programs for technical credibility. For Investors and Strategic Acquirers: Long-term, this sits as a nutrition-platform play because species-specific precision feeds will consolidate around data-integrated compounders controlling both formulation IP and farm-level feeding automation. Acquisition candidates include single-cell protein bioreactor specialists and regional feed mill operators with halal certification infrastructure in Indonesia. Monitor REACH registration timelines for novel alternative proteins as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Proteins | Algae and insect meal cultivation secures supply against Peruvian anchovy harvest volatility. |
| RAS Feed Specialization | Phosphorus-optimized formulations address closed-loop salmon and trout facility requirements. |
| Joint Venture Feed Mill Construction | Greenfield sites in Sulawesi and Maluku capture Indonesian mariculture expansion. |
| CSRD Reporting Alignment | Verified Scope 3 emission reductions position compounders for EU sustainability premiums. |
| Precision Nutrition Technology Investment | Computer-formulated extrusion processes optimize digestibility for carnivorous marine species. |
Methodological Framework
The analysis maps fish meal, soy protein, algae, and functional additive sub-sectors, each validated through compounder procurement directors, aquaculture nutritionists, and marine ingredient traders. Primary interviews with feed mill operations managers and integrated shrimp farm executives combined with secondary validation from customs trade data, FAO aquaculture production statistics, EFSA feed safety registers, and SEC filings of listed agribusiness conglomerates. Bottom-up volume estimates and top-down value triangulation cross-checked against regional production cluster data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product physical form, ingredient protein source, formulation completeness tier, and end-user operational scale. CAGRs derived from trend extrapolation of species-specific feed conversion ratio improvements and aquaculture intensification rates. Forecast inputs incorporated EU Green Deal procurement shift timelines and Indonesian mariculture zone development permits.
Underlying assumptions cover sustained aquaculture intensification in Southeast Asia and REACH registration progression for novel proteins, with deviation risk concentrated in Peruvian anchovy biomass assessments and EU sustainability mandate enforcement pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Organic Feed Market
Agriculture and Agri Products
Asia-Pacific Chaga Mushroom Market
Agriculture and Agri Products
Sophora Japonica Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Argentina Compound Feed Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Greenhouse Horticulture Market
Agriculture and Agri Products
Inulin Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
France Alfalfa Hay Market