
 Mushroom Substrate Market | 2026-2036
Mushroom Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Mushroom Substrate Market Analysis
Automated pasteurization and controlled-environment spawning is tilting substrate production toward precision agriculture protocols. Italspawn leverages vertical integration from spawn to finished substrate to control quality consistency across European supply chains. Mycelia BV anchors its position through specialized mycelium propagation services that sustain high-yield contracts with industrial mushroom farms. North Spore differentiates via direct-to-grower e-commerce channels that compete with traditional agricultural distributors.
Mushroom substrate comprises lignocellulosic material—typically hardwood chips, straw, or sawdust—supplemented with nitrogen sources and conditioned to specific moisture content, typically 60-75 percent, to support mycelial colonization. Its primary commercial purpose is to provide a standardized, contaminant-resistant growth medium that converts agricultural waste into edible fungal biomass. Hardwood-based formulations lead among specialty mushroom growers due to superior lignin degradation support, while bagged substrate dominates commercial channels because pre-sterilized packaging reduces contamination risk and labor overhead. Pelletized forms represent the fastest-expanding segment as automated filling systems displace manual block preparation in large-scale operations.
The EU Green Deal and REACH framework restrict peat extraction and chemical additives, compelling reformulation toward straw and agricultural byproduct bases. The USDA and EPA jointly influence North American substrate standards through organic certification requirements and agricultural runoff regulations that govern composting facility permits. Stakeholders must monitor evolving composting emissions rules and mycotoxin testing protocols, as regulatory stringency in substrate composition will determine which suppliers retain market access.
Market Dynamics
Automated pasteurization systems and controlled-environment spawning are consolidating substrate production around precision agriculture protocols, compressing batch-to-batch variability while elevating capital requirements for new entrants.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants in climate-controlled growing facilities accelerates retrofit demand for substrate operations with closed-loop heat recovery systems.
- Food service procurement:Large-scale restaurant chains and meal-kit distributors are contracting directly with mushroom farms, bypassing wholesale produce markets and creating volume commitments for standardized substrate blocks.
- Hardwood chip conditioning:Advanced steam-explosion pretreatment of lignocellulosic feedstock reduces colonization time by improving cellulose accessibility for Pleurotus and Lentinula species.
Market Restraints
- Peat supply concentration:Baltic states and Ireland control premium horticultural peat extraction, exposing European formulators to supply quotas under the EU Green Deal's wetland restoration mandates.
- Energy cost volatility:Natural gas and electricity price spikes in Germany and the Netherlands directly inflate pasteurization and climate-control operating expenses for substrate production facilities.
- Contamination biology:Trichoderma green mold and bacterial blotch persist as endemic threats requiring continuous facility sterilization protocols that consume labor and chemical inputs.
Strategic Opportunities
- Poland capacity expansion:Lower land and energy costs relative to Western Europe attract substrate producers serving Central European mushroom farming clusters with road freight distribution advantages.
- Organic certification tailwind:USDA National Organic Program and EU organic regulation create price premiums for substrate formulations excluding synthetic nitrogen supplements and chemical pasteurization aids.
- Direct-to-grower e-commerce:Web-based substrate sales with technical support content bypass agricultural distributor markups and capture margin from hobbyist and small commercial cultivators.
Industry Challenges
- Mycology technician scarcity:Specialized skills in spawn quality assessment and contamination diagnostics command wage premiums that strain mid-scale operations competing for talent with pharmaceutical fermentation facilities.
- Composting permit timelines:EPA and state environmental agency approval processes for new aerobic composting facilities extend 18-36 months, delaying capacity expansion in North American markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mushroom Substrate Market |
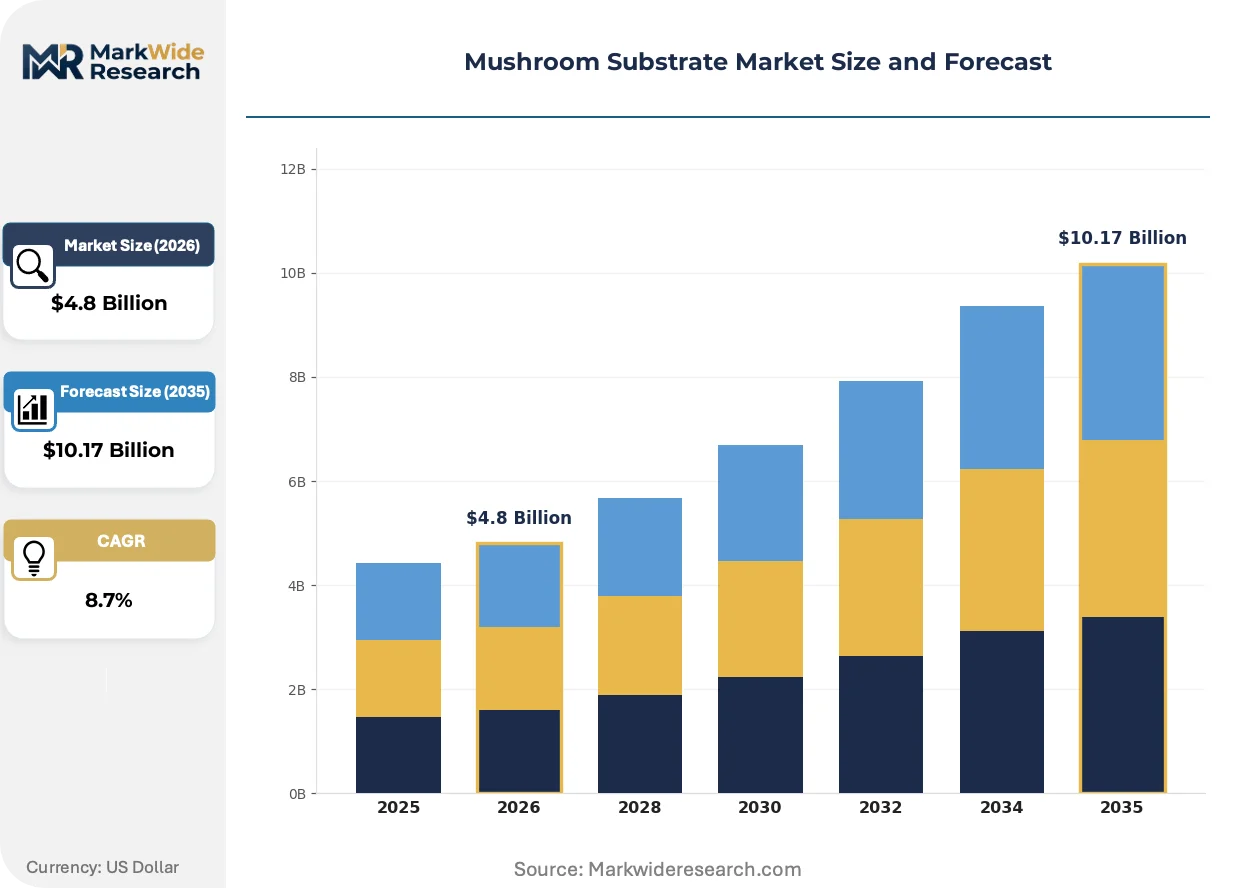
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardwood, Straw, Soil, Sawdust Form: Block, Pellets, Bagged, Loose Component: Nutrients, Additives, Inoculants, Moisture Retention Agents Use Case: Commercial Cultivation, Home Gardening, Research, Teaching |
| Companies Covered | Italspawn, Mycelia BV, Amycel Spawn, JSC Ramundas, Anyang Gemco Energy Machinery Co., Ltd, North Spore, Weimar Enterprise Sdn Bhd., Baltic Wood Service, Hirano Mushroom LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mushroom Substrate Market Emerging Trajectories
Sensor networks and algorithmic climate control are transforming substrate production from craft-based batch processing to data-driven manufacturing with predictable output specifications.
Near-infrared spectroscopy combined with machine vision is digitizing moisture content and contamination detection during substrate conditioning. Large Pleurotus farms in the Netherlands and Germany are deploying these systems to replace manual sampling. Real-time quality feedback loops compress variation in mycelial colonization rates and reduce downstream crop failure risk.
REACH chemical restrictions and the EU Green Deal's peat extraction limits are compelling reformulation toward straw, cottonseed hull, and agricultural byproduct bases. Formulators are investing in enzymatic pretreatment research to match hardwood-based performance without prohibited additives. Specialty mushroom growers in Belgium and northern France face the steepest compliance transitions due to legacy peat-dependent supply contracts.
Buyer consolidation among vertically integrated mushroom farms is compressing distributor margins and demanding technical service bundling with substrate supply. Traditional agricultural distributors in Germany and Poland are responding with in-house mycology support staff and just-in-time delivery contracts. This pattern concentrates procurement volume with suppliers capable of spawn-to-substrate integration and post-sale crop consulting.
Mushroom Substrate Market Segmentation
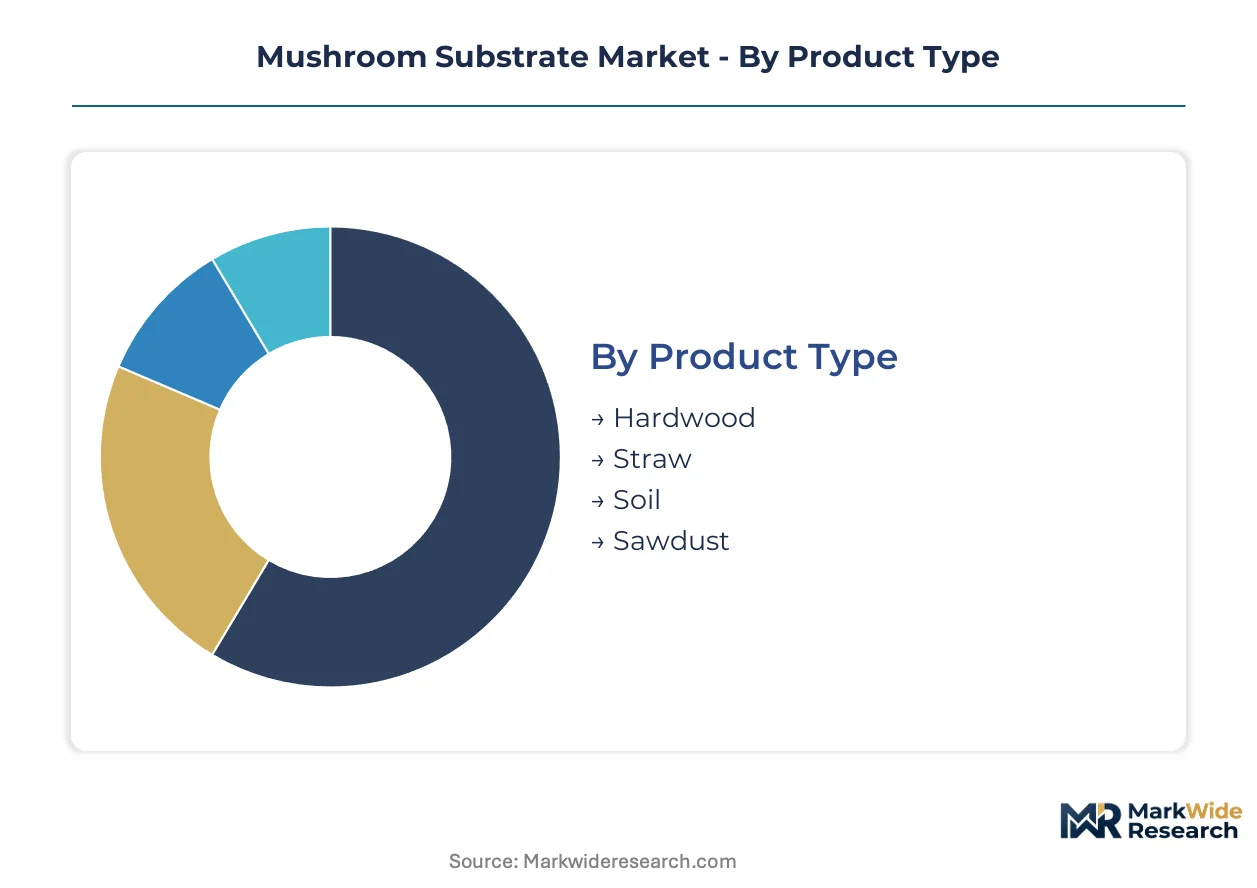
Substrate segmentation determines procurement economics and cultivation outcomes across mushroom operations. Formulation choices directly influence colonization speed, contamination resistance, and compatibility with automated handling systems.
Product Type:
Mature formulations dominate commercial volume while emerging alternatives respond to regulatory pressure on peat extraction.
- Hardwood:Lignin-rich chips and sawdust from oak, beech, and maple support superior degradation by white-rot fungi. Pleurotus and Lentinula farms in Germany and the Netherlands specify hardwood for its structural integrity during extended colonization cycles.
- Straw:Wheat and rice straw formulations offer lower cost per cubic meter and align with EU Green Deal peat reduction mandates. Polish Agaricus operations are converting straw-dominant blends to secure organic certification premiums under EU regulation.
- Soil:Peat-based and peat-reduced variants retain moisture for casing layers in Agaricus bisporus production. Baltic supply quotas under wetland restoration programs constrain availability for Belgian and Dutch formulators.
- Sawdust:Fine-particle softwood and hardwood residues accelerate spawn run in automated bagging systems. Sawdust concentrates in pelletized substrate manufacturing for shiitake and reishi cultivation.
Hardwood handles the majority of throughput; straw is gaining share fastest on regulatory tailwinds.
Form:
Cost tier separation runs from labor-intensive loose material to capital-intensive precision formats.
- Block:Compressed and wrapped substrate cylinders suit manual handling at small-to-mid scale farms. Blocked formulations dominate teaching and research applications where batch traceability matters.
- Pellets:Densified feedstock enables automated filling, hydration, and sterilization in continuous production lines. Pelletized substrates are expanding most quickly as Dutch and German Pleurotus farms retrofit conveyor-based spawning systems.
- Bagged:Pre-sterilized sealed bags reduce contamination risk and labor overhead for commercial cultivators. Bagged substrate commands price premiums in direct-to-grower channels serving hobbyist and specialty markets.
- Loose:Bulk unpackaged material minimizes packaging cost for on-site pasteurization operations. Loose substrate concentrates in large Agaricus farms with captive composting and conditioning infrastructure.
Bagged substrate anchors commercial procurement; pellets show the steepest expansion trajectory on automation adoption.
Component:
Application specificity determines margin structure across functional additives.
- Nutrients:Nitrogen supplements including soybean meal and ammonium sulfate accelerate mycelial biomass accumulation. Nutrient-dense formulations target high-yield contracts with vertically integrated mushroom farms.
- Additives:pH buffers, gypsum, and lime adjust substrate chemistry for species-specific requirements. Additive packages differentiate premium substrates from commodity blends in German distributor catalogs.
- Inoculants:Spawn-compatible carrier materials and pre-colonized supplements reduce time-to-fruiting. Inoculant integration is climbing fastest as spawn suppliers backward-integrate into finished substrate production.
- Moisture Retention Agents:Vermiculite, perlite, and biochar variants maintain 60-75 percent water content through fruiting cycles. Retention agents concentrate in bagged and block formats for shipping stability.
Nutrients drive formulation cost; inoculants are expanding most quickly on spawn-to-substrate integration.
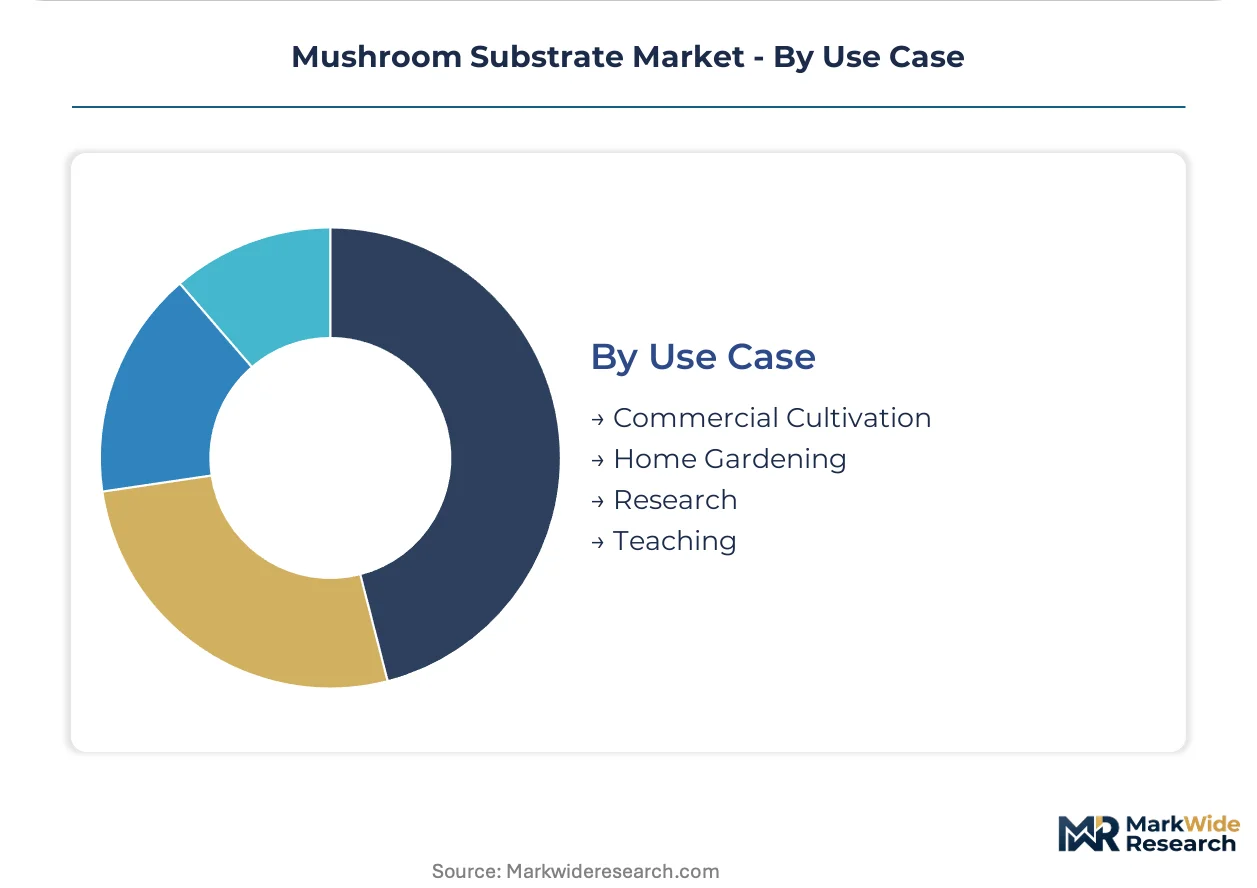
Use Case:
Customer type stratification separates volume procurement from technical service intensity.
- Commercial Cultivation:Large-scale Agaricus, Pleurotus, and specialty mushroom farms demand standardized, contaminant-resistant substrates with just-in-time delivery. Commercial buyers in Poland and the Netherlands contract directly with integrated spawn-to-substrate suppliers.
- Home Gardening:Hobbyist cultivators purchase small-batch bagged substrates through e-commerce and specialty retail. Home gardening channels support margin capture from technical content and grow-kit bundling.
- Research:Universities and agricultural institutes require certified, traceable substrates for reproducible experimental protocols. Research procurement prioritizes batch documentation over unit cost.
- Teaching:Educational institutions source simplified, contamination-forgiving formulations for classroom demonstration. Teaching demand concentrates in agricultural extension programs and vocational training centers.
Commercial cultivation commands absolute volume; home gardening is climbing fastest on direct-to-grower channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands exports sterilized substrate blocks to German and Polish mushroom farms, establishing a north-south trade corridor that concentrates value-added processing in the Low Countries while cultivation spreads eastward.
Germany
Industrial Pleurotus farms in Lower Saxony and Bavaria drive demand for hardwood-chip substrates with precise moisture calibration. The F-Gas Regulation forces climate-controlled facilities to retrofit heat recovery systems, raising capital requirements for substrate storage operations. The Münsterland cluster anchors production, where Italspawn operates integrated spawn-to-substrate facilities serving contract growers.
Netherlands
Automated pelletizing systems and conveyor-based spawning lines concentrate in North Brabant, where labor costs justify capital-intensive precision manufacturing. REACH chemical restrictions block peat-based additives, compelling formulators toward straw-dominant blends with enzymatic pretreatment. The Westland horticulture belt hosts Mycelia BV's mycelium propagation services that underpin high-yield supply contracts.
Poland
Lower land and energy costs relative to Western Europe attract substrate producers targeting Central European mushroom farming clusters. Polish Agaricus operations convert toward straw-based formulations to secure organic certification premiums under EU regulation. The Greater Poland Voivodeship anchors regional consumption, with road freight distribution reaching farms across the German border within hours.
United States
Specialty mushroom growers in Pennsylvania and California source bagged substrates through direct-to-grower e-commerce channels that bypass agricultural distributor markups. The USDA National Organic Program and EPA composting facility permits jointly shape formulation standards and capacity expansion timelines. The Kennett Square area in southeastern Pennsylvania maintains dense Agaricus cultivation, though substrate production increasingly shifts to Midwestern composting operations.
Belgium
Legacy peat-dependent supply contracts create compliance friction as the EU Green Deal's wetland restoration mandates constrain Baltic extraction quotas. Belgian formulators face steep reformulation costs toward agricultural byproduct bases without synthetic nitrogen supplements. The Flanders mushroom belt between Mechelen and Leuven concentrates casing layer demand, where regional suppliers negotiate just-in-time delivery contracts with vertically integrated farms.
Mushroom Substrate Market Vendor Landscape
On the supply side, the industry is consolidating around integrated spawn-to-substrate operators capable of quality consistency across European supply chains. Three archetypes define competitive positioning: vertically integrated propagators controlling mycelium genetics, precision formulators with automated conditioning lines, and direct-to-grower distributors capturing hobbyist margin. Dominant competitive moves include backward integration into spawn production and geographic expansion into lower-cost Central European manufacturing nodes.
Among European propagators, Italspawn and Mycelia BV exemplify the integrated archetype, with the former leveraging captive spawn production and the latter anchoring position through specialized mycelium services. North Spore occupies a distinct channel position, representing the direct-to-grower vector that competes with traditional agricultural distributors through web-based technical content bundling. These three companies illustrate how quality control, service intensity, and route-to-market differentiation segment competitive terrain without requiring scale parity.
| Leading Market Players |
|---|
| Italspawn |
| Mycelia BV |
| Amycel Spawn |
| JSC Ramundas |
| Anyang Gemco Energy Machinery Co., Ltd |
| North Spore |
| Weimar Enterprise Sdn Bhd. |
| Baltic Wood Service |
| Hirano Mushroom LLC |
| Others |
Supply Flow & Price Mechanics
The Münsterland cluster in northwest Germany anchors European substrate production capacity, where Italspawn's integrated spawn-to-substrate facilities translate captive mycelium genetics into pricing power over contract growers in Lower Saxony and Bavaria. This geographic concentration of precision conditioning infrastructure allows formulators with automated pasteurization lines to command premiums for standardized, contaminant-resistant blocks while straw-dependent competitors in Poland compete on unit cost for organic-certified Agaricus operations.
Pricing Analysis
Next-generation enzymatic pretreatment substrates command 15-25% premiums over conventional steam-explosion formulations, while legacy peat-based casing layers face price erosion under EU Green Deal extraction quotas. Three-tier pricing structure across premium certified-organic, standard commercial-grade, and economy bulk-loose levels separates buyers by contamination-risk tolerance and automation compatibility. Cost compression in the standard tier intensifies because energy price spikes in Germany and the Netherlands inflate pasteurization operating expenses. Hobbyist cultivators purchasing through direct-to-grower e-commerce channels exhibit highest price sensitivity, while vertically integrated Pleurotus farms in the Netherlands prioritize batch consistency over unit cost.
Supply Chain Analysis
REACH chemical restrictions function as de facto export controls on peat-based additive formulations, limiting cross-border flows of legacy casing-layer substrates from Belgium to Dutch and German buyers. Raw material sourcing concentrates in the Baltic states and Ireland for horticultural peat, Poland and Ukraine for wheat straw, and German hardwood forestry operations for lignin-rich chips. Single-source vulnerability in Baltic peat extraction under wetland restoration mandates threatens formulation continuity for Belgian Agaricus producers. Distribution runs through just-in-time road freight networks radiating from North Brabant pelletizing facilities to Central European farming clusters, with bagged substrates bypassing traditional agricultural distributors via web-based technical support channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mushroom substrate production is approaching a platform-economics inflection where spawn-to-substrate integration creates data-driven quality feedback loops, much as Mycelia BV's mycelium propagation services now interoperate with Dutch sensor-network climate control to predict colonization outcomes.
For Market Incumbents: Pre-empt displacement by precision-agriculture entrants through backward integration into automated pelletizing systems and captive hardwood chip conditioning infrastructure in Poland's Greater Poland Voivodeship. Defensive consolidation should prioritize acquiring regional distributors with established just-in-time delivery contracts to German Pleurotus farms, locking in volume commitments before channel control fragments further. For New Entrants and Emerging Players: Build out direct-to-grower e-commerce capabilities with bundled technical content targeting the home gardening segment, where North Spore's web-based model has validated margin capture from hobbyist cultivators underserved by traditional agricultural distributors. White-space concentration lies in enzymatic pretreatment research for straw-dominant formulations that match hardwood performance without REACH-restricted additives, with organic certification as the decisive go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated propagators with captive spawn production and algorithmic climate-control data assets over standalone formulators exposed to commodity input volatility. Long-term viability hinges on regulatory compliance infrastructure that navigates evolving EU Green Deal mandates and composting emissions protocols. The signal to watch as inflection indicator is consolidation among Dutch and German distributors adding in-house mycology support staff, signaling channel control is becoming a scarce, acquirable capability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spawn Production | Captive mycelium genetics from Italspawn's Münsterland facilities reduce batch-to-batch variability for contract growers. |
| Automated Pelletizing System Deployment | Dutch North Brabant conveyor-based spawning lines displace manual block preparation in large-scale Pleurotus operations. |
| Organic Certification Pathway Investment | Polish Agaricus farms secure EU regulation premiums by converting straw-dominant formulations away from synthetic nitrogen. |
| Direct-to-Grower E-Commerce Buildout | Web-based substrate sales with technical content bypass agricultural distributor markups in Pennsylvania and California specialty markets. |
| Enzymatic Pretreatment R&D Partnership | Belgian formulators collaborate to match hardwood colonization speeds without peat-dependent legacy supply contracts. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mushroom farm operations managers, spawn quality technicians, agricultural distributor procurement leads, and composting facility regulatory compliance officers. Secondary validation drew from EU F-Gas Regulation implementation reports, EPA composting facility permit databases, USDA National Organic Program certification records, and trade customs data for lignocellulosic feedstock flows. Bottom-up substrate volume estimates from individual facility capacities were triangulated against top-down agricultural sector consumption models.
Calibration against historical capacity expansion timelines and regulatory compliance cost curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation base material, physical form factor, functional component category, and end-use customer type with geographic production cluster overlay. CAGRs were derived from facility-level investment pipelines and buyer procurement contract durations, with specific inputs for energy price volatility in German pasteurization operations and peat extraction quota trajectories under EU wetland restoration mandates.
Sensitivities concentrate around regulatory stringency in REACH chemical restrictions and EU Green Deal peat limits, plus contamination biology breakthroughs affecting facility sterilization protocols. Forecasts reflect assumptions about automation adoption rates in Dutch and German Pleurotus farms and organic certification penetration in Polish Agaricus operations. Material shifts in Baltic peat supply quotas or enzymatic pretreatment cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Canada Compound Feed Market
Agriculture and Agri Products
Colombia Hemp Market
Agriculture and Agri Products
Mexico Compound Feed Market
Agriculture and Agri Products
Organic Hemp Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Cut Flower Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Africa Cashew Market
Agriculture and Agri Products
Global Coco Peat Market
Agriculture and Agri Products
Asia-Pacific Animal Protein Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market