
 Sophora Japonica Market | 2026-2036
Sophora Japonica Market Size, Share, and Industry Trends Forecast 2026-2036
Sophora Japonica Market Analytics
Specialty ingredient distribution networks are reshaping how Sophora japonica extracts reach pharmaceutical and nutraceutical buyers across Asia and Europe. Layn Natural Ingredients leverages its vertical integration from raw flower sourcing to standardized extract production, sustaining quality consistency for European pharmacopeia-grade rutin. Xi'an Lyphar Biotech anchors its position through deep manufacturing scale in Shaanxi province, while Chengdu Wanshan Pharmaceutical differentiates via pharmaceutical-grade certification for domestic hospital procurement channels.
Sophora japonica comprises the dried flower buds and fruits of the Japanese pagoda tree, containing flavonoids—principally rutin, quercetin, and genistein—typically standardized to 95 percent purity for pharmaceutical applications through ethanol or supercritical fluid extraction. The plant serves primarily as a raw material for venotonic, capillary-protective, and antioxidant formulations in both prescription drugs and dietary supplements. Extract forms command the dominant value share due to higher active ingredient concentration and broader pharmaceutical acceptance, while capsule formats represent the fastest-growing delivery segment as direct-to-consumer nutraceutical brands bypass traditional compounding pharmacies. Anti-inflammatory applications generate the deepest margin pools, driven by chronic disease management protocols in regulated healthcare systems.
China's NMPA enforces Good Manufacturing Practice standards for botanical drug substances, while the EMA's Committee on Herbal Medicinal Products governs THMP and well-established use registrations for European market access. REACH compliance for residual solvents and heavy metals increasingly filters smaller processors from export eligibility. Stakeholders must monitor evolving pharmacopeial monograph revisions and extraction technology patents to secure long-term supply contracts.
Market Dynamics
Supercritical CO2 extraction technology is collapsing the cost-quality tradeoff that historically separated pharmaceutical-grade from nutraceutical-grade Sophora japonica extracts, forcing processors to upgrade or exit export channels entirely.
Growth Catalysts
- Venotonic drug protocols:German hospital formulators now specify rutin-rich extracts under EMA herbal medicine guidelines, creating pull-through demand for certified raw material.
- REACH solvent thresholds:The European Chemicals Agency's tightened residual limits favor processors with supercritical capabilities, filtering out solvent-dependent competitors.
- Shaanxi processor clusters:Concentrated extraction infrastructure in China's northwest province yields 60-plus percent of global volume, driving economies of scale for standardized output.
Market Restraints
- Raw material geographic concentration:Over-reliance on Chinese Sophora japonica flower sourcing exposes buyers to single-country harvest volatility and trade policy friction.
- Supercritical equipment capex:Entry-level CO2 extraction systems require seven-figure capital commitments, blocking mid-tier processors from REACH-compliant production.
- Quercetin substitution pressure:Synthetic flavonoid alternatives and onion-derived rutin compete on price for non-pharmaceutical applications, compressing margins in commodity grades.
Strategic Opportunities
- Direct-to-consumer capsule formats:Nutraceutical brands now bypass compounding pharmacies via e-commerce channels, opening margin capture previously held by distribution intermediaries.
- Anti-inflammatory indication expansion:Chronic disease management protocols in regulated healthcare systems are deepening rutin utilization beyond traditional venotonic applications.
- Dual carbon alignment:China's MEE enforcement of carbon intensity metrics creates competitive advantage for processors with renewable-powered extraction facilities.
Industry Challenges
- Pharmacopeial certification timelines:European Pharmacopoeia monograph compliance requires 18-24 month validation cycles, delaying market entry for new extract specifications.
- Flavonoid standardization expertise:Scarcity of analytical chemists capable of HPLC-based rutin-quercetin ratio verification constrains quality control scaling at emerging processors.
- Legacy solvent facility retrofitting:Ethanol-dependent plants face stranded asset risk as EMA and NMPA simultaneously tighten residual solvent specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sophora Japonica Market |
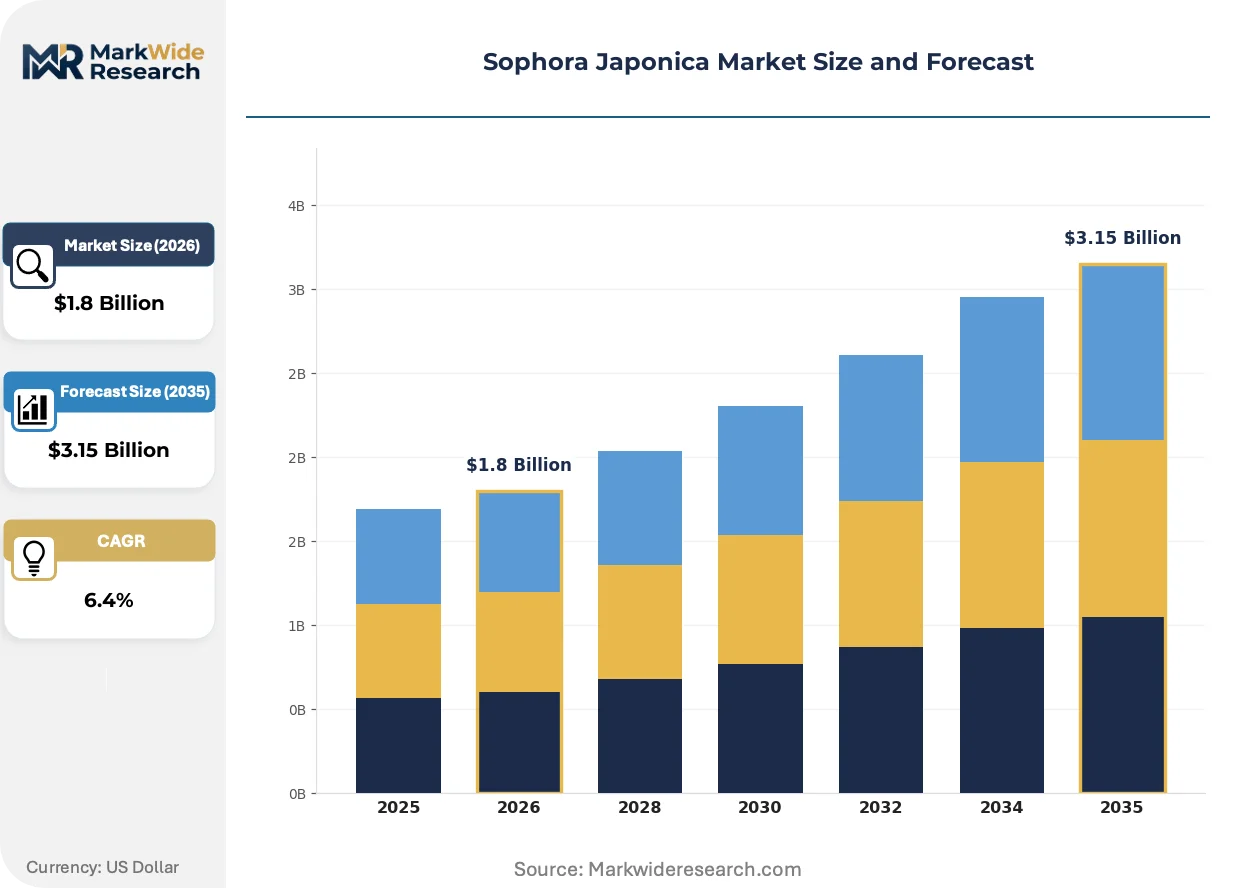
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extract, Powder, Capsules, Teas End User: Pharmaceuticals, Nutraceuticals, Food Industry, Cosmetics Application: Anti-inflammatory, Antioxidant, Cardiovascular Health, Immune Support Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Wholesalers |
| Companies Covered | Layn Natural Ingredients, O'Laughlin Industries, Xi'an Lyphar Biotech, Shaanxi Jintai Biological Engineering, Chengdu Wanshan Pharmaceutical, Beijing Gingko Group, Shaanxi Huike Botanical Development, Xi'an Natural Field Bio-Technique, Hunan Nutramax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sophora Japonica Market Evolving Landscape
Extraction technology convergence with pharmaceutical quality standards is redefining competitive differentiation, while regulatory fragmentation between EMA and NMPA pathways forces dual-track compliance investments.
Supercritical CO2 extraction with integrated online analytics is collapsing the batch-to-batch variability that previously required extensive post-processing refinement. Pharmaceutical formulators in Germany and Switzerland now specify this extraction modality for venotonic drug submissions. The technology is collapsing quality assurance timelines from months to weeks, compressing working capital cycles for extract suppliers.
REACH Annex XVII updates on residual solvents now explicitly reference botanical drug substances, creating a compliance ceiling that ethanol-dependent processors cannot clear without full facility replacement. The regulation forces a bifurcation between export-eligible and domestic-only Chinese suppliers. Shaanxi-based processors with early supercritical adoption capture disproportionate European contract volume as a result.
Hospital procurement departments increasingly specify pharmacopeia-grade certification over generic extract grades, unbundling quality assurance from traditional distributor relationships. This certification-driven preference shift concentrates contract awards among vertically integrated processors with in-house analytical capabilities. The pattern is most visible in German and Austrian hospital formulary decisions, where EMA THMP registration status now dominates supplier selection criteria.
Sophora Japonica Market Segmentation
Sophora japonica derivatives span divergent purity thresholds and regulatory pathways, from pharmacopeia-grade rutin isolates to consumer-facing botanical preparations. Each segment commands distinct manufacturing infrastructure, certification requirements, and margin structures that shape processor investment decisions.
Product Type:
The use-case spectrum stretches from high-concentration pharmaceutical inputs to convenience-oriented consumer formats, with extraction modality determining regulatory eligibility and pricing power.
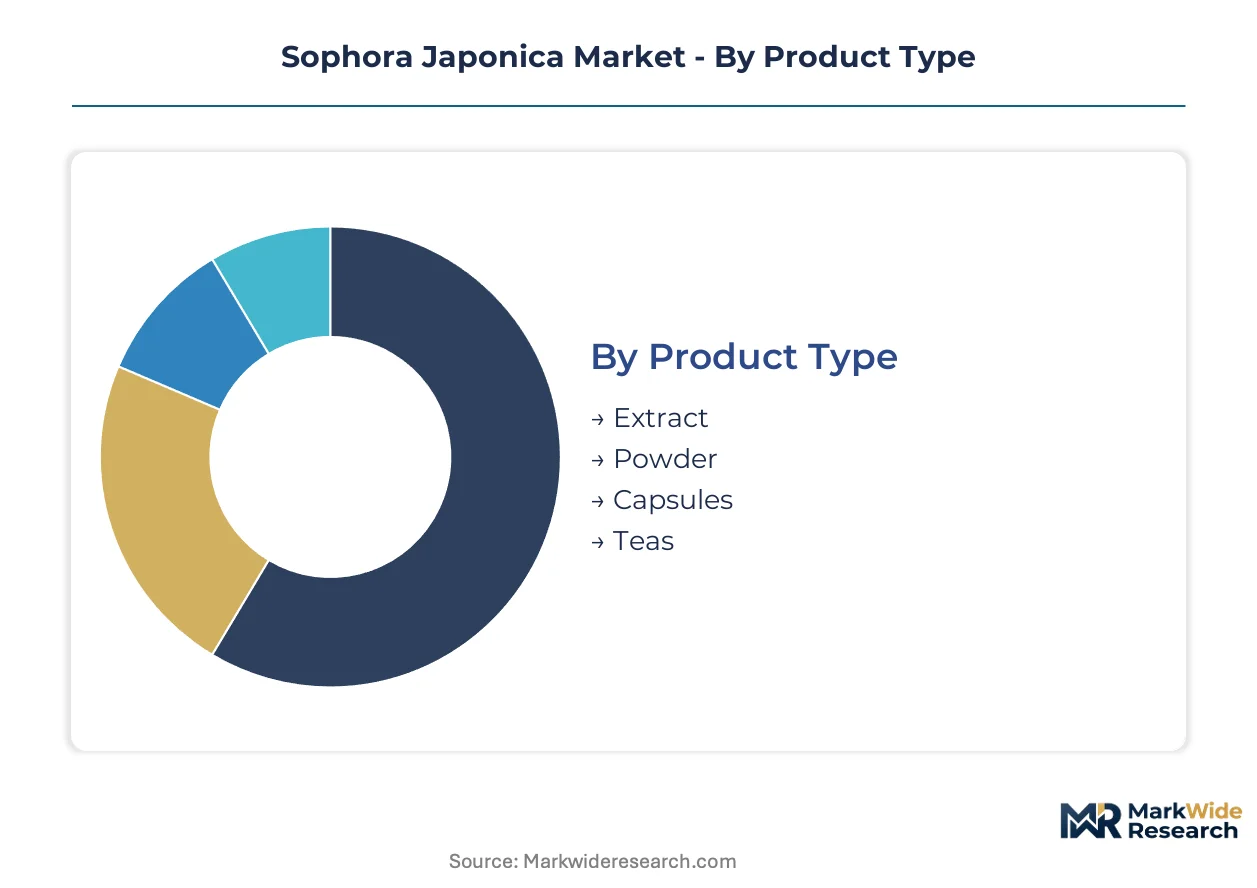
- Extract:Standardized flavonoid concentrates, typically 95 percent rutin purity, serve as the foundational input for venotonic drug compounding and nutraceutical formulation. German pharmaceutical manufacturers under EMA herbal medicine guidelines now specify supercritical CO2-derived extracts to meet REACH residual solvent thresholds, consolidating procurement around Shaanxi-based processors with certified production lines.
- Capsules:Pre-dosed delivery formats enable direct-to-consumer brands to bypass traditional pharmacy distribution, capturing margin previously held by compounding intermediaries. E-commerce channels in North America and Western Europe are absorbing volume fastest as subscription-based nutraceutical models displace retail shelf presence.
- Powder:Bulk botanical material for food fortification and cosmetic formulation, typically standardized to lower flavonoid concentrations than pharmaceutical grades. Food industry buyers in Japan and South Korea source powder grades for functional beverage applications.
- Teas:Whole flower or coarse-cut preparations for traditional medicine practitioners and wellness consumers. Domestic Chinese consumption dominates this segment, with limited export traction due to perishability and customs phytosanitary barriers.
The dominant share belongs to Extract, while Capsules is closing the gap fastest.
End User:
Customer-type concentration mirrors regulatory sophistication, with certified pharmaceutical channels filtering out commodity-grade suppliers.
- Pharmaceuticals:Prescription venotonic and capillary-protective drug manufacturers require pharmacopeia-grade certification under European Pharmacopoeia or Chinese Pharmacopoeia monographs. Hospital procurement departments in Germany and Austria increasingly mandate EMA THMP registration status, unbundling supplier selection from traditional distributor relationships.
- Nutraceuticals:Dietary supplement brands combine rutin with complementary flavonoids for antioxidant positioning, typically sourcing extract grades below pharmaceutical certification thresholds. This segment absorbs the steepest volume expansion as preventive health protocols deepen routine supplementation.
- Food Industry:Functional food and beverage formulators leverage rutin's antioxidant properties for shelf-life extension and clean-label positioning. Japanese and South Korean regulators permit limited flavonoid fortification levels, constraining dosage per serving.
- Cosmetics:Topical applications exploit capillary-strengthening and anti-inflammatory properties for sensitive skin formulations. Korean beauty manufacturers lead incorporation into essence and serum products.
Pharmaceuticals commands the premium tier, though Nutraceuticals is expanding most quickly.
Application:
Therapeutic indication breadth determines pricing stratification, with chronic disease management protocols generating the deepest margin pools.
- Anti-inflammatory:Rutin's modulation of inflammatory cytokine pathways supports chronic condition management protocols in regulated healthcare systems. Hospital formularies in Germany and Switzerland are deepening utilization beyond traditional venotonic applications.
- Venotonic and Capillary Protection:The historical core indication for Sophora japonica-derived drugs, addressing venous insufficiency and microcirculation disorders. EMA herbal medicine guidelines explicitly reference this application for THMP registration eligibility.
- Antioxidant:Cellular protection positioning drives nutraceutical and cosmetic adoption, though regulatory constraints on health claims limit pharmaceutical pricing power in this indication.
- Cardiovascular Health:Emerging applications in endothelial function support and blood pressure modulation are attracting clinical trial investment, particularly in Chinese domestic drug development pipelines.
- Immune Support:General wellness positioning with limited clinical validation, concentrated in direct-to-consumer supplement channels with minimal regulatory oversight.
Anti-inflammatory generates the highest margins, while Cardiovascular Health is gaining share fastest.
Distribution Channel:
Channel structure is concentrating around certification-capable intermediaries as hospital procurement departments disintermediate generic distributors.
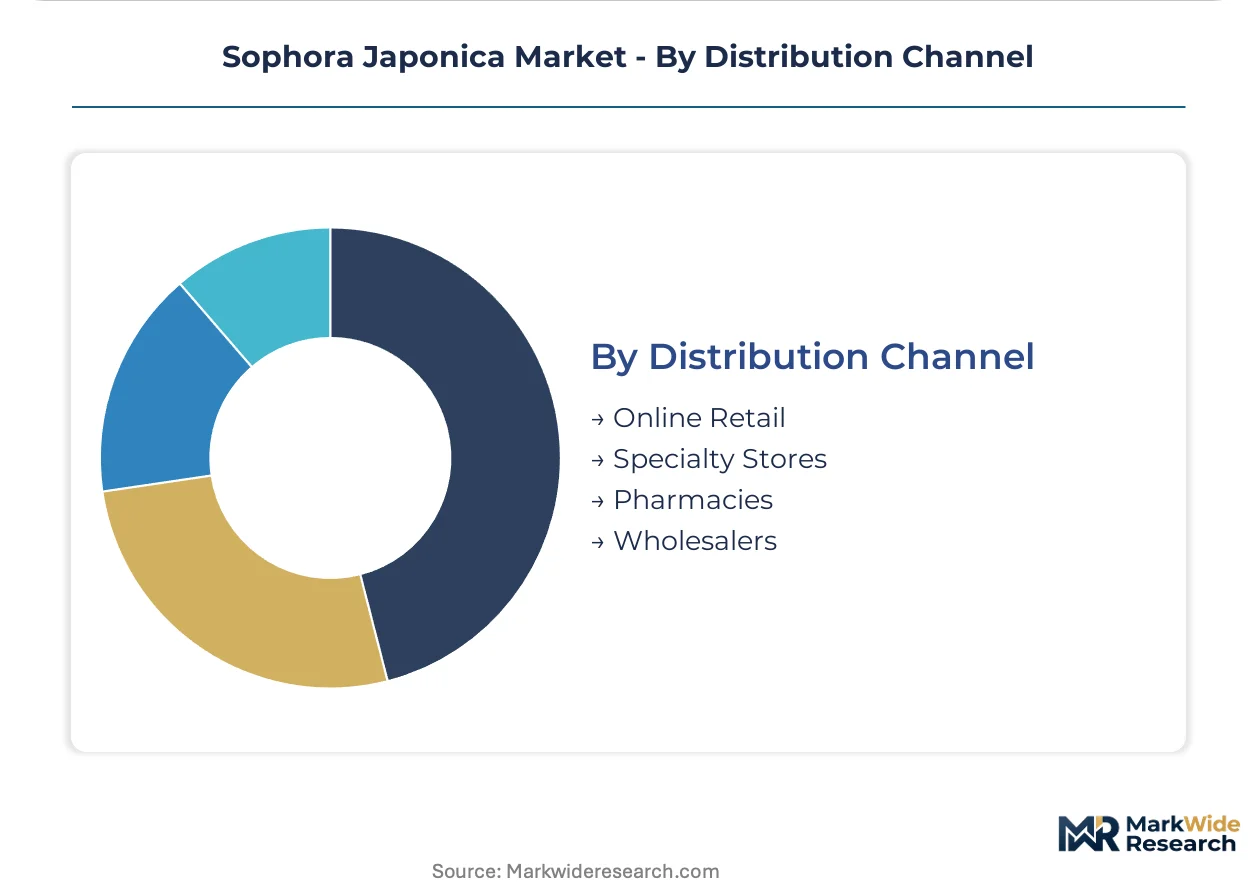
- Pharmacies:Compounding and retail pharmacy networks remain the regulated pathway for prescription venotonic formulations. German pharmacy chains now verify EMA THMP registration before shelf placement.
- Online Retail:Direct-to-consumer platforms enable nutraceutical brands to capture margin previously allocated to wholesale and retail intermediaries. Subscription models in North America and Western Europe are displacing one-time purchase patterns.
- Specialty Stores:Health food and traditional medicine retailers serve wellness-oriented consumers seeking practitioner-grade botanicals. Japanese kampo medicine shops maintain consistent demand for standardized preparations.
- Wholesalers:Bulk distribution to food and cosmetic manufacturers, with procurement increasingly contingent on REACH or NMPA compliance documentation. Smaller ethanol-dependent processors are exiting this channel as residual solvent specifications tighten.
Pharmacies retains the largest value share, while Online Retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical buyers extract 40-50 percent pricing premiums over Chinese domestic contracts for pharmacopeia-grade rutin, while Shaanxi processors capture margin through supercritical extraction scale rather than brand equity.
China
Shaanxi province hosts 60-plus percent of global extraction capacity, with Xi'an and Baoji processor clusters supplying standardized rutin to European pharmaceutical formulators. NMPA Good Manufacturing Practice standards filter smaller ethanol-dependent facilities from export eligibility. The province's concentrated infrastructure yields economies of scale that collapse per-unit costs for REACH-compliant output.
Germany
Hospital formulators in Bavaria and North Rhine-Westphalia now specify EMA THMP-registered rutin extracts for venotonic drug protocols under herbal medicine guidelines. The country's national pharmaceutical regulator enforces residual solvent thresholds that favor supercritical CO2-derived inputs. Frankfurt and Hamburg distribution hubs concentrate procurement authority for Central European hospital networks.
Switzerland
Swissmedic-registered pharmaceutical manufacturers source high-purity flavonoid isolates for capillary-protective drug formulations. The country's cantonal procurement systems prioritize pharmacopeia-grade certification over generic extract grades. Basel and Zurich anchor contract manufacturing demand for precision-dosed venotonic preparations.
United States
Direct-to-consumer nutraceutical brands in California and New York Metro bypass traditional pharmacy distribution via subscription e-commerce models. FDA dietary supplement regulations permit rutin positioning for antioxidant claims without drug approval pathways. Los Angeles and Miami logistics clusters handle bulk import processing from Shaanxi suppliers.
Japan
Kampo medicine practitioners in Tokyo and Osaka sustain consistent demand for standardized Sophora japonica preparations. The Ministry of Health, Labour and Welfare permits limited flavonoid fortification in functional foods under Foods with Function Claims procedures. Kansai region distributors bridge traditional medicine channels and modern nutraceutical retail.
Sophora Japonica Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying standardized extracts to formulators lacking in-house extraction capabilities. The vendor base stratifies across three tiers: vertically integrated processors with pharmacopeia certification, scale-driven extract manufacturers serving nutraceutical brands, and regional traders handling commodity-grade flower sourcing. Two dominant competitive moves define positioning: supercritical equipment investment for REACH compliance, and backward integration into captive flower cultivation to secure raw material supply.
Within the certified-processor tier, Layn Natural Ingredients and Xi'an Lyphar Biotech exemplify divergent scale strategies. Layn occupies a position representing vertical control from raw flower sourcing through standardized extract production. Xi'an Lyphar anchors the Shaanxi manufacturing concentration with deep extraction infrastructure. Chengdu Wanshan Pharmaceutical sits within the pharmaceutical-grade certification segment, targeting domestic hospital procurement channels.
| Leading Market Players |
|---|
| Layn Natural Ingredients |
| O'Laughlin Industries |
| Xi'an Lyphar Biotech |
| Shaanxi Jintai Biological Engineering |
| Chengdu Wanshan Pharmaceutical |
| Beijing Gingko Group |
| Shaanxi Huike Botanical Development |
| Xi'an Natural Field Bio-Technique |
| Hunan Nutramax |
| Others |
Value Network & Pricing Analysis
Single-country harvest concentration in China's Shaanxi province exposes buyers to tariff volatility and trade friction that simultaneously widens pharmacopeia-grade pricing spreads and forces downstream inventory repositioning. German hospital formulators absorb 40-50 percent premiums over Chinese domestic contracts, while REACH compliance costs filter ethanol-dependent processors from export eligibility entirely.
Pricing Analysis
Configured-to-order pricing for EMA THMP-registered extracts commands substantial premiums over standard nutraceutical grades. Three-tier pricing structure across pharmacopeia-certified, food-grade, and cosmetic-grade levels reflects certification investment and analytical capability differentiation. Cost compression in commodity rutin grades intensifies as synthetic quercetin alternatives and onion-derived flavonoids compete for non-pharmaceutical applications. Nutraceutical brands exhibit highest price sensitivity, while hospital procurement departments prioritize certification over unit cost.
Supply Chain Analysis
Upstream Sophora japonica flower cultivation clusters in Shaanxi, Henan, and Shandong provinces feed extraction infrastructure concentrated in Xi'an and Baoji. Supercritical CO2 equipment, analytical chemistry talent, and pharmacopeial reference standards constitute critical input dependencies. Single-source vulnerability to Chinese regulatory enforcement and carbon intensity metrics under MEE supervision creates structural exposure. Distribution runs through Frankfurt and Hamburg hubs for European pharmaceutical formulators, with Los Angeles and Miami handling North American nutraceutical bulk intake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as EMA and NMPA regulatory divergence creates dual-track compliance niches, with certification-capable processors capturing hospital procurement while commodity suppliers serve domestic wellness channels.
For Market Incumbents: Harden analytical chemistry capabilities through HPLC-based rutin-quercetin ratio verification investment to defend against Shaanxi-based scale competitors. Secure captive flower cultivation partnerships to mitigate raw material geographic concentration risk. Prioritize Swissmedic and EMA THMP registration maintenance as hospital formulary decisions unbundle from distributor relationships.
For New Entrants and Emerging Players: Build out direct-to-consumer capsule manufacturing for North American and Western European e-commerce channels, bypassing traditional pharmacy intermediaries. Target anti-inflammatory indication expansion as chronic disease management protocols deepen rutin utilization beyond venotonic applications. Pursue white-label partnerships with subscription-based nutraceutical brands as the fastest-penetrable go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated processors with pharmacopeia certification over standalone traders. Long-term viability rests on supercritical extraction asset ownership and backward integration into raw material supply. Acquisition target archetype: Shaanxi-based processors with early REACH compliance adoption and in-house analytical capabilities. Watch EMA Committee on Herbal Medicinal Products monograph revision timelines as inflection indicator for certification value appreciation.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | REACH Annex XVII compliance secures European pharmaceutical contract eligibility against solvent-dependent competitors. |
| Backward Integration into Cultivation | Captive flower supply mitigates Shaanxi harvest volatility and trade policy friction exposure. |
| EMA THMP Registration Investment | Hospital procurement departments in Germany and Austria mandate registration status for formulary placement. |
| Direct-to-Consumer Capsule Launch | E-commerce subscription models capture margin previously allocated to pharmacy distribution intermediaries. |
| Anti-Indication Clinical Trial Pipeline | Chronic disease management protocols in Swiss and German healthcare systems deepen rutin utilization. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with extraction plant managers, pharmaceutical procurement leads, EMA regulatory affairs specialists, and nutraceutical brand executives; and secondary validation through NMPA GMP certification databases, EMA THMP registration records, REACH Annex XVII updates, and customs trade flows. Bottom-up capacity assessment across Shaanxi processor clusters triangulated against top-down demand modeling from hospital formulary data and e-commerce channel audits.
Forecast inputs span product type segmentation across extract, capsule, powder, and tea formats; end-user categories including pharmaceuticals, nutraceuticals, food industry, and cosmetics; and application areas from venotonic to anti-inflammatory and cardiovascular health. CAGRs derive from regression analysis of historical volume-price relationships and elasticity estimates across certification tiers. Carbon intensity metrics under China's MEE enforcement and EMA herbal medicine guideline revisions constitute industry-specific demand shapers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed processors or abrupt REACH solvent threshold tightening would shift outcomes. Cross-checking against EMA Committee on Herbal Medicinal Products registration velocity and Shaanxi provincial export statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
North America Animal Protein Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
North America Palm Oil Market
Agriculture and Agri Products
Consumer Floriculture Market
Agriculture and Agri Products
Rape Seed Meal Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
South America Swine Feed Premix Market
Agriculture and Agri Products
Cameroon Agriculture Market
Agriculture and Agri Products
Primary Feed Materials Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Marine Seaweed Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Apiculture Market
Agriculture and Agri Products
Rice Straw Market