
 Armored Unmanned Underwater Vehicle Market | 2026-2036
Armored Unmanned Underwater Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Armored Unmanned Underwater Vehicle Market Outlook
The defense procurement channel is narrowing as sovereign buyers consolidate vendor lists around proven platform suppliers. Kongsberg Gruppen leverages its Norwegian naval heritage to dominate Nordic and Baltic contracts. General Dynamics sustains a commanding position in North American AUV programs through its Electric Boat division. Teledyne Technologies competes aggressively in the sensor-integrated segment, where payload modularity determines contract outcomes.
An armored unmanned underwater vehicle is a self-propelled submersible platform encased in pressure-resistant hull materials—typically titanium alloys or carbon-fiber composites rated for depths exceeding 6,000 meters—designed to execute missions without onboard human operators in contested or hazardous marine environments. The autonomous technology segment leads order volumes, though hybrid architectures are gaining traction as navies seek operator override capabilities for sensitive missions. Military Operations applications anchor current procurement budgets, while Environmental Monitoring represents an emerging demand corridor as governments expand subsea domain awareness programs. Ship-Based deployment configurations currently occupy the largest installed base, reflecting integration with existing surface fleet infrastructure.
The U.S. Navy's Unmanned Campaign Framework and NATO's Maritime Unmanned Systems initiative are reshaping certification requirements and interoperability standards for armored AUV platforms. BAE Systems and Lockheed Martin navigate these regulatory currents by aligning R&D roadmaps with emerging STANAG protocols and FAA-equivalent underwater navigation guidelines. Stakeholders must weigh sovereign content requirements against cross-border sensor integration partnerships as procurement rules tighten.
Market Dynamics
Sovereign defense procurement is consolidating around hardened autonomous platforms as NATO members accelerate submarine infrastructure replacement cycles and demand interoperable undersea domain awareness capabilities.
Growth Catalysts
- STANAG Protocol Alignment:NATO's standardization mandates for maritime unmanned systems are forcing cross-border platform compatibility, expanding addressable contract volumes for certified vendors across member navies.
- Titanium-Carbon Composite Hulls:Pressure-resistant materials rated beyond 6,000 meters are extending operational depth envelopes, opening missions in previously inaccessible oceanic trenches.
- Subsea Domain Awareness Programs:Environmental monitoring applications are attracting non-defense budget lines as governments map critical seabed infrastructure and mineral deposits.
Market Restraints
- Titanium Alloy Supply Concentration:Specialized metallurgical feedstock for deep-rated hulls concentrates among a limited supplier base, creating input cost volatility and qualification bottlenecks.
- Autonomous Navigation Certification:FAA-equivalent underwater navigation guidelines remain underdeveloped, extending platform approval timelines and freezing pre-certified procurement.
- Tethered ROV Substitution:Operator-controlled remotely operated vehicles retain cost advantages for survey missions in uncontested waters, compressing autonomous platform addressable market.
Strategic Opportunities
- Baltic Seabed Infrastructure:Norway, Sweden, and Finland are expanding subsea cable and pipeline monitoring programs, creating demand for persistent autonomous patrol assets.
- Hybrid Architecture Convergence:Operator-override capabilities combining autonomous transit with remote piloting for sensitive missions are opening contracts previously reserved for manned platforms.
- UK Defense Industrial Strategy:Sovereign content requirements and the National Shipbuilding Strategy are channeling R&D investment toward domestic AUV supply chain development.
Industry Challenges
- Autonomy Software Talent Scarcity:Naval-grade navigation algorithm development requires cleared personnel with combined robotics and undersea acoustics expertise, constraining program velocity.
- Legacy Sonar Integration:New autonomous platforms must interface with existing surface fleet sensor networks, forcing expensive middleware development and interoperability testing cycles.
- Pressure Vessel Qualification:Deep-rated hull certification requires extended cycle testing that extends development timelines and consumes capital before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Armored Unmanned Underwater Vehicle Market |
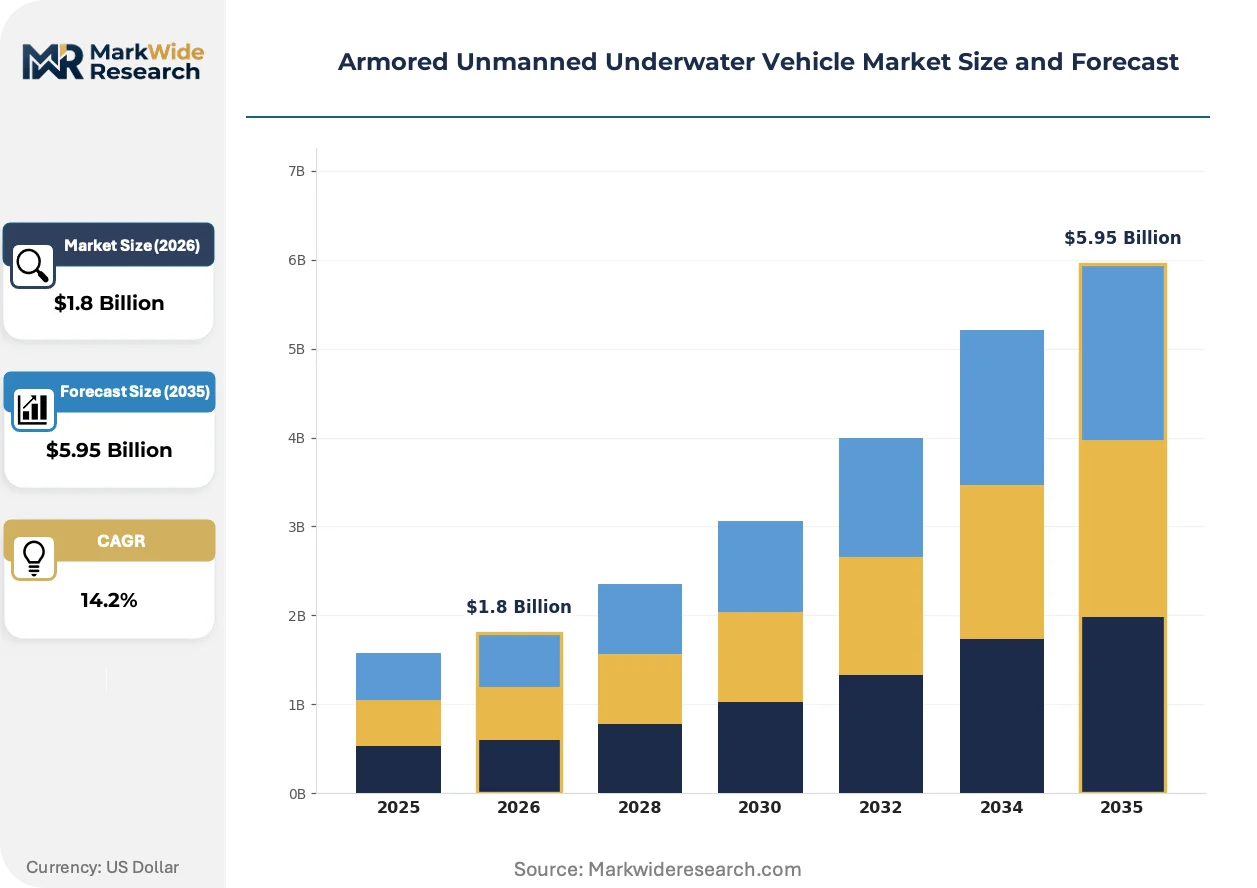
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Autonomous, Remote-Controlled, Hybrid, Semi-Autonomous Application: Military Operations, Surveying, Search & Rescue, Environmental Monitoring End User: Defense, Research Institutions, Oil & Gas, Marine Engineering Deployment: Shore-Based, Ship-Based, Air-Deployment, Subsea Operations |
| Companies Covered | Kongsberg Gruppen, Teledyne Technologies, General Dynamics, Lockheed Martin, BAE Systems, Saab, Subsea 7 S.A, Oceaneering International, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Armored Unmanned Underwater Vehicle Market Strategic Shifts
Autonomous underwater platform development is accelerating around three vectors: hull material substitution, regulatory harmonization, and procurement model restructuring toward capability-as-a-service frameworks.
Carbon-fiber composite pressure hulls are replacing titanium alloys in depth-rated applications above 4,000 meters, slashing structural weight and extending mission endurance. The U.S. Navy and Royal Navy are field-testing these hulls for littoral survey missions. This substitution is rendering obsolete the titanium-dominated supply chains that have defined deep-submergence vehicle construction for four decades.
REACH and RoHS compliance requirements for underwater sensor payloads are forcing component redesigns across European defense procurement. The industrial consequence is a purge of legacy lead-based soldering and cadmium-plated connectors from subsea electronics. Sensor-integrated AUV segments serving NATO member states are responding by accelerating supplier qualification programs to meet 2027 substance restriction deadlines.
Capability-based contracting is displacing unit purchase models as sovereign buyers seek operational availability rather than platform ownership. The Royal Navy's Maritime Autonomous Systems Trials and Development Unit is pioneering lease-to-operate structures for mine countermeasure missions. This shift is most visible in UK and Norwegian procurement, where defense budget pressures favor opex over capex treatment for unmanned assets.
Armored Unmanned Underwater Vehicle Market Segmentation
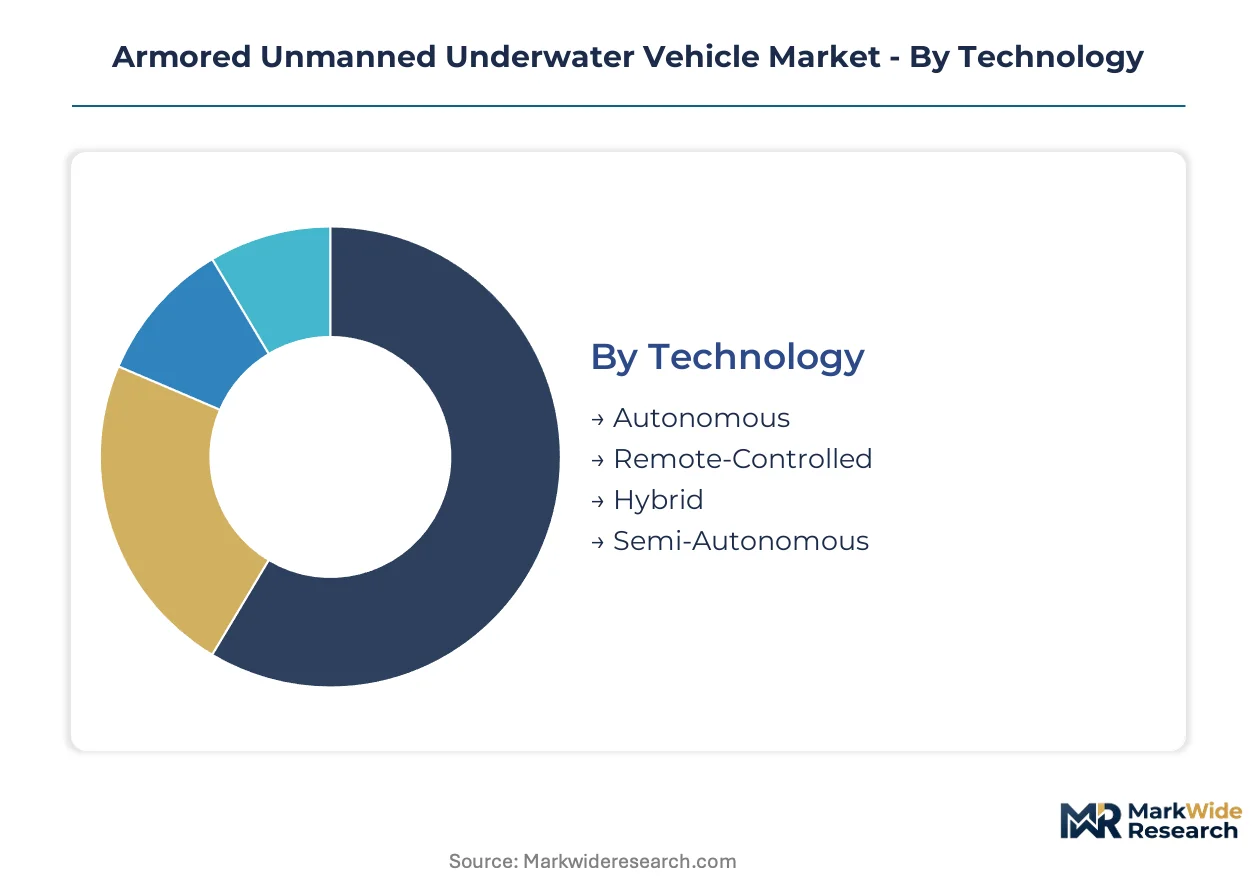
Segmentation in the armored AUV market reveals how mission requirements dictate technology selection and procurement channels. Hull depth ratings, autonomy levels, and deployment infrastructure compatibility determine vendor positioning and contract eligibility across sovereign defense programs.
Technology:
Maturity varies sharply across autonomy architectures, with fully autonomous platforms dominating established naval procurement while hybrid systems capture emerging demand for operator-override missions.
- Autonomous:Self-directed navigation algorithms execute pre-programmed mission profiles without real-time operator intervention. NATO's Maritime Unmanned Systems initiative and the U.S. Navy's Unmanned Campaign Framework are channeling procurement toward these platforms for mine countermeasure and seabed infrastructure patrol missions in contested waters.
- Hybrid:Architectures combine autonomous transit with remote piloting capabilities for sensitive phases, addressing sovereignty concerns in nuclear-armed navies. Norway and the United Kingdom are pioneering these configurations for littoral survey and critical infrastructure protection where human judgment remains mandatory.
- Remote-Controlled:Tethered operator dependence limits operational depth and endurance but retains cost advantages for commercial survey applications in uncontested environments.
- Semi-Autonomous:Waypoint-based navigation with periodic human verification occupies a narrowing middle ground as full autonomy gains certification traction.
Autonomous platforms handle the majority of defense procurement throughput; hybrid architectures are expanding most quickly as certification frameworks mature.
Application:
Cost tier segmentation separates sovereign defense budgets from commercial and research funding streams, with mission-critical military applications commanding premium hull specifications.
- Military Operations:Mine countermeasures, anti-submarine warfare training, and seabed infrastructure protection drive demand for titanium-carbon composite hulls rated beyond 6,000 meters. The U.S. Navy and Royal Navy are consolidating procurement around hardened platforms for contested undersea domain operations.
- Environmental Monitoring:Subsea domain awareness programs for critical mineral deposit mapping and seabed ecology assessment are attracting non-defense budget lines. Norway's seabed infrastructure expansion and Sweden's Baltic cable monitoring initiatives are creating persistent patrol requirements.
- Surveying:Commercial bathymetric and geophysical survey missions favor lighter carbon-fiber hulls above 4,000 meters where pressure requirements moderate.
- Search & Rescue:Time-critical recovery operations prioritize rapid deployment capability over depth endurance, favoring air-deployable configurations.
Military Operations commands the dominant revenue share; Environmental Monitoring is climbing the fastest as governments expand subsea sovereignty programs.
End User:
Customer type segmentation reflects fundamentally different procurement timelines, with defense programs operating on decade-long fleet modernization cycles against research institutions' project-based acquisition.
- Defense:Sovereign procurement channels concentrate around proven platform suppliers with established security clearances and NATO STANAG certification. Kongsberg Gruppen leverages Norwegian naval heritage for Nordic and Baltic contracts; General Dynamics sustains North American dominance through Electric Boat division integration.
- Research Institutions:Academic and governmental oceanographic programs prioritize payload modularity and sensor integration flexibility over hardened hull specifications.
- Oil & Gas:Subsea field inspection and pipeline survey requirements favor cost-optimized remotely operated vehicles for infrastructure in uncontested waters.
- Marine Engineering:Port construction and coastal infrastructure projects generate episodic demand for shallow-water survey platforms with rapid mobilization capability.
Defense absorbs the preponderance of armored platform investment; Research Institutions are gaining share fastest as climate science funding expands subsea observation networks.
Deployment:
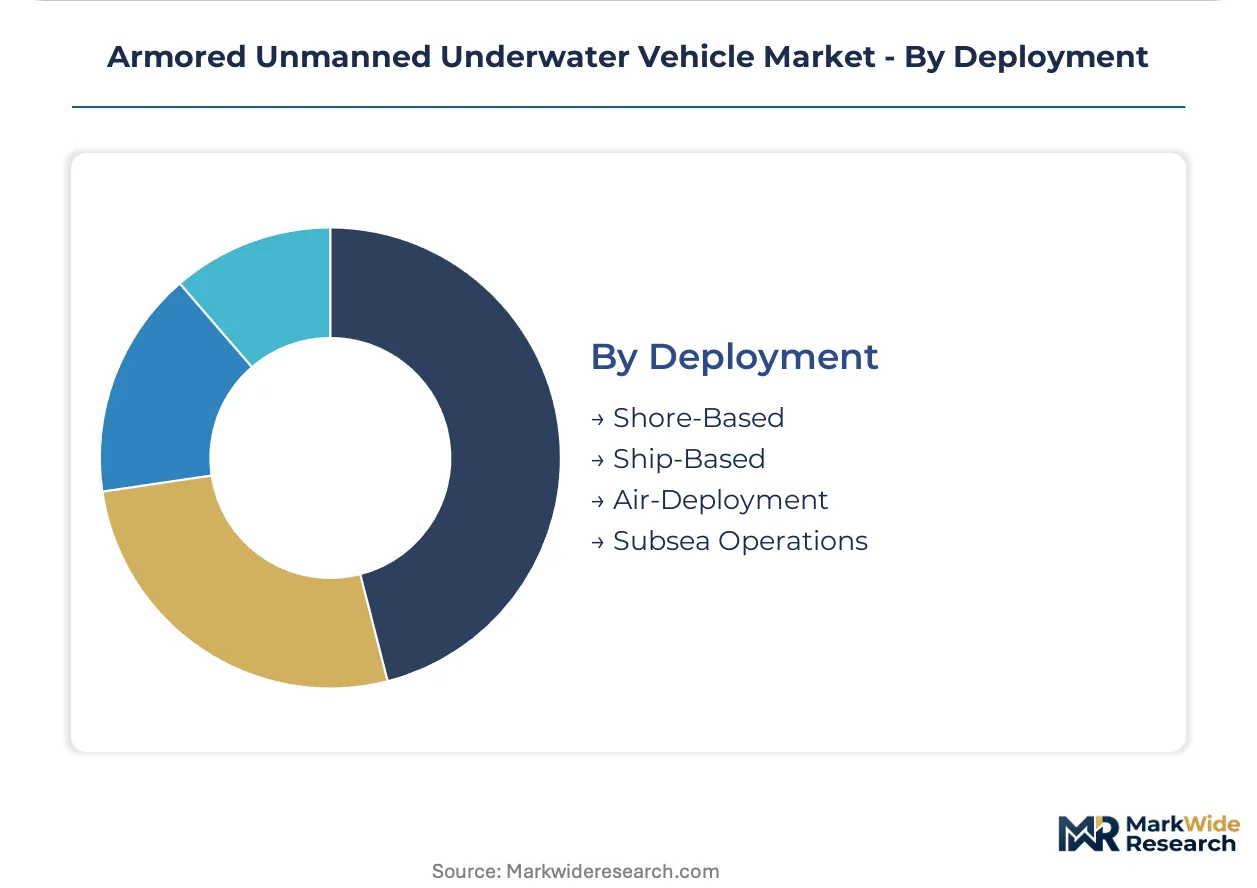
Volume concentration reflects integration burden with existing fleet infrastructure, with surface vessel compatibility dominating current installed base against emerging air-deployment modalities.
- Ship-Based:Integration with existing surface fleet infrastructure—frigates, destroyers, and dedicated support vessels—occupies the largest installed base. The Royal Navy's Maritime Autonomous Systems Trials and Development Unit and comparable NATO programs are standardizing launch and recovery systems across member navies.
- Shore-Based:Fixed coastal facilities support persistent patrol missions for seabed infrastructure monitoring. Norway's Arctic shoreline stations and UK coastal defense sites are expanding dedicated AUV maintenance and rapid-response capabilities.
- Air-Deployment:Helicopter and maritime patrol aircraft launch systems remain developmental, constrained by payload weight limits and recovery complexity in open ocean conditions.
- Subsea Operations:Docking stations on seabed infrastructure or submarine-deployed configurations enable extended-duration missions without surface support, requiring hardened pressure vessels rated for ambient depth plus operational margin.
Ship-Based configurations manage the bulk of operational sorties; Shore-Based systems are expanding most rapidly as persistent patrol requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States defense procurement commands premium pricing for deep-rated titanium hulls, while Norwegian and UK programs optimize around carbon-fiber composites for littoral missions. Sovereign content requirements and NATO STANAG certification timelines create divergent contract structures across these procurement channels.
United States
The U.S. Navy's Unmanned Campaign Framework drives fleet modernization through hardened autonomous platforms for contested undersea operations. FAA-equivalent underwater navigation guidelines under development by the Department of Defense extend platform approval timelines. Electric Boat facilities in Connecticut and Rhode Island anchor submarine infrastructure integration for AUV programs.
Norway
Arctic seabed infrastructure expansion and Baltic cable monitoring programs generate persistent patrol requirements for autonomous assets. The National Shipbuilding Strategy channels sovereign content requirements toward domestic supply chain development. Kongsberg facilities near Horten concentrate Nordic naval heritage and STANAG-aligned platform certification capabilities.
United Kingdom
The Royal Navy's Maritime Autonomous Systems Trials and Development Unit pioneers lease-to-operate structures for mine countermeasure missions. UK Defense Industrial Strategy mandates align R&D roadmaps with emerging NATO interoperability protocols. Plymouth and Clyde naval bases standardize launch and recovery systems integration across surface fleet infrastructure.
Germany
REACH and RoHS compliance deadlines for underwater sensor payloads force component redesigns across European defense procurement. The country's national defense procurement office consolidates vendor lists around proven platform suppliers with established security clearances. Industrial clusters in Schleswig-Holstein and Bavaria concentrate maritime systems engineering expertise.
Sweden
Baltic Sea critical infrastructure protection programs expand demand for hybrid autonomy architectures combining autonomous transit with remote piloting. Swedish Defense Materiel Administration procurement rules tighten cross-border sensor integration partnerships against sovereign content benchmarks. Saab facilities in Linköping and Karlskrona anchor Nordic-Baltic defense industrial cooperation frameworks.
Armored Unmanned Underwater Vehicle Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in sensor and hull material supply. The vendor base concentrates around defense primes with established NATO security clearances and STANAG certification histories, creating tiered access to sovereign procurement channels. Two archetypes dominate: full-spectrum platform suppliers with submarine heritage, and sensor-integrated specialists competing on payload modularity. Competitive moves center on strategic partnerships for autonomy software development and geographic expansion through NATO member state joint ventures.
Among Nordic-Baltic platform suppliers, Kongsberg Gruppen exemplifies the naval heritage archetype, while General Dynamics represents North American submarine infrastructure integration. Teledyne Technologies occupies a position within the sensor-integrated segment where payload flexibility determines contract eligibility. These three anchors illustrate how certification access and sovereign content compliance shape competitive positioning across NATO procurement channels.
| Leading Market Players |
|---|
| Kongsberg Gruppen |
| Teledyne Technologies |
| General Dynamics |
| Lockheed Martin |
| BAE Systems |
| Saab |
| Subsea 7 S.A |
| Oceaneering International |
| L3Harris Technologies |
| Others |
Value Chain & Pricing Dynamics
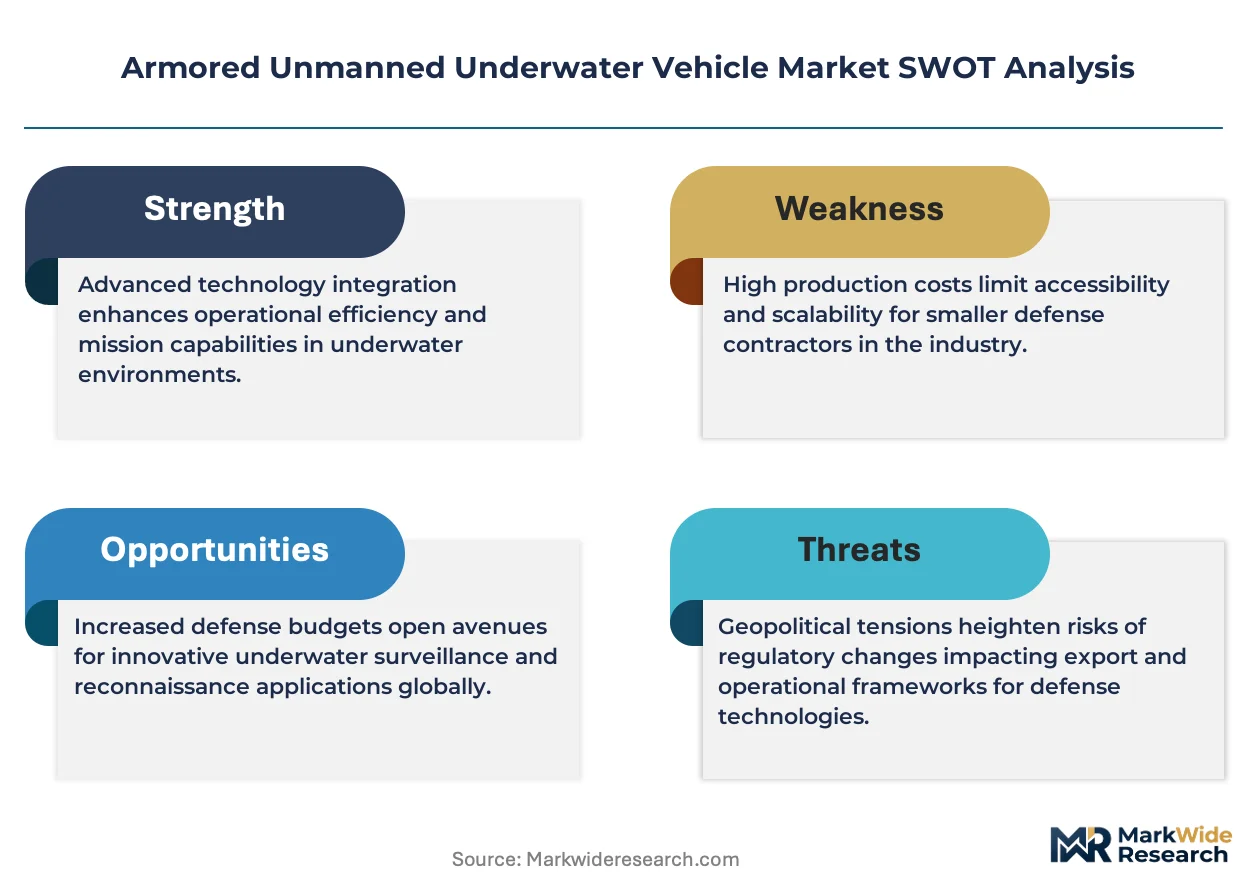
Titanium alloy supply concentration among a limited metallurgical supplier base creates input cost volatility that simultaneously widens pricing spreads between deep-rated hull configurations and compresses margins across the supply chain. This single-source dependency for pressure-resistant materials rated beyond 6,000 meters forces buyers into long-term offtake commitments while vendors absorb qualification bottlenecks that extend pre-revenue development cycles.
Pricing Analysis
Configured-to-order pricing for mission-specific hull depth ratings and autonomy architectures commands substantial premiums over standard littoral survey configurations. Three-tier pricing structure across deep-rated titanium-carbon composite platforms, mid-depth carbon-fiber hulls, and commercial survey variants reflects certification grade and sovereign content compliance levels. Cost compression in the commercial survey tier is intensifying because tethered ROV alternatives retain cost advantages for uncontested waters. Defense procurement channels exhibit the lowest price sensitivity due to mission-critical requirements and NATO STANAG certification mandates.
Supply Chain Analysis
Contract manufacturing for pressure vessel fabrication concentrates in Norway, the United Kingdom, and the United States where submarine infrastructure heritage anchors specialized welding and composite layup capabilities. The supply chain draws from titanium feedstock suppliers in Russia and China, carbon-fiber prepregs from Japan and the United States, and autonomy software development clusters in Sweden and the United Kingdom. Single-source vulnerability for deep-rated titanium alloy qualification creates procurement risk for platforms exceeding 6,000-meter ratings. Distribution runs through sovereign defense procurement channels with established security clearances rather than open commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The armored AUV market represents a service-attach opportunity where capability-as-a-service frameworks and lease-to-operate structures for mine countermeasure missions are expanding faster than hardware unit sales. Persistent patrol requirements for seabed infrastructure monitoring generate recurring revenue streams that outpace transactional platform procurement.
For Market Incumbents: Insulate certification advantages by accelerating STANAG protocol alignment investments before regulatory harmonization widens vendor eligibility. Deepen backward integration into titanium-carbon composite hull fabrication to capture margin currently lost to qualified pressure vessel subcontractors. Lockheed Martin and BAE Systems navigation of emerging FAA-equivalent underwater guidelines demonstrates how early regulatory engagement freezes out later entrants. For New Entrants and Emerging Players: Build out payload modularity capabilities for the environmental monitoring segment where sovereign buyers seek sensor-integrated platforms without submarine heritage premiums. The Baltic seabed infrastructure corridor offers the most penetrable geography given Norway, Sweden, and Finland's expansion of cable and pipeline monitoring programs. A go-to-market angle emphasizing hybrid autonomy architectures for operator-override missions addresses nuclear-armed navies' sovereignty concerns. For Investors and Strategic Acquirers: NATO's Maritime Unmanned Systems initiative reshapes the acquisition landscape by consolidating vendor lists around proven platform suppliers with established security clearances. The five-to-ten-year viability window favors full-spectrum platform integrators over component specialists as procurement shifts toward capability-based contracting. Acquisition target archetypes include sensor-integrated specialists competing on payload flexibility. The signal to watch is Royal Navy lease-to-operate structure adoption rates as a proxy for opex-preference normalization across NATO member states.| Strategic Initiative | Industry Significance |
|---|---|
| STANAG Certification Investment | Early alignment with NATO interoperability protocols locks in cross-border contract eligibility before harmonization completes. |
| Carbon-Fiber Hull Substitution | Weight reduction above 4,000 meters extends mission endurance and disrupts titanium-dominated supply chains. |
| Capability-as-a-Service Transition | Lease-to-operate structures for mine countermeasure missions convert capex procurement into recurring revenue streams. |
| Autonomy Software Partnership | Collaboration with cleared personnel pools addresses naval-grade navigation algorithm talent scarcity constraining program velocity. |
| Baltic Joint Venture Formation | Norwegian-Swedish-Finnish seabed infrastructure programs create localized content compliance for persistent patrol assets. |
Study Parameters
A spread of perspectives from submarine platform engineers, defense procurement officers, autonomy software architects, and sensor integration specialists converged on the working assumptions underlying this analysis. Primary fieldwork with NATO member state naval program offices and AUV manufacturer engineering directors combined with secondary validation through U.S. Navy Unmanned Campaign Framework documentation, UK National Shipbuilding Strategy filings, and Norwegian Defense Materiel Administration procurement records. Bottom-up unit economics modeling and top-down defense budget allocation analysis were triangulated to anchor volume and value estimates.
Demand-supply-balance framing across the analysis window integrated sovereign fleet modernization cycles, titanium alloy feedstock availability constraints, and autonomy certification timeline uncertainties. Segmentation dimensions modeled include technology architecture, hull depth rating, application mission profile, end-user procurement channel, and deployment infrastructure compatibility. CAGRs were derived from weighted scenario outcomes across defense budget trajectory assumptions and subsea domain awareness program expansion rates. Industry-specific forecast inputs incorporated NATO STANAG protocol adoption timelines and FAA-equivalent underwater navigation guideline development progress.
Stress conditions across titanium supply disruption, autonomous navigation certification delays, and tethered ROV cost competition were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sovereign content requirement enforcement and cross-border sensor integration partnership rules. Quarterly review of NATO Maritime Unmanned Systems initiative implementation progress and Royal Navy lease-to-operate contract award velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
United States ROV Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Europe Aerostat Systems Market
Unmanned Systems
Europe Military Unmanned Vehicles Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Autonomous Military Weapon Market
Unmanned Systems
Unmanned Surface Vessel (USV) Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
North America AUV Market