
 Umbrella Insurance Market | 2026-2036
Umbrella Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Umbrella Insurance Market Analysis
The gap between premium-tier commercial umbrella policies and commoditized personal coverage is restructuring how carriers allocate capital and price risk. Travelers dominates the commercial segment through captive distribution and specialized underwriting teams. Berkshire Hathaway sustains its position via scale advantages in reinsurance backing and long-tail liability reserves. Chubb differentiates through white-glove service models targeting ultra-high-net-worth households with complex global exposures.
Umbrella insurance provides excess liability coverage above primary policies, typically activating at thresholds between one million and ten million dollars and extending protection against bodily injury, property damage, and personal liability claims. Commercial umbrella coverage leads premium volume as corporations face escalating nuclear verdicts in employment practices and product liability cases, while personal umbrella policies show faster growth among mass-affluent households with appreciating real estate and investment portfolios. Distribution through insurance agents still captures the majority of placement value, though online brokers are gaining share in standardized personal lines where coverage terms homogenize.
State insurance commissioners across the United States regulate rate filings and reserve adequacy, while the National Association of Insurance Commissioners coordinates financial solvency standards and market conduct examinations. The SEC's disclosure requirements for publicly traded carriers indirectly shape capital allocation transparency, and ISO develops standardized policy forms that reduce friction in policy comparison and placement. Stakeholders must monitor how emerging litigation funding trends and social inflation in jury awards force carriers to recalibrate attachment points and aggregate limits.
Market Dynamics
Social inflation in jury awards is compressing attachment points and forcing carriers to recalibrate aggregate limits across both commercial and personal lines, fundamentally altering capital deployment strategies.
Growth Catalysts
- Nuclear Verdicts in Employment Practices:California, Texas, and Florida courts are delivering outsized liability judgments that push corporations toward higher excess limits. Commercial umbrella placements accelerate as risk managers seek protection against eight-figure settlements.
- ISO Standardized Policy Forms:Uniform contract language reduces friction in policy comparison and accelerates placement velocity. Independent agents leverage these forms to streamline quoting across multiple admitted carriers.
- Mass-Affluent Household Asset Appreciation:Real estate and investment portfolio growth among professionals with one to five million dollars in net worth is expanding the addressable market for personal umbrella coverage beyond traditional high-net-worth segments.
Market Restraints
- Long-Tail Liability Reserve Volatility:Asbestos, environmental, and latent injury claims require decades of capital lockup. Berkshire Hathaway and other scale players absorb this burden while smaller carriers exit the segment.
- Reinsurance Capacity Concentration:Bermuda and London markets control the bulk of catastrophe excess-of-loss capacity. Primary carriers face attachment point resets when global property-catastrophe losses tighten retrocessional markets.
- State Rate Filing Friction:Insurance commissioners in New York, Illinois, and Ohio impose extended review timelines for umbrella rate increases. Regulatory lag prevents carriers from matching pricing to loss cost trends within a single underwriting year.
Strategic Opportunities
- Underpenetrated Midwest Suburban Markets:Ohio, Michigan, and Wisconsin show lower personal umbrella penetration relative to coastal states. Independent agent networks in these geographies retain strong placement influence with less direct-channel competition.
- Cyber Liability Convergence:Traditional bodily injury and property damage umbrella forms increasingly exclude cyber events. Carriers developing affirmative cyber excess coverage capture premium from technology and healthcare verticals.
- Online Broker Channel Expansion:Digital platforms are gaining share in standardized personal lines where coverage terms homogenize. Mass-affluent buyers with simpler risk profiles complete purchases without agent involvement.
Industry Challenges
- Actuarial Talent Scarcity in Excess Layers:Pricing catastrophe and clash covers requires specialized modeling expertise. Carriers compete for underwriters with experience in multi-line aggregate accumulation.
- Legacy Policy Administration System Integration:Many regional carriers operate on decades-old core systems that cannot support real-time exposure aggregation across primary and excess layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Umbrella Insurance Market |
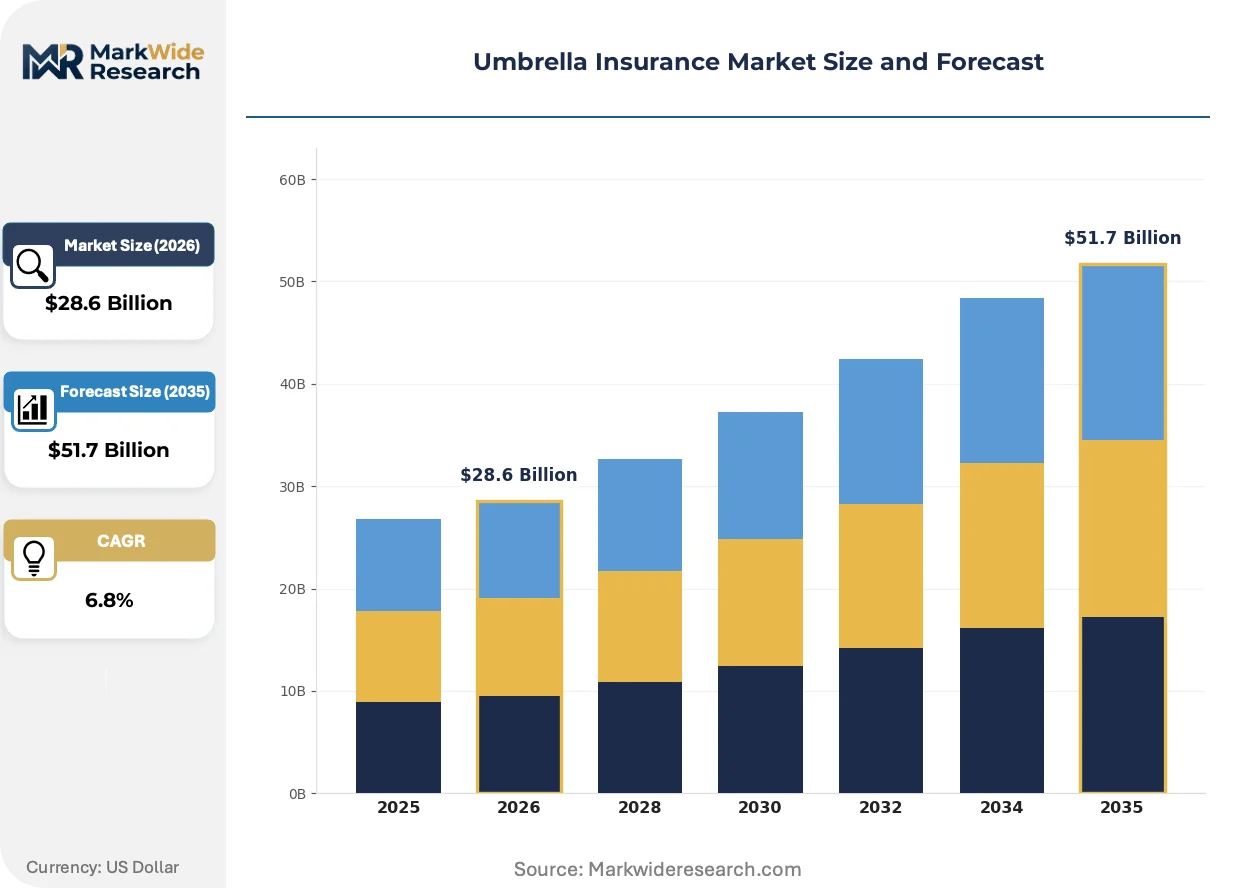
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Personal Umbrella, Commercial Umbrella, Employer's Liability, Excess Liability Client Type: Individuals, Small Businesses, Corporations, Non-Profits Policy Features: Worldwide Coverage, Legal Defense, Personal Injury Protection, Property Damage Distribution Channel: Online Brokers, Insurance Agents, Direct Sales, Financial Advisors |
| Companies Covered | Amica, CIS Commercial Insurance Solutions, Travelers, Ramey & King Insurance, Franklin Street Insurance, biBERK, Pathfinder Insurance, Berkshire Hathaway, Chubb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Umbrella Insurance Market Emerging Trajectories
Predictive analytics and litigation funding transparency are reshaping how carriers price frequency-severity profiles and manage aggregate accumulation across correlated exposures.
Telematics-enabled risk scoring is consolidating personal umbrella underwriting around verified behavioral data rather than proxy variables. Carriers integrating driving records, property IoT sensors, and public records into unified risk scores refine pricing granularity. Mass-affluent households with demonstrably lower claim frequency capture rate advantages that compress cross-subsidization in standard tiers.
The SEC's climate disclosure rules are extending into insurance holding company reporting requirements. Carriers must now quantify and disclose climate-related transition risks in their liability portfolios. Commercial umbrella underwriters in California and Florida are responding by incorporating flood and wildfire liability exposure into pricing models for real estate-heavy insureds.
Mass-affluent buyers are unbundling personal lines procurement from traditional agency relationships. Direct-to-consumer platforms and online brokers capture placement value in standardized coverage tiers where terms converge across carriers. This channel rotation is most visible in Texas and Florida suburban markets where digital-native demographics intersect with high property values requiring excess protection.
Umbrella Insurance Market Segmentation
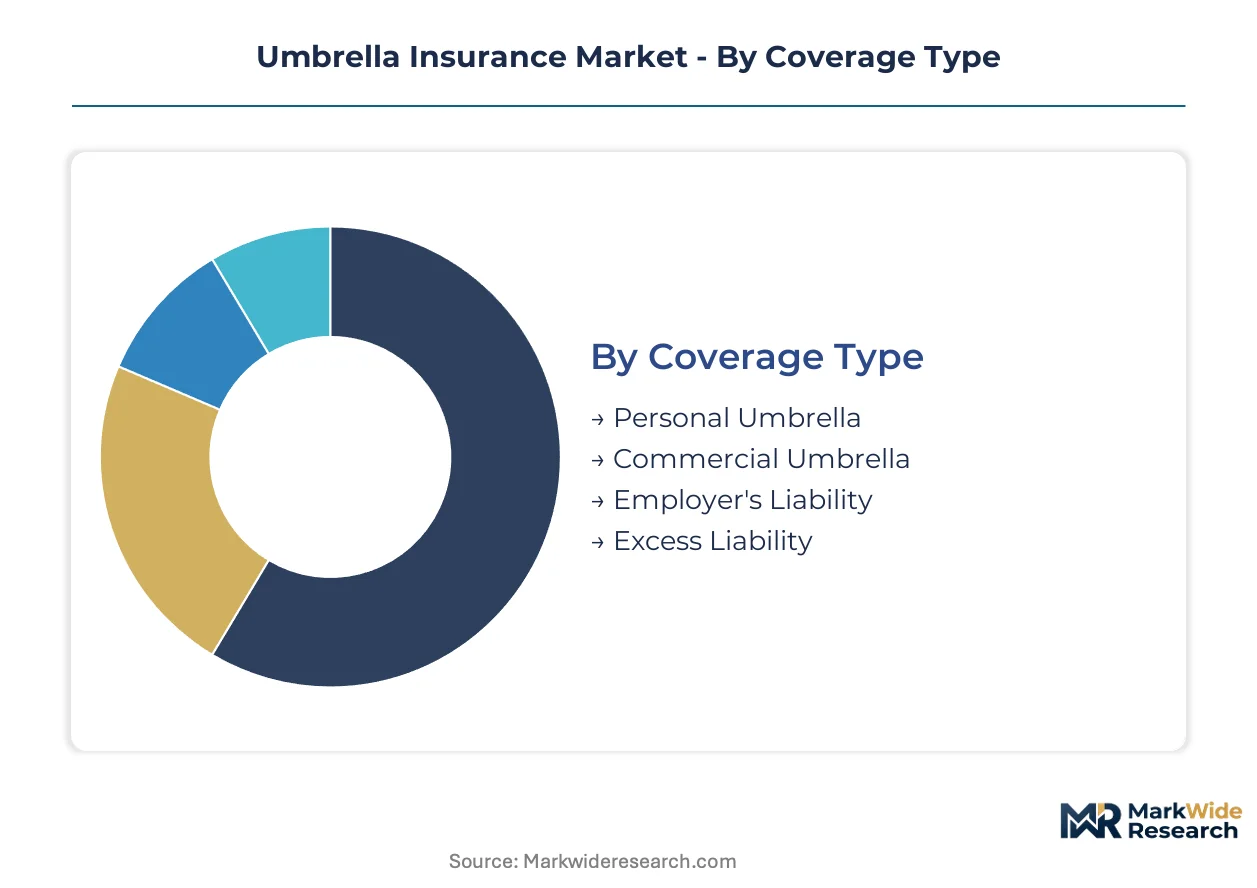
Umbrella insurance segmentation reflects divergent risk profiles between personal and commercial buyers, with coverage architecture, client sophistication, and distribution economics creating distinct strategic pockets. Carriers calibrate capital allocation and pricing models differently across these dimensions.
Coverage Type:
Attachment thresholds and liability triggers define how excess layers stack above primary policies, with coverage architecture determining capital intensity and reserve duration.
- Personal Umbrella:Activates at one to five million dollars above homeowners or auto primary limits, covering bodily injury and property damage claims against individuals. Demand concentrates in California, Texas, and Florida where real estate appreciation and litigation frequency push mass-affluent households toward excess protection.
- Commercial Umbrella:Provides excess coverage above general liability, auto, and employers primary policies for corporations facing nuclear verdicts. Corporate risk managers in California, Texas, and Florida drive placements as employment practices and product liability settlements escalate into eight-figure ranges.
- Employer's Liability:Extends workers compensation exclusions into excess layers for catastrophic workplace injuries.
- Excess Liability:Follows form above scheduled underlying policies with narrower coverage grants.
Mature deployment sits with Commercial Umbrella. Newer deployment is concentrated in Personal Umbrella.
Client Type:
Premium volume and underwriting complexity correlate directly with organizational scale and asset concentration.
- Corporations:Generate the majority of commercial umbrella premium through multi-layer tower placements requiring sophisticated clash coverage and aggregate monitoring. Risk managers in asset-heavy sectors negotiate ten to fifty million dollar limits across admitted and excess markets.
- Individuals:Represent the expanding addressable market as mass-affluent households with one to five million dollars in net worth seek protection against personal liability claims. Independent agents and online brokers compete for this segment where coverage terms have homogenized.
- Small Businesses:Purchase simplified umbrella endorsements above business owners policies.
- Non-Profits:Face unique director and officer exposure requiring specialized excess forms.
Corporations anchor current premium volume. Individuals are gaining share fastest.
Policy Features:
Coverage grants differentiate premium positioning, with feature breadth determining placement channel and buyer sophistication.
- Legal Defense:Covers attorney fees and court costs outside policy limits, a critical value driver for commercial buyers facing protracted litigation. Corporations in California and Florida prioritize this feature given jurisdiction-specific discovery rules and plaintiff bar activity.
- Worldwide Coverage:Extends protection to foreign occurrences and suits brought outside the United States. Ultra-high-net-worth households with international real estate holdings and multinational corporations require this feature, commanding premium pricing from specialized carriers.
- Personal Injury Protection:Addresses libel, slander, and privacy violations excluded from standard liability forms.
- Property Damage:Covers physical destruction claims above primary auto or homeowners limits.
Legal Defense commands widest adoption. Worldwide Coverage shows steepest expansion trajectory.
Distribution Channel:
Channel economics shape carrier go-to-market investment, with placement value concentrating where advice complexity intersects with buyer trust.
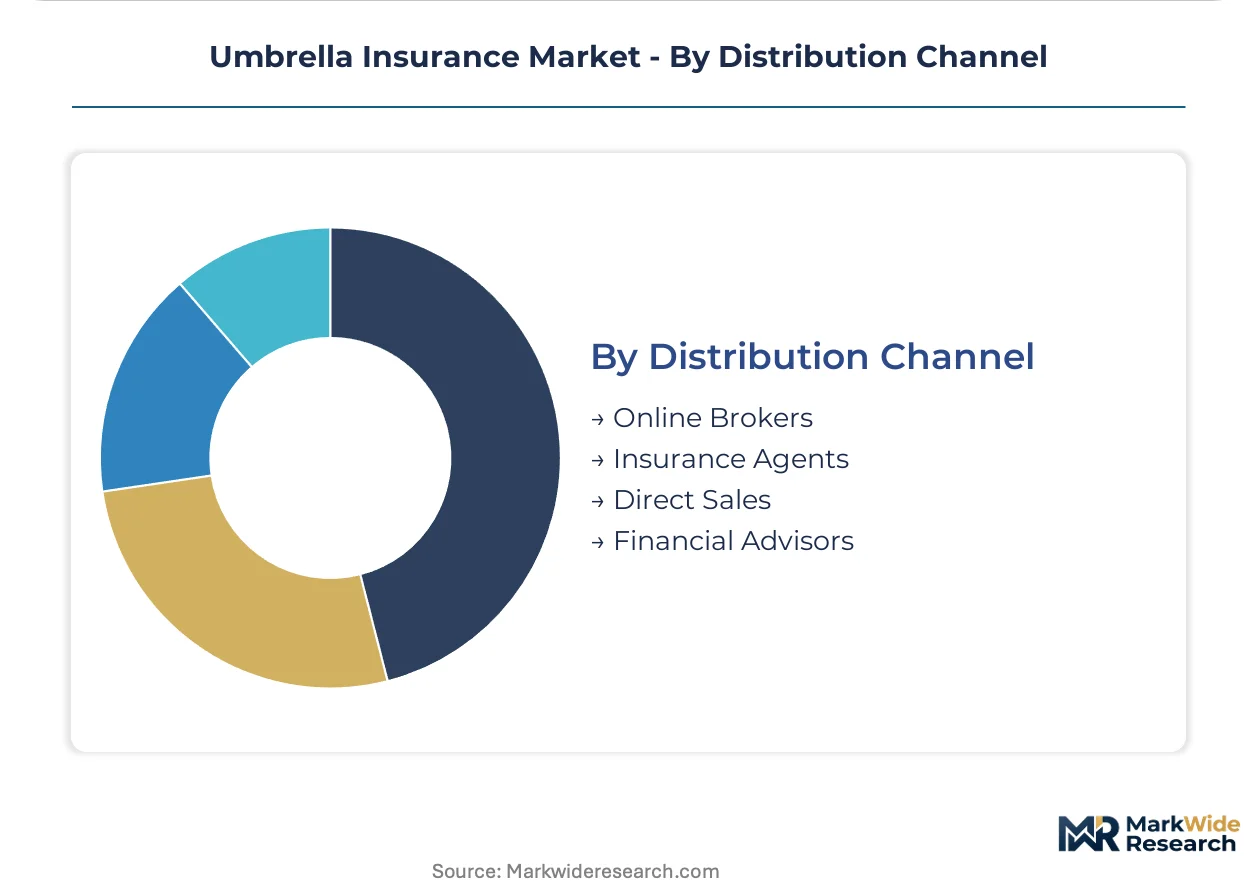
- Insurance Agents:Capture majority placement value through captive and independent networks, particularly for commercial umbrella requiring coverage design expertise. Travelers and Chubb prioritize agent relationships for complex risk placements where terms negotiation and claims advocacy matter.
- Online Brokers:Gain share in standardized personal umbrella tiers where coverage homogenization enables algorithmic quoting. Digital platforms target mass-affluent buyers in Texas and Florida suburban markets with simplified application workflows and immediate binding authority.
- Direct Sales:Serves high-volume personal lines through carrier-owned digital channels.
- Financial Advisors:Cross-sell umbrella coverage within wealth management relationships.
Insurance Agents retain commercial dominance. Online Brokers are penetrating personal lines most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan anchors the highest concentration of commercial umbrella placements, with corporate risk managers in the New York Metro negotiating multi-layer towers above ten million dollars as litigation frequency in federal district courts escalates.
United States
California, Texas, and Florida generate the majority of personal and commercial umbrella premium as nuclear verdicts in employment practices and product liability push attachment points higher. State insurance commissioners in New York, Illinois, and Ohio impose extended rate filing timelines that create regulatory lag against loss cost trends. The New York Metro and South Florida corridors concentrate ultra-high-net-worth households requiring complex global coverage structures.
United Kingdom
London's Lloyd's market provides reinsurance capacity that backs primary carriers' excess-of-loss layers across European and North American risks. The Prudential Regulation Authority and Financial Conduct Authority coordinate solvency standards and market conduct examinations for admitted carriers. The City of London remains the dominant hub for international commercial umbrella placements requiring clash coverage and aggregate monitoring.
Germany
Industrial conglomerates in Bavaria and North Rhine-Westphalia drive demand for employer's liability extensions above statutory workers compensation limits. BaFin supervises reserve adequacy and rate adequacy for domestic carriers writing commercial umbrella coverage. The Munich reinsurance cluster supplies retrocessional capacity that stabilizes primary market attachment points during catastrophe loss cycles.
France
Luxury goods manufacturers and aerospace suppliers in Île-de-France seek worldwide coverage extensions for product liability exposures in North American courts. The Autorité de Contrôle Prudentiel et de Résolution enforces Solvency II capital requirements for carriers writing excess layers. The Paris commercial insurance market specializes in complex international programs for multinational corporations.
Australia
Mining and resource companies in Western Australia and Queensland purchase commercial umbrella coverage above primary general liability for catastrophic environmental and workplace incidents. The Australian Prudential Regulation Authority monitors insurer solvency and reserve strength for long-tail liability exposures. Sydney and Melbourne house the dominant broker networks placing excess coverage for Asia-Pacific regional programs.
Umbrella Insurance Market Vendor Landscape
Premium-margin players sit above commodity-margin players across distribution sophistication and underwriting specialization. The market structures around three tiers: scale-driven national carriers with captive agent networks, specialized excess liability underwriters with reinsurance backing, and digital-first platforms targeting standardized personal lines. Consolidation pressure favors carriers with long-tail reserve expertise and clash coverage modeling capabilities. Strategic moves concentrate on deepening agent relationships for commercial placements and acquiring predictive analytics capabilities for personal lines pricing.
Within the scale-driven tier, Berkshire Hathaway and Travelers exemplify divergent paths to market position. Berkshire Hathaway occupies a position anchored by reinsurance scale and long-duration reserve management. Travelers sits within the agent-centric commercial segment where specialized underwriting teams capture complex risk placements. Chubb represents the white-glove service archetype targeting ultra-high-net-worth households with international exposure requirements.
| Leading Market Players |
|---|
| Amica |
| CIS Commercial Insurance Solutions |
| Travelers |
| Ramey & King Insurance |
| Franklin Street Insurance |
| biBERK |
| Pathfinder Insurance |
| Berkshire Hathaway |
| Chubb |
| Others |
Supply Flow & Price Mechanics
Captive reinsurance arrangements in Bermuda and London anchor both the supply position and pricing power for primary carriers seeking excess-of-loss backing. This integration choice allows admitted carriers in California, Texas, and Florida to stabilize attachment point pricing while Bermuda markets absorb catastrophe volatility through long-duration capital lockup.
Pricing Analysis
Outcome-based pricing tied to claims frequency performance anchors commercial umbrella contracts, with corporations in litigation-heavy jurisdictions paying premiums scaled to historical loss ratios. Three-tier pricing structure across premium, standard, and economy levels separates white-glove service models from commoditized personal lines. Cost compression in the mass-affluent personal segment is intensifying because online brokers automate underwriting and strip advisory fees. Small businesses show highest price sensitivity, while ultra-high-net-worth households prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Reverse-logistics flows in long-tail liability reserving create capital recycling challenges, as asbestos and environmental claims require decades of reserve maintenance before final settlement. Reinsurance capacity concentrates in Bermuda, London, and Munich, with retrocessional markets drawing from catastrophe bond issuance and collateralized reinsurance structures. Single-source vulnerability sits with Lloyd's syndicate capacity for clash coverage and multi-line aggregate protection. Distribution runs through captive agent networks for commercial placements and digital platforms for standardized personal lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Umbrella insurance functions as a cost-of-compliance story where state rate filing requirements under NAIC coordination create barrier-to-entry moats for carriers with established regulatory relationships and reserve adequacy track records.
For Market Incumbents: Cement dominance in commercial excess layers by deepening captive agent relationships and acquiring predictive analytics capabilities for personal lines frequency scoring. Defend against direct-channel disintermediation by embedding legal defense services and worldwide coverage as non-negotiable policy features. Capacity addition in underpenetrated Midwest suburban markets offers geographic diversification from coastal litigation concentration. For New Entrants and Emerging Players: The price-point gap between premium-tier white-glove service and economy-tier digital placement creates white-space opportunity in mass-affluent suburban markets. Target Ohio, Michigan, and Wisconsin where independent agent influence persists and direct-channel competition remains muted. Affirmative cyber excess coverage for technology and healthcare verticals offers specialized entry with lower capital requirements than general liability stacking. For Investors and Strategic Acquirers: Exit pathways concentrate in reinsurance-backed scale carriers with demonstrated long-tail reserve management expertise. Long-term viability favors carriers with clash coverage modeling capabilities and multi-line aggregate monitoring infrastructure. Watch litigation funding transparency regulation as the signal indicating when social inflation assumptions require fundamental recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Analytics Acquisition | Telematics integration with driving records and property IoT sensors refines personal lines pricing granularity. |
| Midwest Agent Network Expansion | Independent agent relationships in Ohio and Wisconsin capture underpenetrated mass-affluent households with appreciating real estate. |
| Cyber Liability Coverage Development | Affirmative cyber excess forms address coverage gaps in traditional bodily injury and property damage umbrellas. |
| Climate Risk Disclosure Integration | SEC climate rules extend into holding company reporting, requiring flood and wildfire liability exposure quantification. |
| Long-Tail Reserve Expertise Consolidation | Asbestos and environmental claim management capabilities create sustainable competitive moats against smaller regional carriers. |
Methodological Framework
Document review covered NAIC financial solvency filings, state insurance commissioner rate filing databases, and SEC disclosure requirements for publicly traded carriers, complemented by interviews with commercial underwriting executives, independent agency principals, reinsurance brokers, and corporate risk managers. Secondary validation drew from ISO standardized policy form documentation, Lloyd's market capacity reports, and Bermuda Monetary Authority regulatory filings. Bottom-up policy count and premium volume estimates triangulated against top-down market size assessments from regulatory aggregates.
Historical premium growth patterns cross-referenced against panel input from underwriting executives informed the analytical framework across the analysis window. Segmentation dimensions modeled include coverage type, client sophistication tier, policy feature breadth, and distribution channel. CAGRs derived from loss cost trend analysis, attachment point reset frequency, and reinsurance capacity cycle positioning. Industry-specific forecast inputs incorporated litigation funding database growth and social inflation indices from nuclear verdict tracking.
Inputs from state insurance commissioners and Lloyd's syndicate capacity reports were available through the study window; gaps in latent injury claim development data introduce uncertainty bands around long-tail liability reserve adequacy assumptions. Forecasts reflect documented assumptions regarding tort reform legislative activity and reinsurance market softening cycles. Material deviation in nuclear verdict frequency or retrocessional market capacity contraction warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Road Assistance Insurance Market
Insurance
Asia-Pacific Insurance Aggregators Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
Dental Insurance Market
Insurance
India Liability Insurance Market
Insurance
Financial Guarantee Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Europe Bancassurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Takaful Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Africa Insurance Market