
 Russia Property and Casualty Insurance Market | 2026-2036
Russia Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Property and Casualty Insurance Market Analytics
Project finance and reinsurance-backed capital structures is tilting competitive dynamics toward carriers with stronger balance-sheet depth. RESO Garantia leverages its extensive regional branch network to sustain premium volume across Russia's federal districts. Sogaz Insurance anchors its position through dominant relationships with state-linked industrial enterprises. Ingosstrakh Insurance Company differentiates via specialized coverage for complex infrastructure and energy assets.
Property and casualty insurance encompasses risk transfer mechanisms covering physical asset damage, legal liability exposure, and financial loss from insured events, with policies structured around actuarial pricing models, deductible tiers, and claims-adjustment protocols designed to restore policyholders to pre-loss financial positions. Auto and property policy types lead premium generation, while online platform distribution channels represent the fastest-expanding access route as digital onboarding reduces acquisition costs. SME end users command disproportionate attention from underwriters seeking to diversify beyond saturated individual motor coverage segments.
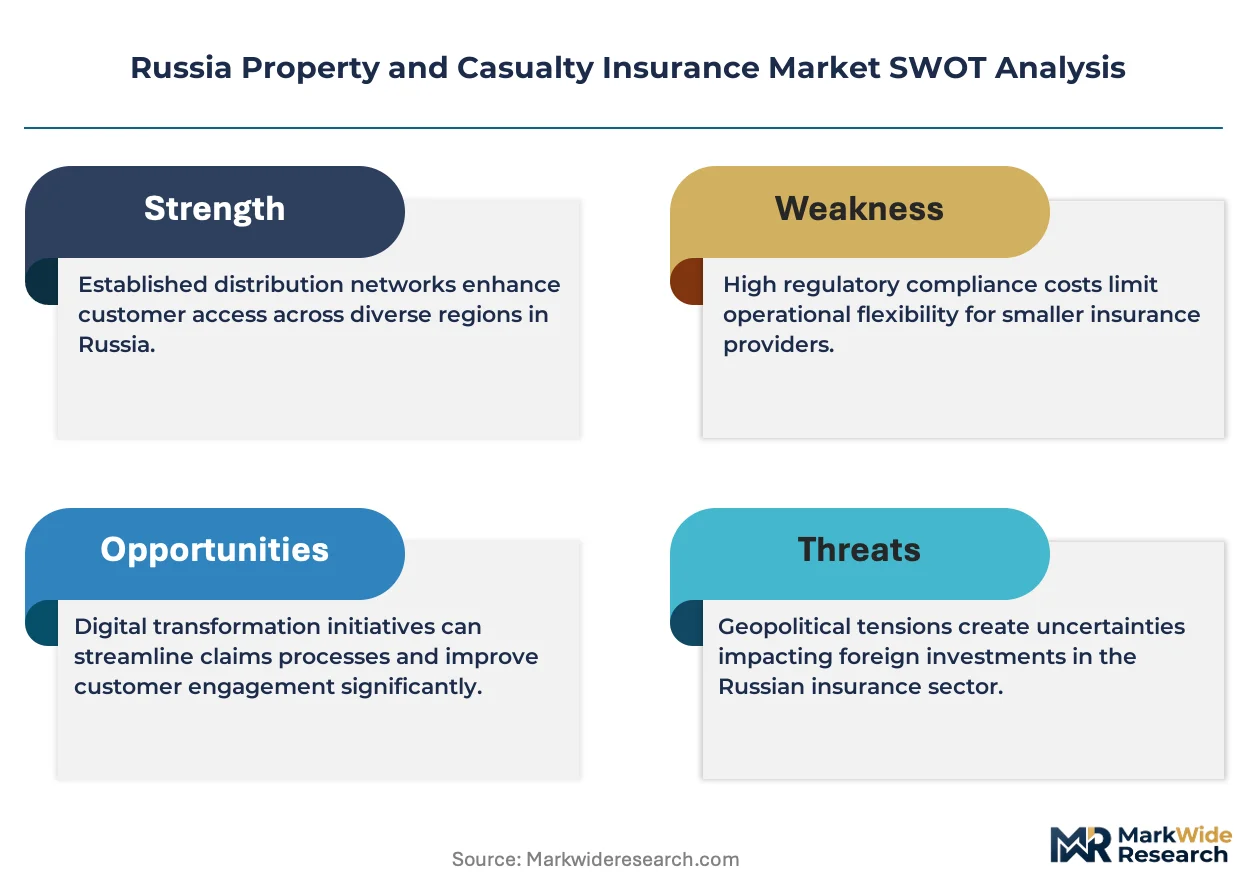
The Central Bank of Russia mandates capital adequacy ratios and consumer protection standards that directly shape product design and pricing flexibility across all licensed carriers. Federal Law on Compulsory Motor Third-Party Liability Insurance establishes minimum coverage thresholds that elevate baseline demand while constraining premium competition. Stakeholders must monitor how sanctions-related capital flow restrictions alter reinsurance access and foreign partner capacity.
Market Dynamics
The Central Bank of Russia's capital adequacy mandates are compressing underwriting flexibility while simultaneously forcing carriers toward sophisticated risk-pooling mechanisms and reinsurance partnerships.
Growth Catalysts
- Mandatory Motor Third-Party Liability:Federal Law establishes baseline coverage thresholds that guarantee premium inflows across all vehicle-owning households and commercial fleets.
- SME Risk Awareness:Small and medium enterprises in Moscow and St. Petersburg are purchasing property and business interruption coverage at accelerating rates following operational disruption episodes.
- Digital Onboarding Platforms:Mobile-first policy issuance is collapsing acquisition costs and expanding addressable reach into secondary cities and remote federal districts.
Market Restraints
- Reinsurance Access Constraints:Capital flow restrictions linked to sanctions frameworks are limiting Russian carriers' ability to secure foreign-backed risk capacity.
- Concentrated Commercial Asset Geography:Moscow and the Central Federal District generate disproportionate premium volume, leaving carriers exposed to correlated catastrophic loss events.
- Interest Rate Compression:Low-yield environments constrain investment income that traditionally subsidizes underwriting operations.
Strategic Opportunities
- Underpenetrated Far Eastern Districts:Vladivostok and Khabarovsk commercial hubs present untapped demand for industrial property and cargo transit coverage.
- Parametric Weather Products:Index-based triggers for agricultural and infrastructure assets are bypassing traditional claims-adjustment bottlenecks.
- Cyber Liability Expansion:Regulatory pressure on data protection is driving mid-market enterprises toward first-party cyber risk transfer mechanisms.
Industry Challenges
- Actuarial Talent Scarcity:Shortages of professionals skilled in predictive modeling and catastrophe risk assessment are delaying product development cycles.
- Legacy Core System Integration:Incumbent carriers face friction connecting modern API-driven distribution layers to decades-old policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Property and Casualty Insurance Market |
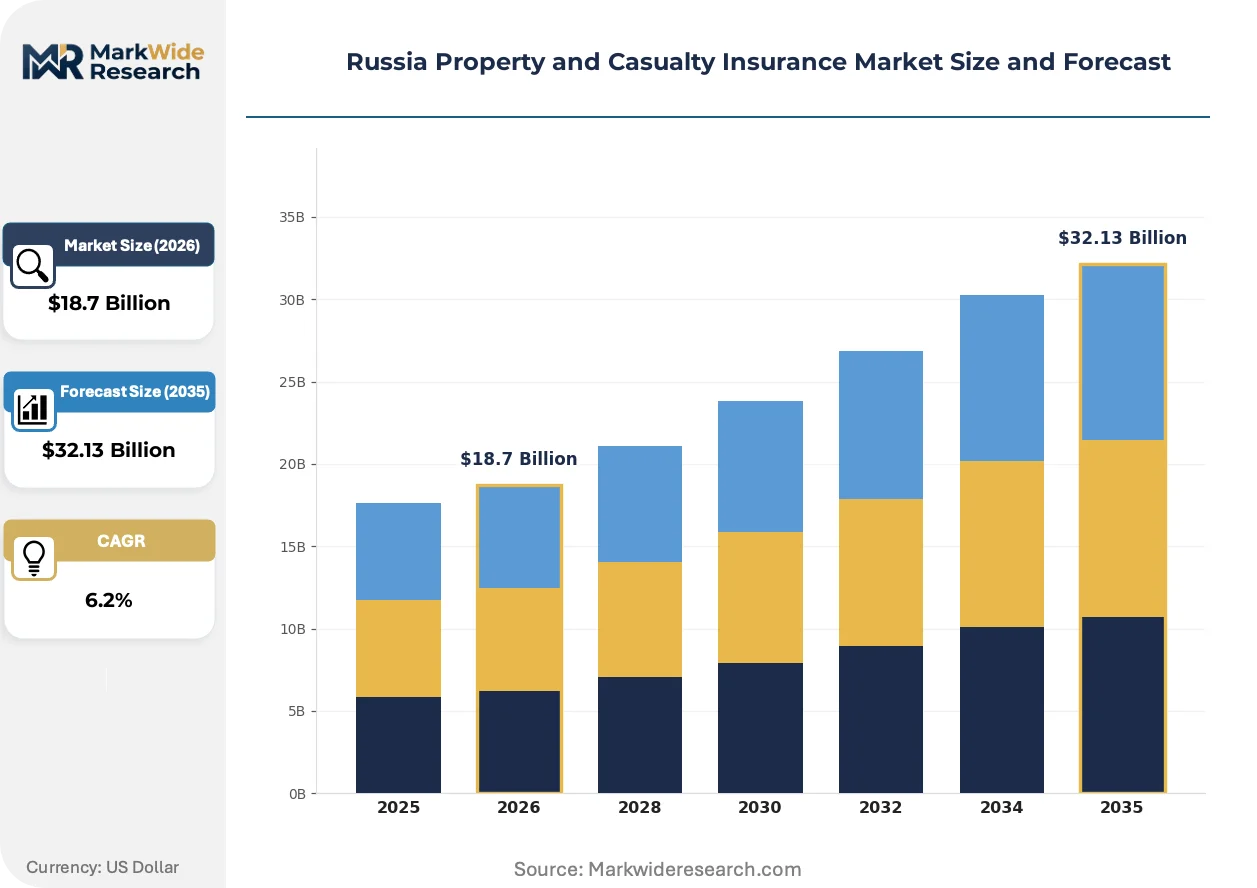
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Auto, Property, Liability, Travel Distribution Channel: Direct Sales, Brokers, Online Platforms, Banks Coverage Scope: Comprehensive, Third-party, Fire, Theft End User: Individuals, SMEs, Corporates, Government |
| Companies Covered | RESO Garantia, Sogaz Insurance, Rosgosstrakh Insurance Company, Zurich Reliable Insurance, VSK Insurance, Ingosstrakh Insurance Company, Sberbank Insurance, Renaissance Insurance, AlfaStrakhovanie, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Property and Casualty Insurance Market Evolving Landscape
Telematics, algorithmic underwriting, and usage-based pricing models are converging to transform how risk is measured, priced, and transferred across personal and commercial lines.
Telematics hardware and smartphone-based driving behavior monitoring is hybridizing traditional motor rating methodologies with real-time data streams. Fleet operators and individual policyholders in Moscow and St. Petersburg are adopting these programs fastest. This convergence is compressing loss ratios for early-adopting carriers while segmenting the market into behavior-priced tiers.
The Central Bank of Russia's consumer protection standards are tightening disclosure requirements and claims-handling timelines. Licensed carriers must now demonstrate transparent pricing methodologies and accelerated settlement protocols. SME and individual motor segments face the steepest compliance investments as they retool customer-facing processes.
Broker channel consolidation is displacing traditional agency networks as large intermediaries capture volume through digital comparison platforms. Regional independent agents in secondary cities are losing share to Moscow-headquartered digital brokers. This concentration is most visible in the auto and property personal lines segments where price transparency tools dominate purchase decisions.
Russia Property and Casualty Insurance Market Segmentation
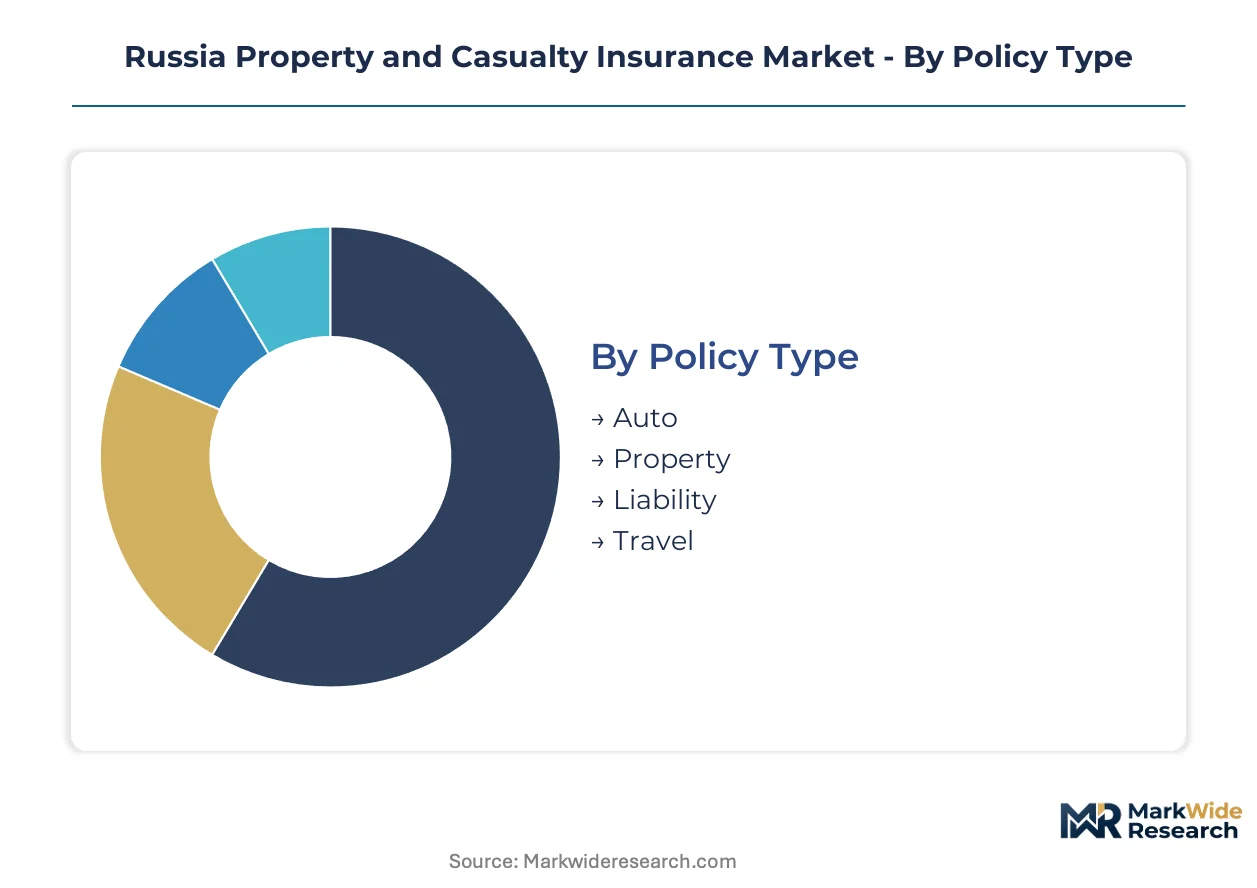
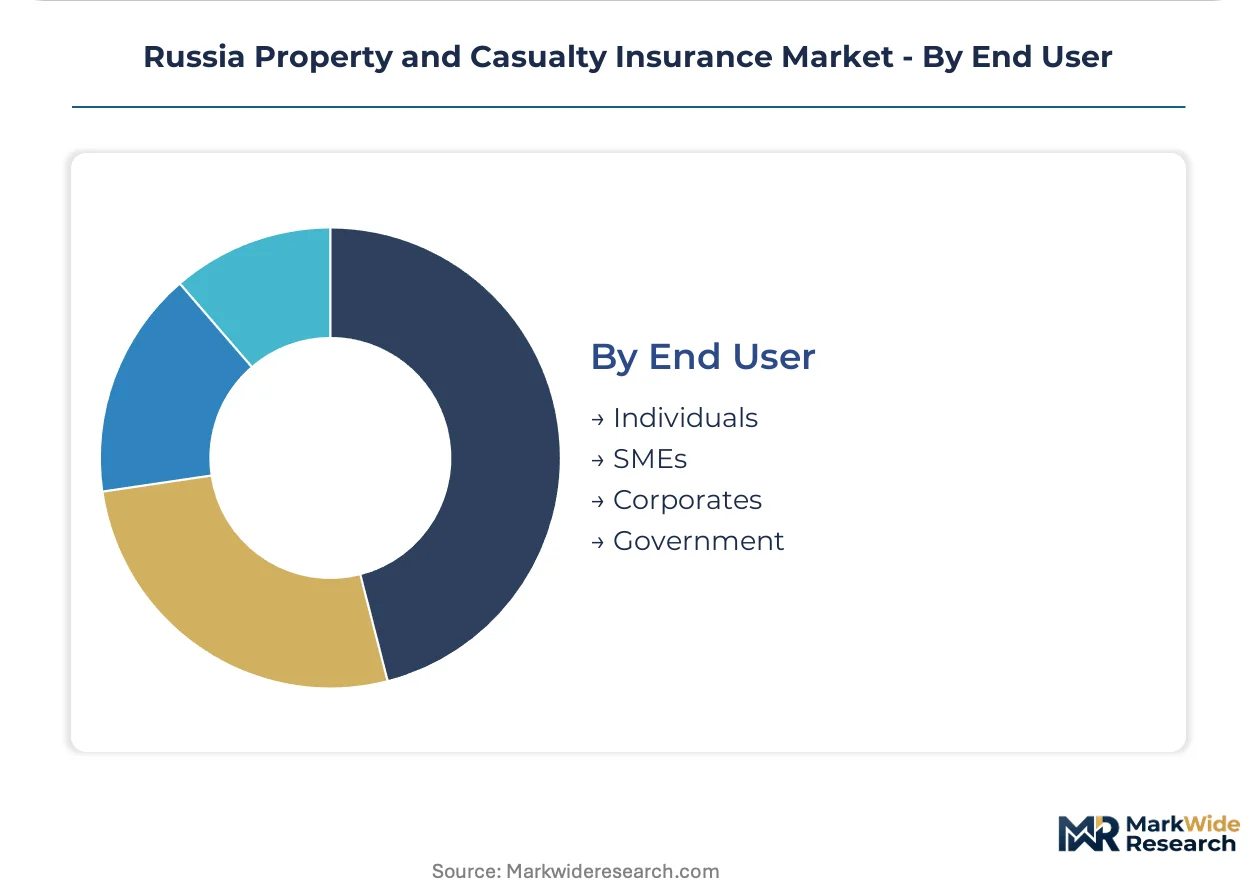
Risk transfer mechanisms in Russia's property and casualty insurance market fragment across policy structures, distribution pathways, coverage depth, and purchaser scale. Each segmentation axis reveals distinct margin profiles, regulatory exposure, and growth velocity that shape carrier resource allocation.
Policy Type:
Mature personal lines dominate premium volume while emerging commercial categories reshape competitive positioning.
- Auto:Mandatory motor third-party liability under Federal Law guarantees baseline inflows across all vehicle-owning households and commercial fleets. Moscow and St. Petersburg fleet operators generate disproportionate premium density as telematics adoption accelerates behavior-based pricing segmentation.
- Property:Physical asset coverage spans residential dwellings, commercial buildings, and industrial facilities with actuarial models calibrated to regional catastrophe exposure. SME purchasers in the Central Federal District are expanding coverage limits following operational disruption episodes.
- Liability:Legal exposure transfer for professional negligence and product defects serves corporate risk management programs.
- Travel:Short-term medical and trip cancellation products target outbound leisure and business travelers.
Auto handles the majority of throughput; Property is expanding most quickly on share.
Distribution Channel:
Cost tier stratification separates high-touch advisory relationships from automated acquisition pathways.
- Direct Sales:Carrier-owned branch networks and call centers sustain premium volume across Russia's federal districts. RESO Garantia leverages its extensive regional presence to capture renewals through face-to-face policy servicing.
- Brokers:Large intermediaries consolidate volume through digital comparison platforms, displacing independent agents in secondary cities. Price transparency tools dominate auto and property personal lines purchase decisions.
- Online Platforms:Mobile-first issuance collapses acquisition costs and expands addressable reach into remote federal districts.
- Banks:Bancassurance partnerships embed policies within lending products and deposit relationships.
Brokers command the largest share of new business flow; Online Platforms are climbing the fastest on volume contribution.
Coverage Scope:
Application intensity varies by asset protection priority and regulatory mandate.
- Comprehensive:All-risk protection combining property damage, liability, and business interruption within unified policy structures. Industrial enterprises in state-linked sectors anchor demand through Sogaz Insurance relationships.
- Third-party:Minimum legal coverage thresholds established by federal statute guarantee baseline market size. Central Bank of Russia capital adequacy mandates constrain pricing flexibility in this commoditized segment.
- Fire:Named peril coverage for structural and content damage from combustion events.
- Theft:Criminal loss protection for movable assets and inventory.
Comprehensive policies generate the highest premium per contract; Third-party coverage maintains the broadest policy count base.
End User:
Customer type determines risk sophistication, price sensitivity, and service expectation profiles.
- Individuals:Personal motor and residential coverage purchases concentrate in Moscow and St. Petersburg where asset density and risk awareness align. Digital onboarding reduces friction for first-time policyholders.
- SMEs:Small and medium enterprises seek protection against operational disruptions with accelerating adoption in Moscow commercial corridors. Underwriters target this segment to diversify beyond saturated individual motor coverage.
- Corporates:Large industrial and infrastructure assets require specialized coverage for complex energy and construction exposures.
- Government:State entity procurement follows public tender protocols with dominant relationships concentrated among carriers with federal accreditation.
Individuals account for the greatest policy count; SMEs are gaining share fastest on premium growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Russia's property and casualty insurance flows concentrate in import-dependent metropolitan hubs where foreign equipment and commercial assets require protection, while export-oriented industrial zones in the Urals and Far East generate specialized cargo and infrastructure coverage demand.
Central Federal District
Moscow anchors premium generation through dense corporate headquarters and high-value commercial real estate portfolios. The Central Bank of Russia's capital adequacy mandates shape product availability across this district. Moscow's financial district concentrates underwriting expertise and broker intermediation capacity.
Northwestern Federal District
St. Petersburg's port infrastructure and manufacturing bases drive marine cargo and industrial property coverage procurement. Federal Law on Compulsory Motor Third-Party Liability extends baseline auto coverage throughout the district. The city's automotive assembly clusters generate fleet insurance demand from commercial vehicle operators.
Volga Federal District
Nizhny Novgorod and Kazan manufacturing centers sustain demand for equipment breakdown and business interruption policies. Regional branch networks of major carriers penetrate secondary cities with standardized product suites. The district's chemical and machinery plants require specialized industrial risk transfer mechanisms.
Ural Federal District
Yekaterinburg's mining and metals processing operations anchor demand for heavy industrial asset coverage. State-linked procurement protocols favor carriers with federal accreditation in this resource-extraction zone. The district's commodity export infrastructure generates transit and storage risk transfer requirements.
Far Eastern Federal District
Vladivostok and Khabarovsk commercial hubs present underpenetrated demand for cargo transit and industrial property coverage. The Central Bank of Russia's regulatory framework extends to these peripheral markets with modified capital requirements. Pacific port development projects are drawing infrastructure coverage interest from specialized underwriters.
Russia Property and Casualty Insurance Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in risk assessment and claims servicing layers. The Russian property and casualty insurance structure consolidates around state-affiliated conglomerates and privately held national carriers with federal branch networks. Three archetypes dominate: balance-sheet-heavy incumbents with reinsurance access, digitally native intermediaries collapsing distribution costs, and regionally embedded specialists serving industrial niches. Competitive dynamics center on branch network expansion into underpenetrated federal districts and API-driven partnerships with digital distribution platforms.
Within the state-linked tier, Sogaz Insurance occupies a position anchored to industrial enterprise relationships, while RESO Garantia exemplifies the regionally distributed archetype through its extensive federal district presence. Ingosstrakh Insurance Company represents the specialized infrastructure segment, serving complex energy and construction asset coverage requirements. These three carriers illustrate how competitive positioning stratifies across relationship depth, geographic reach, and technical underwriting capability.
| Leading Market Players |
|---|
| RESO Garantia |
| Sogaz Insurance |
| Rosgosstrakh Insurance Company |
| Zurich Reliable Insurance |
| VSK Insurance |
| Ingosstrakh Insurance Company |
| Sberbank Insurance |
| Renaissance Insurance |
| AlfaStrakhovanie |
| Others |
Value Network & Pricing Analysis
Reinsurance capacity concentration in London, Zurich, and Singapore directly determines where underwriting margin pools accumulate downstream. Russian carriers facing capital flow restrictions must absorb more risk on-balance-sheet, compressing pricing flexibility for complex commercial coverage while elevating retention requirements for mandatory motor lines.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term pricing structure across commercial property and liability segments. Premium differentiation hinges on claims history quality and Central Bank of Russia solvency tier certification, with fleet operators in Moscow commanding standard rates while remote district purchasers face geographic delivery cost loading. Pricing pressure stems from investment income compression as low-yield environments constrain traditional underwriting subsidies. SMEs exhibit highest price sensitivity due to constrained risk management budgets, whereas state-linked corporates prioritize coverage breadth over premium minimization.
Supply Chain Analysis
Domestic actuarial talent pools in Moscow and St. Petersburg hold analytical capacity, with secondary support from Belarus and Kazakhstan technical institutes. Risk assessment infrastructure draws from satellite imagery providers, telematics hardware manufacturers, and catastrophe modeling software vendors. Single-source vulnerability concentrates in foreign reinsurance treaty access, where sanctions frameworks restrict capacity placement. Distribution runs through carrier-owned branch networks, digital broker platforms, and bancassurance partnerships embedded within Sberbank lending relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized underwriting capability for complex energy and infrastructure assets represents the scarcest competitive resource in this market. Carriers possessing actuarial depth and reinsurance relationships command disproportionate positioning power as regulatory capital requirements tighten.
For Market Incumbents: Build regulatory compliance moats through accelerated Central Bank of Russia solvency tier advancement and transparent claims-handling protocol certification. Consolidate branch network presence in underpenetrated Far Eastern Federal District hubs before digital-native intermediaries capture SME flows. Defensive investments in API-driven policy administration modernization will offset legacy system friction threatening retention rates. For New Entrants and Emerging Players: Mid-market commercial buildings in Vladivostok and Khabarovsk represent the most penetrable entry point, where incumbent branch density remains thin and cargo transit coverage demand outpaces supply. Parametric weather products for agricultural assets in the Volga Federal District offer technical differentiation without traditional claims-adjustment infrastructure requirements. Go-to-market execution should prioritize direct digital onboarding partnerships with regional logistics associations. For Investors and Strategic Acquirers: Capital is best deployed toward carriers with demonstrated reinsurance treaty access and specialized infrastructure underwriting teams. Long-term viability across the projection horizon rests on balance-sheet depth sufficient to absorb retention increases as foreign capacity constraints persist. Watch for Central Bank of Russia regulatory forbearance signals as inflection indicators of sector consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reinsurance Treaty Diversification | London and Dubai capacity access reduces single-market dependency for Russian carriers. |
| Telematics Platform Integration | Real-time driving data from Moscow fleet operators compresses motor loss ratios. |
| Parametric Product Development | Index-based agricultural triggers bypass claims-adjustment bottlenecks in remote districts. |
| Branch Network Optimization | Far Eastern Federal District expansion captures underpenetrated cargo coverage demand. |
| Core System Modernization | API-driven policy administration connects digital broker platforms to legacy infrastructure. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with underwriting directors, actuarial leads, broker network heads, and Central Bank of Russia regulatory officials; and secondary validation through carrier financial disclosures, reinsurance treaty filings, and regional premium registration databases. Bottom-up policy count and premium volume estimates were triangulated against top-down macroeconomic and asset stock projections.
Forecast outputs reflect modeled trajectories across policy type, distribution channel, coverage scope, and end-user segmentation dimensions. CAGRs were derived from historical premium growth patterns, regulatory mandate expansion schedules, and SME penetration rate assumptions. Key inputs included motor vehicle fleet growth projections, commercial real estate development pipelines, and digital onboarding adoption curves.
Stress conditions across reinsurance access constraints, sanctions framework evolution, and interest rate environments were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of Central Bank of Russia capital adequacy enforcement patterns and foreign treaty renewal rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Liability Insurance Market
Insurance
Credit Insurance Market
Insurance
Singapore Business Income Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Japan Bancassurance Market
Insurance
China Online Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
Reinsurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
Insurance Claims Services Market
Insurance
Trade Credit Insurance Market
Insurance
France Car Insurance Market
Insurance
Europe Parametric Insurance Market
Insurance
Specialty Insurance Market
Insurance
Spain Parametric Insurance Market
Insurance
Usage-Based Insurance (UBI) Market