
 Industrial Lighting Cybersecurity Market | 2026-2036
Industrial Lighting Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Lighting Cybersecurity Market Insights
Silicon photonics is realigning cost structures for secure lighting communication modules. Schneider Electric leverages its building-to-grid integration expertise to dominate European industrial campus deployments. Siemens sustains deep R&D pipelines in operational technology security, anchoring its position across power plant and chemical processing applications. Cisco Systems specializes in converged IT-OT network architectures, differentiating through native segmentation capabilities for lighting control backbones.
Industrial lighting cybersecurity encompasses the protection of connected luminaire networks, sensors, and control systems within manufacturing and critical infrastructure environments, typically operating across 2.4 GHz Zigbee, Bluetooth Mesh, or Power over Ethernet protocols with AES-128 encryption baselines to prevent unauthorized access, data exfiltration, or operational disruption. The hardware firewall segment currently occupies the largest installed base as facilities retrofit legacy DALI and 0-10V networks, though behavioral analytics is accelerating fastest as operators seek anomaly detection in lighting-driven occupancy and energy data streams. Endpoint security retains concentrated margin pools due to certificate provisioning complexity and firmware signing requirements for distributed luminaire nodes.
The EU Cyber Resilience Act and IEC 62443-3-3 framework mandate security-by-design for networked industrial devices, directly elevating procurement specifications for lighting control gateways and driving vendor compliance investments. In the United States, NIST SP 800-82 and FDA cybersecurity guidance for pharmaceutical production environments shape product certification pathways, narrowing market access for uncertified suppliers. Stakeholders must weigh the trade-off between cloud-native security orchestration and air-gapped lighting networks as regulatory scope expands beyond traditional IT perimeters into operational technology infrastructure.
Market Dynamics
IEC 62443-3-3 compliance mandates are forcing manufacturing facilities to rip-and-replace legacy lighting control networks with cryptographically hardened architectures, compressing procurement cycles for secure gateways and endpoint modules.
Growth Catalysts
- EU Cyber Resilience Act:Security-by-design mandates for networked industrial devices are elevating procurement specifications for lighting control gateways across German automotive plants and Dutch chemical processing facilities.
- Bluetooth Mesh with AES-128:Wireless protocol adoption in pharmaceutical cleanrooms is eliminating cable infrastructure costs while maintaining FDA cybersecurity guidance compliance for production environments.
- Energy generation sector:Power plant operators are expanding network access control procurement as NERC CIP adjacent standards influence lighting network segmentation requirements.
Market Restraints
- Silicon photonics component costs:Secure communication module substrates remain 40-60% above legacy copper-based alternatives, constraining retrofit budgets for mid-sized manufacturing facilities.
- Certificate provisioning complexity:Firmware signing infrastructure for distributed luminaire nodes requires specialized PKI expertise that concentrates among a handful of European system integrators.
- Air-gapped network preference:Critical infrastructure operators in nuclear and defense-adjacent facilities resist cloud-native orchestration, limiting addressable market for SaaS-delivered security platforms.
Strategic Opportunities
- Behavioral analytics integration:Anomaly detection in occupancy and energy data streams represents underexploited white space as operators seek OT-native threat visibility beyond IT perimeters.
- Building-to-grid convergence:Campus-wide microgrid deployments create demand for lighting networks that participate in demand response while maintaining cryptographic isolation from utility SCADA.
- India PLI scheme:Domestic manufacturing incentives for electronic components are attracting gateway assembly investments that could reshape Asia-Pacific supply configurations.
Industry Challenges
- IT-OT skill bifurcation:Facilities struggle to hire engineers conversant in both DALI lighting protocols and zero-trust network architectures, elongating deployment timelines.
- Legacy DALI retrofit friction:0-10V analog networks in decades-old industrial plants require physical rewiring for Power over Ethernet, triggering cost overruns and production downtime.
- Multi-standard certification lag:Vendors face 18-24 month validation cycles to satisfy simultaneous IEC 62443, NIST SP 800-82, and FDA cybersecurity guidance requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Lighting Cybersecurity Market |
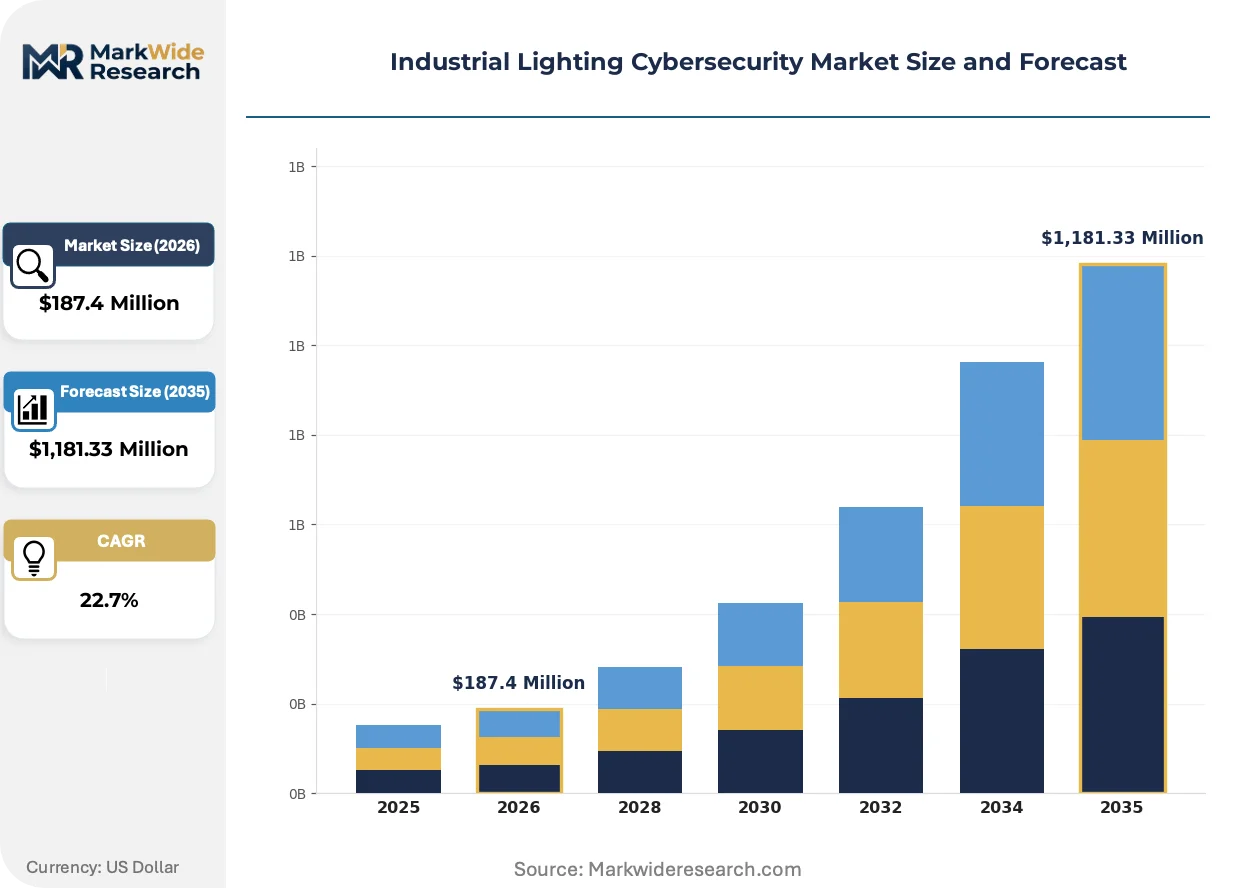
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware Firewall, Intrusion Detection System, Endpoint Security, Network Access Control, Security Information Event Management, Data Loss Prevention Technology: Artificial Intelligence, Machine Learning, Behavioral Analytics, Blockchain, Cloud Security, Encryption Application: Manufacturing Facilities, Warehousing, Power Plants, Transportation Hubs, Chemical Processing Units, Water Treatment Plants End User Industry: Energy Generation, Food & Beverage Processing, Pharmaceutical Production, Mining Operations, Textile Production, Electronics Assembly |
| Companies Covered | Schneider Electric, Siemens, Honeywell International, ABB, Rockwell Automation, Microsoft, Cisco Systems, IBM, Palo Alto Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Lighting Cybersecurity Market Trends and Innovations
Silicon photonics is collapsing cost curves for optical interconnects in secure lighting backbones. Three developments are compressing competitive positioning and procurement patterns.
Silicon photonics transceivers are overtaking copper Ethernet for inter-luminaire communication in high-security manufacturing zones. Semiconductor foundries in Taiwan and Germany are scaling 400G optical engines for industrial IoT form factors. The shift is compressing electromagnetic interference vulnerabilities while extending physical segmentation between lighting zones and corporate IT networks.
REACH substance restrictions are accelerating halogen-free PCB substrate adoption for lighting control modules. German chemical regulators are tightening flame-retardant material approvals, forcing vendors to requalify supply chains. The automotive and aerospace verticals in Bavaria and Baden-Württemberg are demanding pre-certified component traceability, privileging European contract manufacturers with established ECHA documentation systems.
Buyer committees now mandate native network segmentation capabilities as table stakes in RFP evaluations. Energy managers and CISOs are jointly specifying lighting procurement, displacing siloed facilities-driven purchasing. This pattern is most pronounced in German automotive OEM campuses and Swiss pharmaceutical production clusters, where integrated IT-OT governance models have matured.
Industrial Lighting Cybersecurity Market Segmentation
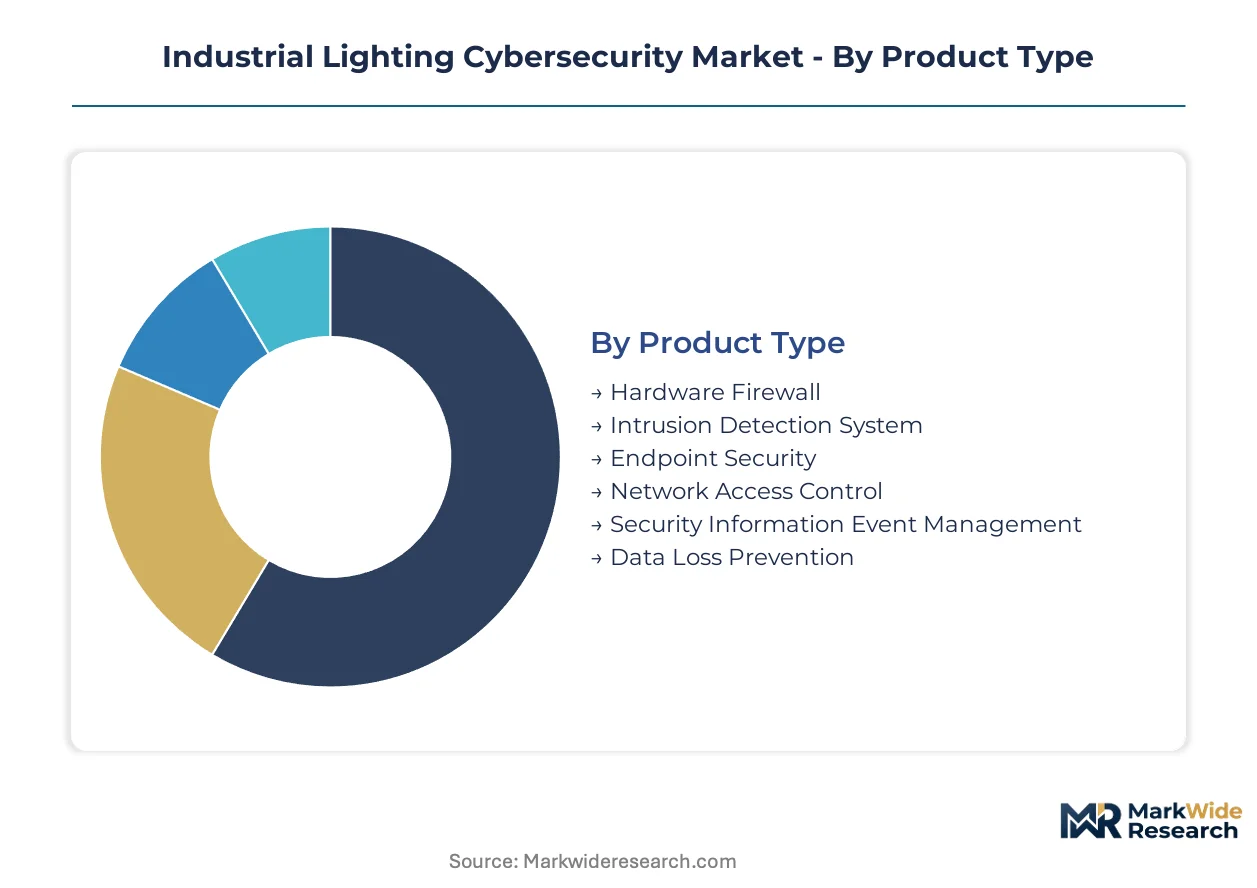
Procurement patterns in industrial lighting cybersecurity diverge sharply across product architectures, detection methodologies, facility types, and sector-specific compliance regimes. Buyers prioritize solutions that bridge legacy DALI retrofit requirements with IEC 62443-3-3 cryptographic mandates without triggering production downtime.
Product Type:
Facilities weigh capital expenditure against operational risk exposure when selecting defensive layers, with air-gapped environments demanding hardware-centric approaches while cloud-connected campuses favor orchestration platforms.
- Hardware Firewall:Purpose-built appliances enforce zone segmentation between lighting control networks and corporate IT infrastructure. German automotive plants and Dutch chemical facilities dominate procurement as IEC 62443-3-3 mandates harden gateway specifications.
- Endpoint Security:Certificate provisioning and firmware signing modules protect distributed luminaire nodes from supply chain compromise. Margin concentration reflects PKI complexity that European system integrators have captured.
- Intrusion Detection System:Signature and anomaly-based monitoring for Zigbee and Bluetooth Mesh lighting backbones.
- Network Access Control:Device authentication frameworks for Power over Ethernet lighting deployments.
- Security Information Event Management:Centralized logging aggregation across heterogeneous lighting control protocols.
- Data Loss Prevention:Content inspection for occupancy and energy data streams exiting OT perimeters.
Hardware Firewall leads on scale; Endpoint Security leads on momentum.
Technology:
Detection sophistication determines pricing tiers, with rule-based engines anchoring budget retrofit projects while adaptive systems command premium positioning in pharmaceutical cleanrooms.
- Behavioral Analytics:Baseline profiling of occupancy patterns and energy consumption anomalies enables OT-native threat visibility without IT network dependency. Swiss pharmaceutical clusters and Bavarian aerospace facilities are expanding deployment as FDA cybersecurity guidance tightens data integrity requirements.
- Artificial Intelligence:Neural architectures for predictive threat modeling in converged IT-OT lighting environments.
- Machine Learning:Supervised classification models for device fingerprinting in mixed-protocol networks.
- Blockchain:Distributed ledger approaches for firmware update attestation across luminaire fleets.
- Cloud Security:SaaS-delivered orchestration for multi-site lighting control governance.
- Encryption:AES-128 and emerging post-quantum cryptographic implementations for wireless lighting mesh.
Behavioral Analytics commands the steepest expansion trajectory as operators seek anomaly detection beyond traditional perimeter defenses.
Application:
Environmental hazard classification and uptime requirements shape procurement specifications, with explosive atmosphere zones demanding intrinsically safe enclosures and continuous operations mandating hot-swappable redundancy.
- Manufacturing Facilities:Assembly line lighting networks require millisecond-failover resiliency to prevent production line stoppages. German automotive OEM campuses in Stuttgart and Wolfsburg are specifying native segmentation capabilities in joint energy-CISO procurement committees.
- Chemical Processing Units:Corrosion-resistant enclosures and ATEX-certified components for hazardous vapor environments. BASF and Dow facilities in Ludwigshafen and Terneuzen are driving demand for hardened lighting control gateways.
- Power Plants:NERC CIP-influenced segmentation for turbine hall and switchyard illumination.
- Warehousing:High-bay LED networks with motion-activated security monitoring.
- Transportation Hubs:24/7 operational requirements for airport and seaport cargo terminals.
- Water Treatment Plants:SCADA-isolated lighting for critical infrastructure protection.
Manufacturing Facilities anchor volume concentration; Chemical Processing Units are climbing the fastest on regulatory compliance intensity.
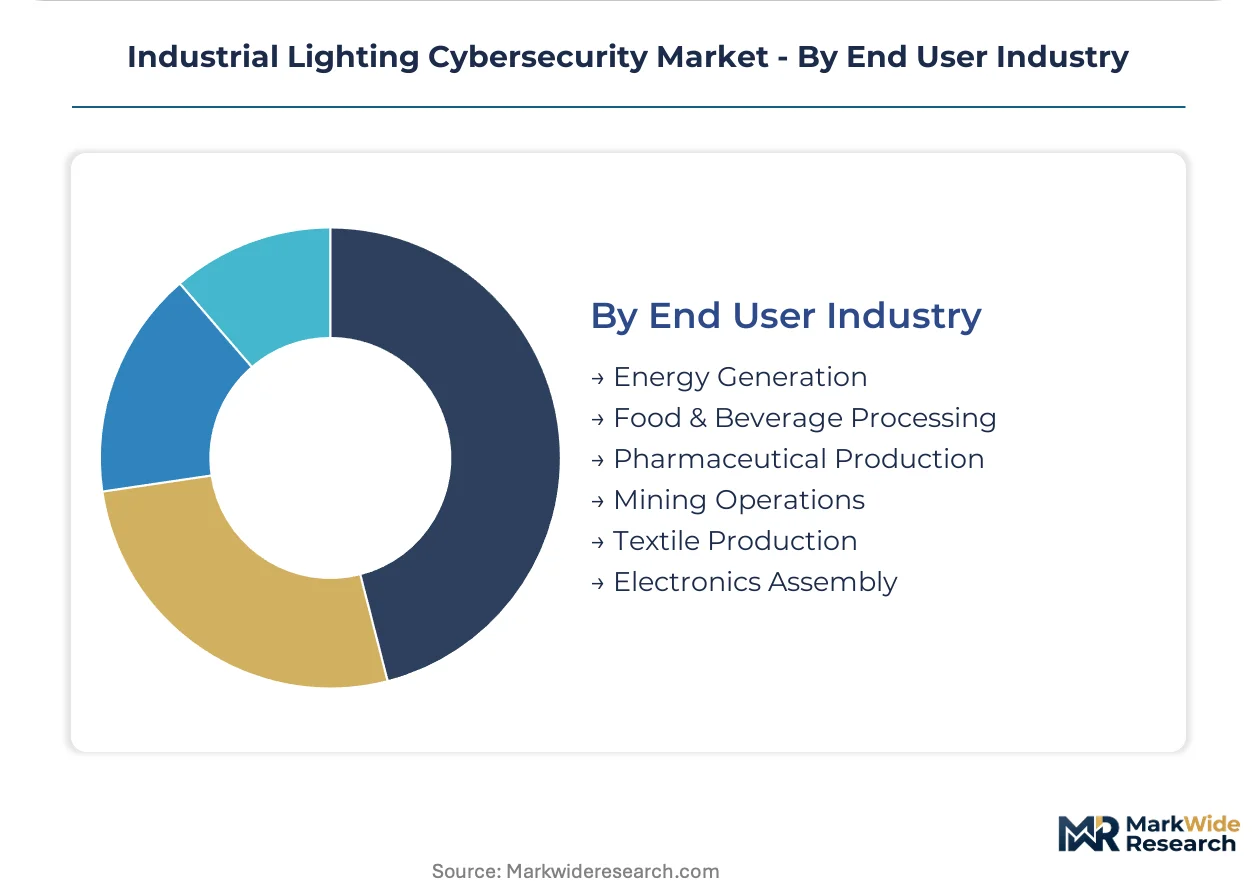
End User Industry:
Sector-specific certification pathways create vendor lock-in effects, with pharmaceutical and food processing verticals demanding pre-validated component traceability that privileges established European suppliers.
- Pharmaceutical Production:FDA cybersecurity guidance and EU GMP Annex 15 requirements mandate lighting network documentation for batch record integrity. Novartis and Roche facilities in Basel are requiring ECHA-traceable halogen-free PCB substrates for all control modules.
- Energy Generation:Coal, natural gas, and renewable power operators are expanding network access control procurement as NERC CIP adjacent standards influence lighting segmentation. RWE and E.ON facilities in the Rhineland are retrofitting legacy DALI networks with cryptographically hardened architectures.
- Food & Beverage Processing:USDA and EFSA hygiene mandates for luminaire housing materials and cleaning protocol compatibility.
- Mining Operations:Underground lighting networks with methane-rated enclosure requirements.
- Textile Production:Dust explosion protection for spinning and weaving floor illumination.
- Electronics Assembly:ESD-sensitive cleanroom lighting with particulate contamination controls.
Energy Generation dominates current procurement velocity; Pharmaceutical Production is gaining share fastest on regulatory documentation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation ecosystems anchor procurement intensity for cryptographically hardened lighting control networks, with IEC 62443 compliance mandates compressing retrofit timelines across manufacturing clusters.
United States
Pharmaceutical production facilities and power plant operators drive network access control procurement as NIST SP 800-82 and FDA cybersecurity guidance tighten segmentation requirements. The Rhineland industrial corridor influences American energy sector procurement patterns through NERC CIP-adjacent standards adoption. BASF and Dow facilities in Ludwigshafen and Terneuzen demonstrate hardened gateway specifications that US chemical processors increasingly emulate.
Germany
Automotive OEM campuses in Stuttgart and Wolfsburg specify native IT-OT segmentation capabilities through joint energy-CISO procurement committees. The EU Cyber Resilience Act and IEC 62443-3-3 framework elevate gateway specifications for lighting control networks. Bavarian aerospace facilities and Baden-Württemberg automotive plants demand ECHA-traceable halogen-free PCB substrates with pre-certified component documentation.
Switzerland
Novartis and Roche facilities in Basel mandate lighting network documentation for batch record integrity under FDA cybersecurity guidance and EU GMP Annex 15. Swissmedic pharmaceutical regulations reinforce data integrity requirements for cleanroom illumination systems. The Basel pharmaceutical cluster exemplifies integrated IT-OT governance models that prioritize cryptographic isolation from corporate networks.
China
Domestic manufacturing incentives through MIIT industrial upgrading programs attract gateway assembly investments for Asia-Pacific supply reconfiguration. GB standards and dual carbon goals accelerate Power over Ethernet lighting retrofits in Yangtze River Delta manufacturing zones. Semiconductor foundries in Taiwan and mainland China scale 400G optical engines for industrial IoT form factors serving regional demand.
India
The PLI scheme for electronic components draws gateway assembly investments that reshape Asia-Pacific supply configurations. BIS certification requirements and CEA power sector mandates influence lighting network security specifications in Maharashtra and Gujarat industrial corridors. Domestic contract manufacturers in Karnataka and Tamil Nadu develop PKI expertise for firmware signing infrastructure serving distributed luminaire deployments.
Industrial Lighting Cybersecurity Market Competitive Landscape
Global majors compete with regional champions across compliance certification depth and IT-OT integration capabilities. The vendor base organizes around three strategic archetypes: industrial automation incumbents with native OT security pipelines, converged networking specialists with segmentation-native architectures, and cybersecurity pure-plays with OT-native threat detection. Dominant competitive moves include vertical integration into silicon photonics transceiver supply and strategic partnerships for multi-standard certification acceleration.
Within the industrial automation tier, Schneider Electric and Siemens exemplify European champions with building-to-grid integration expertise and operational technology security depth. Cisco Systems occupies a position among converged networking specialists, differentiating through native segmentation capabilities for lighting control backbones. These three anchors represent distinct competitive vectors: campus-wide microgrid convergence, power plant and chemical processing R&D pipelines, and IT-OT architectural convergence respectively.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| Honeywell International |
| ABB |
| Rockwell Automation |
| Microsoft |
| Cisco Systems |
| IBM |
| Palo Alto Networks |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between IEC 62443-3-3 validated gateways and uncertified commodity alternatives manifests in both pricing stratification and supply chain qualification intensity. Premium-tier hardware commands substantial markups due to European system integrator concentration in PKI infrastructure, while mid-sized manufacturing facilities face compressed procurement budgets that reshape component sourcing toward Asia-Pacific assembly hubs.
Pricing Analysis
Input-cost pass-through from silicon photonics transceiver substrates drives pricing stratification across secure lighting communication modules. Three-tier pricing structure across premium, standard, and economy levels separates cryptographic-hardened IEC 62443 gateways from legacy DALI retrofit units and uncertified commodity alternatives. Pricing pressure stems from REACH substance restrictions forcing halogen-free PCB requalification costs onto vendors. Pharmaceutical production facilities show least price sensitivity due to FDA cybersecurity guidance mandates, while mid-sized warehousing operations exhibit highest budget elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs and Swiss pharmaceutical clusters mandate multi-supplier qualification for lighting control gateway semiconductors. Supply concentration centers on Taiwan and Germany for 400G optical engine foundry capacity, with India PLI scheme attracting assembly investments that diversify final-stage manufacturing. Silicon photonics substrates, AES-128 cryptographic modules, and ECHA-traceable halogen-free PCBs constitute critical input dependencies. Single-source vulnerability runs through Taiwan semiconductor foundry concentration for industrial IoT form factors. Distribution runs through European system integrators with captive PKI expertise for firmware signing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial lighting cybersecurity functions as a stable compounder anchored by regulatory compliance mandates that deepen procurement specification intensity across manufacturing and critical infrastructure verticals.
For Market Incumbents: Deploy IEC 62443-4-2 component certification as a margin defense lever against emerging OT-native cybersecurity pure-plays. Incumbents should accelerate backward integration into silicon photonics transceiver supply to capture substrate cost compression, while consolidating channel control through exclusive PKI infrastructure partnerships with European system integrators that concentrate firmware signing expertise.
For New Entrants and Emerging Players: EU Cyber Resilience Act in Germany opens a window for behavioral analytics specialists to penetrate pharmaceutical cleanroom deployments where FDA cybersecurity guidance tightens anomaly detection requirements. New entrants should target mid-sized chemical processing facilities in the Netherlands with SaaS-delivered security orchestration that bypasses air-gapped network preferences through OT-native deployment models.
For Investors and Strategic Acquirers: Asymmetric upside sits with OT-native threat detection specialists possessing pre-certified IEC 62443 component libraries and established European pharmaceutical customer relationships. Long-term viability hinges on multi-standard certification acceleration capabilities across IEC, NIST, and FDA pathways. The signal to watch is consolidation momentum among European system integrators holding captive PKI expertise for distributed luminaire firmware signing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Photonics | In-house 400G optical engine production collapses secure communication module cost structures for German automotive deployments. |
| Multi-Standard Certification Acceleration | Parallel IEC 62443, NIST SP 800-82, and FDA validation compresses 18-24 month cycles to capture pharmaceutical procurement windows. |
| Behavioral Analytics Platform Launch | OT-native anomaly detection for occupancy data streams addresses Swiss pharmaceutical cluster requirements under EU GMP Annex 15. |
| European System Integrator Partnership | Exclusive PKI infrastructure alliances concentrate firmware signing expertise and block emerging entrant channel access. |
| India PLI Scheme Manufacturing Footprint | Gateway assembly investments in Karnataka and Tamil Nadu reshape Asia-Pacific supply configurations for cost-competitive retrofit markets. |
Research Methodology
Coverage spans Germany, Switzerland, the United States, China, and India, with primary inputs from each market informing demand-side validation. The research combines structured interviews with CISOs at pharmaceutical production facilities, energy sector OT security directors, automotive plant engineers, lighting control system procurement leads, and European system integrators specializing in PKI infrastructure. Secondary validation draws from IEC 62443 certification registries, FDA cybersecurity guidance documentation, NIST SP 800-82 publications, ECHA REACH substance restriction updates, and customs trade data for industrial IoT component flows. Bottom-up unit economics for lighting control gateway deployments triangulate against top-down market sizing from regulatory mandate penetration rates.
Granularity-level modeling disaggregates volume and value outputs across product type, detection technology, facility application, and end-user industry verticals throughout the forecast period. The analytical framework incorporates protocol-specific adoption curves for Zigbee, Bluetooth Mesh, and Power over Ethernet lighting backbones. CAGRs derive from regulatory compliance deadline clustering, retrofit cycle compression in German automotive corridors, and silicon photonics cost curve trajectories for secure optical interconnects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Cyber Resilience Act enforcement timelines or prolonged semiconductor foundry capacity constraints in Taiwan. Forecasts reflect documented assumptions regarding IEC 62443-3-3 mandate adoption rates, pharmaceutical facility capital expenditure cycles, and air-gapped network preference persistence in critical infrastructure verticals. Deviation in NERC CIP standard expansion into lighting network segmentation requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
India Lighting Market
Lighting
Solar Lights Market
Lighting
Hazardous Lighting Market
Lighting
Street Lighting Market
Lighting
Smart Lamp Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Wireless Lighting Market
Lighting
Photocell Market
Lighting
Specialty Lighting Market
Lighting
Europe Decorative Lighting Market
Lighting
Dimmers Market
Lighting
Global Lighting Control System Market
Lighting
Intelligent Lighting Controls Market
Lighting
Circadian Lighting Market
Lighting
Europe Lighting Control Systems Market
Lighting
US Indoor LED Lighting Market