
 Global Gastrointestinal Stent Market | 2026-2036
Global Gastrointestinal Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gastrointestinal Stent Market Foresight
The gastrointestinal stent market is restructuring around a widening gap between premium nitinol-based metal platforms and commodity plastic alternatives used for short-term palliation. Boston Scientific Corporation leverages its interventional endoscopy portfolio to dominate complex malignant biliary obstruction cases across North American academic centers. Taewoong Medical anchors its position in the Asia-Pacific corridor through specialized self-expanding metal stent designs optimized for esophageal stricture anatomy. Cook Medical differentiates via backward integration into nitinol wire processing, sustaining margin control against contract-manufactured competitors.
Gastrointestinal stents are tubular prosthetic devices typically constructed from nitinol, stainless steel, or biocompatible polymers, designed to maintain luminal patency in obstructed segments of the esophagus, bile duct, duodenum, or colon; they deploy via endoscopic or fluoroscopic guidance with radial expansion forces calibrated to tissue compliance. Self-expanding metal stents command the dominant revenue share due to superior patency duration in malignant indications, while biodegradable stents represent the fastest-expanding category as absorbable magnesium and polymer platforms reduce retrieval morbidity in benign stricture management. Plastic stents retain volume leadership in preoperative biliary decompression where temporary drainage precedes definitive surgical resection, concentrating margin pools in high-throughput gastroenterology clinics.
FDA 510(k) clearance pathways govern U.S. market entry for novel stent geometries, while the EU Medical Device Regulation mandates notified body conformity assessment and post-market surveillance systems that extend commercialization timelines. Japan's PMDA enforces Japan Industrial Standards compatibility testing for nitinol fatigue resistance, filtering out lower-durability imports. Stakeholders must monitor evolving reimbursement thresholds for palliative versus curative-intent stent placement as health technology assessment bodies recalibrate cost-effectiveness benchmarks.
Market Dynamics
Self-expanding metal stent technology is bifurcating the gastrointestinal stent market into premium nitinol platforms for malignant obstruction and commodity plastic alternatives for temporary palliation, compressing margin pools for mid-tier manufacturers lacking backward integration into nitinol wire processing.
Growth Catalysts
- Aging demographics:Japan's super-aged population and Germany's expanding 65-plus cohort are driving procedural volumes for malignant biliary obstruction management in established endoscopy infrastructure.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for novel stent geometries accelerates commercialization timelines for U.S.-based manufacturers relative to EU MDR conformity assessments.
- Biodegradable magnesium platforms:Absorbable stent technology eliminates retrieval morbidity in benign stricture management, expanding addressable indications beyond traditional metal stent palliation.
Market Restraints
- Nitinol supply concentration:Captive wire processing capabilities at Cook Medical and select Asian metallurgical suppliers create input bottlenecks for contract-manufactured competitors.
- EU MDR timeline extension:Notified body conformity assessments and post-market surveillance mandates extend European commercialization cycles by 12-18 months versus legacy CE marking.
- Plastic stent substitution ceiling:Commodity polymer alternatives cap pricing power in preoperative biliary decompression where temporary drainage precedes definitive surgical resection.
Strategic Opportunities
- India's underserved gastroenterology infrastructure:PLI scheme incentives for medical device manufacturing and expanding private hospital networks create first-mover advantages for esophageal stent localization.
- Ambulatory surgical center channel expansion:Same-day biliary procedure protocols in U.S. outpatient settings shift volume from inpatient reimbursement pools to lower-cost site-of-care alternatives.
- Digital fluoroscopy integration:Convergence of endoscopic deployment systems with real-time imaging guidance is automating physician training curves and expanding treatable patient populations.
Industry Challenges
- Interventional endoscopy specialist scarcity:ERCP credentialing requirements and proctoring mandates constrain procedure capacity expansion in community hospital settings.
- Japan Industrial Standards fatigue testing:PMDA-mandated nitinol durability validation filters lower-durability imports, requiring dedicated R&D investment for market access.
- Health technology assessment recalibration:Palliative versus curative-intent stent placement reimbursement thresholds vary across German, French, and UK assessment bodies, complicating pricing strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gastrointestinal Stent Market |
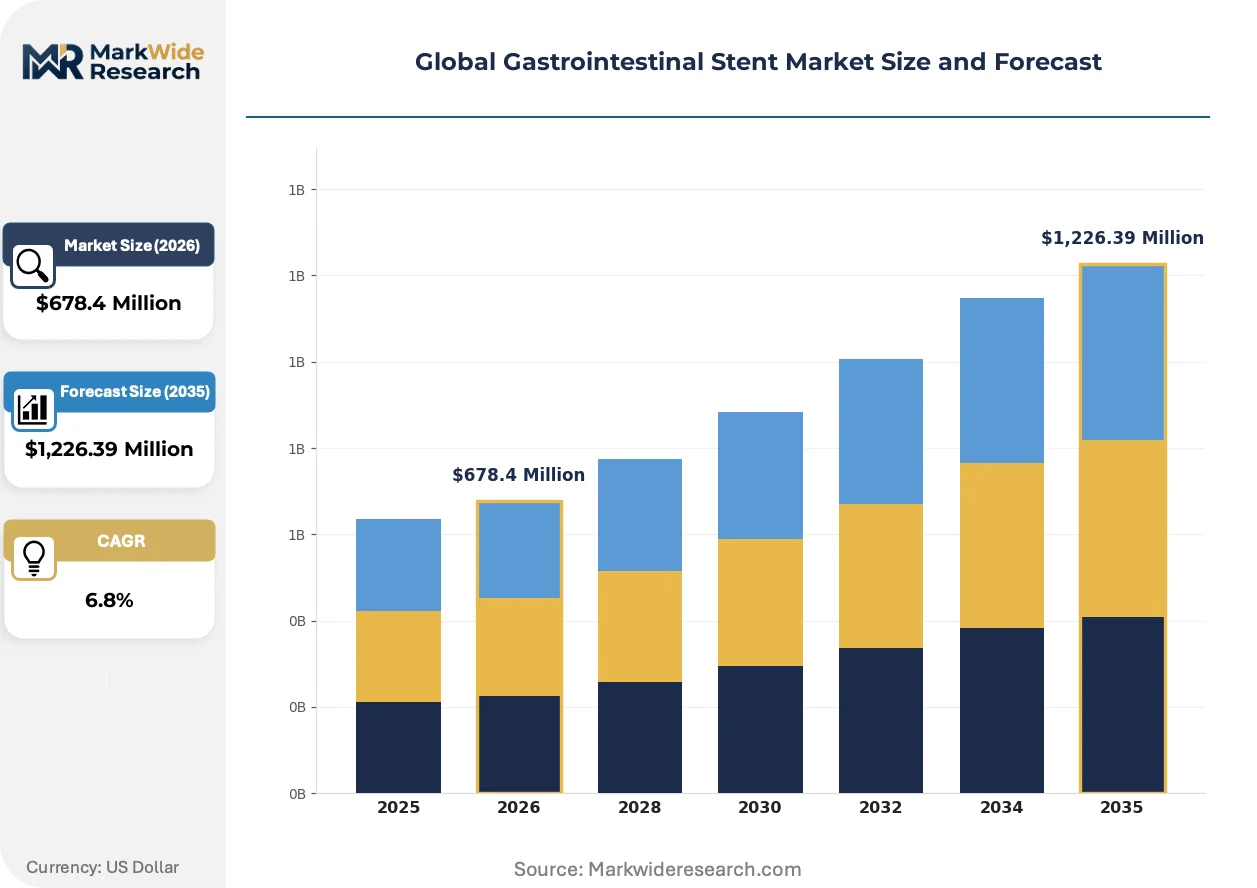
| Market Size in 2026 | $678.4 Million |
| Market Size in 2035 | $1,226.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-expanding Metal Stents, Plastic Stents, Biodegradable Stents, Drug-eluting Stents Application: Esophageal Stricture, Malignant Biliary Obstruction, Colorectal Obstruction, Gastroduodenal Obstruction End User: Specialty Surgical Centers, Ambulatory Surgical Facilities, Academic Medical Centers, Gastroenterology Clinics Deployment Type: Emergency Procedure, Elective Procedure, Palliative Care, Preoperative Intervention |
| Companies Covered | Olympus Corporation, Taewoong Medical, Boston Scientific Corporation, Merit Medical Systems, Micro-Tech (Nanjing) Co., Ltd., Cook Medical, Becton Dickinson and Company, CONMED Corporation, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gastrointestinal Stent Market Shifts & Advancements
Robotic-assisted endoscopic deployment systems and AI-guided stricture measurement tools are compressing physician training requirements while expanding treatable anatomy, fundamentally altering the specialist-labor bottleneck that has constrained procedure volume growth.
Shape-memory alloy engineering is automating radial force calibration to tissue compliance across esophageal, biliary, and colonic anatomies. Academic medical centers in the United States and Japan are adopting these platforms for complex malignant obstruction cases where manual deployment variability previously limited outcomes. The technology is automating standardization of expansion forces, reducing revision rates and enabling same-day discharge protocols.
EU Medical Device Regulation post-market surveillance requirements are extending commercialization timelines for novel stent geometries. Manufacturers must maintain clinical follow-up registries and periodic safety update reports that legacy CE marking did not mandate. Small-to-mid cap developers without dedicated regulatory affairs infrastructure are outsourcing notified body interactions to specialized consultancies, concentrating market access capabilities.
Hospital procurement departments are unbundling stent placement from bundled endoscopy service contracts, creating direct vendor relationships for high-volume consumables. German and Japanese university hospitals are negotiating multi-year supply agreements with nitinol-integrated manufacturers, bypassing traditional distributor markups. This consolidation of purchasing authority favors vertically integrated suppliers with transparent cost structures over contract-manufactured alternatives.
Global Gastrointestinal Stent Market Segmentation
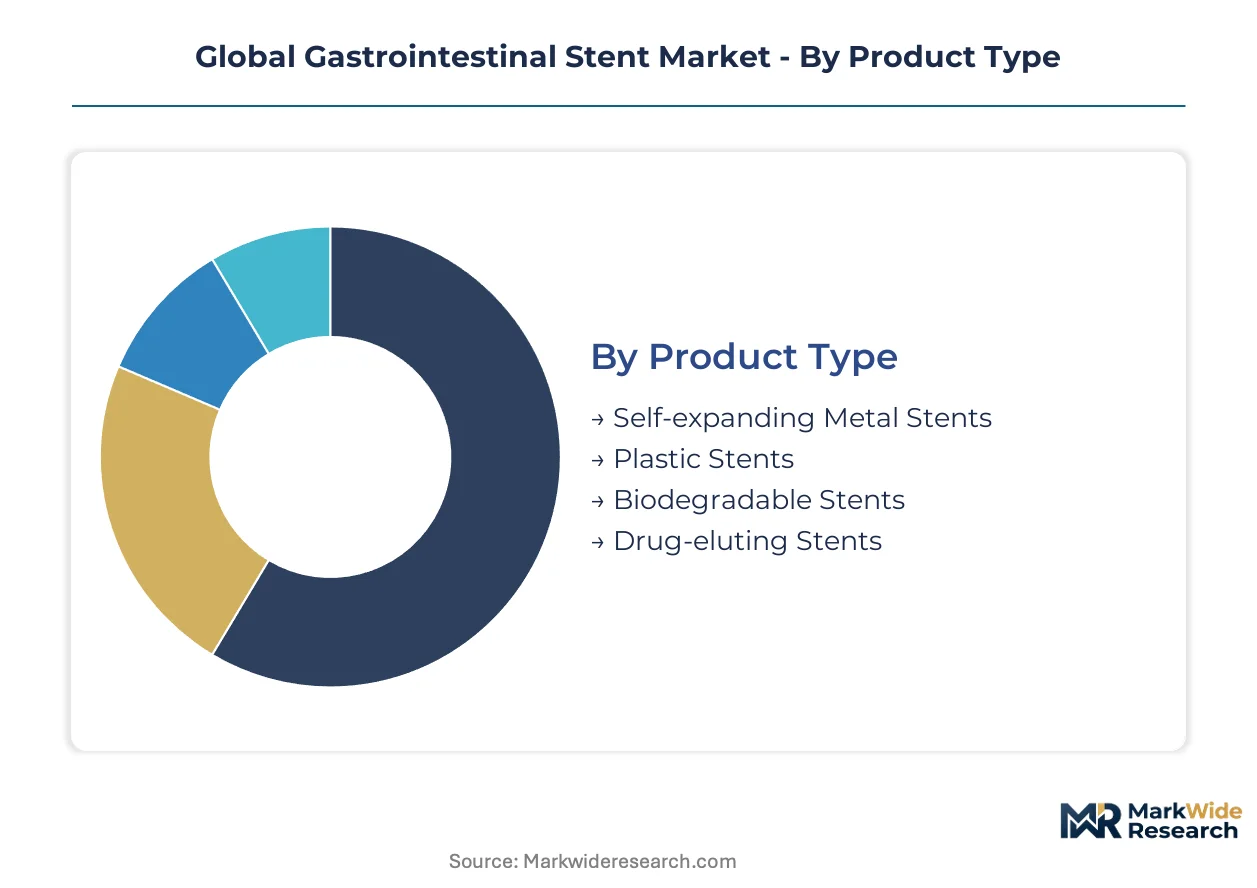
Gastrointestinal stent procurement varies sharply by clinical setting and patient acuity. Product selection hinges on patency duration requirements, retrieval feasibility, and reimbursement classification rather than unit cost alone.
Product Type:
Purchasing committees distinguish platforms by intended dwell time and tissue interaction profile.
- Self-expanding Metal Stents:Nitinol-based platforms deploy radial force against malignant strictures with calibrated expansion mechanics. Demand clusters in U.S. academic medical centers managing complex biliary obstruction where patency duration determines total cost of care.
- Plastic Stents:Polyethylene or polyurethane constructs provide temporary luminal support with endoscopic retrievability. High-throughput gastroenterology clinics in Germany favor these for preoperative biliary decompression where definitive surgery follows within weeks.
- Biodegradable Stents:Absorbable magnesium and polymer matrices eliminate retrieval procedures in benign stricture management. Japan's PMDA has cleared several platforms for esophageal applications.
- Drug-eluting Stents:Paclitaxel-coated surfaces inhibit neoplastic ingrowth to extend patency intervals. Limited commercial penetration reflects manufacturing complexity and specialized indication requirements.
Volume sits with self-expanding metal platforms; growth tilts toward biodegradable alternatives.
Application:
Anatomical site dictates stent geometry, radial force requirements, and physician specialty involvement.
- Malignant Biliary Obstruction:Hepatic duct strictures from pancreatic or cholangiocarcinoma require covered metal stents with side-branch patency. Interventional endoscopists at U.S. tertiary centers drive specification standards for this indication.
- Esophageal Stricture:Proximal and distal esophageal segments demand differential flexibility and flare configurations. Taewoong Medical's specialized designs dominate Asia-Pacific corridor procurement for this anatomy.
- Colorectal Obstruction:Large-diameter through-the-scope deployment addresses malignant large bowel obstruction as bridge-to-surgery or palliation. European adoption lags biliary applications due to anatomical variability challenges.
- Gastroduodenal Obstruction:Pyloric and duodenal strictures from pancreatic malignancy require enteral stenting with anti-migration features. Procedure volume concentrates in Japan's specialized cancer centers.
Malignant biliary cases generate the largest revenue pool; esophageal applications are climbing the fastest.
End User:
Site-of-care economics and credentialing infrastructure determine product mix and pricing tolerance.
- Academic Medical Centers:Complex case referrals and fellowship training programs sustain premium platform adoption. These institutions negotiate direct supply agreements bypassing distributor markups.
- Ambulatory Surgical Facilities:Same-day discharge protocols for ERCP procedures favor streamlined stent systems with reduced fluoroscopy time. U.S. outpatient settings are expanding biliary intervention capacity rapidly.
- Specialty Surgical Centers:Focused gastrointestinal practices concentrate elective stricture management with standardized product formularies.
- Gastroenterology Clinics:Community-based practices handle preoperative drainage and benign stricture surveillance with plastic stent predominance.
Academic centers command premium pricing; ambulatory facilities are gaining share fastest.
Deployment Type:
Clinical intent shapes reimbursement classification and product selection urgency.
- Palliative Care:End-stage malignancy management prioritizes durable patency over retrievability. Covered metal stents dominate this intent category across German and Japanese reimbursement frameworks.
- Preoperative Intervention:Temporary drainage to optimize surgical candidacy favors plastic stents or short-dwell metal alternatives. Gastroenterology clinics in the United States handle substantial volume in this category.
- Emergency Procedure:Acute cholangitis or complete obstruction demands immediate biliary decompression without product substitution flexibility.
- Elective Procedure:Scheduled interventions allow product selection optimization and cost comparison across vendor portfolios.
Palliative deployments anchor revenue; preoperative interventions are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American gastrointestinal stent manufacturing through Cook Medical's captive nitinol wire processing operations, while Tokyo's Kanto corridor concentrates Japan's interventional endoscopy specialist training infrastructure.
United States
Academic medical centers in Boston and Baltimore drive complex malignant biliary obstruction case volumes through fellowship-trained interventional endoscopists. FDA 510(k) premarket notification pathways accelerate commercialization timelines for novel stent geometries relative to European regulatory frameworks. Massachusetts General Hospital and Johns Hopkins Hospital set procurement standards that cascade through regional hospital networks.
Germany
University hospitals in Munich and Heidelberg negotiate direct supply agreements with nitinol-integrated manufacturers, bypassing traditional distributor markups for self-expanding metal stent procurement. EU Medical Device Regulation notified body conformity assessments extend commercialization cycles by 12-18 months versus legacy CE marking. The Baden-Württemberg medical technology corridor hosts specialized metallurgical suppliers serving stent wire processing demands.
Japan
PMDA-enforced Japan Industrial Standards compatibility testing for nitinol fatigue resistance filters lower-durability imports from contract-manufactured competitors. Tokyo's National Cancer Center and Osaka University Hospital concentrate gastroduodenal obstruction procedure volumes requiring enteral stenting with anti-migration features. METI funding supports shape-memory alloy engineering research at Nagoya-based materials institutes.
India
PLI scheme incentives for medical device manufacturing attract esophageal stent localization investments as private hospital networks in Mumbai and Delhi expand endoscopy infrastructure. CDSCO regulatory pathways for Class C implantable devices require clinical investigation data that domestic manufacturers are assembling through hospital partnerships. Maharashtra's medical device manufacturing clusters in Pune and Aurangabad are adding nitinol processing capabilities.
South Korea
MFDS approval frameworks for self-expanding metal stents align with international standards while maintaining domestic clinical data requirements. Seoul National University Hospital and Asan Medical Center anchor demand for complex biliary stricture management. The Gyeonggi-do biocluster north of Seoul hosts contract manufacturers serving regional stent assembly operations.
Global Gastrointestinal Stent Market Competitive Landscape
Premium-margin players sit above commodity-margin players across nitinol supply chain control and regulatory infrastructure depth, compressing returns for mid-tier manufacturers lacking backward integration into wire processing or dedicated notified body relationships. The market structure concentrates around three strategic archetypes: vertically integrated metallurgical specialists, diversified interventional endoscopy platform owners, and regional contract manufacturers serving price-sensitive procurement committees. Dominant competitive moves include capacity expansion into India under PLI scheme incentives and technology licensing partnerships for biodegradable magnesium platforms.
Within the diversified platform tier, Boston Scientific Corporation and Olympus Corporation exemplify scale-driven endoscopy portfolio breadth, while Taewoong Medical occupies a specialized position in esophageal stricture-optimized designs. Cook Medical represents the vertically integrated archetype through captive nitinol wire processing capabilities that sustain margin control against contract-manufactured alternatives. These three entities anchor distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| Olympus Corporation |
| Taewoong Medical |
| Boston Scientific Corporation |
| Merit Medical Systems |
| Micro-Tech (Nanjing) Co., Ltd. |
| Cook Medical |
| Becton Dickinson and Company |
| CONMED Corporation |
| Medtronic |
| Others |
Supply & Pricing Matrix
A sharp bifurcation between premium nitinol-based metal stents and commodity plastic alternatives manifests in divergent pricing architectures and supply chain configurations across the gastrointestinal stent market. Premium platforms command value-based pricing anchored to patency duration and retrieval morbidity reduction, while plastic alternatives trade on per-unit transactional economics shaped by high-throughput gastroenterology clinic procurement. This tier divergence concentrates margin pools with manufacturers possessing captive wire processing capabilities, compressing returns for contract-assembled competitors dependent on spot-market nitinol sourcing.
Pricing Analysis
Value-based pricing anchors premium self-expanding metal stents to total cost-of-care outcomes in malignant biliary obstruction management. Price differentiation separates FDA-cleared nitinol platforms with extended patency guarantees from economy-tier polyethylene constructs used for preoperative drainage. Pricing pressure stems from ambulatory surgical center procurement committees demanding streamlined systems with reduced fluoroscopy time. Academic medical centers exhibit lowest price sensitivity, prioritizing patency duration and retrieval feasibility over unit cost in complex case referrals.
Supply Chain Analysis
Japan Industrial Standards fatigue certification gates market access for nitinol wire suppliers, filtering lower-durability imports from contract manufacturers. Geographic supply concentration centers on the United States, Germany, and Japan, with captive metallurgical processing at select facilities. Raw material dependencies include nitinol wire, biocompatible polymer resins, and shape-memory alloy feedstock. Single-source vulnerability persists in specialized wire drawing capabilities. Distribution runs through direct hospital supply agreements at academic centers and distributor networks for community gastroenterology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gastrointestinal stent market functions as a vertical-integration race where control over nitinol wire processing and regulatory infrastructure depth determines sustainable margin capture. Players are pursuing backward integration into metallurgical supply as the decisive upstream lever.
For Market Incumbents: Anchor market position through exclusive supply agreements with Japan's PMDA-certified wire processors and capacity expansion into India's PLI-subsidized manufacturing corridors. Biodegradable magnesium platform substitution threatens traditional metal stent volumes in benign stricture indications. Defensive patent clustering around shape-memory alloy geometries preserves premium pricing power against emerging Korean and Chinese entrants. For New Entrants and Emerging Players: The price-point gap between premium covered metal stents and economy plastic alternatives opens white-space targeting for mid-tier biodegradable platforms in India's expanding private hospital networks. Esophageal stricture management offers the most penetrable application segment given anatomical specialization requirements that deter diversified incumbents. A go-to-market angle anchored to CDSCO regulatory pathway partnerships with Maharashtra-based teaching hospitals accelerates market access without duplicating PMDA certification burdens. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists given EU MDR timeline extensions that filter out regulatory-light competitors. Long-term viability over the next decade hinges on nitinol supply security and notified body relationship depth. Acquisition target archetypes include captive wire processors with JIS certification and biodegradable platform developers with PMDA clearances. The signal to watch is CDSCO approval velocity for Class C implantable devices as India domestication accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitinol Processing | Captive wire drawing capabilities at Cook Medical insulate margin structures against spot-market volatility. |
| PMDA Certification Pathway Investment | Japan Industrial Standards fatigue validation filters lower-durability competitors from Tokyo's National Cancer Center procurement. |
| Hospital System Partnership | Direct supply agreements with German university hospitals bypass traditional distributor markups for self-expanding metal stents. |
| Biodegradable Platform Development | Absorbable magnesium matrices eliminate retrieval morbidity in benign esophageal stricture management. |
| Reimbursement Strategy | Health technology assessment navigation across German, French, and UK bodies optimizes palliative versus curative-intent pricing. |
Research Methodology
Independent corroboration across interventional endoscopists, hospital purchasing committees, and biomedical engineering directors underwrites the qualitative findings in this study. Primary interviews with GPO contracts managers and regulatory affairs specialists at notified bodies combined with secondary validation from FDA 510(k) filings, PMDA approval databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation anchored market sizing across product type, application, and end-user segments.
Comparable-period anchoring to historical stent placement volumes and reimbursement rate trajectories structured the forecast window over the projection horizon. The analytical framework modeled segmentation across self-expanding metal, plastic, biodegradable, and drug-eluting platforms; malignant biliary, esophageal, colorectal, and gastroduodenal anatomies; and academic medical center, ambulatory surgical, and community clinic end-user settings. CAGRs derived from patent duration trends, aging demographic procedure elasticities, and site-of-care shift velocities. Forecast inputs incorporated EU MDR timeline impacts and PLI scheme manufacturing capacity buildouts.
Underlying measurement precision varies by segment; self-expanding metal stent volumes carry tighter precision than emerging biodegradable categories given established procedure coding. Forecasts reflect assumptions around regulatory approval velocity, reimbursement stability, and interventional endoscopist supply expansion. A model refresh is warranted upon material change in Japan's PMDA certification requirements or India's CDSCO clinical investigation mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
Crohns Disease Therapeutics Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Disposable Intestinal Wash Bags Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market