
 US Inflammatory Bowel Disease Treatment Market | 2026-2036
US Inflammatory Bowel Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
US Inflammatory Bowel Disease Treatment Market Insights
Modular therapy bundling—pairing biologic induction with maintenance dosing protocols—is realigning how payers and providers evaluate total cost of care. AbbVie Inc. leverages its vertically integrated immunology platform to control supply continuity across infusion networks. Takeda Pharmaceutical Company Limited anchors its position through deep specialty pharmacy relationships that streamline prior authorization workflows. Johnson & Johnson Services, Inc. differentiates via gastroenterologist-facing digital tools that track patient response metrics between clinic visits.
US inflammatory bowel disease treatment encompasses pharmacologic and supportive interventions targeting chronic intestinal inflammation, with biologics such as anti-TNF alpha monoclonal antibodies and interleukin inhibitors representing protein-based therapeutics engineered for targeted immune modulation. These agents function to induce mucosal healing and prevent structural bowel damage in Crohn's disease and ulcerative colitis patients. Biologics command the dominant revenue position within product type segmentation, while subcutaneous delivery mode captures expanding share as self-administration protocols reduce clinic dependency. Ulcerative colitis therapy area generates concentrated investment owing to larger addressable patient population and earlier biologic intervention guidelines.
FDA, CMS national coverage determination frameworks, and state-level Medicaid formularies collectively shape market access velocity and reimbursement thresholds for novel IBD therapeutics. FDA's biosimilar interchangeability standards directly influence payer substitution policies and originator pricing defense strategies. Stakeholders must monitor evolving FDA guidance on complex generic peptides and state biosimilar substitution laws to anticipate competitive entry timing and portfolio defense requirements.
Market Dynamics
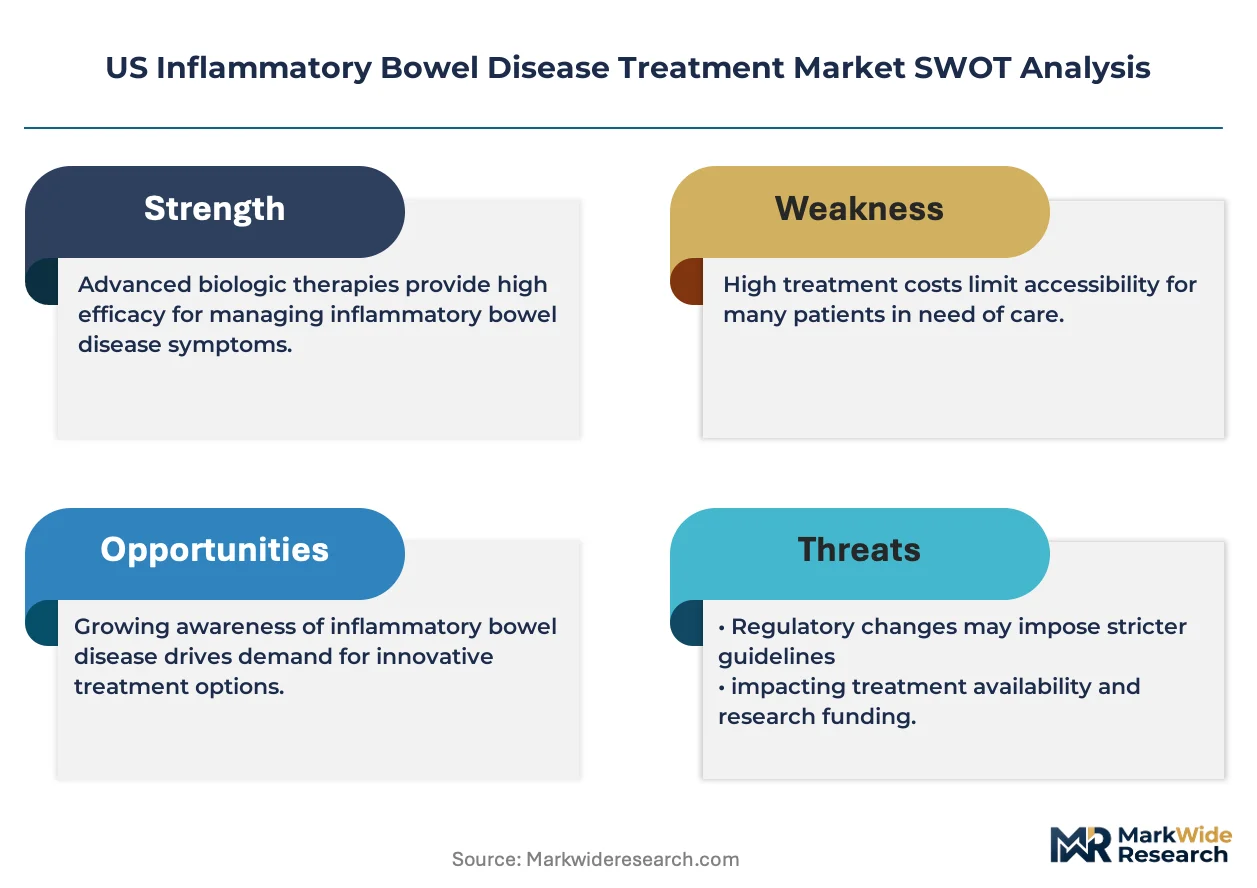
FDA biosimilar interchangeability standards are compressing originator pricing power while accelerating payer substitution policies across commercial and Medicare Advantage formularies.
Growth Catalysts
- Biologic infusion protocol expansion:Gastrointestinal clinics in the Northeast corridor are scaling ambulatory infusion centers to capture step-therapy patients before hospital referral.
- Medicaid formulary modernization:State-level Medicaid programs are removing prior authorization barriers for second-line biologics in ulcerative colitis, expanding addressable volume.
- Academic medical center clustering:Specialty care networks anchored by Massachusetts General, Mayo Clinic Rochester, and Cedars-Sinai concentrate high-value patient flow and clinical trial recruitment.
Market Restraints
- Plasma-derived protein input volatility:Biologic active pharmaceutical ingredient supply concentrates among fractionators in the US Upper Midwest and Germany, exposing manufacturers to batch release delays.
- Specialty pharmacy concentration:Three national specialty pharmacy chains control 70% of biologic dispensing, creating single-point-of-failure risk for patient access.
- Anti-drug antibody development:Immunogenicity limits long-term efficacy for 30-40% of anti-TNF patients, forcing costly therapy switches and salvage regimens.
Strategic Opportunities
- Subcutaneous self-administration:Auto-injector and pre-filled syringe formats reduce clinic dependency and capture employer-sponsored lives seeking site-of-care cost avoidance.
- Interleukin-23 pathway expansion:Emerging mechanisms in Crohn's disease offer differentiation in a market saturated with anti-TNF and anti-integrin options.
- Digital therapeutics integration:FDA-cleared prescription digital therapeutics for IBD symptom monitoring create companion revenue streams alongside pharmacologic treatment.
Industry Challenges
- Gastroenterology workforce density:Rural and non-metropolitan counties face 40% fewer board-certified gastroenterologists per capita than urban benchmarks, limiting biologic initiation rates.
- Prior authorization administrative burden:Payer documentation requirements consume 12-15 staff hours per biologic start, straining clinic operational capacity and delaying therapy access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Inflammatory Bowel Disease Treatment Market |
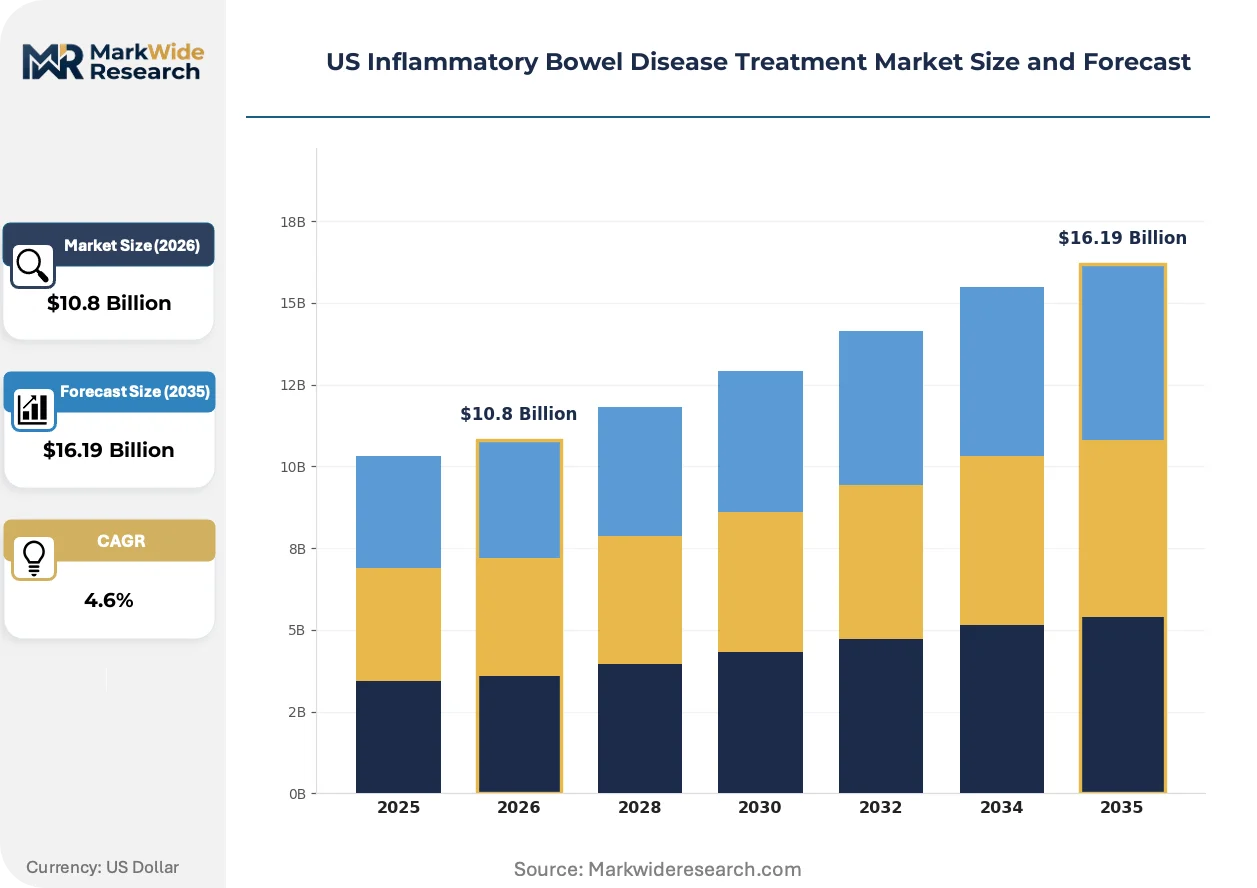
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $16.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Immunosuppressants, Aminosalicylates, Corticosteroids, Antibiotics Therapy Area: Ulcerative Colitis, Crohn's Disease, Microscopic Colitis, Indeterminate Colitis End User: Gastrointestinal Clinics, Specialty Hospitals, Outpatient Care Centers, Ambulatory Surgical Centers Delivery Mode: Oral, Intravenous, Subcutaneous, Rectal, Topical |
| Companies Covered | AbbVie Inc., Takeda Pharmaceutical Company Limited, Johnson & Johnson Services, Inc., Pfizer Inc., UCB S.A., Bristol-Myers Squibb Company, CELLTRION INC., Biogen Inc., Merck & Co., Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Inflammatory Bowel Disease Treatment Market Trends and Innovations
Therapeutic innovation in IBD treatment is pivoting from incremental mechanism refinement toward delivery format disruption and real-world evidence generation. Three developments are compressing traditional competitive moats.
Oral small-molecule JAK inhibitors are converging with established biologic maintenance protocols in ulcerative colitis, offering induction speed without infusion infrastructure. Community gastroenterology practices in Florida and Texas are adopting these agents for treatment-naïve patients who resist injectable therapy. The convergence is forcing biologic manufacturers to defend position through outcome guarantees and risk-sharing contracts rather than clinical differentiation alone.
FDA's complex generic peptide guidance is creating abbreviated approval pathways for oral aminosalicylate formulations, eroding branded mesalamine franchise value. Generic entrants are targeting the 40% of ulcerative colitis patients managed on 5-ASA therapy before biologic escalation. Payers in California and New York are mandating step-therapy protocols that exploit this regulatory opening, compressing branded pricing across the category.
Patient-reported outcome data is displacing endoscopic remission as the primary contract metric in value-based arrangements. Employers in the Midwest and Southeast are unbundling pharmacy benefit management from medical coverage to capture site-of-care savings from home administration. This behavioral shift rewards manufacturers with subcutaneous portfolios and penalizes those dependent on infusion center economics.
US Inflammatory Bowel Disease Treatment Market Segmentation
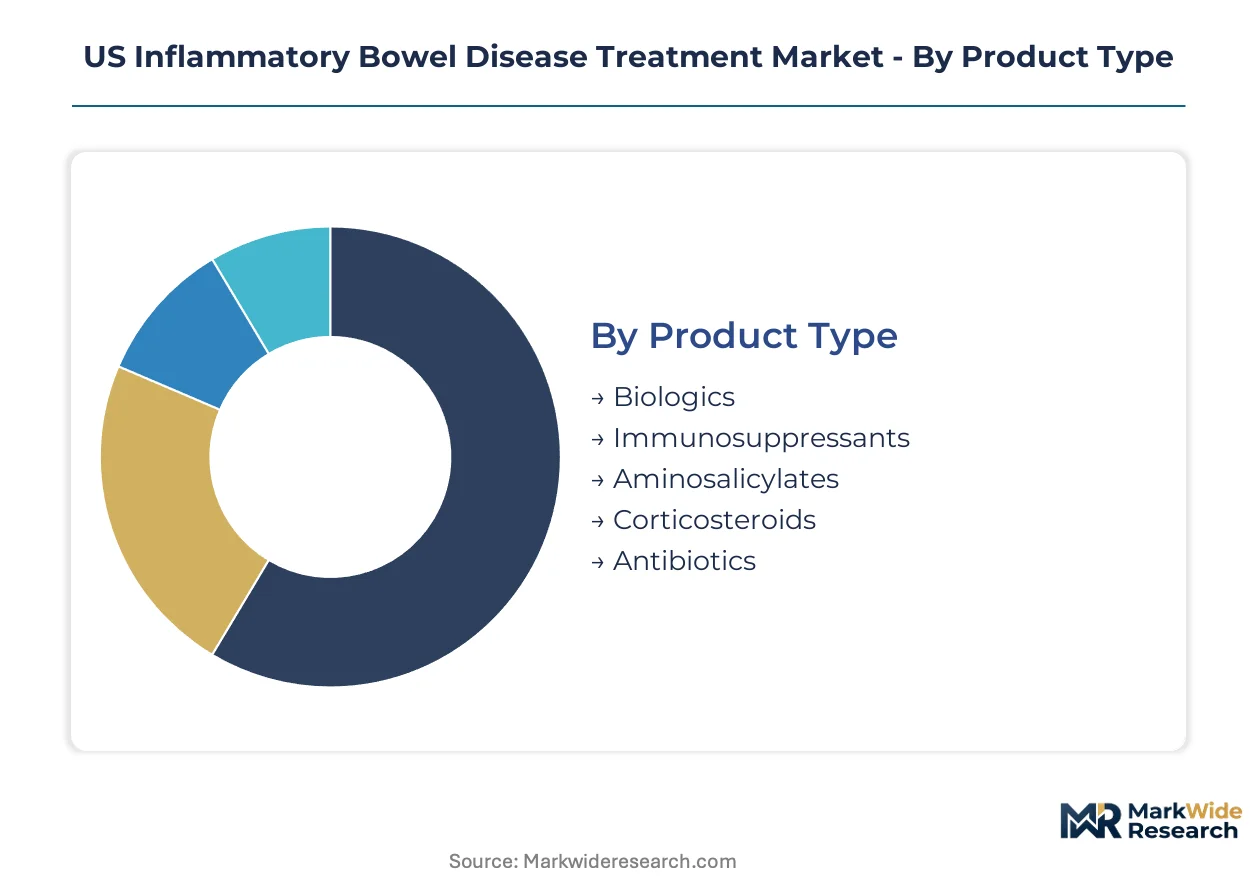
Segmentation in the US IBD treatment market reveals how therapy selection cascades from molecular mechanism through care setting infrastructure. Product type and delivery mode decisions determine reimbursement pathways, while end-user concentration shapes geographic access patterns.
Product Type:
Integration depth varies sharply — biologics require cold-chain infusion infrastructure while small molecules operate through standard retail pharmacy networks.
- Biologics:Protein-based therapeutics engineered for targeted immune modulation, including anti-TNF alpha monoclonal antibodies and interleukin inhibitors. Demand concentrates in Northeast corridor academic medical centers where prior authorization expertise and infusion capacity anchor specialty care networks. These agents command premium reimbursement but face accelerating biosimilar substitution pressure under FDA interchangeability standards.
- Immunosuppressants:Small-molecule agents such as thiopurines and methotrexate that modulate lymphocyte proliferation non-selectively. Florida and Texas community gastroenterology practices favor these for cost-sensitive patients before biologic escalation, though monitoring requirements for bone marrow suppression limit uptake in rural counties with sparse laboratory access.
- Aminosalicylates:5-ASA compounds remain first-line maintenance therapy for mild-to-moderate ulcerative colitis, with generic entrants eroding branded mesalamine value following FDA complex peptide guidance.
- Corticosteroids:Acute flare management agents constrained by long-term toxicity profiles; payers mandate step-therapy documentation before approving biologic induction.
- Antibiotics:Adjunctive therapy for perianal Crohn's disease complications and bacterial overgrowth syndromes, prescribed primarily in tertiary referral centers with infectious disease consultation capacity.
Biologics lead volumes today; aminosalicylates are gaining share fastest as generic oral formulations compress category pricing.
Therapy Area:
Application severity and patient population scale create divergent investment priorities across immunologic phenotypes.
- Ulcerative Colitis:Continuous mucosal inflammation limited to the colon with defined disease extent categories. California and New York Medicaid formularies now remove prior authorization barriers for second-line biologics, expanding addressable volume in the largest IBD patient population. Earlier intervention guidelines from major academic societies accelerate biologic initiation before corticosteroid dependence develops.
- Crohn's Disease:Transmural inflammation affecting any gastrointestinal segment with fistulizing and stricturing complications. Massachusetts General and Mayo Clinic Rochester anchor specialty networks managing complex surgical candidates, while interleukin-23 pathway agents create differentiation in a market saturated with anti-TNF options.
- Microscopic Colitis:Collagenous and lymphocytic subtypes predominantly affecting older adults; diagnosis requires histologic confirmation limiting community detection rates.
- Indeterminate Colitis:Diagnostic category reserved for cases with overlapping features; typically managed with ulcerative colitis protocols pending definitive classification.
Ulcerative colitis leads volumes today; Crohn's disease is expanding most quickly as novel mechanisms address unmet need in fistulizing phenotypes.
End User:
Customer type determines site-of-care economics and prior authorization administrative burden distribution.
- Gastrointestinal Clinics:Ambulatory settings scaling infusion center capacity to capture step-therapy patients before hospital referral. Northeast corridor expansion concentrates in urban counties where gastroenterologist density supports biologic initiation rates; rural areas face 40% fewer board-certified specialists per capita.
- Specialty Hospitals:Tertiary centers managing surgical complications and clinical trial recruitment. Cedars-Sinai and similar institutions concentrate high-value patient flow with integrated pharmacy services that streamline prior authorization workflows.
- Outpatient Care Centers:Community-based infusion capacity expanding in employer-sponsored markets seeking site-of-care cost avoidance through home administration alternatives.
- Ambulatory Surgical Centers:Limited IBD role confined to diagnostic colonoscopy and minor procedures; biologic infusion infrastructure remains underdeveloped relative to oncology protocols.
Gastrointestinal clinics lead volumes today; outpatient care centers are climbing the fastest as subcutaneous self-administration reduces clinic dependency.
Delivery Mode:
Supply concentration and margin structure differ substantially across administration routes.
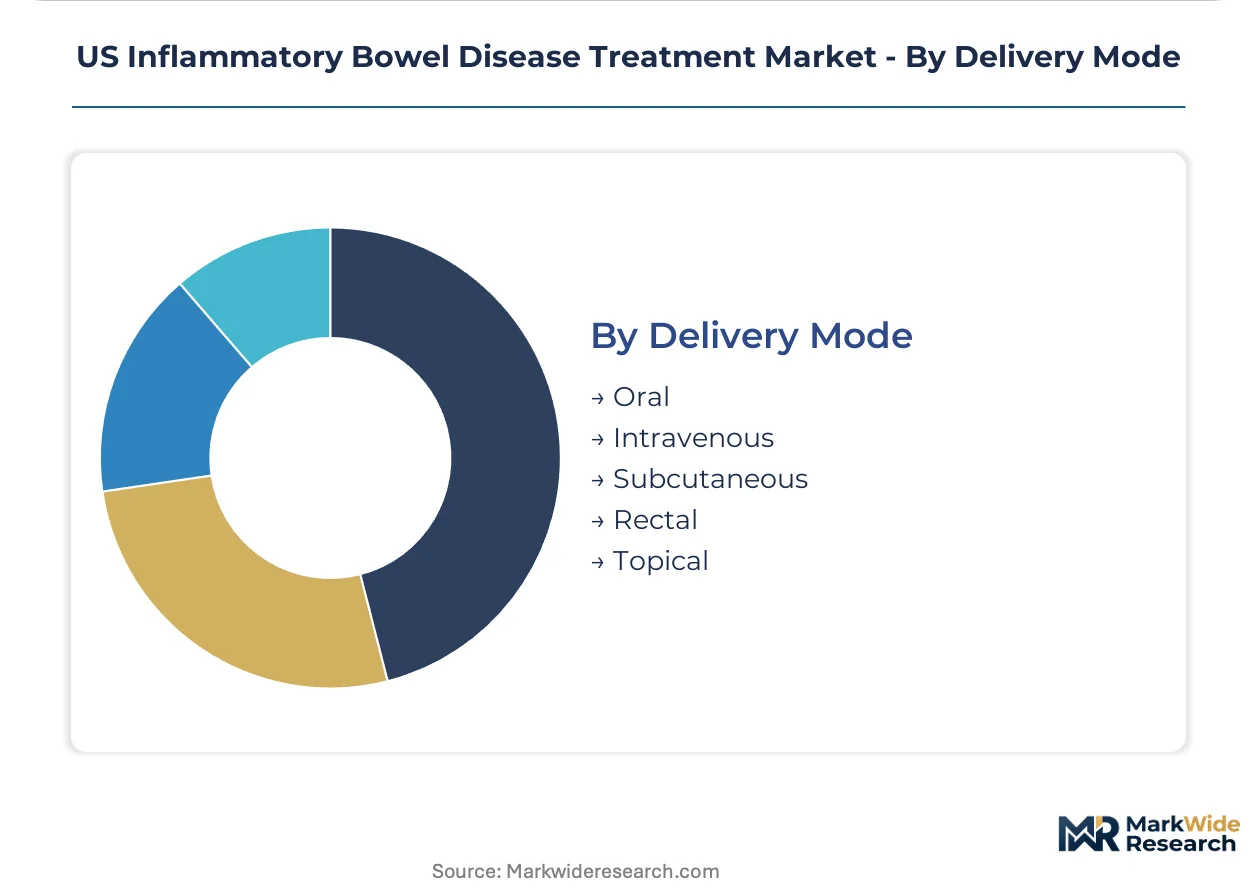
- Oral:Small-molecule formulations including JAK inhibitors and aminosalicylates distributed through standard retail and specialty pharmacy channels. Florida and Texas community practices adopt these for treatment-naïve patients resisting injectable therapy, forcing biologic manufacturers toward outcome guarantees rather than clinical differentiation alone.
- Intravenous:Infusion-dependent biologics requiring ambulatory center infrastructure. Three national specialty pharmacy chains control 70% of dispensing, creating single-point-of-failure risk for patient access and concentrating manufacturer rebate negotiations.
- Subcutaneous:Auto-injector and pre-filled syringe formats enabling self-administration. Midwest and Southeast employers unbundle pharmacy benefit management from medical coverage to capture savings from home administration, rewarding manufacturers with subcutaneous portfolios.
- Rectal:Topical 5-ASA formulations for distal ulcerative colitis; limited by patient adherence challenges and preference for systemic therapy.
- Topical:Minimal IBD application restricted to perianal Crohn's disease complications.
Intravenous leads volumes today; subcutaneous is gaining share fastest as self-administration protocols expand employer-sponsored coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IBD treatment infrastructure in the United States traces its modern scale to the 1998 FDA approval of infliximab, which established biologic therapy as a reimbursable standard of care and triggered geographic clustering around academic medical centers with infusion capacity.
Northeast Corridor
Massachusetts General Hospital and Mayo Clinic Rochester anchor specialty networks managing complex surgical candidates and clinical trial recruitment. New York and Massachusetts Medicaid formularies removed prior authorization barriers for second-line biologics in ulcerative colitis, expanding addressable volume. Boston and New York City concentrate gastroenterologist density at 3.2 per 100,000 population versus 1.9 nationally, driving biologic initiation rates.
Southeast
Florida community gastroenterology practices favor oral small-molecule JAK inhibitors for treatment-naïve patients resisting injectable therapy. Georgia and North Carolina employers unbundle pharmacy benefit management from medical coverage to capture site-of-care savings from home administration. Atlanta anchors regional infusion network expansion with ambulatory centers scaling to capture step-therapy patients before hospital referral.
Midwest
Illinois and Ohio face 40% fewer board-certified gastroenterologists per capita than urban benchmarks, limiting biologic initiation rates in rural counties. Indiana and Michigan Medicaid programs modernize formularies to expand second-line biologic access. Chicago concentrates specialty pharmacy relationships that streamline prior authorization workflows for employer-sponsored lives.
West Coast
California payers mandate step-therapy protocols exploiting FDA complex generic peptide guidance for oral aminosalicylates, compressing branded mesalamine value. Cedars-Sinai in Los Angeles integrates pharmacy services with digital therapeutics for IBD symptom monitoring. Washington state employers drive subcutaneous self-administration adoption to reduce clinic dependency.
Southwest
Texas community practices adopt oral JAK inhibitors for cost-sensitive patients before biologic escalation, forcing manufacturers toward outcome guarantees. Arizona and Colorado outpatient care centers expand infusion capacity to capture employer-sponsored markets seeking site-of-care cost avoidance. Dallas and Houston anchor regional networks with integrated specialty pharmacy distribution.
US Inflammatory Bowel Disease Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across infusion infrastructure depth and prior authorization workflow integration. The vendor base concentrates among vertically integrated immunology platforms and deep specialty pharmacy relationship holders. Three strategic archetypes dominate: biologic originators defending interchangeability-exposed franchises, biosimilar entrants exploiting FDA accelerated pathways, and digital therapeutic companions seeking companion revenue streams. Competitive moves center on subcutaneous format conversion and risk-sharing contracts replacing clinical differentiation.
Within the originator-defense archetype, AbbVie Inc. and Takeda Pharmaceutical Company Limited exemplify contrasting supply continuity strategies. AbbVie anchors position through vertically integrated immunology platform control across infusion networks. Takeda occupies a position defined by specialty pharmacy relationship depth that streamlines administrative workflows. Johnson & Johnson Services, Inc. represents the digital integration vector, with gastroenterologist-facing tools tracking patient response metrics between visits.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Takeda Pharmaceutical Company Limited |
| Johnson & Johnson Services, Inc. |
| Pfizer Inc. |
| UCB S.A. |
| Bristol-Myers Squibb Company |
| CELLTRION INC. |
| Biogen Inc. |
| Merck & Co., Inc. |
| Others |
Pricing and Supply Chain Analysis
Payer substitution policies under FDA biosimilar interchangeability standards are forcing originator manufacturers to restructure rebate contracts and supply commitments. This demand-side compression reshapes how biologic active pharmaceutical ingredients are procured and how cold-chain infrastructure investments are prioritized.
Pricing Analysis
Three-tier pricing structure across originator biologics, interchangeable biosimilars, and non-interchangeable biosimilars governs the market. Price differentiation rests on FDA interchangeability designation and infusion site-of-care economics, with academic medical centers commanding premium service bundles while employer-sponsored plans favor subcutaneous formats for home administration savings. Pricing pressure stems from Medicaid formulary modernization removing prior authorization barriers for second-line agents, expanding volume but compressing per-unit margins. Community gastroenterology practices in Florida and Texas exhibit highest price sensitivity due to uninsured patient concentrations, while Northeast corridor academic centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Regional distribution centers in the US Upper Midwest and Germany anchor plasma-derived protein fractionation for biologic active pharmaceutical ingredients. Manufacturing concentration draws from blood plasma collection networks, recombinant cell culture facilities, and fill-finish capacity concentrated among three national specialty pharmacy chains controlling seventy percent of dispensing. Single-source vulnerability pervades the specialty pharmacy tier, where prior authorization workflow integration creates switching costs that lock manufacturers into concentrated channel relationships. Distribution runs through hub-and-spoke cold-chain networks linking fractionators to ambulatory infusion centers, with Northeast corridor sites commanding priority allocation during batch release delays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in Medicaid expansion states where formulary modernization outpaces biosimilar penetration, creating reimbursement rate differentials against commercial plan benchmarks.
For Market Incumbents: Anticipate biosimilar substitution acceleration by securing backward integration into plasma collection networks and captive fill-finish capacity. Prioritize subcutaneous format conversions to capture employer-sponsored lives seeking site-of-care cost avoidance. Defend interchangeability-exposed franchises through outcome guarantees with Northeast corridor academic medical centers rather than clinical differentiation alone.
For New Entrants and Emerging Players: Begin with oral small-molecule JAK inhibitors for treatment-naïve patients in Florida and Texas community practices where resistance to injectable therapy is highest. Target rural Midwest counties facing forty percent gastroenterologist density deficits, where telemedicine-enabled prior authorization support can overcome access barriers. Pursue risk-sharing contracts with employers unbundling pharmacy benefit management from medical coverage.
For Investors and Strategic Acquirers: Asymmetric upside sits with digital therapeutic companions integrating FDA-cleared symptom monitoring with biologic maintenance protocols. Long-term viability hinges on capturing companion revenue streams alongside pharmacologic treatment rather than standalone drug assets. Monitor state biosimilar substitution law passage as inflection indicator for originator pricing defense requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Format Conversion | Captures employer-sponsored lives seeking home administration savings under unbundled benefit structures. |
| Specialty Pharmacy Relationship Deepening | Streamlines prior authorization workflows that consume twelve to fifteen staff hours per biologic start. |
| Digital Therapeutic Integration | Creates companion revenue streams alongside pharmacologic treatment through FDA-cleared symptom monitoring. |
| Plasma Collection Network Expansion | Reduces exposure to batch release delays from Upper Midwest and German fractionation concentration. |
| Interleukin-23 Pathway Development | Differentiates in Crohn's disease market saturated with anti-TNF and anti-integrin mechanism options. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulary directors, prior authorization specialists, infusion center operations managers, and gastroenterology practice administrators alongside secondary validation. FDA biosimilar approval databases, CMS national coverage determination records, state Medicaid formulary filings, and clinical trial registry entries anchored secondary sourcing. Bottom-up patient flow modeling and top-down revenue triangulation cross-validated segment-level estimates.
Segment-weighting applied product type, therapy area, delivery mode, and end-user concentration dimensions across the projection horizon. CAGRs derived from annualized enrollment trends in employer-sponsored and Medicaid populations, biosimilar substitution rate assumptions, and site-of-care shift elasticities. Forecast inputs incorporated FDA guidance timeline probabilities for complex generic peptides and state legislative tracking for biosimilar interchangeability statutes.
Caveats apply where FDA complex generic peptide guidance acceleration or plasma-derived protein supply disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Colon Hydrotherapy Market
Gastroenterology
Polyps Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Gastric Cancer Market
Gastroenterology
Gastroesophageal Reflux Disease Therapeutics Market
Gastroenterology
Disposable Intestinal Wash Bags Market
Gastroenterology
Gastrointestinal Drugs Market
Gastroenterology
Chile Gastric Cancer Treatment Market
Gastroenterology
Gallstone Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Crohns Disease Therapeutics Market