
 Ulcerative Colitis (UC) Treatment Market | 2026-2036
Ulcerative Colitis (UC) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ulcerative Colitis (UC) Treatment Market Analytics
Buyer concentration among hospital systems and integrated delivery networks is hardening across the UC treatment landscape, with centralized formulary committees now controlling access to high-cost biologics. AbbVie leverages its immunology infrastructure to sustain broad payer contracts across Medicare and commercial plans. Takeda Pharmaceutical Company anchors its position through deep relationships with academic medical centers that manage complex UC cases. Pfizer competes via manufacturing scale that supports reliable supply of oral aminosalicylates and emerging pipeline assets.
Ulcerative Colitis treatment encompasses pharmacologic interventions targeting mucosal inflammation of the colon, with biologics such as anti-TNF agents, integrin inhibitors, and interleukin blockers requiring cold-chain distribution and subcutaneous or intravenous administration. The primary purpose is to induce remission, prevent relapse, and reduce colectomy rates in moderate-to-severe disease. Biologics command the dominant margin pool due to biosimilar erosion timelines and patent cliff dynamics, while oral aminosalicylates retain volume leadership in mild-to-moderate maintenance therapy. Injectable delivery modes are capturing disproportionate growth as patient self-administration programs expand beyond clinic-dependent infusion models.
FDA review standards for IBD biologics, EMA pharmacovigilance requirements for immunosuppressants, and Japan PMDA's conditional approval frameworks collectively elevate clinical evidence thresholds and post-market surveillance obligations. These regulatory architectures shape trial design, labeling claims, and reimbursement negotiations across major markets. Stakeholders must monitor how evolving biosimilar interchangeability designations and real-world evidence mandates reshape competitive positioning without reliance on traditional patent exclusivity structures.
Market Dynamics
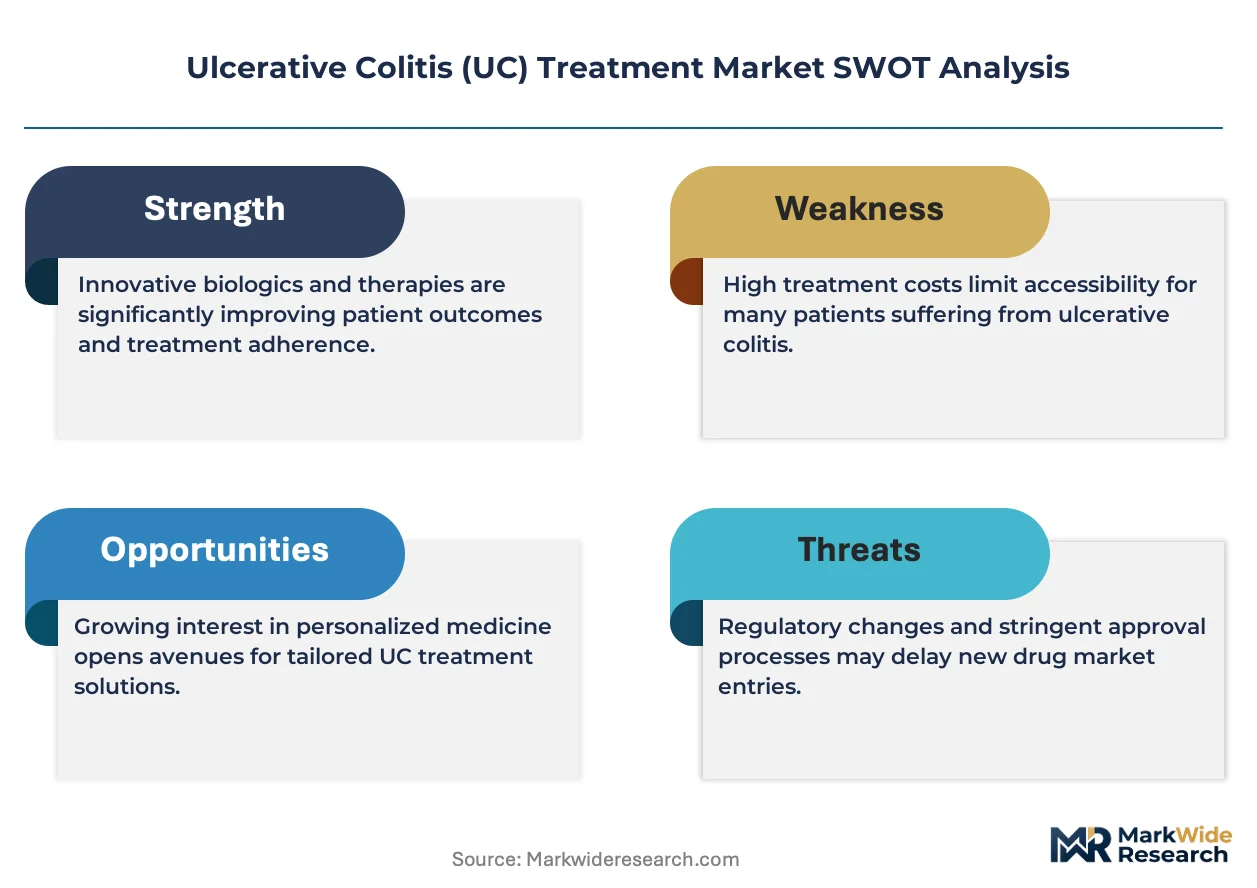
Hospital formulary consolidation is compressing access pathways for high-cost biologics as integrated delivery networks centralize purchasing authority under pharmacy and therapeutics committees.
Growth Catalysts
- FDA Accelerated Approval Pathways:The streamlined review framework for inflammatory bowel disease therapies compresses time-to-market for novel biologics targeting refractory patient populations.
- Self-Administration Technology:Subcutaneous delivery devices are displacing clinic-dependent infusion models and expanding addressable patient pools beyond academic medical center catchments.
- Japan PMDA Conditional Approval:The adaptive licensing framework enables earlier patient access to interleukin inhibitors while generating real-world efficacy data.
Market Restraints
- Cold-Chain Distribution Costs:Temperature-controlled logistics for biologics inflate per-unit delivery expenses by 15-25% versus small-molecule alternatives.
- Biosimilar Erosion Timelines:Patent cliff dynamics for anti-TNF agents compress branded revenue windows ahead of interchangeable biosimilar entry.
- EMA Pharmacovigilance Burden:Post-market surveillance obligations for immunosuppressants elevate ongoing compliance costs and label restriction risks.
Strategic Opportunities
- Specialty Pharmacy Networks:Direct-to-patient distribution channels bypass hospital markup structures and capture margin previously allocated to institutional buyers.
- Real-World Evidence Mandates:FDA and EMA guidance on RWE integration enables label expansion without redundant placebo-controlled trials.
- Pediatric Formulation Gaps:Underpenetrated adolescent UC populations lack approved dosing regimens for existing biologic classes.
Industry Challenges
- Gastroenterology Workforce Constraints:Specialist shortages in community settings delay biologic initiation and suboptimal disease monitoring.
- Prior Authorization Complexity:Payer step-therapy protocols require extensive documentation and create treatment initiation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ulcerative Colitis (UC) Treatment Market |
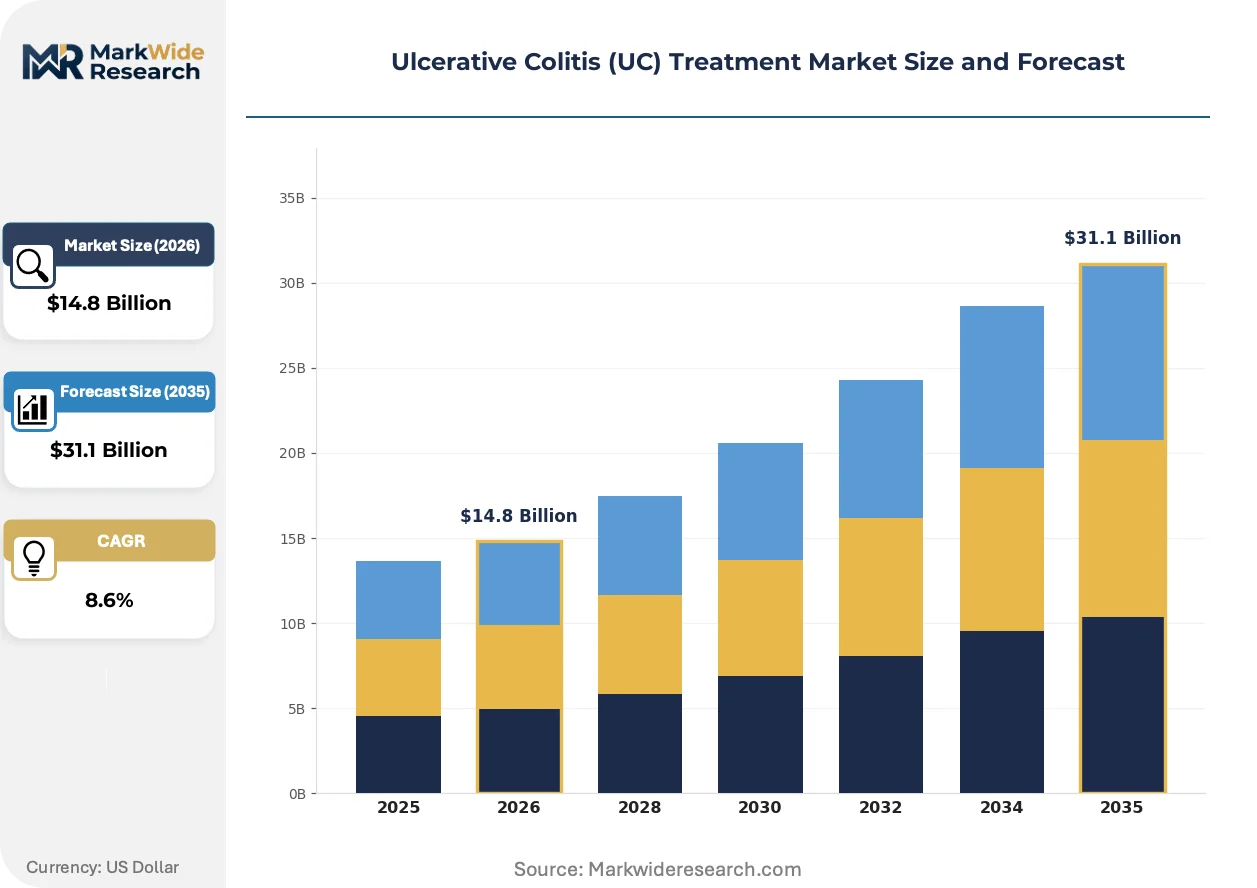
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Aminosalicylates, Corticosteroids, Immunomodulators Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Ambulatory Surgical Centers, Homecare, Clinics Treatment Stage: Induction, Maintenance, Remission, Acute |
| Companies Covered | AbbVie, Johnson & Johnson, Takeda Pharmaceutical Company, Pfizer, Bristol Myers Squibb, Merck & Co., Novartis, Eli Lilly, Gilead Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ulcerative Colitis (UC) Treatment Market Evolving Landscape
Biologic therapy development is pivoting toward precision targeting of mucosal inflammation pathways while distribution models fragment across institutional and direct-to-patient channels.
Oral small-molecule JAK inhibitors are converging with biologic maintenance regimens as gastroenterology practices seek alternatives for patients with anti-drug antibodies. Community-based clinics are adopting these agents at faster rates than academic centers due to simpler storage requirements. This convergence is compressing the historical bifurcation between infusion-dependent biologics and conventional immunomodulators.
The EMA's adaptive licensing frameworks are reshaping how manufacturers sequence Phase III trials across European member states. Sponsors now design master protocols that accommodate heterogeneous reimbursement evidence requirements. Germany's Federal Joint Committee (G-BA) early benefit assessments are forcing earlier health technology evaluation integration into clinical development.
Patient self-administration programs are displacing clinic-based infusion dependency as the default care model for maintenance therapy. Specialty pharmacies are capturing dispensing volume previously routed through hospital outpatient departments. This channel rotation is most pronounced in United States commercial insurance populations where copay assistance programs reduce patient cost exposure.
Ulcerative Colitis (UC) Treatment Market Segmentation
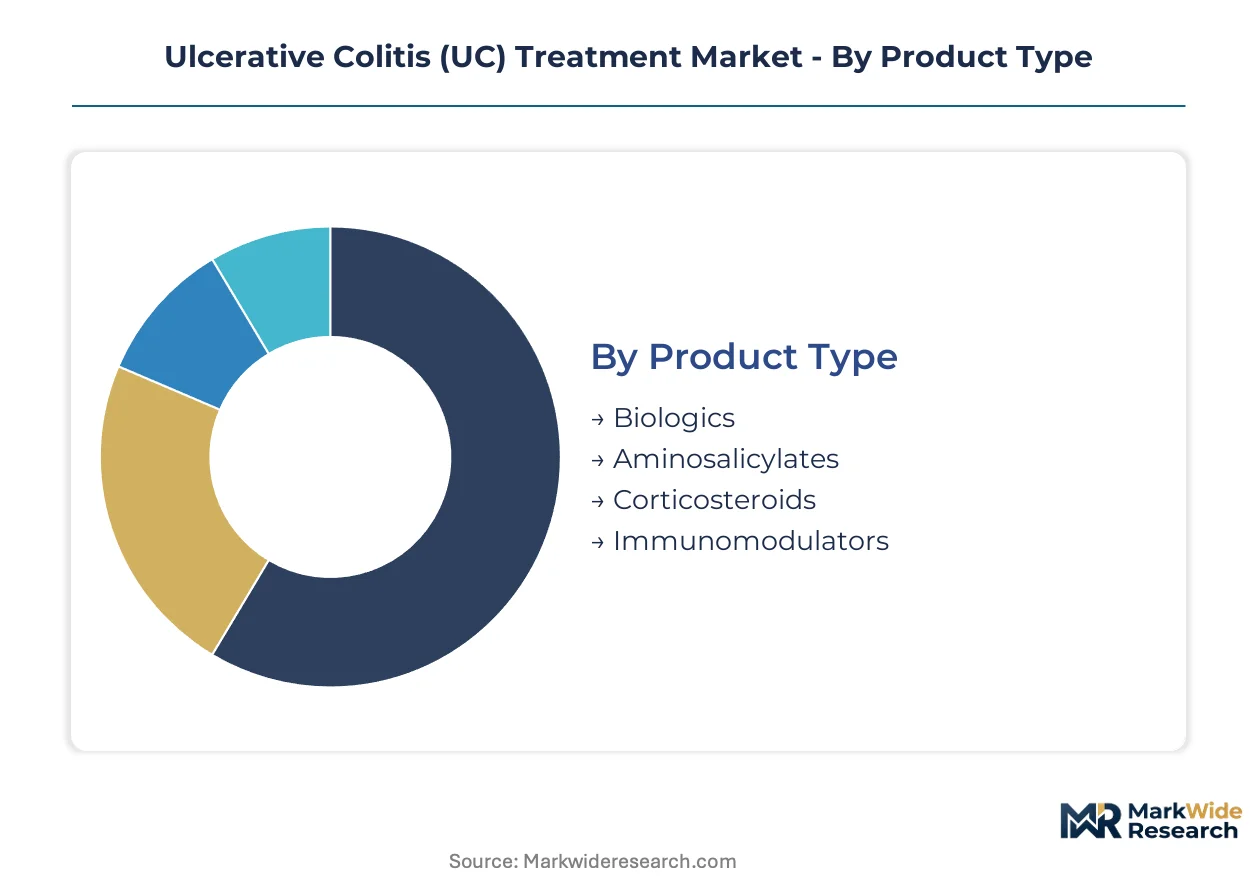
UC treatment segmentation reveals divergent margin structures across therapeutic classes and delivery technologies. Biologics command premium pricing through cold-chain requirements while oral agents sustain volume leadership in maintenance populations.
Product Type:
Volume leadership resides with conventional small molecules, yet margin concentration follows biologic innovation pipelines and patent-protected biologics.
- Biologics:Engineered proteins including anti-TNF agents, integrin inhibitors, and interleukin blockers target refractory disease through precise immunomodulation. Demand concentrates in academic medical centers managing complex cases, driven by step-therapy protocols that reserve these agents for anti-drug antibody failures.
- Aminosalicylates:Mesalamine-based formulations constitute first-line maintenance therapy for mild-to-moderate disease. Community gastroenterology practices in the United States generate the highest prescription volumes, supported by favorable tiering on Medicare Part D formularies.
- Corticosteroids:Systemic and topical glucocorticoids serve acute flare management with rapid anti-inflammatory onset.
- Immunomodulators:Thiopurines and methotrexate bridge therapy for steroid-dependent patients awaiting biologic efficacy.
Mature deployment sits with Aminosalicylates. Newer deployment is concentrated in Biologics.
Delivery Mode:
Patient preference and reimbursement mechanics are redistributing volume across administration routes, with self-administration gaining share fastest.
- Injectable:Subcutaneous delivery devices enable home-based maintenance dosing without infusion center dependency. United States specialty pharmacy networks capture disproportionate dispensing volume as prior authorization protocols favor self-administration for commercial populations.
- Oral:Tablet and capsule formulations dominate aminosalicylate and JAK inhibitor categories. Germany's Federal Joint Committee early benefit assessments prioritize oral agents for outpatient cost containment.
- Intravenous:Hospital outpatient departments retain control over loading doses and anti-TNF infusions.
- Topical:Rectal formulations target distal colitis with localized mucosal delivery.
Established infrastructure supports Intravenous administration. Patient migration is accelerating toward Injectable platforms.
End User:
Channel concentration reflects formulary control dynamics, with institutional buyers consolidating purchasing authority.
- Hospitals:Integrated delivery networks centralize biologic procurement under pharmacy and therapeutics committees. Takeda Pharmaceutical Company anchors relationships with academic medical centers managing severe disease requiring colectomy evaluation.
- Homecare:Direct-to-patient distribution bypasses hospital markup structures through specialty pharmacy networks. United States commercial insurance populations access copay assistance programs that reduce patient cost exposure for self-administered products.
- Ambulatory Surgical Centers:Limited biologic infusion capacity concentrates on stable maintenance patients.
- Clinics:Community gastroenterology practices initiate oral therapy and monitor disease activity.
Procurement authority concentrates in Hospitals. Volume expansion is shifting toward Homecare channels.
Treatment Stage:
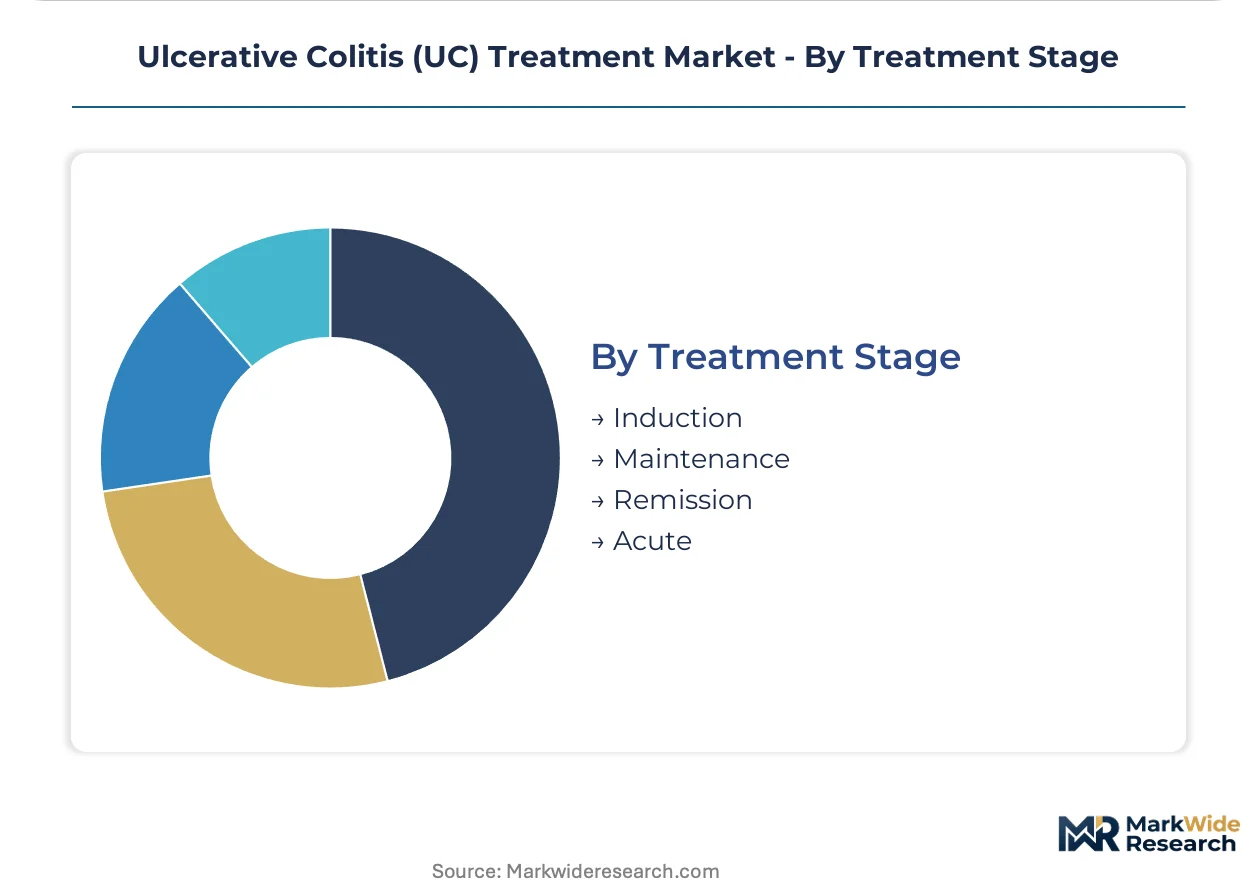
Disease trajectory dictates therapeutic intensity, with acute intervention requiring rapid escalation and maintenance demanding adherence optimization.
- Maintenance:Long-term remission preservation drives recurring revenue through scheduled dosing regimens. Japan PMDA conditional approval frameworks enable earlier patient access to interleukin inhibitors for maintenance populations generating real-world efficacy data.
- Induction:Rapid mucosal healing protocols require intensive therapy to achieve steroid-free remission. FDA accelerated approval pathways compress time-to-market for novel biologics targeting refractory induction failures.
- Remission:Therapy de-escalation decisions balance flare risk against treatment burden.
- Acute:Hospitalization-triggered interventions address severe colitis requiring intravenous corticosteroids.
Recurring revenue concentrates in Maintenance. Regulatory innovation is expanding fastest in Induction protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems concentrate biologic demand through specialty pharmacy networks and prior authorization protocols that favor self-administered products over clinic-dependent infusions.
United States
Medicare Part D formularies and commercial insurance step-therapy protocols drive biologic access decisions through centralized pharmacy benefit managers. FDA accelerated approval pathways for inflammatory bowel disease therapies compress development timelines for novel interleukin inhibitors. The Boston-Cambridge corridor anchors clinical trial density with academic medical centers generating real-world evidence for maintenance therapy positioning.
Germany
Hospital outpatient departments retain procurement authority for intravenous anti-TNF agents under statutory health insurance reimbursement frameworks. The Federal Joint Committee (G-BA) early benefit assessments force manufacturers to integrate health technology evaluation into Phase III trial design. The Rhine-Ruhr metropolitan region concentrates gastroenterology specialist practices adopting oral small-molecule alternatives.
Japan
PMDA conditional approval frameworks enable earlier patient access to biologic maintenance therapies while generating post-market surveillance data. Aging demographics expand the addressable pool of moderate-to-severe cases requiring colectomy evaluation. The Tokyo-Osaka corridor hosts concentrated clinical research organization activity supporting adaptive licensing submissions.
United Kingdom
NICE technology appraisals determine National Health Service formulary placement for high-cost biologics through cost-effectiveness thresholds. Biosimilar tendering programs at integrated care system level compress branded revenue windows for anti-TNF agents. The Greater Manchester and London clusters concentrate inflammatory bowel disease specialist centers managing complex induction failures.
India
CDSCO regulatory pathways for biosimilar interchangeability are reshaping competitive entry for anti-TNF copies in the private hospital sector. Out-of-pocket payment dynamics for biologic therapies concentrate demand in metropolitan tertiary care institutions. The Delhi-NCR and Mumbai-Pune corridors anchor gastroenterology department expansion within corporate hospital chains.
Ulcerative Colitis (UC) Treatment Market Competitive Landscape
United States-based pharmaceutical conglomerates anchor one tier of the competitive structure; Japanese and European specialists hold differentiated positions through regional regulatory relationships and academic medical center networks. The vendor base concentrates around immunology-focused portfolios with cross-indication infrastructure. Three archetypes dominate: diversified biopharmaceutical conglomerates with payer scale, mid-cap specialists with gastroenterology depth, and emerging biotechs with precision-targeted pipelines. Consolidation through bolt-on acquisitions and strategic partnerships for distribution access represent the dominant competitive moves.
Within the diversified conglomerate tier, AbbVie and Johnson & Johnson occupy positions defined by immunology infrastructure breadth and hospital system contracting scale. Takeda Pharmaceutical Company exemplifies the regional specialist archetype with concentrated relationships in Japanese and European academic medical centers. Pfizer represents manufacturing-scale players leveraging reliable supply chains across oral aminosalicylate and emerging pipeline categories.
| Leading Market Players |
|---|
| AbbVie |
| Johnson & Johnson |
| Takeda Pharmaceutical Company |
| Pfizer |
| Bristol Myers Squibb |
| Merck & Co. |
| Novartis |
| Eli Lilly |
| Gilead Sciences |
| Others |
Value Network & Pricing Analysis
Biologic-versus-small-molecule divergence splits the UC treatment market into cold-chain premium tiers and commodity oral maintenance segments, with that bifurcation manifesting in both hospital markup structures and distribution infrastructure investments. Manufacturers of infused anti-TNF agents absorb 15-25% logistics premiums for temperature-controlled fulfillment, while aminosalicylate producers compete on manufacturing scale and raw material sourcing efficiency.
Pricing Analysis
Volume leadership sits with oral aminosalicylates, yet margin concentration flows to patent-protected biologics facing biosimilar erosion timelines. Three-tier pricing structure across premium biologics, standard immunomodulators, and economy oral agents reflects formulation complexity and administration mode. Pricing pressure stems from formulary consolidation under integrated delivery network pharmacy committees. Community gastroenterology practices exhibit highest price sensitivity for maintenance therapies, while academic medical centers prioritize clinical efficacy over acquisition cost for refractory induction cases.
Supply Chain Analysis
Specialized biologics manufacturing workforce availability concentrates in the United States, Ireland, and Switzerland, where FDA and EMA inspection histories anchor contract production decisions. Active pharmaceutical ingredient sourcing for mesalamine derivatives draws from Indian and Chinese chemical synthesis hubs, while monoclonal antibody cell culture media rests on single-source suppliers for specialized growth factors. Tariff exposure on Chinese-sourced starting materials elevates cost volatility for oral therapy manufacturers. Distribution runs through hospital outpatient departments for intravenous loading doses and specialty pharmacy networks for subcutaneous maintenance products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UC treatment market functions as a cost-of-compliance arena where EMA pharmacovigilance burdens and FDA accelerated approval pathways erect regulatory moats favoring incumbents with established post-market surveillance infrastructure.
For Market Incumbents: Hedge biosimilar erosion exposure through pipeline diversification into interleukin inhibitor classes and oral small-molecule JAK inhibitors. Vertical integration into subcutaneous device manufacturing secures channel control as self-administration displaces infusion dependency. Cold-chain logistics capabilities represent a defendable lever against emerging entrants lacking temperature-controlled distribution scale. For New Entrants and Emerging Players: Specialty pharmacy networks offer the most penetrable channel for bypassing hospital formulary gatekeepers, particularly in United States commercial insurance populations with established copay assistance programs. Pediatric formulation gaps present white-space opportunity for biologic dosing regimens in adolescent UC populations. Community gastroenterology practices in Germany's Rhine-Ruhr corridor provide a go-to-market angle for oral agents with simpler storage requirements. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap specialists possessing gastroenterology depth and adaptive licensing expertise given PMDA conditional approval frameworks expanding addressable patient pools. Long-term viability hinges on real-world evidence generation capabilities replacing traditional placebo-controlled trial dependencies. Watch FDA biosimilar interchangeability designations as the inflection signal for branded revenue compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Integration | FDA and EMA guidance enables label expansion without redundant placebo-controlled trials. |
| Self-Administration Device Development | Subcutaneous delivery platforms capture dispensing volume from hospital outpatient departments. |
| Pediatric Formulation Investment | Underpenetrated adolescent populations lack approved biologic dosing regimens. |
| Specialty Pharmacy Network Partnership | Direct-to-patient channels bypass institutional markup structures in United States commercial markets. |
| Adaptive Licensing Pathway Navigation | PMDA conditional approval frameworks compress time-to-market for maintenance therapy positioning. |
Research Methodology
Independent corroboration across gastroenterology department heads, formulary directors at integrated delivery networks, regulatory affairs leads, and payer access specialists underwrites the qualitative findings. Primary interview data triangulates against FDA filings, EMA submission documents, ClinicalTrials.gov protocols, and hospital procurement database records. Bottom-up prescription volume modeling and top-down therapeutic class revenue estimates converge across the analysis window.
Comparable historical periods anchored the forecast framework to anti-TNF patent expiration cycles and biosimilar entry timelines. Segmentation dimensions span therapeutic class, administration route, treatment stage, and regional regulatory cluster. CAGRs derive from patient population epidemiology, step-therapy protocol penetration rates, and pricing elasticity assumptions for infused versus self-administered products.
Caveats apply where biosimilar interchangeability designations, EMA pharmacovigilance enforcement intensity, or gastroenterology workforce shortages could materially shift the outlook. Forecasts reflect assumptions about formulary consolidation velocity and prior authorization protocol stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
Ultrasound Gastroscopes Market
Gastroenterology
Malabsorption Syndrome Treatment Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Stomach Cancer Market
Gastroenterology
Zollinger Ellison Syndrome Treatment Market
Gastroenterology
Gallstone Market
Gastroenterology
Gastrointestinal Drugs Market
Gastroenterology
Global Gastrointestinal Stent Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Polyps Market
Gastroenterology
Digestive Health Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Pouchitis Treatment Market