
 Stomach Cancer Market | 2026-2036
Stomach Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Stomach Cancer Market Analytics
Japan is reconfiguring its domestic biologics manufacturing footprint to reduce import dependency for critical oncology inputs. Novartis AG leverages its Basel-based R&D infrastructure to sustain leadership in targeted therapy development for gastrointestinal malignancies. Pfizer Inc. anchors its competitive position through vertical control over active pharmaceutical ingredient sourcing for cytotoxic agents. Bristol-Myers Squibb Company differentiates via its immuno-oncology franchise, positioning nivolumab-based combinations as first-line standards in selected patient populations.
Stomach cancer encompasses malignant neoplasms arising from the gastric mucosa, classified histologically as adenocarcinoma, lymphoma, or gastrointestinal stromal tumor, with HER2 expression status and PD-L1 biomarker profiles guiding therapeutic selection. The condition demands multimodal management spanning surgical resection, systemic chemotherapy, and precision-directed biologics to extend survival and preserve quality of life. Immunotherapy segments capture disproportionate investment attention as checkpoint inhibitors displace conventional cytotoxic protocols in frontline metastatic settings. Targeted therapy occupies concentrated margin pools where HER2-directed and VEGF-inhibiting agents command premium positioning against biomarker-defined subpopulations.
The FDA's accelerated approval framework compresses development timelines for novel gastric cancer therapeutics, while EMA's centralized marketing authorization demands robust European efficacy data for pan-EU access. Japan's PMDA maintains distinct technical standards for ethnic bridging studies, shaping regional trial design and submission strategies for multinational sponsors. Stakeholders must monitor evolving biomarker-driven label expansions and companion diagnostic co-development requirements to secure sustainable market access across jurisdictions.
Market Dynamics
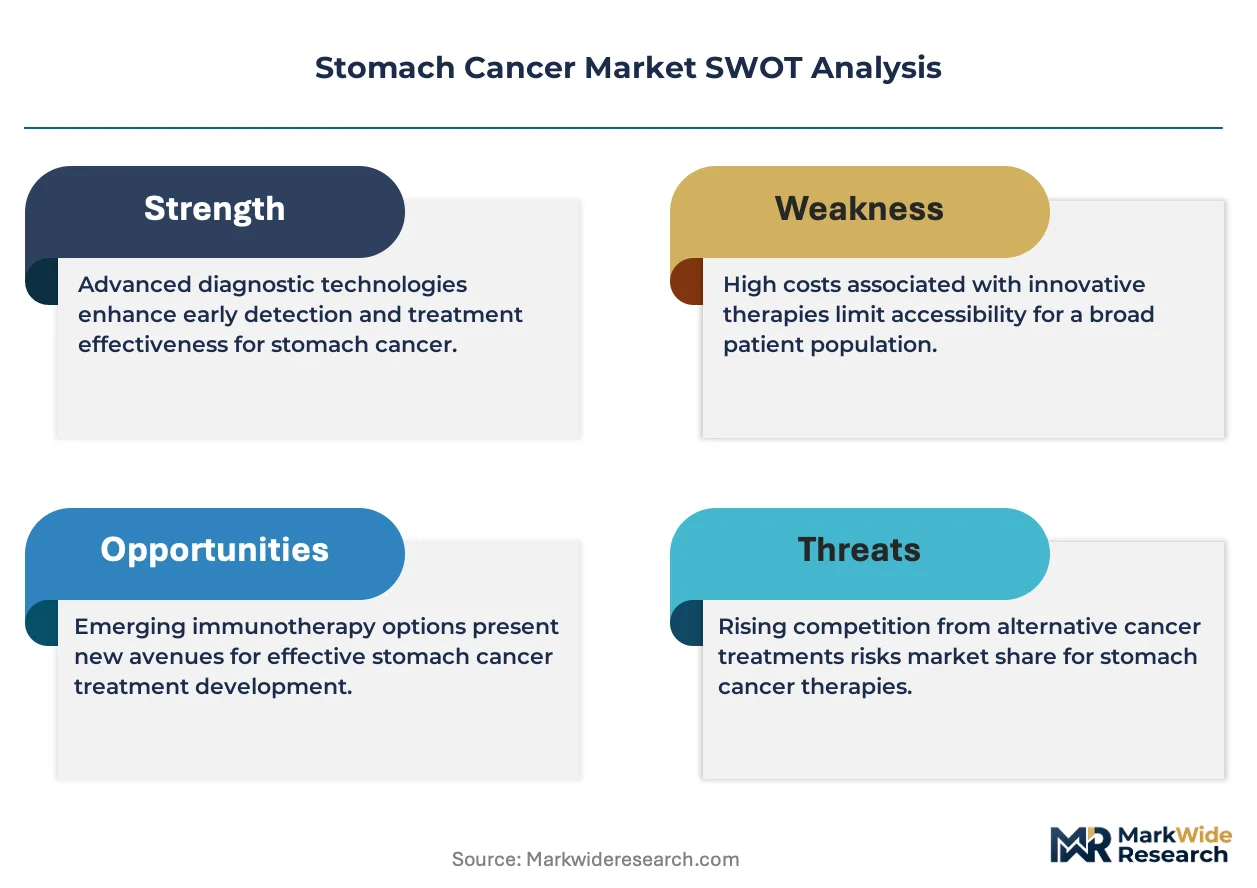
Checkpoint inhibitor combinations are displacing cytotoxic backbones as first-line standards in metastatic gastric adenocarcinoma, forcing incumbent developers to reconfigure trial designs and commercial infrastructure around biomarker stratification.
Growth Catalysts
- Japan's PMDA ethnic bridging framework:Streamlined approval pathways for Asian-specific efficacy data accelerate regional launches for HER2-directed and PD-L1-targeted agents.
- Hospital oncology consolidation:Integrated cancer centers in the United States and Germany centralize purchasing power and standardize combination protocols across multi-site networks.
- Companion diagnostic co-development:Automated immunohistochemistry platforms reduce testing turnaround times, expanding eligible patient pools for precision therapies.
Market Restraints
- API supply concentration:Cytotoxic active pharmaceutical ingredient production clusters in China and India, exposing sponsors to geopolitical disruption and quality enforcement variability.
- EMA centralized authorization demands:Robust European-specific survival data requirements delay pan-EU market access relative to FDA accelerated pathways.
- Platinum salt cost volatility:Fluctuations in iridium and palladium prices compress margins on FOLFOX and FLOT backbone regimens.
Strategic Opportunities
- Claudin 18.2 targeting:Emerging biomarker-defined subpopulations in East Asian populations create first-mover positioning for novel monoclonal antibodies.
- Perioperative immunotherapy integration:Neoadjuvant checkpoint blockade in resectable disease represents an expansion of addressable treatment phases.
- India's CDSCO priority review:Domestic manufacturing incentives and abbreviated approval timelines for oncology orphan indications attract regional investment.
Industry Challenges
- Biomarker assay standardization:Discordant PD-L1 scoring between 22C3 and 28-8 assays complicates patient selection and reimbursement eligibility.
- Cross-border trial recruitment:Divergent informed consent requirements across Japan, South Korea, and China fragment enrollment timelines for multinational studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stomach Cancer Market |
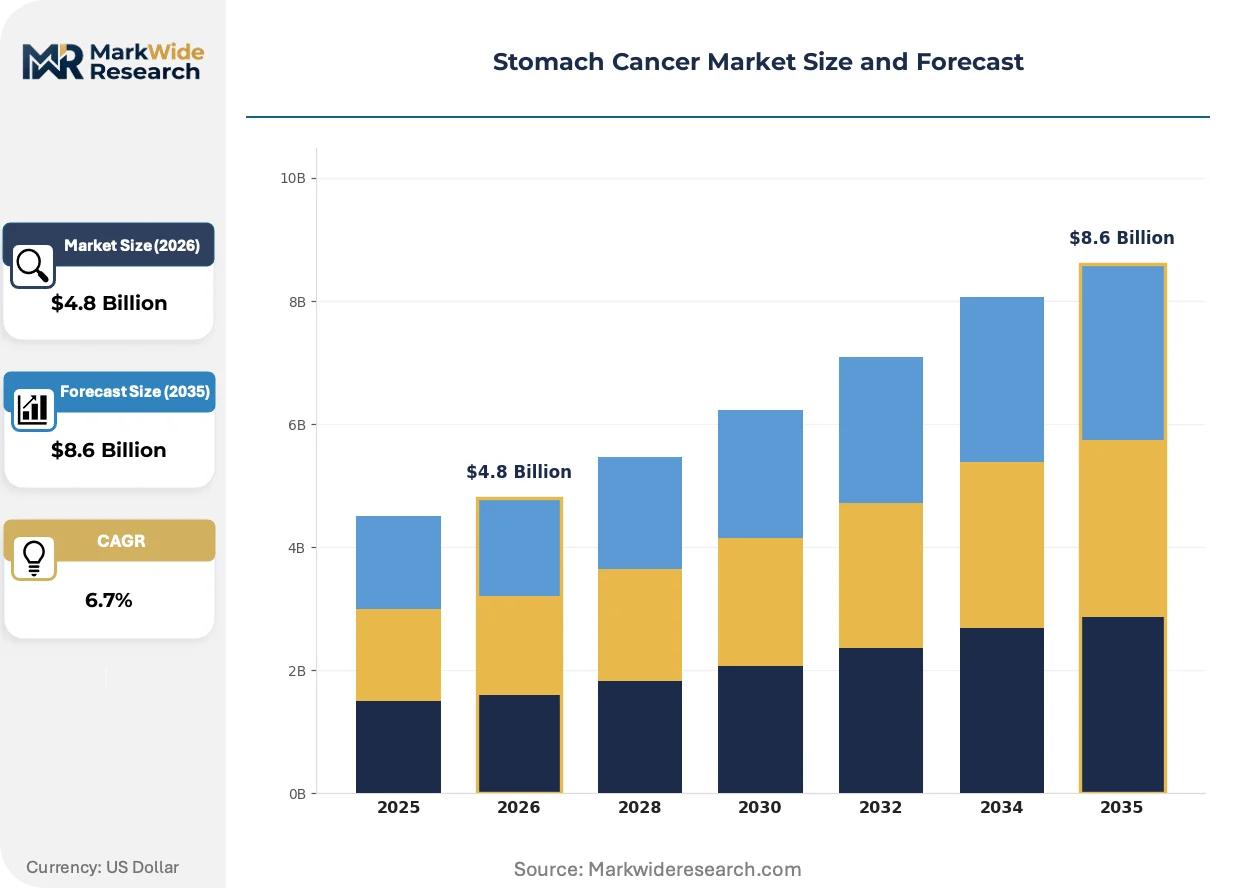
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy Stage: Early Stage, Locally Advanced, Metastatic, Recurrent End User: Hospitals, Clinics, Research Institutions, Home Care Drug Type: Generic Drugs, Brand-name Drugs, Biologics, Chemotherapeutic Agents |
| Companies Covered | Novartis AG, Pfizer Inc., F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Bristol-Myers Squibb Company, AstraZeneca PLC, Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., Samsung Bioepis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stomach Cancer Market Evolving Landscape
Artificial intelligence-driven biomarker discovery and decentralized diagnostic deployment are compressing the interval between molecular profiling and therapeutic initiation, reshaping how treatment decisions are operationalized across care settings.
Next-generation sequencing panels are hybridizing with liquid biopsy workflows to enable real-time clonal evolution monitoring during systemic therapy. Community oncology practices in the United States are adopting these platforms to retain patients who would otherwise transfer to academic centers for molecular triage. This convergence is compressing referral networks and redistributing margin capture toward integrated diagnostic-therapeutic vendors.
The FDA's Project Optimus dose-optimization mandate now requires randomized evaluations of alternative dosing schedules in oncology trials, elevating pharmacometric modeling to a regulatory necessity. Sponsors must now generate exposure-response data earlier in development, extending pre-NDA timelines but potentially expanding label flexibility. Gastric cancer programs with established modeling capabilities gain competitive advantage in protocol design negotiations.
Hospital procurement committees are unbundling drug acquisition from companion diagnostic provision, forcing separate vendor negotiations and price transparency. Academic medical centers in Germany and Japan are piloting direct-to-laboratory contracting for IHC and NGS testing, bypassing traditional distributor markups. This disintermediation pressures legacy commercial models that bundled testing subsidies with drug pricing.
Stomach Cancer Market Segmentation
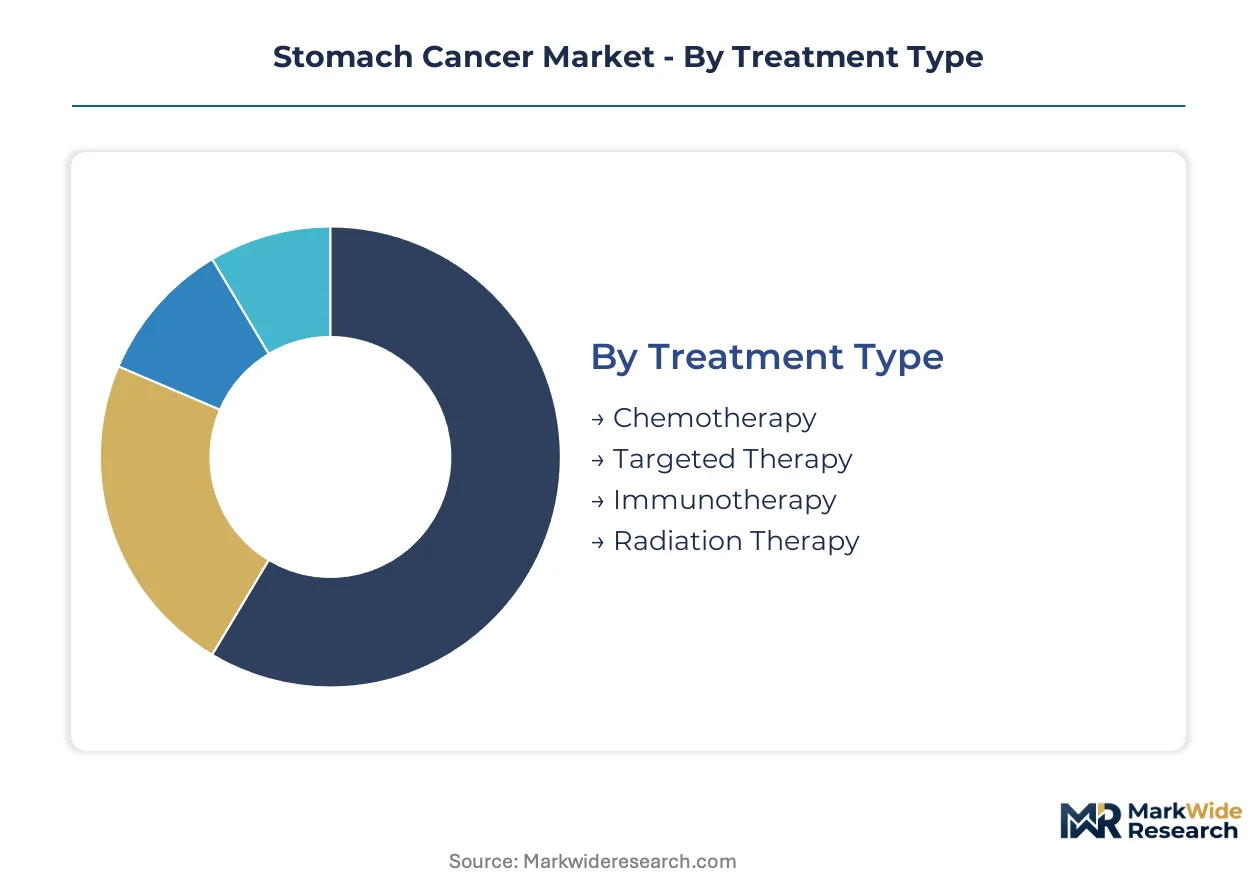
Stomach cancer treatment selection hinges on biomarker status, disease stage, and care setting infrastructure. Segmentation reveals where precision medicine investments concentrate and which delivery channels capture margin.
Treatment Type:
After-sales service intensity varies sharply across modalities, with immunotherapy requiring specialized infusion monitoring and adverse event management protocols.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways demand cold-chain logistics and dedicated nursing support for immune-related adverse event surveillance. United States academic medical centers concentrate demand as they build dedicated immuno-oncology infusion suites.
- Targeted Therapy:HER2-directed agents and VEGF inhibitors require companion diagnostic coordination and pharmacist-led patient education on oral adherence. Japan's PMDA ethnic bridging studies accelerate regional uptake of trastuzumab deruxtecan.
- Chemotherapy:Platinum-fluoropyrimidine backbones dominate volume but face margin compression from biosimilar erosion and generic substitution.
- Radiation Therapy:Intensity-modulated and proton beam modalities concentrate at tertiary centers with capital-intensive equipment footprints.
By volume, chemotherapy leads. By growth pace, immunotherapy is ahead.
Stage:
Cost tier stratification separates curative-intent interventions from palliative protocols, with perioperative regimens commanding premium positioning.
- Metastatic:First-line checkpoint inhibitor combinations now displace cytotoxic monotherapy in PD-L1-positive populations, extending survival benchmarks. Germany's statutory health insurance funds negotiate indication-specific rebates for nivolumab-based regimens.
- Locally Advanced:Neoadjuvant chemoradiation and perioperative FLOT protocols require multidisciplinary tumor board coordination and surgical oncology capacity. United States NCCN guidelines drive standardization across integrated delivery networks.
- Early Stage:Endoscopic resection and limited lymphadenectomy concentrate at high-volume Asian centers with mature screening infrastructure.
- Recurrent:Salvage chemotherapy and clinical trial enrollment dominate, with molecular profiling guiding off-label targeted therapy selection.
Metastatic disease captures the largest addressable spend. Locally advanced stages show steepest expansion trajectory as perioperative immunotherapy gains evidence.
End User:
Customer type determines procurement sophistication, with hospital systems leveraging scale against fragmented clinic purchasing.
- Hospitals:Inpatient oncology units and infusion centers manage complex combination regimens requiring pharmacy compounding and nursing specialization. Japan's cancer care hubs in Tokyo and Osaka centralize gastric surgery volumes.
- Clinics:Community oncology practices adopt oral targeted therapies and subcutaneous immunotherapy formulations to retain patients locally. United States practices invest in in-house NGS panels to reduce academic center referrals.
- Research Institutions:Phase I units and academic medical centers concentrate early-phase checkpoint inhibitor trials and novel agent development.
- Home Care:Oral capecitabine and supportive care medications shift administration burden to patients and caregivers with remote monitoring support.
Hospitals dominate current spend. Clinics are gaining share fastest as oral and subcutaneous formulations expand.
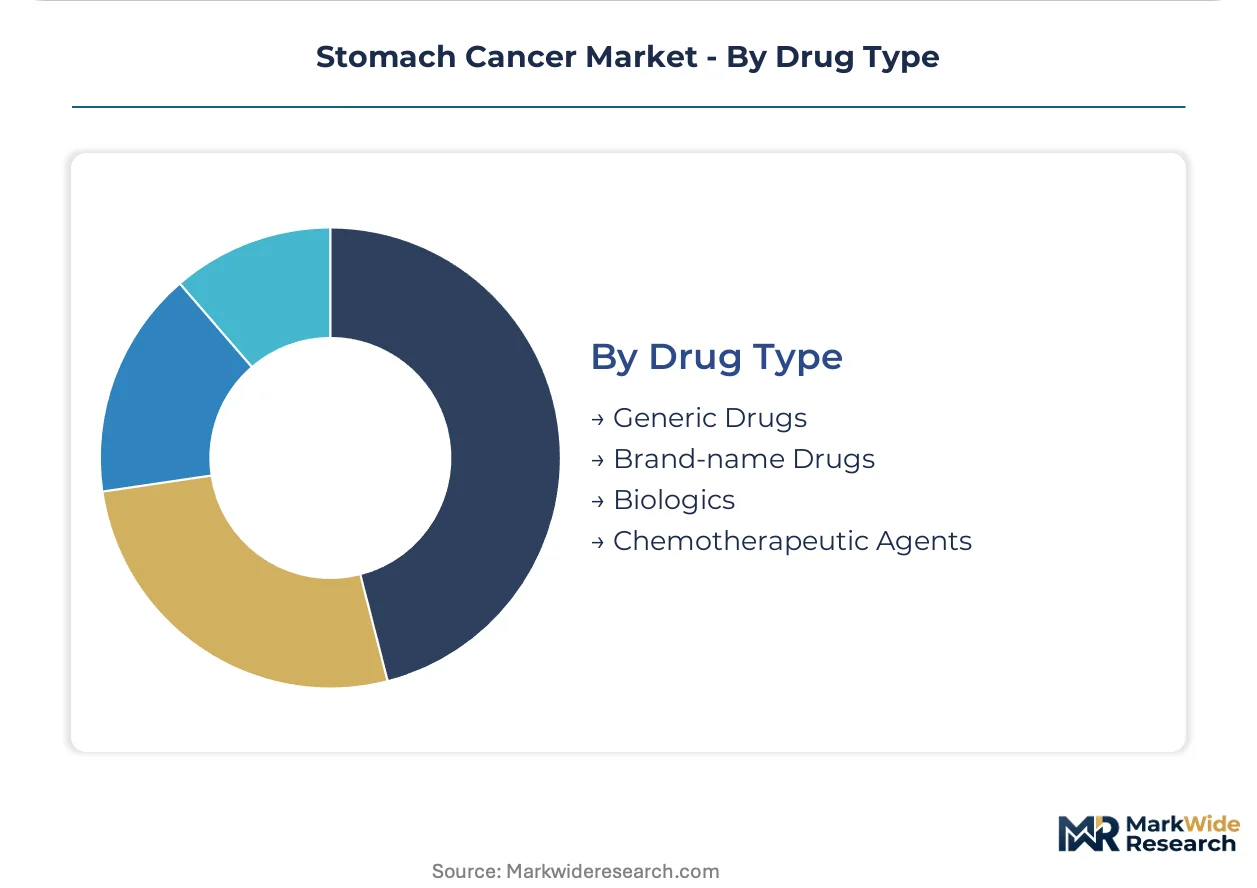
Drug Type:
Margin pools concentrate where manufacturing complexity creates supply barriers and regulatory exclusivity persists.
- Biologics:Monoclonal antibodies and antibody-drug conjugates require mammalian cell culture production and biosimilar defense strategies. Basel-based R&D infrastructure supports gastrointestinal malignancy leadership.
- Brand-name Drugs:Novel small molecules and next-generation checkpoint inhibitors command price premiums against generic backbones. FDA accelerated approval pathways compress commercialization timelines.
- Generic Drugs:Fluoropyrimidines and platinum salts face commodity pricing with API sourcing concentration in China and India creating supply vulnerability.
- Chemotherapeutic Agents:Cytotoxic backbones remain volume anchors but suffer reimbursement pressure and site-of-care shift to lower-cost settings.
Biologics lead by revenue per patient. Generic drugs dominate by prescription volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with Asian markets prioritizing perioperative protocols and Western markets concentrating investment in metastatic checkpoint inhibitor combinations. The United States, Japan, and Germany anchor demand through distinct reimbursement architectures and biomarker adoption velocities.
United States
Medicare's coverage determination for companion diagnostics accelerates HER2 and PD-L1 testing penetration in community oncology settings. The FDA's Project Optimus mandate forces dose-optimization studies into early-phase gastric cancer trials, extending development timelines. Memorial Sloan Kettering and MD Anderson concentrate perioperative immunotherapy trials, reshaping NCCN guideline evolution.
Japan
PMDA's ethnic bridging framework streamlines approval for agents with Asian-specific efficacy data, compressing launch timelines versus Western markets. Universal health insurance eliminates cost barriers to trastuzumab deruxtecan access. Tokyo and Osaka cancer care hubs centralize gastric surgery volumes exceeding 200 cases annually per center.
Germany
Statutory health insurance funds negotiate indication-specific rebates for nivolumab-based first-line regimens, constraining net pricing flexibility. EMA centralized authorization demands robust European survival data, delaying pan-EU access relative to FDA pathways. Heidelberg and Munich academic medical centers pilot direct-to-laboratory diagnostic contracting.
China
NMPA's priority review pathway for oncology innovations accelerates domestic PD-1 inhibitor approvals, intensifying price competition against multinational entrants. National reimbursement drug list negotiations compress margins but expand addressable patient pools. Shanghai and Beijing biotech clusters concentrate antibody-drug conjugate development programs.
India
CDSCO's abbreviated approval timelines for oncology orphan indications attract regional manufacturing investment under PLI scheme incentives. Out-of-pocket payment dominance limits biologic penetration to insured urban populations. Mumbai and Hyderabad pharmaceutical clusters expand biosimilar production for export markets.
Stomach Cancer Market Competitive Landscape
Capability concentration sits with biologics specialists commanding antibody-drug conjugate and checkpoint inhibitor platforms; scale advantage sits with diversified pharmaceuticls with verticalized manufacturing infrastructure. The market structures around three tiers: integrated oncology franchises with immuno-oncology leadership, targeted therapy specialists with companion diagnostic ecosystems, and generic cytotoxic manufacturers facing API supply vulnerability. Dominant competitive moves include portfolio diversification into biomarker-defined subpopulations and strategic partnerships for diagnostic co-development.
Within the integrated oncology tier, Bristol-Myers Squibb Company and Merck & Co., Inc. exemplify checkpoint inhibitor platform leverage, while Novartis AG occupies a position reflecting targeted therapy specialization. These entities anchor competitive dynamics through distinct therapeutic modality priorities rather than overlapping market contestation.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| AstraZeneca PLC |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| Samsung Bioepis |
| Others |
Value Network & Pricing Analysis
China and India concentrate cytotoxic active pharmaceutical ingredient production for platinum salts and fluoropyrimidines, anchoring margin capture downstream with biologics specialists who command antibody-drug conjugate premiums. This upstream concentration creates pricing asymmetry between commoditized chemotherapy backbones and protected immuno-oncology franchises.
Pricing Analysis
Long-term offtake agreements dominate biologics procurement, with hospital systems locking in multi-year supply commitments for checkpoint inhibitors to secure volume discounts against list prices. Price differentiation rests on biomarker stratification and companion diagnostic bundling, where HER2-directed agents command premium positioning against PD-L1 scoring variability. Cost compression in platinum-fluoropyrimidine regimens is intensifying because of biosimilar erosion and API oversupply. Community oncology practices exhibit highest price sensitivity, while academic medical centers prioritize clinical efficacy over acquisition cost.
Supply Chain Analysis
Extended payment terms from multinational sponsors are financing working capital for Indian and Chinese API manufacturers, extending cash conversion cycles for contract manufacturers serving oncology markets. Mammalian cell culture production draws from Basel, Boston, and Singapore biologics clusters, resting on iridium and palladium feedstock volatility for cytotoxic synthesis. Single-source vulnerability concentrates in palladium catalyst suppliers for platinum salt manufacturing. Distribution runs through specialty pharmacy networks and hospital-based infusion centers with cold-chain requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Checkpoint inhibitor adoption in frontline metastatic gastric cancer represents early-cycle expansion, with perioperative immunotherapy integration extending addressable treatment phases beyond palliative settings.
For Market Incumbents: Entrench biomarker-defined positioning by deepening companion diagnostic ecosystems and securing exclusive IHC platform partnerships. Incumbent developers face displacement from emerging Claudin 18.2 targeting programs; backward integration into automated diagnostic deployment protects channel control against unbundling pressures from hospital procurement committees.
For New Entrants and Emerging Players: India's CDSCO priority review pathway offers the most penetrable regulatory entry point for oncology orphan indications, with abbreviated timelines and domestic manufacturing incentives under PLI schemes. White-space targets include perioperative immunotherapy in resectable disease and liquid biopsy-guided patient selection. A hospital-direct contracting model bypasses legacy distributor markups.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed antibody-drug conjugate developers possessing Asian-specific efficacy datasets and PMDA bridging study infrastructure. Long-term viability over a 5-10 year window hinges on biomarker assay standardization and reimbursement pathway clarity. The signal to watch is FDA Project Optimus dose-optimization mandate compliance, which separates modeling-capable sponsors from protocol design laggards.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Automated IHC platforms reduce turnaround times for HER2 and PD-L1 testing. |
| Perioperative Immunotherapy Integration | Neoadjuvant checkpoint blockade expands addressable phases beyond metastatic disease. |
| Ethnic Bridging Study Investment | PMDA's streamlined Asian-specific pathway compresses Japan launch timelines. |
| API Supply Diversification | Domestic biologics manufacturing reduces import dependency for critical oncology inputs. |
| Dose-Optimization Modeling | Pharmacometric capabilities gain FDA negotiation advantage under Project Optimus mandates. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down therapeutic class spend analysis were triangulated to converge on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with treatment line, biomarker status, and regional regulatory cluster serving as core segmentation dimensions. CAGRs were derived from patient incidence projections, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs included checkpoint inhibitor displacement rates in first-line metastatic disease and perioperative immunotherapy trial readouts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian biotech clusters with NMPA priority review access would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Fecal Incontinence Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Biliary Tract Cancers (Btcs) Treatment Market
Gastroenterology
Pouchitis Treatment Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Anal Fissure Treatment Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Disposable Intestinal Wash Bags Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market
Gastroenterology
Polyps Market