
 Global Hysteroscopy Instruments Market | 2026-2036
Global Hysteroscopy Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hysteroscopy Instruments Market Foresight
Aftermarket service revenue for hysteroscope repair and refurbishment is rewriting profit allocation across the value chain. Stryker leverages its endoscopy service infrastructure to capture recurring revenue from capital equipment installed base. KARL STORZ anchors its competitive stance through rigid optics manufacturing depth and direct hospital contracting in European markets. Olympus competes on digital imaging sensor integration, extending its camera system dominance into gynecological applications.
Hysteroscopy instruments are specialized endoscopic devices comprising an optical channel, working channel, and distension medium delivery system, typically manufactured with stainless steel sheaths and sapphire or quartz glass lens assemblies for intrauterine visualization and intervention. Their primary commercial purpose is to enable diagnostic inspection and operative manipulation of the uterine cavity without abdominal incision. Rigid hysteroscopes occupy the largest revenue share due to superior optical resolution and durability in high-volume hospital settings, while flexible hysteroscopes are gaining procedural share in office-based environments where patient tolerance and anesthesia minimization matter. Digital imaging technology is displacing fiber optic systems as the dominant technology segment, with high-definition visualization creating new margin pools through integrated video processing and documentation platforms.
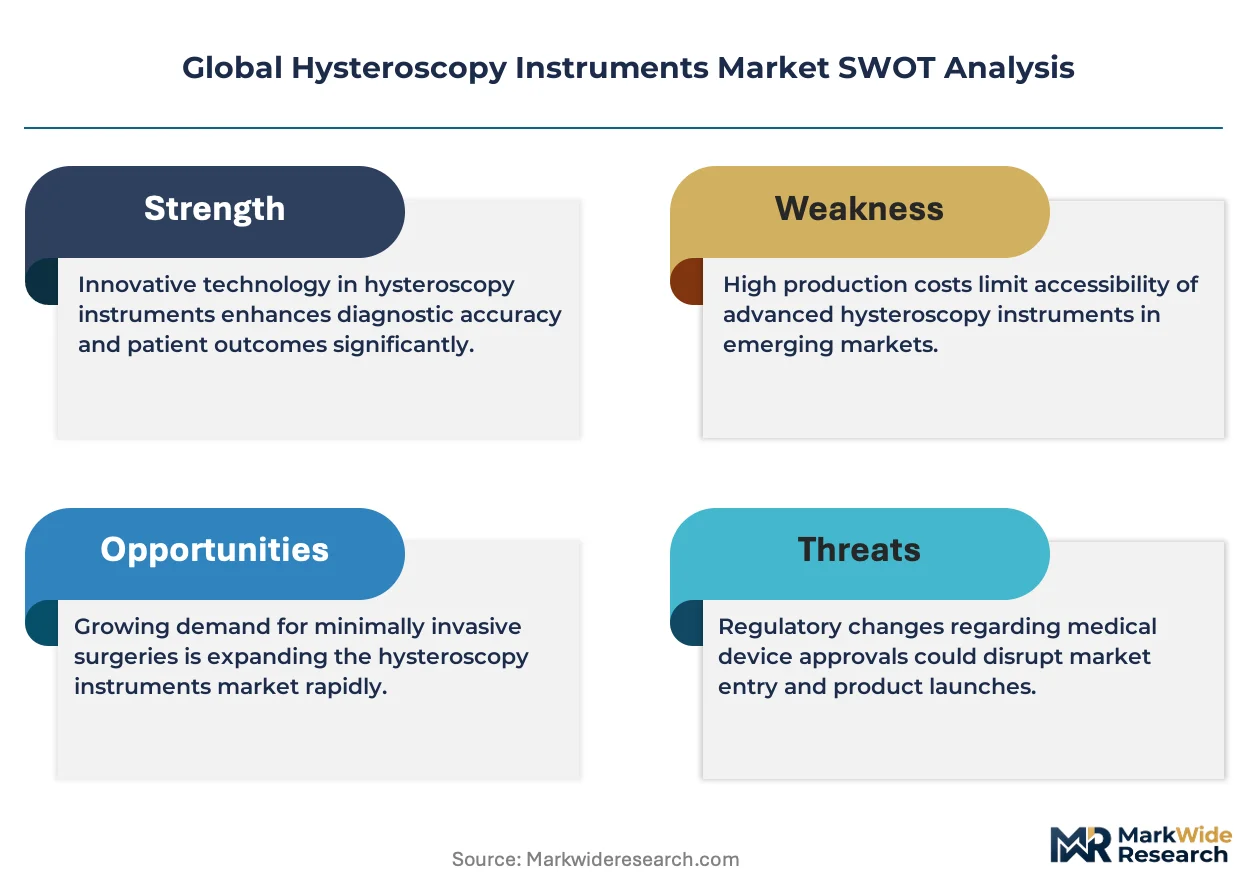
FDA 510(k) clearance pathways shape product development timelines and clinical evidence requirements for hysteroscopic devices entering the United States market, while the EU Medical Device Regulation and CE marking framework impose strengthened post-market surveillance obligations across European jurisdictions. ISO 13485 quality management standards govern manufacturing consistency for instruments distributed internationally. Stakeholders must monitor reimbursement coding revisions for office-based hysteroscopic procedures and evolving sterilization validation requirements that could alter single-use versus reusable instrument economics.
Market Dynamics
The EU Medical Device Regulation is tightening conformity assessment requirements for reusable hysteroscopy instruments, forcing manufacturers to revalidate sterilization protocols and accelerate single-use portfolio development.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Office-based hysteroscopic procedures are capturing procedural volume previously routed to hospital operating rooms, particularly in the United States where CMS reimbursement codes now cover diagnostic hysteroscopy in freestanding settings.
- Digital Imaging Sensor Integration:CMOS and CCD sensor technology is displacing fiber optic bundles in hysteroscope distal tips, enabling 4K visualization platforms that integrate with existing hospital video infrastructure.
- Distension Medium Safety Protocols:FDA guidance on fluid management systems has standardized pressure monitoring and deficit tracking, reducing complication rates and expanding eligible patient populations for outpatient hysteroscopy.
Market Restraints
- Sapphire Lens Supply Concentration:Optical-grade sapphire substrate production concentrates in a limited number of specialty crystal growth facilities, creating vulnerability in rigid hysteroscope manufacturing supply chains.
- MDR Transition Costs:The EU Medical Device Regulation requires renewed technical documentation and clinical evidence for legacy reusable instruments, compressing margins for manufacturers with extensive CE-marked product catalogs.
- Flexible Endoscope Substitution:Office-based gynecology practices are evaluating flexible single-use cystoscopes adapted for uterine access, threatening rigid hysteroscope procedural share in diagnostic applications.
Strategic Opportunities
- Japan's Aging Demographics:Postmenopausal bleeding evaluation protocols in Japanese prefectural health systems are expanding hysteroscopy indications, creating demand for smaller-diameter instruments suited to cervical stenosis cases.
- Artificial Intelligence-Assisted Detection:Machine learning algorithms for endometrial pathology recognition are converging with hysteroscopic imaging systems, enabling real-time diagnostic support during operative procedures.
- Direct-to-Hospital Contracting:Manufacturers are bypassing traditional distributor networks in Germany to secure multi-year instrument and service bundled agreements with university hospital consortia.
Industry Challenges
- Sterilization Validation Expertise:Reusable hysteroscope reprocessing requires specialized knowledge of hydrogen peroxide plasma and ethylene oxide cycles, creating talent scarcity in central sterile processing departments.
- ISO 13485 Audit Compression:Notified body capacity constraints are extending quality management system recertification timelines, delaying product line extensions and geographic expansion plans.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hysteroscopy Instruments Market |
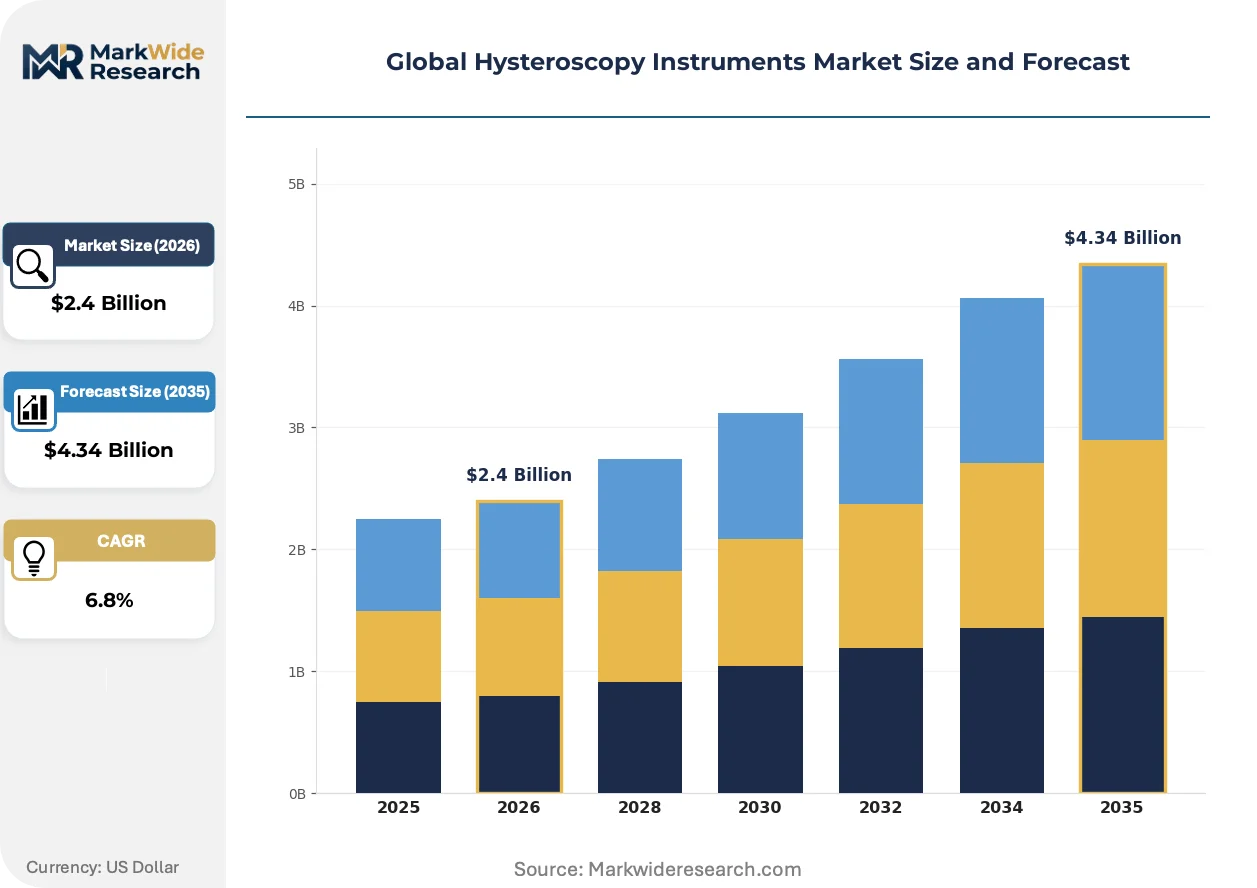
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Hysteroscopes, Flexible Hysteroscopes, Operative Hysteroscopes, Diagnostic Hysteroscopes Technology: Fiber Optic, Digital Imaging, LED Lighting, High-Definition Visualization Application: Endometrial Ablation, Polypectomy, Myomectomy, Adhesiolysis, Biopsy End User: Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories, Research Institutes |
| Companies Covered | Stryker, B. Braun, Olympus, Boston Scientific, Hologic, Medtronic, Ethicon, Richard Wolf, KARL STORZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hysteroscopy Instruments Market Shifts & Advancements
Digital visualization platforms are compressing the traditional hysteroscope value chain by integrating imaging, documentation, and fluid management into unified control systems that displace standalone device procurement.
CMOS sensor technology is migrating from fiber optic hysteroscope systems to chip-on-tip configurations that place the image sensor at the distal end of the insertion tube. Academic medical centers in Germany and the United States are standardizing on 4K resolution platforms for operative hysteroscopy suites. This migration from proximal sensor architecture is enabling slimmer instrument profiles that reduce cervical dilation requirements and expand office-based procedural candidacy.
The EU Medical Device Regulation's strengthened post-market surveillance obligations are extending clinical follow-up requirements for reusable hysteroscopic instruments across European jurisdictions. Manufacturers must now maintain vigilance databases capturing device-related adverse events for the full product lifecycle. High-volume hospital systems in France and Italy are responding by accelerating evaluation of single-use hysteroscope alternatives that eliminate reprocessing liability.
After-sales service contracts are unbundling from capital equipment purchases as ambulatory surgical centers seek third-party repair providers for hysteroscope maintenance. Independent service organizations in Texas and Bavaria are capturing refurbishment volume previously retained by original equipment manufacturers. This behavioral shift is most pronounced in multi-site gynecology practice networks where instrument utilization tracking supports predictive maintenance scheduling.
Global Hysteroscopy Instruments Market Segmentation
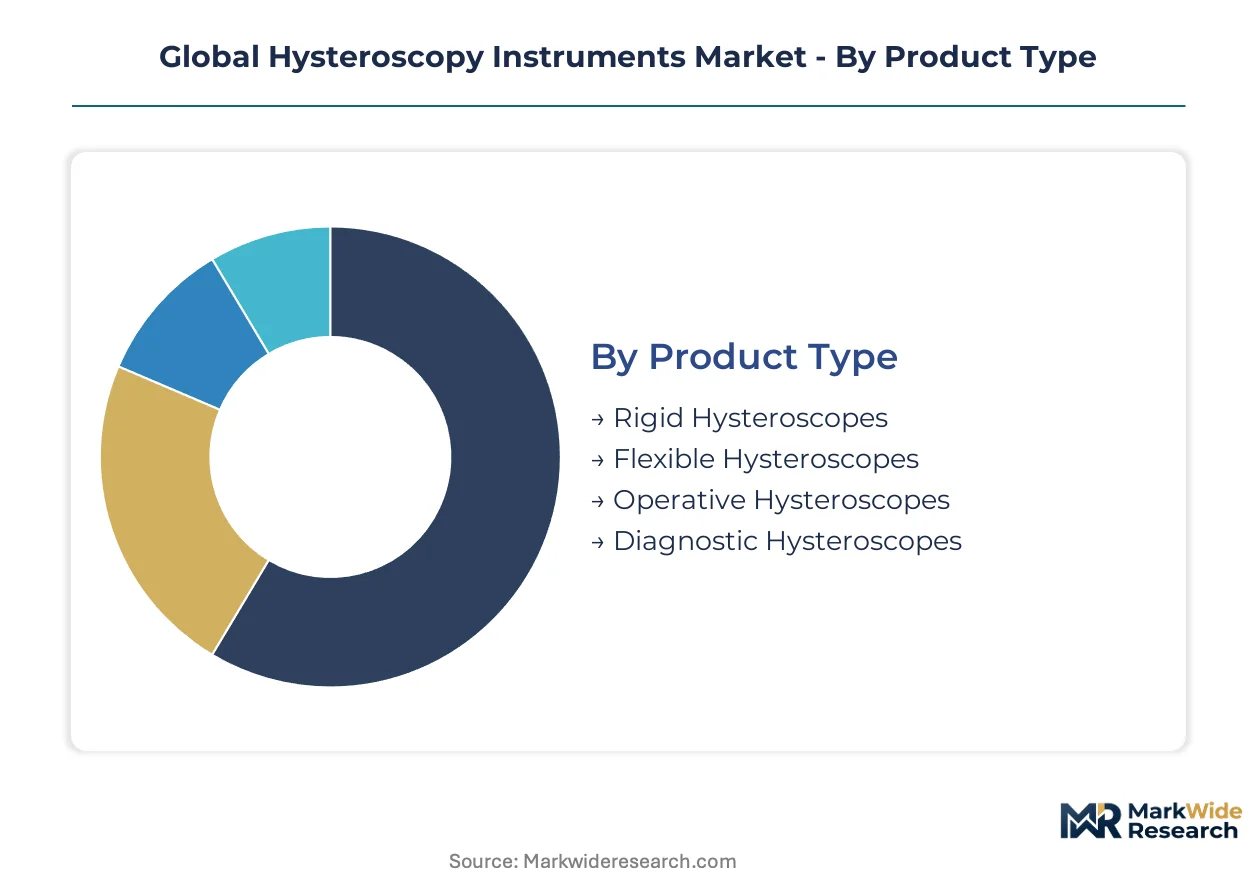
Segmentation in the hysteroscopy instruments market reveals how technology architecture, procedural setting, and clinical application reshape procurement patterns. Manufacturers align R&D portfolios and distribution strategies around these fault lines to defend margin pools and capture procedure volume migration.
Product Type:
Cost tier separation across product architectures determines capital expenditure cycles and service contract economics in hospital and ambulatory settings.
- Rigid Hysteroscopes:Stainless steel sheaths with sapphire glass lens assemblies deliver superior optical resolution and mechanical durability for high-volume operative suites. Demand concentrates in Germany and the United States where university hospital consortia prioritize instrument longevity over acquisition cost. Reprocessing validation requirements under EU MDR are compressing margins for legacy reusable portfolios.
- Flexible Hysteroscopes:Polymer-based insertion tubes with articulating distal tips enable office-based diagnostic procedures without cervical dilation. Adoption is climbing fastest in Japanese prefectural health systems and United States ambulatory surgical centers where anesthesia minimization drives patient throughput. Smaller-diameter profiles suit postmenopausal cervical stenosis cases.
- Operative Hysteroscopes:Integrated working channels accommodate electrosurgical and mechanical tissue removal devices.
- Diagnostic Hysteroscopes:Simplified optical pathways prioritize visualization over intervention capability.
Rigid hysteroscopes hold installed capacity. Flexible hysteroscopes are rotating up the share rankings.
Technology:
Application requirements across diagnostic versus operative procedures determine sensor architecture and illumination system selection.
- Digital Imaging:CMOS and CCD sensors displace fiber optic bundles with chip-on-tip configurations enabling 4K resolution platforms. United States academic medical centers are standardizing on digital visualization suites that integrate with existing hospital video infrastructure. Real-time documentation and AI-assisted pathology detection expand procedural value capture.
- Fiber Optic:Proximal sensor architecture with quartz glass light transmission maintains cost advantage in price-sensitive procurement environments. Demand persists in Italian and French public hospital systems where capital replacement cycles extend beyond typical technology obsolescence curves. Optical degradation and repair frequency elevate total cost of ownership.
- LED Lighting:Solid-state illumination reduces heat generation at the distal tip and extends instrument service intervals.
- High-Definition Visualization:Enhanced resolution standards drive video processor and display subsystem upgrades.
Digital imaging dominates new capital installations. Fiber optic maintains replacement part revenue.
Application:
Procedure complexity and reimbursement coding shape instrument specification requirements across clinical indications.
- Endometrial Ablation:Thermal and radiofrequency energy delivery systems require dedicated hysteroscope configurations with integrated fluid management. United States ambulatory surgical centers are capturing volume previously routed to hospital operating rooms following CMS coding revisions. Distension medium safety protocols mandate pressure monitoring and deficit tracking systems.
- Polypectomy:Mechanical and electrosurgical tissue removal techniques demand versatile working channel configurations. German gynecological practices prioritize instruments compatible with both resectoscopic loops and hysteroscopic morcellators. Procedure volume expansion in office-based settings drives demand for smaller-diameter operative platforms.
- Myomectomy:Submucosal fibroid resection requires robust fluid management and tissue extraction capabilities.
- Adhesiolysis:Intrauterine synechiae division demands precise visualization and gentle tissue manipulation.
- Biopsy:Targeted endometrial sampling prioritizes diagnostic accuracy and specimen quality.
Endometrial ablation anchors revenue concentration. Polypectomy is climbing the fastest.
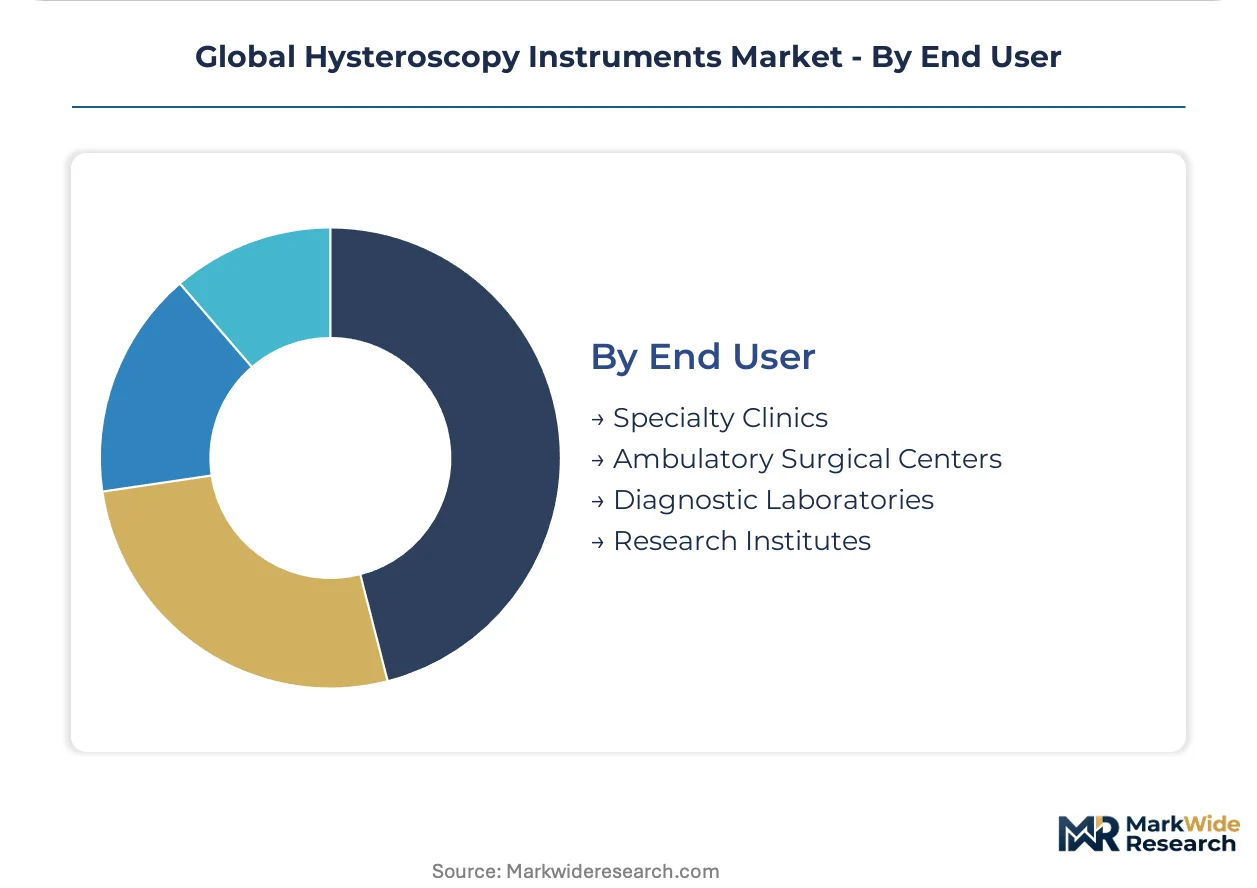
End User:
Customer type determines purchasing authority, service contract preferences, and sterilization infrastructure investment.
- Ambulatory Surgical Centers:Freestanding facilities prioritize single-use and limited-use instruments to eliminate reprocessing liability and central sterile processing overhead. United States multi-site gynecology networks are standardizing on disposable hysteroscope programs with third-party repair contracts for capital equipment. CMS reimbursement codes for office-based diagnostic hysteroscopy accelerate capital deployment.
- Specialty Clinics:Focused gynecological practices balance procedure volume against instrument utilization rates. Japanese metropolitan clinics are adopting smaller-diameter flexible systems for postmenopausal bleeding evaluation protocols. Direct-to-clinic distribution models bypass traditional hospital supply chain intermediaries.
- Diagnostic Laboratories:Pathology-focused settings require specimen retrieval and documentation capabilities.
- Research Institutes:Academic research centers drive early adoption of experimental imaging and AI integration platforms.
Ambulatory surgical centers command procurement velocity. Specialty clinics are expanding addressable procedure volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for hysteroscopy instruments varies sharply across procurement environments. German university hospitals prioritize optical resolution and instrument longevity over acquisition cost. United States ambulatory surgical centers face capital constraints that accelerate single-use adoption.
United States
CMS reimbursement codes for office-based diagnostic hysteroscopy now cover freestanding settings, redirecting procedural volume from hospital operating rooms. FDA 510(k) clearance pathways shape product development timelines for devices entering the market. Texas-based independent service organizations capture refurbishment volume previously retained by original equipment manufacturers.
Germany
University hospital consortia prioritize rigid hysteroscope durability and direct manufacturer contracting over distributor intermediaries. EU Medical Device Regulation conformity assessment requirements force revalidation of sterilization protocols for reusable instruments. Bavarian gynecological practices drive demand for instruments compatible with both resectoscopic loops and hysteroscopic morcellators.
Japan
Prefectural health systems are expanding hysteroscopy indications for postmenopausal bleeding evaluation protocols. PMDA regulatory frameworks govern medical device approval timelines and clinical evidence standards. Metropolitan Tokyo clinics adopt smaller-diameter flexible systems suited to cervical stenosis cases in aging patient populations.
France
Public hospital systems extend capital replacement cycles beyond typical technology obsolescence curves, sustaining fiber optic demand. ANSM post-market surveillance obligations require vigilance databases capturing device-related adverse events. Parisian academic medical centers standardize on 4K resolution platforms for operative hysteroscopy suites.
Italy
High-volume hospital systems accelerate evaluation of single-use hysteroscope alternatives to eliminate reprocessing liability. CE marking technical documentation renewal compresses margins for manufacturers with extensive legacy product catalogs. Northern Italian industrial clusters concentrate optical-grade sapphire substrate processing for rigid hysteroscope lens assemblies.
Global Hysteroscopy Instruments Market Competitive Landscape
Integrated endoscopy conglomerates and specialized optical manufacturers split the market between service infrastructure dominance and component manufacturing depth. Vendor concentration is moderate, with tier-one players controlling installed base expansion while mid-scale specialists capture niche procedural segments. Three archetypes define competitive positioning: diversified medtech platforms with endoscopy service networks, rigid optics specialists with direct hospital contracting capabilities, and single-use instrument innovators targeting ambulatory migration. M&A activity concentrates on digital imaging sensor integration capabilities, while strategic partnerships address EU MDR compliance cost sharing.
Among diversified medtech platforms, Stryker and Olympus exemplify the service-anchored archetype, leveraging endoscopy infrastructure for recurring revenue capture. KARL STORZ occupies a position within the rigid optics specialist tier, with manufacturing depth in sapphire glass lens assemblies and established direct contracting relationships across European university hospital systems. These three companies represent the dominant competitive anchors, each aligning R&D portfolios and distribution strategies around distinct technology migration paths—digital imaging integration, optical component mastery, or single-use portfolio acceleration.
| Leading Market Players |
|---|
| Stryker |
| B. Braun |
| Olympus |
| Boston Scientific |
| Hologic |
| Medtronic |
| Ethicon |
| Richard Wolf |
| KARL STORZ |
| Others |
Supply & Pricing Matrix
Undercapacity in optical-grade sapphire crystal growth facilities is compressing margins for rigid hysteroscope manufacturers while amplifying pricing power for substrate suppliers with qualified production lines. This utilization squeeze propagates through instrument bill-of-materials, forcing OEMs to absorb input cost volatility or accelerate single-use portfolio development that sidesteps lens assembly dependencies.
Pricing Analysis
After-sales service revenue from extended maintenance contracts and refurbishment programs drives lifetime value capture for capital equipment manufacturers. Pricing stratifies across premium, standard, and economy tiers based on optical resolution specifications and ISO 13485 certification status. Cost compression in reusable instrument portfolios is intensifying because EU MDR conformity assessment requirements extend quality management system recertification timelines. Ambulatory surgical centers exhibit highest price sensitivity, prioritizing single-use instruments that eliminate central sterile processing overhead, while German university hospital consortia accept premium positioning for instrument longevity and direct manufacturer contracting.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities have become critical liquidity tools for component suppliers navigating OEM procurement consolidation. Optical-grade sapphire substrate production concentrates in Italy, Germany, and specialized facilities in the United States. Rigid hysteroscope manufacturing draws from stainless steel sheath forging, quartz glass lens assemblies, and CMOS sensor fabrication. Single-source vulnerability in specialty crystal growth operations creates exposure to production disruption. Distribution runs through direct hospital contracting in European markets and GPO-aggregated procurement channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital imaging sensor integration and EU MDR regulatory inflection are disrupting established competitive positions, creating asymmetric opportunity for players with compliance infrastructure and chip-on-tip manufacturing capabilities.
For Market Incumbents: Insulate installed base revenue through backward integration into sapphire lens substrate supply and accelerated single-use portfolio development. Stryker and Olympus should leverage endoscopy service infrastructure to capture recurring revenue from predictive maintenance contracts. KARL STORZ must defend direct hospital contracting relationships in German university consortia against flexible endoscope substitution threats. For New Entrants and Emerging Players: Establish a beachhead in Japanese prefectural health systems where postmenopausal bleeding evaluation protocols expand hysteroscopy indications for smaller-diameter instruments. Target ambulatory surgical center networks in Texas and the United States Southeast with disposable hysteroscope programs bundled with third-party repair services. Pursue regulatory fast-track pathways through FDA 510(k) predicate device strategies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diversified medtech platforms with endoscopy service networks and installed base expansion capabilities. Five-to-ten year viability favors manufacturers with digital imaging integration depth and EU MDR technical documentation expertise. Acquisition targets should demonstrate sterilization validation capabilities or single-use instrument manufacturing scale. Monitor PMDA approval timelines for chip-on-tip hysteroscope platforms as inflection indicator for technology migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation renewal compresses margins for legacy reusable portfolios. |
| Hospital System Partnership | Direct-to-hospital contracting in Germany bypasses distributor intermediaries and secures multi-year agreements. |
| Software Companion Development | AI-assisted pathology detection integration creates real-time diagnostic support and documentation value capture. |
| FDA Submission | 510(k) clearance pathways shape product development timelines for chip-on-tip configurations entering United States market. |
| Reimbursement Strategy | CMS coding revisions for office-based diagnostic hysteroscopy redirect procedural volume to ambulatory settings. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS reimbursement coding archives. Primary interviews engaged gynecological surgeons, hospital purchasing committee members, biomedical engineers specializing in sterile processing, GPO contracts managers, and aftermarket service directors. Bottom-up instrument shipment analysis triangulates against top-down healthcare expenditure allocation models.
Forecast inputs span product type segmentation across rigid, flexible, and operative hysteroscope architectures; technology migration from fiber optic to digital imaging platforms; application concentration in endometrial ablation and polypectomy procedures; and end-user distribution between ambulatory surgical centers and hospital operating suites. CAGRs derive from procedure volume elasticity against reimbursement rate changes and capital replacement cycle analysis. Sterilization validation cost inflation and single-use adoption curves inform substitution modeling.
Sensitivities concentrate around EU MDR notified body capacity constraints, sapphire substrate supply disruption, and flexible cystoscope substitution for diagnostic applications. Forecasts reflect assumptions regarding regulatory enforcement consistency and technology migration pace. Macroeconomic deviation in healthcare capital expenditure, regulatory timeline extension, or breakthrough flexible endoscope platform introduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Laparoscopic Gynecological Procedures Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Medical Penlights Market
Surgical Instruments
Robotic Surgery Market
Surgical Instruments
Surgical Drains Market
Surgical Instruments
Handheld Arthroscopic Instruments Market
Surgical Instruments
Global Surgical Scalpel Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Biosurgery Market
Surgical Instruments
Spain General Surgical Devices Market
Surgical Instruments
Iris Retractors Market
Surgical Instruments
Needle Holders Market
Surgical Instruments
Surgical Stapling Devices Market