
 Recessed Lighting Market | 2026-2036
Recessed Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Recessed Lighting Market Outlook
The EU Green Deal is hardening minimum efficacy thresholds for fixed luminaires across member states. Signify leverages its vertically integrated LED engine production to sustain margin capture under tightening Ecodesign requirements. Acuity Brands anchors North American specification channels through deep distributor relationships. WAC Lighting specializes in architectural-grade trim and housing systems that command premium positioning in hospitality and luxury residential verticals.
Recessed lighting denotes ceiling-embedded luminaires installed within a hollow opening, typically requiring a housing can, trim bezel, and light module with specified lumen output and beam angle. These fixtures deliver ambient, task, or accent illumination while preserving clean ceiling planes in commercial, residential, and institutional interiors. LED product type dominates value capture given superior efficacy and extended operational life versus legacy halogen and CFL alternatives. Retrofit installation type expands fastest as building owners pursue energy upgrades without structural ceiling demolition. Smart lighting technology concentrates margin pools through connected controls integration and circadian programming capabilities.
EMA and ECHA frameworks govern material restrictions and ecotoxicity disclosures for luminaire components sold across Europe. The EU AI Act and cybersecurity certification schemes increasingly shape smart lighting product roadmaps and market access conditions. Building codes in Germany, France, and Italy incorporate daylight harvesting and occupancy sensing mandates that directly determine fixture specification criteria. Stakeholders must monitor evolving interoperability standards and embedded software compliance obligations that will separate contract-capable suppliers from commodity assemblers.
Market Dynamics
The EU Green Deal's escalating efficacy mandates are compressing specification windows for fixed luminaires, forcing suppliers to absorb certification costs while racing to deploy higher-efficiency LED engines ahead of enforcement deadlines.
Growth Catalysts
- Ecodesign Enforcement:The EU's tightening minimum efficacy thresholds for fixed luminaires are accelerating replacement cycles across German office and retail portfolios, converting deferred maintenance into active procurement.
- Retrofit Installation Surge:Building owners across commercial real estate are prioritizing ceiling-preserving LED upgrades over structural demolition, expanding addressable project volume without new construction permits.
- Smart Controls Integration:Connected lighting platforms with circadian programming capabilities are capturing premium specification slots in healthcare and education verticals where occupant wellness metrics influence procurement.
Market Restraints
- Aluminum Housing Cost Volatility:Raw material price swings for die-cast aluminum housings compress margin predictability for mid-tier fixture assemblers lacking long-term supply agreements.
- Driver Electronics Concentration:Taiwan and mainland China dominate LED driver manufacturing, exposing European and North American luminaire brands to geopolitical supply disruption and extended lead times.
- Halogen Phase-Out Complexity:Legacy GU10 socket infrastructure in residential renovation markets creates specification friction as installers encounter compatibility gaps between old housings and new LED modules.
Strategic Opportunities
- Daylight Harvesting Mandates:German and French building codes now require occupancy sensing and daylight-responsive dimming in new commercial construction, embedding fixture specification criteria that favor sensor-integrated suppliers.
- Hospitality Wellness Positioning:Luxury hotel operators are specifying tunable-white recessed systems for guest room circadian alignment, opening premium positioning above commodity ambient lighting.
- Distributor Direct Digital Channels:Specification-grade brands are bypassing traditional rep agencies to capture project data and margin through architect-facing configurators and BIM-integrated specification tools.
Industry Challenges
- Cybersecurity Certification Timelines:The EU AI Act and emerging cybersecurity frameworks for connected lighting are extending product development cycles as firmware validation and third-party testing gates proliferate.
- Legacy DALI-1 Infrastructure:Commercial building automation systems running first-generation DALI protocols require gateway hardware or complete controller replacement to support modern addressable LED drivers, complicating retrofit quoting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recessed Lighting Market |
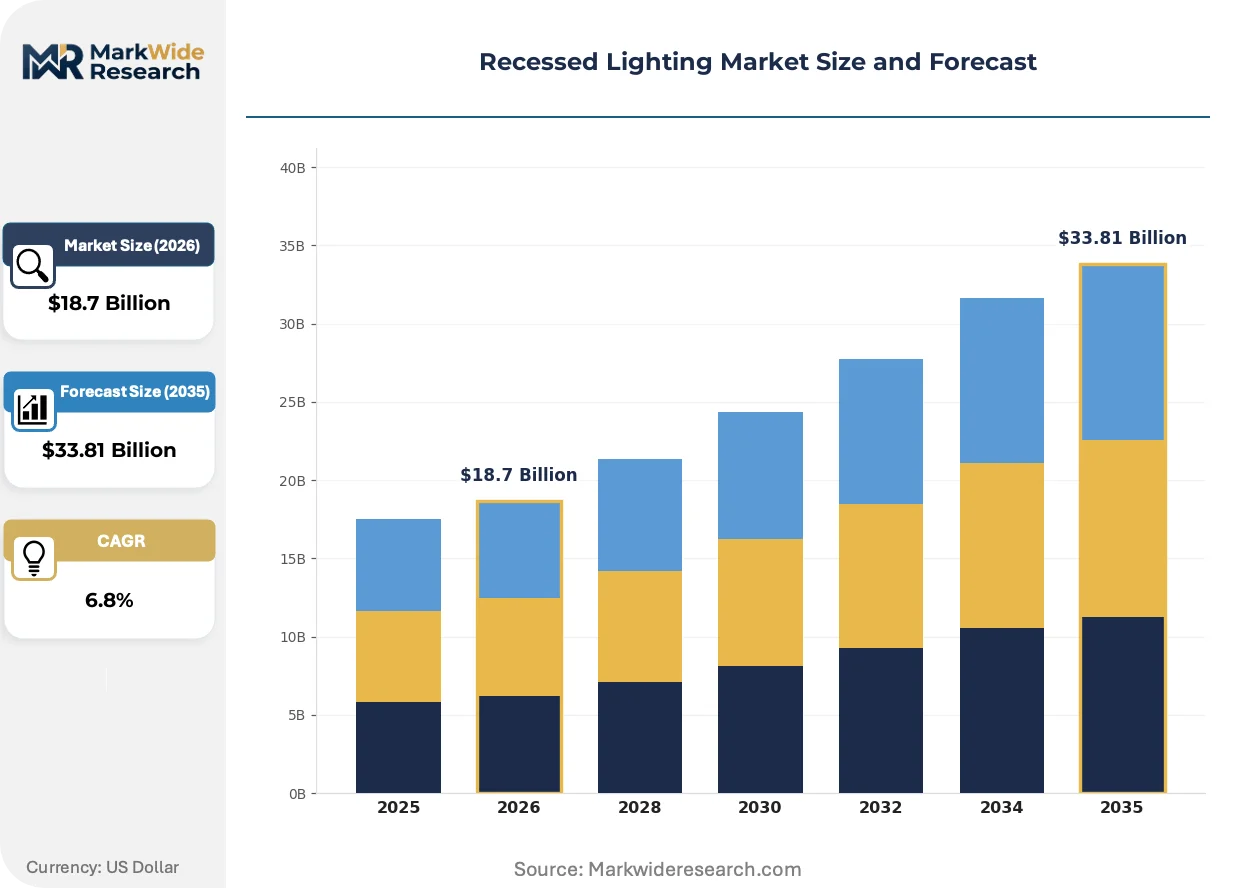
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, CFL, Incandescent Application: Residential, Commercial, Industrial, Hospitality Technology: Smart Lighting, Dimmable, RGB, Solar Installation Type: New Construction, Retrofit, Ceiling Mounted, Wall Mounted |
| Companies Covered | Eaton (Halo), WAC Lighting, Philips (Signify), RC Lighting, Nora Lighting, Acuity Brands, Lithonia Lighting, TORCHSTAR, Cree Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recessed Lighting Market Strategic Shifts
Recessed lighting specification is pivoting from lumen-per-watt efficiency metrics toward integrated system performance, where fixture selection now encompasses wireless control compatibility, embedded sensor density, and software update architecture.
Chip-on-board LED arrays with integrated optics are absorbing specification share from discrete SMD configurations in high-lumen commercial downlights, enabling tighter beam control and reduced thermal management complexity. Corporate headquarters and flagship retail chains are specifying these modules for 50,000-hour maintenance-free operation, compressing the addressable market for field-replaceable lamp formats.
France's ANSM and Germany's KBA-aligned building efficiency regulators are tightening disclosure requirements for luminaire component ecotoxicity under ECHA framework extensions, compelling suppliers to requalify housing coatings and PCB substrates ahead of 2027 enforcement windows. Manufacturers with pre-validated material libraries are capturing specification priority in public sector procurement where compliance documentation gates bid eligibility.
Architects and lighting designers are consolidating specification authority through master specification templates that pre-approve three to four qualified brands per fixture category, displacing distributor influence over final product selection. This concentration is most visible in US commercial office development where developer-standardized design guidelines reduce variability across multi-building portfolios, compressing market access for unlisted suppliers.
Recessed Lighting Market Segmentation
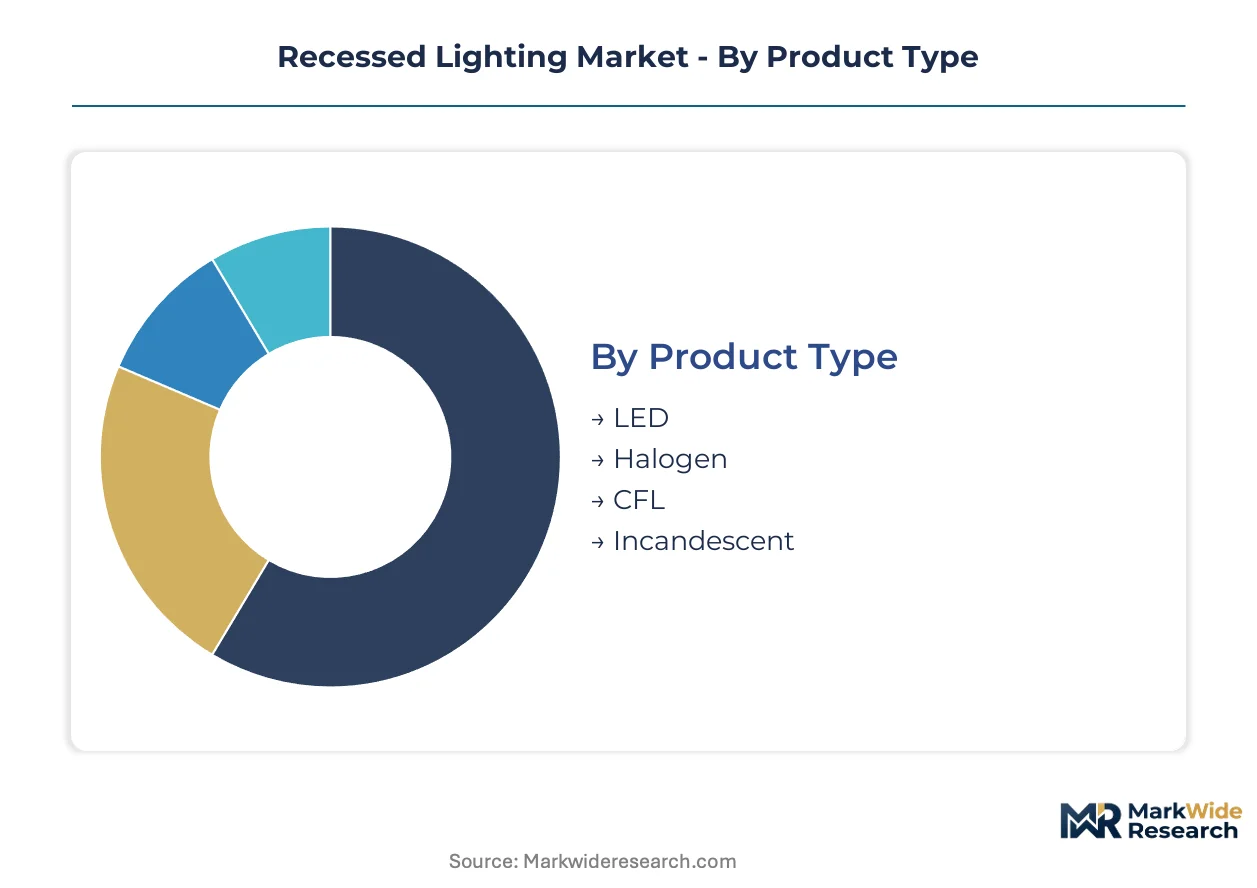
Recessed lighting procurement follows distinct specification pathways where product architecture, installation constraints, and control technology determine margin capture. Segment boundaries reflect divergent certification burdens, supply chain configurations, and customer procurement authority across residential, commercial, and institutional channels.
Product Type:
LED modules face Ecodesign efficacy mandates and CE marking complexity, while legacy formats navigate phased obsolescence under EU Green Deal timelines. Halogen and CFL categories carry diminishing certification relevance as enforcement hardens.
- LED:Chip-on-board arrays with integrated optics dominate commercial downlight specifications, delivering 50,000-hour maintenance-free operation. German office and retail portfolios drive volume as Ecodesign enforcement accelerates replacement cycles. CE marking and Ecodesign compliance documentation gates bid eligibility in public sector procurement.
- Halogen:GU10 socket infrastructure persists in residential renovation markets, creating specification friction with compatibility gaps between legacy housings and retrofit LED modules. France and Italy still report residual demand in heritage building applications where dimmer compatibility constraints limit LED substitution.
- CFL:Compact fluorescent formats retain niche presence in price-sensitive commercial retrofits where immediate capital constraints override lifecycle cost analysis.
- Incandescent:Decorative and specialty applications in hospitality verticals sustain minimal volume where warm dimming characteristics resist LED replication.
LED sits at the top of the volume ranking, with halogen climbing the fastest in residential retrofit channels where installer familiarity delays technology transition.
Application:
End-use verticals diverge sharply in procurement authority, specification complexity, and control system integration requirements. Commercial and hospitality segments concentrate premium product absorption.
- Residential:Homeowner-driven procurement favors retrofit-compatible formats and price-accessible trim systems. German multi-family housing renovation cycles expand addressable project volume without new construction permits.
- Commercial:Corporate headquarters and flagship retail chains specify tunable-white and sensor-integrated systems where daylight harvesting mandates in Germany and France embed fixture criteria. Building automation integration determines supplier qualification.
- Industrial:High-bay and hazardous location applications demand IP-rated housings with extended temperature tolerance. Energy-intensive manufacturing facilities in Poland and Czech Republic prioritize efficacy over aesthetic trim refinement.
- Hospitality:Luxury hotel operators specify circadian-aligned tunable-white systems for guest room wellness positioning. Paris and Milan design hotels command premium above commodity ambient lighting through architectural-grade specification.
Commercial applications absorb the highest value concentration, with hospitality gaining share fastest through wellness-oriented premium positioning.
Technology:
Control capability tiering determines margin structure, with connected platforms requiring cybersecurity validation under emerging EU AI Act frameworks. Basic dimming functions face commoditization pressure.
- Smart Lighting:Wireless control compatibility and embedded sensor density capture premium specification slots in healthcare and education verticals. Firmware validation and third-party testing gates extend product development cycles under cybersecurity certification timelines.
- Dimmable:Phase-cut and 0-10V protocols remain standard in commercial retrofits where legacy infrastructure limits addressable driver deployment. Compatibility verification with existing wall controls dominates procurement criteria.
- RGB:Color-tuning systems concentrate in hospitality and entertainment applications where dynamic scene programming differentiates experiential spaces.
- Solar:Off-grid and remote installation applications sustain minimal volume, constrained by battery storage economics and lumen output limitations.
Smart lighting commands the steepest margin tier, with dimmable formats retaining volume leadership across retrofit-dominant markets.
Installation Type:
Structural intervention requirements determine project economics, with ceiling-preserving methods expanding addressable volume in occupied building upgrades. New construction channels concentrate specification-grade procurement.
- New Construction:Integrated ceiling planning enables specification-grade housing and trim systems with optimal thermal management. German commercial development pipelines concentrate volume where building codes mandate occupancy sensing and daylight-responsive dimming.
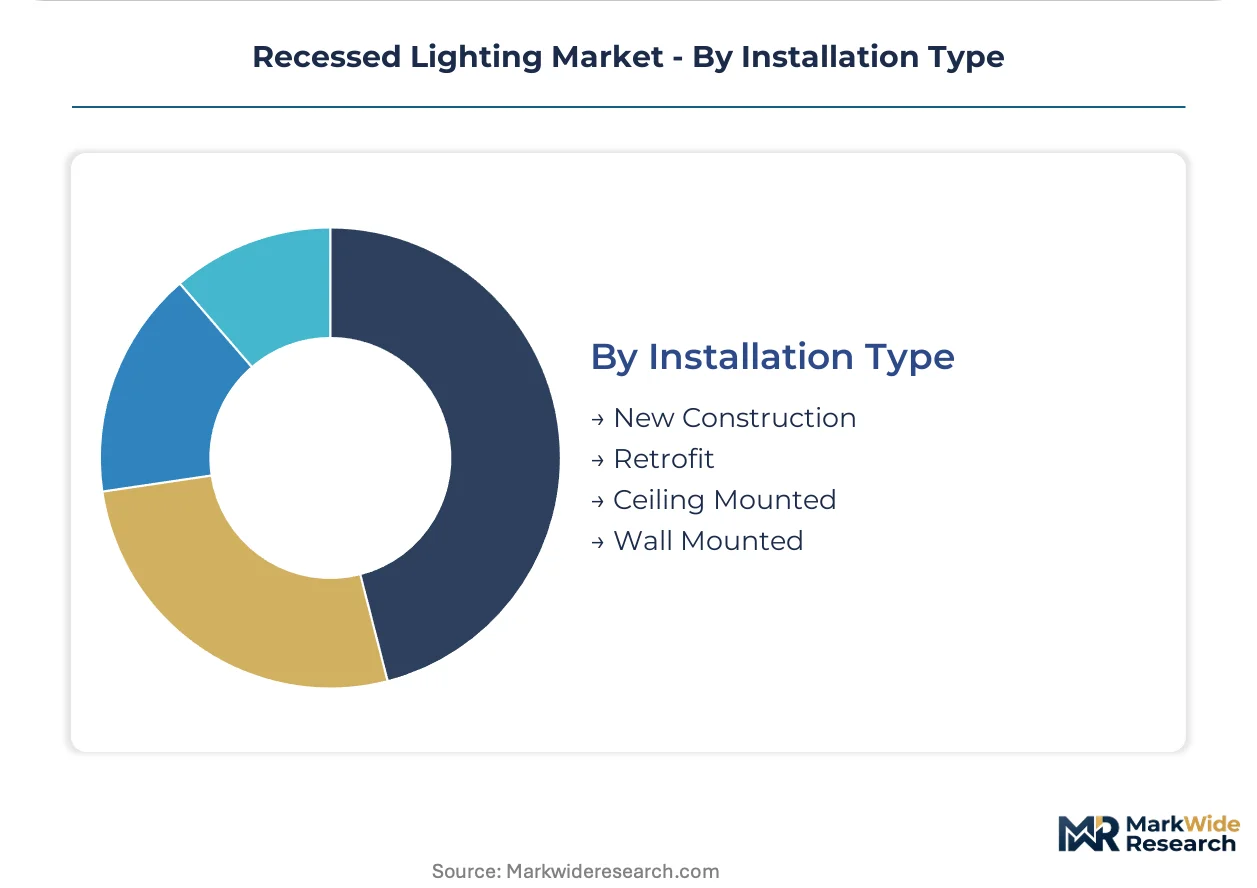
- Retrofit:Ceiling-preserving LED upgrades bypass structural demolition and permitting delays, converting deferred maintenance into active procurement across French and Italian commercial real estate portfolios.
- Ceiling Mounted:Surface and semi-recessed formats accommodate concrete slab constraints where hollow ceiling cavities are unavailable.
- Wall Mounted:Architectural accent applications in galleries and retail displays utilize directional recessed wash lighting for vertical surface illumination.
Retrofit installation expands most quickly, with new construction retaining value concentration through specification-grade procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The recessed lighting industry traces its modern specification-grade roots to German engineering traditions of precision metalwork and thermal management, later amplified by North American commercial construction standards and Asian LED module manufacturing scale.
Germany
Renovation cycles across Frankfurt and Munich office portfolios accelerate luminaire replacement under Ecodesign enforcement. The EU Green Deal's tightening efficacy thresholds compress specification windows, converting deferred maintenance into active procurement. Berlin-Brandenburg clusters concentrate specification-grade housing production for pan-European distribution.
United States
Commercial real estate developers in Texas and Florida prioritize ceiling-preserving retrofit installations over structural demolition. The Inflation Reduction Act's commercial building energy efficiency tax provisions influence capital allocation toward LED upgrade projects. Chicago and Atlanta distribution hubs anchor specification-grade fixture logistics for national contractor networks.
France
ANSM-aligned building efficiency regulators tighten ecotoxicity disclosure requirements for luminaire components ahead of 2027 enforcement. Paris design hotels command premium positioning through architectural-grade tunable-white specification. Île-de-France commercial development pipelines concentrate volume where daylight harvesting mandates embed fixture criteria.
China
MIIT industrial policy supports domestic LED engine manufacturing scale for export-oriented fixture assembly. Yangtze River Delta clusters dominate die-cast aluminum housing production and LED driver component supply. Shenzhen and Dongguan electronics corridors concentrate smart lighting firmware development for connected control platforms.
Italy
Milan hospitality and luxury residential verticals sustain demand for architectural-grade trim systems with premium positioning. Heritage building applications in Rome and Florence report residual halogen demand where dimmer compatibility constraints limit LED substitution. Lombardy manufacturing clusters specialize in decorative recessed formats for European export markets.
Recessed Lighting Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the recessed lighting value chain, creating a tiered structure where integrated manufacturing commands specification-grade positioning while assembly-focused brands compete on retrofit volume. The vendor base fragments across housing fabricators, LED engine suppliers, and control system integrators with divergent certification burdens. Three strategic archetypes dominate: vertically integrated lighting conglomerates with captive LED production, specialized architectural fixture houses with deep designer relationships, and scale-driven retrofit brands with distributor channel density. Competitive intensity centers on M&A activity to secure LED engine supply and strategic partnerships to embed smart control compatibility.
Among North American specification channels, Eaton (Halo) and Acuity Brands occupy positions representing integrated electrical infrastructure and deep distributor network archetypes respectively. WAC Lighting exemplifies the architectural-grade specialist tier with concentrated presence in hospitality and luxury residential verticals. These three anchors illustrate how competitive positioning diverges between scale-driven retrofit penetration and premium-tier specification authority.
| Leading Market Players |
|---|
| Eaton (Halo) |
| WAC Lighting |
| Philips (Signify) |
| RC Lighting |
| Nora Lighting |
| Acuity Brands |
| Lithonia Lighting |
| TORCHSTAR |
| Cree Lighting |
| Others |
Value Chain & Pricing Dynamics
Commercial real estate developers and specification-grade fixture procurement teams command pricing leverage through consolidated project volumes, compressing margin capture for mid-tier assemblers while rewarding vertically integrated suppliers with validated Ecodesign documentation libraries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates architectural-grade specification houses from distributor-channel retrofit brands and commodity assemblers. Price differentiation hinges on CE marking tier and thermal management certification, with German public sector procurement gates favoring suppliers with pre-validated compliance documentation. Cost compression in the economy tier is intensifying because die-cast aluminum housing volatility exposes assemblers lacking long-term supply agreements. Residential retrofit channels exhibit highest price sensitivity, while hospitality wellness positioning commands premium absorption.
Supply Chain Analysis
Container freight rates from Yangtze River Delta ports to Hamburg and Rotterdam directly influence landed cost structures for European specification-grade brands sourcing finished housings. Manufacturing gravity centers on China for die-cast aluminum housings and LED driver electronics, Germany for precision thermal management components, and Taiwan for semiconductor-grade driver ICs. The supply chain rests on concentrated rare earth phosphor and aluminum billet inputs. Single-source vulnerability in LED driver manufacturing exposes brands to geopolitical disruption. Distribution runs through electrical distributor networks and architect-facing specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recessed lighting market functions as a stable compounder where regulatory-driven replacement cycles under the EU Green Deal generate predictable procurement velocity across European commercial real estate portfolios.
For Market Incumbents: Hedge against margin compression by securing captive LED engine production capacity and accelerating Ecodesign pre-certification ahead of enforcement windows. Threat exposure concentrates in mid-tier retrofit brands with undifferentiated housing supply. Channel control through BIM-integrated specification tools represents the priority defensive lever.
For New Entrants and Emerging Players: Begin with sensor-integrated smart lighting platforms targeting French and German healthcare verticals where cybersecurity certification requirements create incumbent capability gaps. The most penetrable white space sits in circadian programming systems for education facilities. A direct digital specification channel bypassing traditional rep agencies offers viable go-to-market positioning.
For Investors and Strategic Acquirers: Electrical infrastructure conglomerates with existing specification-grade channel access represent the most active acquirer category in this space. Long-term viability over a five-to-ten year horizon rests on software-defined lighting platform ownership rather than hardware margin capture. Target acquisition archetypes include architectural fixture houses with validated designer relationships and embedded control firmware developers. The signal to monitor is DALI-2 protocol adoption velocity as a proxy for addressable smart lighting retrofit volume.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Engine Production | Captures margin pools under tightening EU Ecodesign efficacy mandates. |
| Cybersecurity Certification Investment | Secures market access under emerging EU AI Act firmware validation requirements. |
| BIM-Integrated Specification Tool Launch | Bypasses traditional rep agencies to capture architect project data directly. |
| Sensor-Integrated Platform Development | Addresses German and French daylight harvesting mandate compliance. |
| Architectural Designer Relationship Deepening | Secures master specification template inclusion across multi-building portfolios. |
Study Parameters
Multiple input streams — specification-grade luminaire manufacturer interviews, electrical distributor channel assessments, and regulatory compliance documentation reviews — were reconciled against secondary validation from ECHA substance restriction databases, EU Green Deal enforcement timelines, and commercial building permit filings. Primary fieldwork engaged lighting design consultants, electrical contractor procurement leads, commercial real estate development executives, and facilities maintenance directors across German, French, and North American markets. Secondary sources encompassed CE marking registries, Ecodesign directive implementation reports, and aluminum futures pricing data. Bottom-up project pipeline enumeration and top-down construction spending allocation were triangulated to derive volume estimates.
Data-stream reconciliation across the projection horizon applied segment-specific growth coefficients to modeled LED retrofit penetration, smart controls integration rates, and new commercial construction fixture intensity. Segmentation dimensions encompassed product architecture, installation constraint category, control technology tier, and end-use vertical procurement authority. CAGRs were derived from regression against historical replacement cycle data and regulatory enforcement phase-in schedules. Industry-specific forecast inputs included German building code amendment trajectories and aluminum LME price volatility assumptions.
Caveats apply where Ecodesign enforcement delay, LED driver supply disruption, or cybersecurity certification timeline extension could materially shift the outlook. Forecasts reflect modeling assumptions anchored in stated regulatory implementation schedules and commodity price baselines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Eye-Illuminating Gadgets Market
Lighting
Specialty Lighting Market
Lighting
Industrial OLED Lighting Market
Lighting
Industrial Lighting Cybersecurity Market
Lighting
US Indoor LED Lighting Market
Lighting
High Bay Lighting Market
Lighting
Cleanroom Lighting Market
Lighting
Global Plasma Lamp Market
Lighting
LED Eye Protection Lamp Market
Lighting
High-End Lighting Market
Lighting
Flexible Lighting Foils Market
Lighting
Battery Operated Lights Market
Lighting
Europe Decorative Lighting Market
Lighting
Street and Roadway Lighting Market
Lighting
Global Lamps Market
Lighting
Smart Lighting Market