
 Street and Roadway Lighting Market | 2026-2036
Street and Roadway Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Street and Roadway Lighting Market Analysis
A widening capital-intensity gap between integrated lamp manufacturers and component assemblers is reorganizing competitive tiers in the Street and Roadway Lighting Market. Signify N.V. leverages captive LED chip supply chains to sustain margin advantages across European municipal tenders. Acuity Brands Inc. anchors its position through deep architectural specification relationships in North American commercial roadway projects.
Street and road lighting encompasses pole-mounted luminaires engineered to deliver uniform illuminance measured in lux across vehicular and pedestrian corridors, typically employing die-cast aluminum housings with IP66 ingress protection and correlated color temperatures between 2700K and 5700K. LED product types now command the dominant share of new installations as lumen-per-watt efficiency exceeds legacy high-pressure sodium by roughly two-to-one, while solar technology segments accelerate fastest in off-grid and rural corridor applications where trenching costs prove prohibitive. Smart lighting technology captures expanding margin pools through adaptive dimming and remote monitoring capabilities that reduce energy draw during low-traffic periods.
The U.S. Department of Energy's SSL program and the EU Ecodesign Directive jointly enforce minimum efficacy standards that filter substandard imports from municipal supply chains, while India's Bureau of Energy Efficiency mandates star-labeling for LED street luminaires procured under central government schemes. China's GB standards for road lighting establish photometric performance baselines that shape export competitiveness for Asian manufacturers. Stakeholders must weigh retrofit cycle timing against emerging LiDAR-integrated pole infrastructure that could redefine roadway lighting as a multiservice platform.
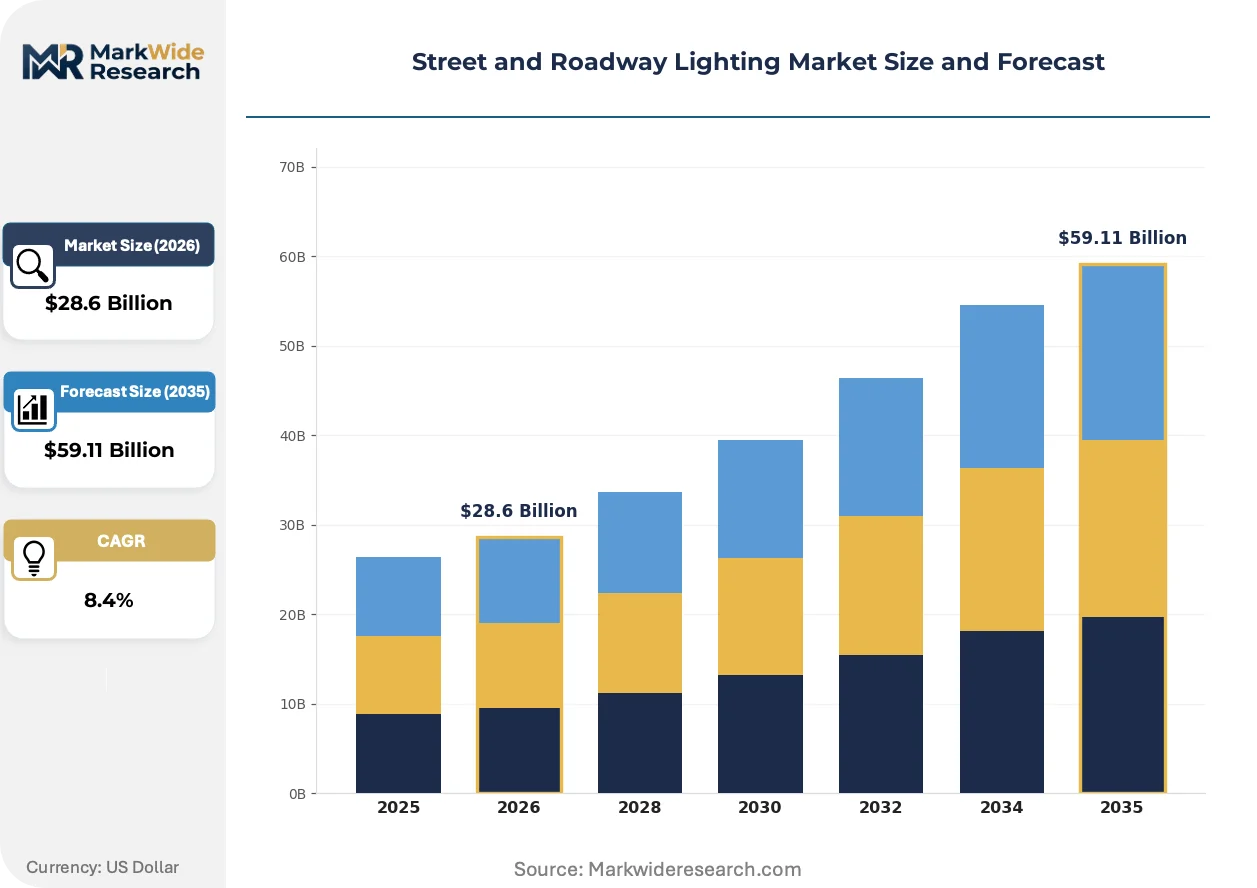
Market Dynamics
The EU Ecodesign Directive's phase-out deadlines for high-pressure sodium luminaires are compressing retrofit timelines across European municipal procurement cycles, forcing asset managers to accelerate capital deployment toward LED infrastructure before legacy stock depletion.
Growth Catalysts
- LED efficacy thresholds:The U.S. Department of Energy's SSL program mandates minimum lumen-per-watt performance that eliminates substandard imports from municipal supply chains, redirecting procurement toward qualified domestic and regional manufacturers.
- India:Bureau of Energy Efficiency star-labeling requirements for LED street luminaires under central government schemes are standardizing quality tiers and expanding addressable market volume through subsidized urban retrofit programs.
- Smart city infrastructure:Adaptive dimming and remote monitoring capabilities embedded in connected pole systems are capturing margin pools previously allocated to energy utilities, creating recurring revenue attachments for lighting vendors.
Market Restraints
- Aluminum die-casting concentration:IP66-rated housing production clusters in China's Guangdong and Zhejiang provinces create supply vulnerability for European and North American assemblers lacking backward integration into casting operations.
- Trenching economics:Grid-connected installations in rural corridors face prohibitive underground cable costs where rock substrate or permafrost conditions extend civil works budgets beyond lamp hardware expenditure.
- Legacy pole asset life:Existing galvanized steel infrastructure with 25-30 year residual service life delays full-system replacement cycles even where luminaire retrofit is technically optimal.
Strategic Opportunities
- LiDAR-integrated poles:Convergence of roadway illumination with autonomous vehicle sensing infrastructure positions lighting assets as multiservice platforms for traffic management and pedestrian safety analytics.
- Solar-hybrid segments:Off-grid and rural corridor applications where grid extension costs prove prohibitive represent underpenetrated volume for photovoltaic-integrated luminaires with battery storage.
- Performance contracting:Energy Service Company financing models transfer capex burden from municipal balance sheets to vendor-operated infrastructure, accelerating procurement velocity in fiscally constrained jurisdictions.
Industry Challenges
- Photometric engineering talent:Specialized expertise in IESNA-compliant roadway illumination modeling remains concentrated among legacy lighting designers, creating recruitment friction for LED-native manufacturers expanding specification capabilities.
- Legacy control system interoperability:Integration of DALI-2 and Zhaga-compliant connected luminaires with existing photocell and timer-based infrastructure requires protocol bridging hardware that complicates commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Street and Roadway Lighting Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Solar, High Pressure Sodium, Metal Halide Application: Highways, Residential Areas, Commercial Areas, Parks Technology: Smart Lighting, Traditional Lighting, Solar Technology, IoT-Enabled End User: Municipalities, Commercial Developers, Construction Companies, Transportation Authorities |
| Companies Covered | Signify N.V., Acuity Brands Inc., OSRAM GmbH, Hubbell Inc., Eaton Corporation plc, Current Lighting Solutions, LLC, Wolfspeed Inc., General Electric Company, Schréder S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Street and Roadway Lighting Market Emerging Trajectories
Photobiological safety standards and circadian rhythm research are redirecting specification priorities toward tunable white systems and melanopic content metrics, compressing demand for fixed-CCT legacy installations.
Chip-on-board LED architectures with integrated driver electronics are supplanting discrete SMD module designs in high-lumen roadway applications. German and Dutch transport authorities specify these packages for motorway projects requiring 50,000-hour maintenance intervals. The technology is compressing luminaire form factors and reducing thermal management component counts, enabling slimmer pole aesthetics that satisfy urban design review boards.
REACH restrictions on hexavalent chromium surface treatments are eliminating conventional galvanizing processes for pole and bracket fabrication. Finnish and Swedish infrastructure agencies now mandate hot-dip zinc-aluminum-magnesium coatings with superior salt-spray resistance for coastal installations. Manufacturers with captive metal finishing capacity in the Baltic region are securing preferential qualification status in Nordic municipal tenders.
Municipal procurement offices are consolidating vendor relationships through framework agreements that bundle luminaire supply with 10-year maintenance and energy performance guarantees. British and Irish local authorities pioneered this bundled contracting structure, which transfers lumen depreciation risk to manufacturers and displaces traditional unit-price purchasing. The model concentrates award volume among suppliers with in-house field service organizations and remote monitoring platforms.
Street and Roadway Lighting Market Segmentation
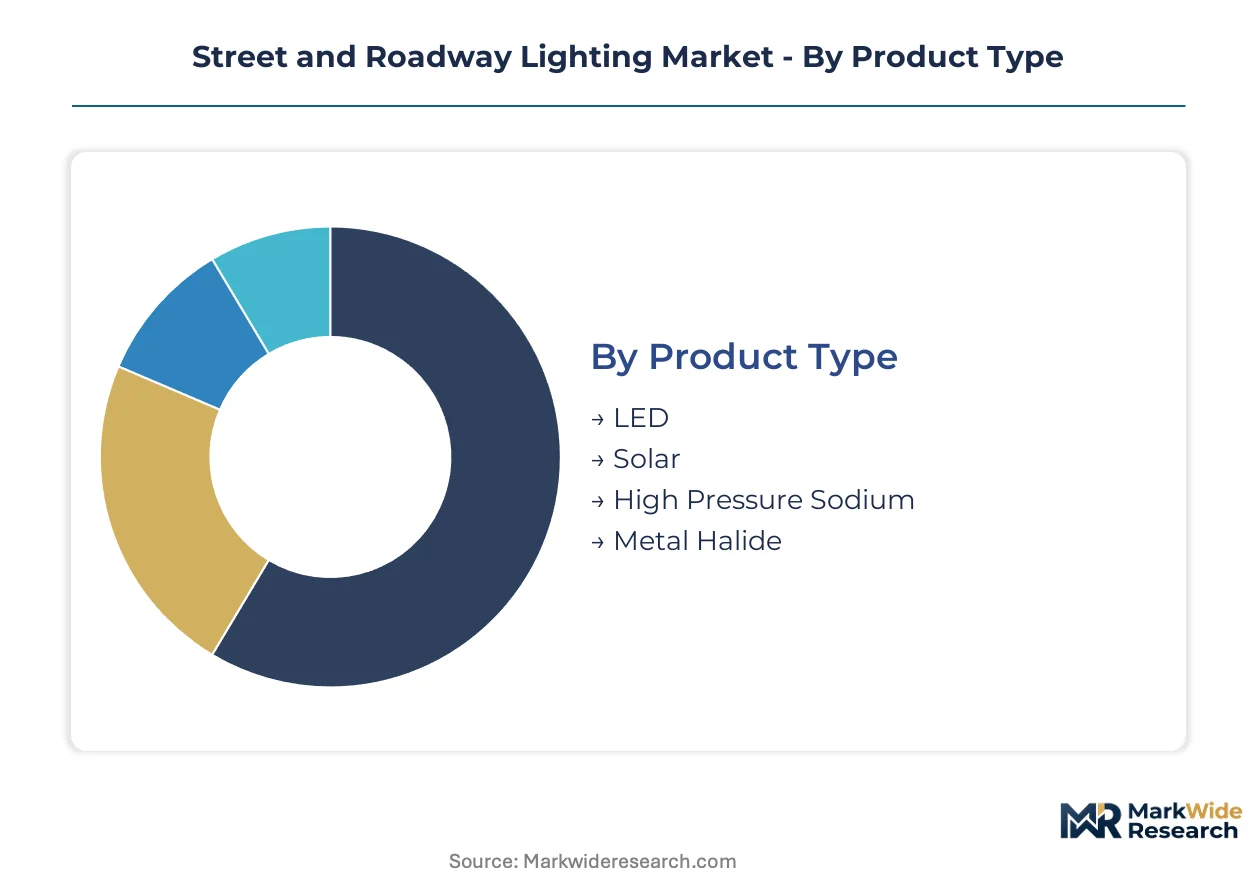
Segmentation in the Street and Roadway Lighting Market exposes divergent substitution pressures across technology generations. Product type splits reveal where LED conversion economics override legacy asset depreciation schedules, while application and end-user dimensions illuminate procurement authority fragmentation.
Product Type:
LED technology exerts accelerating substitution pressure on legacy lamp architectures, compressing residual value in installed high-pressure sodium bases and forcing premature retirement decisions.
- LED:Solid-state luminaires employing chip-on-board or SMD architectures deliver lumen-per-watt performance exceeding legacy sources by roughly two-to-one. Municipal procurement in India and subsidized retrofit programs across European cities concentrate demand volume for qualified products under Bureau of Energy Efficiency star-labeling and EU Ecodesign Directive compliance frameworks.
- Solar:Photovoltaic-integrated luminaires with lithium-ion or LiFePO4 battery storage eliminate trenching costs in rural corridors where rock substrate or permafrost conditions inflate civil works budgets. Off-grid installations in India's smart city peripheries and remote Nordic municipalities anchor emerging demand clusters.
- High Pressure Sodium:Legacy discharge lamps with 100-150 lm/W efficacy face regulatory phase-out timelines under EU Ecodesign Directive mandates.
- Metal Halide:Ceramic and quartz halide sources retain niche presence in color-critical applications requiring high CRI performance.
LED anchors the volume base while Solar gains share at the steepest rate.
Application:
Cost tier differentiation separates premium specification corridors from standardized volume deployments across municipal contract tiers.
- Highways:High-lumen motorway installations demand 50,000-hour maintenance intervals and IESNA-compliant photometric modeling. German and Dutch transport authorities specify chip-on-board architectures with integrated drivers, compressing form factors for aesthetic review compliance.
- Commercial Areas:Mixed-use districts with pedestrian priority zones drive tunable white and circadian-optimized specifications. British and Irish local authorities bundle 10-year performance guarantees with luminaire supply, transferring lumen depreciation risk to vendors.
- Residential Areas:Neighborhood collector roads and cul-de-sac networks prioritize cost-efficient LED retrofit over smart capability deployment.
- Parks:Recreational pathway illumination emphasizes wildlife-friendly amber spectra and motion-activated dimming protocols.
Highways concentrate procurement value while Commercial Areas expand most quickly through bundled service contracting.
Technology:
Customer type stratification separates utility-scale infrastructure managers from site-specific developers seeking feature differentiation.
- Smart Lighting:Connected pole systems with adaptive dimming, remote monitoring, and DALI-2 or Zhaga-compliant control interfaces capture recurring revenue attachments. Municipalities with in-house field service organizations and remote monitoring platforms consolidate vendor relationships through framework agreements.
- IoT-Enabled:Sensor-integrated luminaires supporting traffic analytics, air quality monitoring, and pedestrian safety applications position lighting assets as multiservice platforms. LiDAR convergence for autonomous vehicle infrastructure drives specification in forward-looking transport authority tenders.
- Traditional Lighting:Photocell and timer-based control systems persist in fiscally constrained jurisdictions with legacy commissioning protocols.
- Solar Technology:Standalone photovoltaic-battery systems serve grid-extension-prohibitive locations with autonomous operation requirements.
Traditional Lighting retains installed base dominance while IoT-Enabled climbs the fastest through infrastructure convergence mandates.
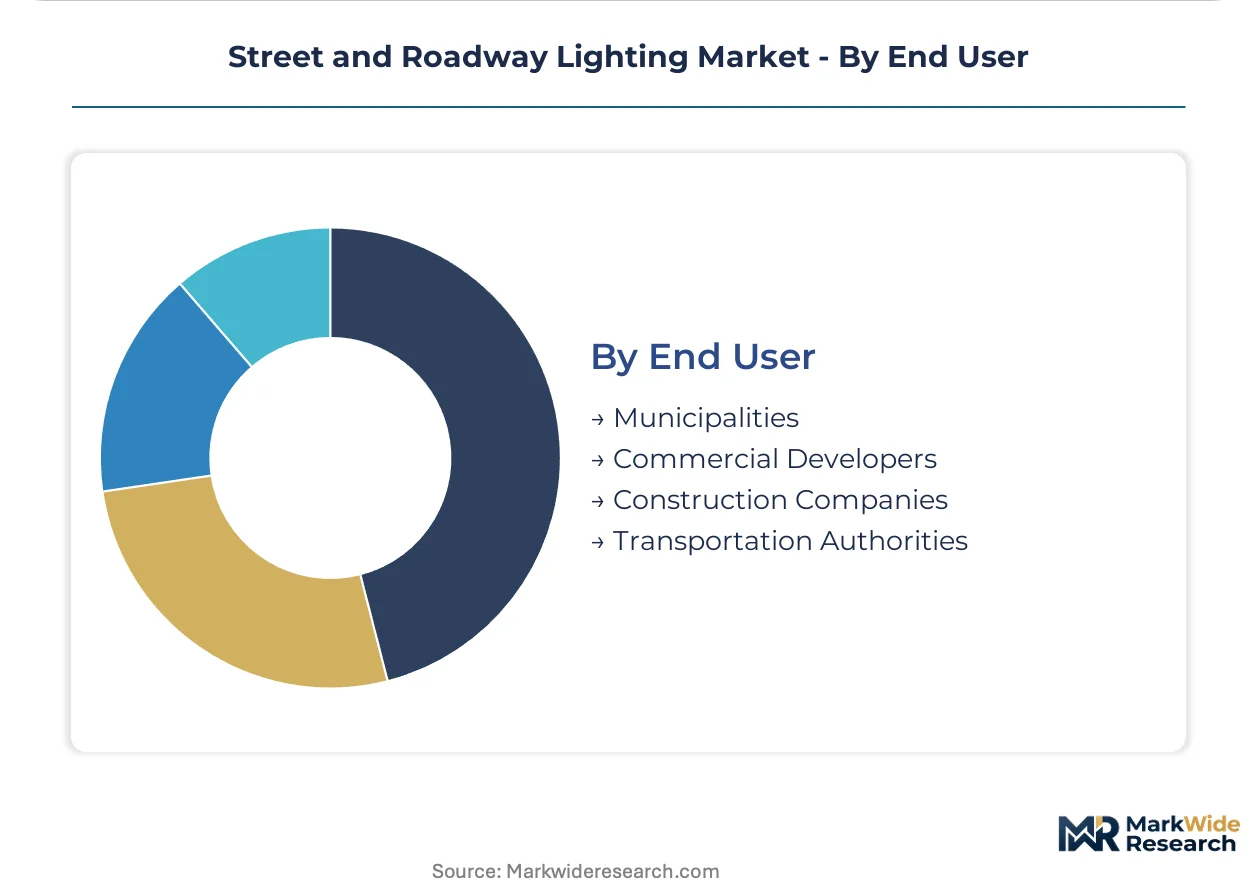
End User:
Supply concentration in aluminum die-casting and driver electronics shapes procurement leverage across buyer categories with divergent technical sophistication.
- Municipalities:City and county public works departments with consolidated street lighting inventories negotiate framework agreements bundling hardware, installation, and long-term maintenance. India's central government schemes and EU municipal procurement directives standardize quality tiers through mandatory certification.
- Transportation Authorities:State and national road agencies with motorway portfolios specify chip-on-board architectures for high-lumen, long-life applications. German, Dutch, and Nordic agencies mandate salt-spray-resistant coatings and 50,000-hour maintenance intervals.
- Commercial Developers:Private site infrastructure builders prioritize aesthetic compliance with urban design review boards over lifecycle cost optimization.
- Construction Companies:Project-based contractors seek unit-price purchasing flexibility with minimal specification burden.
Municipalities anchor procurement volume while Transportation Authorities expand specification influence through standard-setting authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exhibits the highest demand elasticity as price-sensitive municipal budgets prioritize subsidized LED retrofits, while Germany and the Netherlands show inelastic specification demand where transport authorities mandate premium chip-on-board architectures regardless of unit cost.
United States
Municipal procurement offices in California and Texas are consolidating vendor relationships through 10-year performance guarantee frameworks. The Department of Energy's SSL program enforces minimum efficacy standards that filter substandard imports from supply chains. Chicago and New York City public works departments anchor volume demand for smart pole infrastructure with adaptive dimming capabilities.
Germany
Autobahn expansion projects and urban smart city initiatives in Berlin and Munich drive specification-grade demand. The Federal Motor Transport Authority (KBA) influences roadway safety standards that cascade into lighting photometric requirements. Bavarian transport agencies mandate 50,000-hour maintenance intervals for motorway luminaires, compressing supplier qualification timelines.
India
Urban smart city missions in Delhi, Mumbai, and Bangalore are accelerating roadway illumination upgrades across 100 designated municipalities. The Bureau of Energy Efficiency mandates star-labeling for LED street luminaires procured under central government schemes. Gujarat and Maharashtra industrial clusters host die-casting operations supplying IP66-rated housings to domestic assemblers.
Netherlands
Rijkswaterstaat motorway specifications set European benchmarks for chip-on-board LED architectures with integrated drivers. The EU Ecodesign Directive phase-out deadlines compress retrofit timelines across municipal procurement cycles. Eindhoven's lighting design heritage concentrates photometric engineering talent that shapes regional specification authority.
China
Domestic demand from tier-one city smart infrastructure programs in Shanghai and Shenzhen runs parallel to export manufacturing scale. GB standards for road lighting establish photometric performance baselines that shape export competitiveness. Guangdong and Zhejiang province die-casting clusters create supply concentration for IP66-rated housing production.
Street and Roadway Lighting Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with captive LED chip supply chains separating margin-sustainable integrated manufacturers from component-dependent assemblers. The market structures around three tiers: multinational lighting conglomerates with backward integration into semiconductor supply, regional specialists with deep municipal specification relationships, and volume-driven fabricators competing on unit economics. Dominant competitive moves include framework agreement consolidation bundling hardware with long-term maintenance obligations, and strategic partnerships with energy service companies transferring capex burden from municipal balance sheets.
Among European-anchored lighting conglomerates, Signify N.V. and Schréder S.A. occupy positions representing integrated supply chain archetypes, while Acuity Brands Inc. exemplifies the North American specification-relationship model. These three companies anchor competitive positioning across divergent procurement authority structures, with each representing distinct approaches to municipal tender capture and technology platform deployment.
| Leading Market Players |
|---|
| Signify N.V. |
| Acuity Brands Inc. |
| OSRAM GmbH |
| Hubbell Inc. |
| Eaton Corporation plc |
| Current Lighting Solutions, LLC |
| Wolfspeed Inc. |
| General Electric Company |
| Schréder S.A. |
| Others |
Supply Flow & Price Mechanics
Die-cast aluminum housing capacity utilization above 85 percent in China's Guangdong and Zhejiang provinces compresses cost floors for IP66-rated luminaire enclosures while simultaneously concentrating bargaining power among three dominant casting clusters. This scale geometry forces European and North American assemblers to absorb margin compression or pursue captive foundry investments, reshaping competitive tiering across municipal tender markets.
Pricing Analysis
Extended maintenance and energy performance guarantee contracts now drive lifetime value capture, with British and Irish local authorities pioneering 10-year bundled frameworks that transfer lumen depreciation risk to manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates chip-on-board motorway specifications from residential retrofit commodity tiers, with certification grade under EU Ecodesign Directive and Bureau of Energy Efficiency star-labeling acting as primary price differentiation levers. Pricing pressure stems from aluminum ingot cost volatility and subsidized procurement in India's urban smart city missions. Municipalities in fiscally constrained jurisdictions exhibit highest price sensitivity, while German and Dutch transport authorities demonstrate lowest sensitivity due to mandated 50,000-hour maintenance intervals.
Supply Chain Analysis
Inventory lead times for LED driver electronics have extended from 8 to 14 weeks as semiconductor foundry capacity prioritizes automotive and consumer electronics allocations. Supply concentrates in China for die-cast aluminum housings, Taiwan for LED chip fabrication, and Germany for precision driver components, creating multi-node dependency chains. Raw material inputs span aluminum ingot, gallium nitride wafers, and lithium-ion battery cells for solar-hybrid segments. Single-source vulnerability in Guangdong casting clusters poses structural risk given REACH restrictions on hexavalent chromium surface treatments eliminate alternative European galvanizing pathways. Distribution runs through municipal procurement framework agreements and energy service company financing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as procurement authority splits between consolidated municipal framework agreements and project-based commercial developer specifications, with smart city infrastructure mandates creating niche entry points for specialized platform vendors.
For Market Incumbents: Shield specification-grade positioning by deepening captive LED chip supply chains and securing preferential qualification status in Nordic municipal tenders through hot-dip zinc-aluminum-magnesium coating investments. Acquire field service organizations to support 10-year performance guarantee bundling, neutralizing emerging competition from component assemblers lacking maintenance infrastructure. For New Entrants and Emerging Players: Differentiate on LiDAR-integrated pole convergence for autonomous vehicle infrastructure, targeting transportation authority tenders in Germany and the Netherlands where specification influence outpaces price sensitivity. Penetrate India's smart city peripheries through solar-hybrid luminaire offerings that eliminate trenching cost barriers, leveraging Bureau of Energy Efficiency star-labeling as qualification pathway. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with backward semiconductor control over component-dependent assemblers facing margin compression. Long-term viability rests on pole infrastructure evolving into multiservice platforms rather than standalone illumination assets. Watch LiDAR sensor integration mandates in forward-looking transport authority specifications as inflection indicator for platform value capture.| Strategic Initiative | Industry Significance |
|---|---|
| Framework Agreement Consolidation | Bundles luminaire supply with 10-year maintenance obligations, transferring lumen depreciation risk to vendors. |
| Captive Foundry Investment | Backward integration into die-cast aluminum housing production neutralizes Guangdong supply concentration vulnerability. |
| LiDAR Platform Convergence | Positions lighting assets as multiservice infrastructure for German and Dutch autonomous vehicle sensing requirements. |
| Energy Service Company Partnership | Transfers municipal capex burden to vendor-operated infrastructure, accelerating procurement in fiscally constrained jurisdictions. |
| Photometric Engineering Acquisition | Addresses IESNA-compliant roadway modeling talent scarcity concentrated among legacy lighting designers. |
Methodological Framework
Initial hypotheses were tested against primary input from municipal public works directors, transportation authority specification engineers, lighting manufacturer product managers, and energy service company financing officers, and refined through secondary validation against EU Ecodesign Directive implementation timelines, Bureau of Energy Efficiency procurement databases, U.S. Department of Energy SSL program efficacy standards, and municipal tender documentation from German, Dutch, British, and Indian authorities. Bottom-up luminaire shipment estimates were triangulated against top-down infrastructure investment flows.
Variance decomposition across technology substitution rates, regulatory phase-out timelines, and municipal budget elasticity shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, application corridor tier, technology generation, and end-user procurement authority structure. CAGRs were derived from fitted diffusion curves for LED substitution and smart capability attachment rates, with aluminum ingot price indices and semiconductor foundry utilization serving as industry-specific forecast inputs.
Material uncertainties — regulatory deadline acceleration, municipal fiscal stress, and autonomous vehicle infrastructure mandate timing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding retrofit cycle timing and technology cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
LED Eye Protection Lamp Market
Lighting
LED Solar Lighting Market
Lighting
Photography Light Box Market
Lighting
Global Lighting Control System Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
North America Street Lighting Market
Lighting
Cleanroom Lighting Market
Lighting
Smart Lighting Market
Lighting
Lamps and Lighting Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
GCC Smart Lighting Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Solar Column Headlight Market
Lighting
Wireless Lighting Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Intelligent Lighting Controls Market