
 Fluorescent Lighting Market | 2026-2036
Fluorescent Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorescent Lighting Market Intelligence
The integration of smart controls and maintenance services into lighting contracts is restructuring how fluorescent systems are procured and managed. Philips Lighting leverages its extensive distribution network to serve both new installation and replacement markets. Osram specializes in specialty lamps for automotive and industrial applications, creating a distinct market position. Schneider Electric competes by integrating lighting controls within its broader building automation and energy management platforms.
Fluorescent lighting generates visible light by using electricity to excite mercury vapor in a glass tube, producing short-wave ultraviolet light. A phosphor coating on the lamp's interior converts this UV light to visible illumination, designed for efficient area lighting. Linear tubes represent the largest product segment, installed widely across commercial spaces and industrial facilities due to their operational efficiency. Compact fluorescent lamps are now concentrated in specific replacement applications, facing pressure in the residential uses segment.
Regulations such as the EU's RoHS directive and the US EPA's disposal guidelines for mercury-containing products directly impact lamp design and end-of-life management. Concurrently, China's energy efficiency standards under its dual carbon goals influence the acceptable performance benchmarks for new installations. Stakeholders must navigate the transition toward LED alternatives while managing the extensive installed base of fluorescent systems requiring maintenance and replacement.
Market Dynamics
The fluorescent lighting market is shaped by the structural tension between sustained replacement demand from a vast installed base and accelerating regulatory pressures to phase out mercury-containing products. This dynamic forces a bifurcation of strategy between servicing legacy systems and managing a transition to alternatives.
Growth Catalysts
- Mandatory Replacement Cycles:The EU's RoHS directive, by phasing out specific mercury-containing lamps, creates a non-discretionary replacement demand, compelling facility upgrades and sustaining sales of compliant fluorescent or alternative systems.
- Infrastructure Development:Large-scale commercial and industrial construction projects, particularly in India, continue to specify linear fluorescent lighting for its cost-effectiveness in illuminating large areas, providing a consistent demand stream.
- Legacy System Maintenance:The enormous installed base of fluorescent fixtures in existing commercial buildings and industrial plants worldwide requires a steady supply of replacement lamps and ballasts, forming a stable, recurring revenue foundation.
Market Restraints
- LED Substitution Threat:The continuous improvement in LED efficacy and decline in production costs present a direct and powerful substitution threat, progressively eroding the market share and long-term viability of fluorescent technology.
- Regulatory Compliance Costs:End-of-life management is complicated by regulations such as the US EPA's disposal guidelines for mercury, which increase the total cost of ownership and administrative burden for end-users.
- Input Material Volatility:The manufacturing of high-quality phosphors relies on rare earth elements, whose price volatility and supply chain concentration can introduce significant cost pressures and margin instability for lamp producers.
Strategic Opportunities
- Service Model Innovation:Developing lighting-as-a-service (LaaS) contracts that bundle lamp supply, maintenance, and recycling services offers a pathway to secure long-term revenue streams from large institutional and commercial clients.
- Niche Application Focus:Concentrating on specialty fluorescent lamps for applications such as horticulture, medical phototherapy, and UV-C disinfection provides a defensible market segment with less direct competition from general-purpose LEDs.
- Targeted Geographic Expansion:Focusing on price-sensitive commercial and public sector projects in developing economies across Africa and Southeast Asia can capture demand where upfront capital cost remains the primary purchasing criterion.
Industry Challenges
- Supply Chain Restructuring:Manufacturers must reconfigure production lines and supply chains to cease production of lamps banned under new environmental standards, a process that requires significant capital investment and operational adjustment.
- Legacy System Integration:Ensuring compatibility between modern, energy-efficient electronic ballasts and older building automation systems can present significant technical hurdles, leading to project delays and unexpected costs for retrofitters.
- Navigating Patchwork Regulations:Adhering to a complex and divergent set of energy efficiency and material standards, such as China's dual carbon goals and California's Title 24, complicates global product development and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorescent Lighting Market |
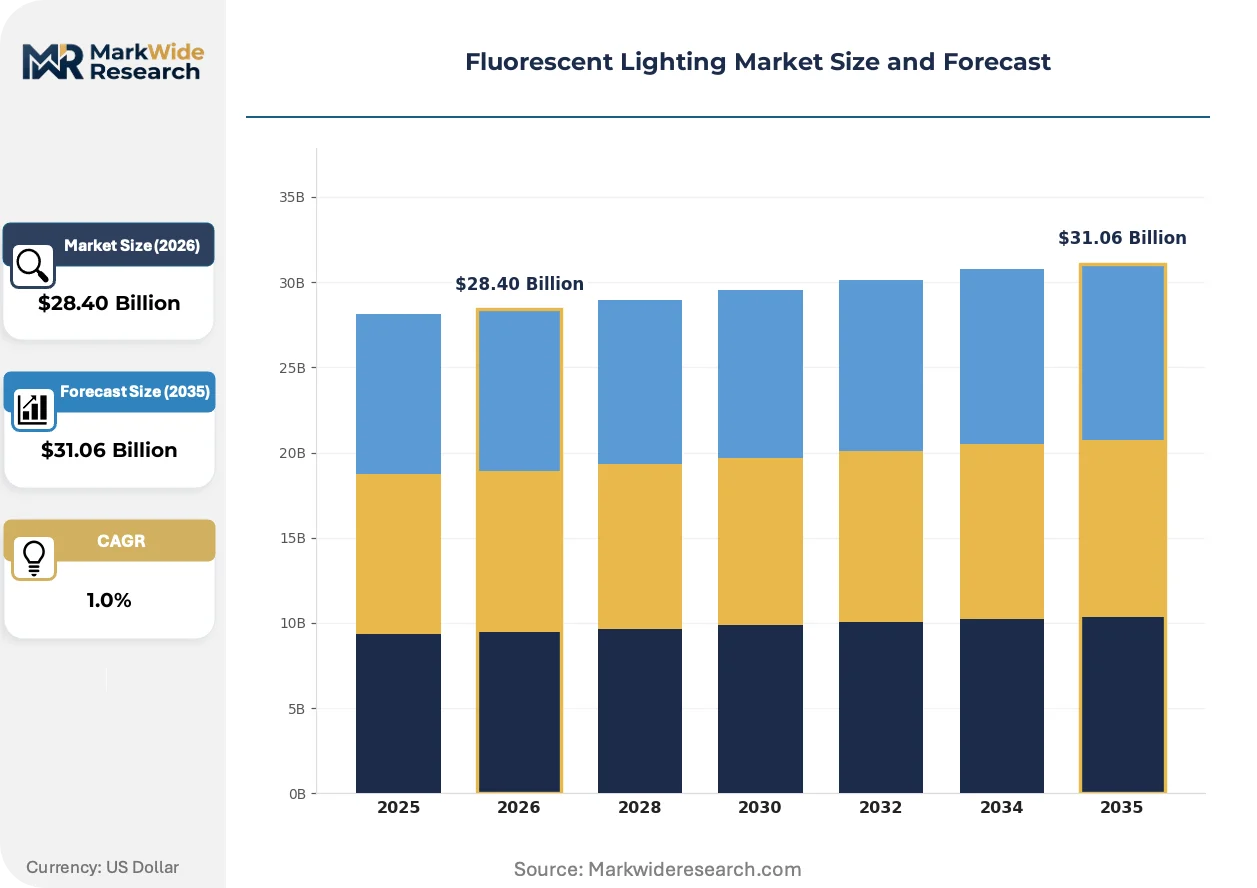
| Market Size in 2026 | $28.40 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Tubes, Compact Fluorescent Lamps, High-Intensity Discharge, Specialty Lamps Application: Commercial Spaces, Industrial Facilities, Outdoor Lighting, Residential Uses Technology: Ballast Type, Integrated, Dimmable, Non-Dimmable End User: Retail Chains, Office Buildings, Manufacturing Units, Educational Institutions |
| Companies Covered | Sylvania, Narva, Philips Lighting, Facom, Neutral, Osram, Schneider Electric, Orbitec, GE Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorescent Lighting Market Strategic Shifts & Innovations
The market is defined by a dual-track evolution. One path focuses on managing the end-of-life for a massive installed base under new environmental rules, while the other pursues niche technological advancements to extend the relevance of fluorescent systems in specific applications.
High-frequency electronic ballasts enhance the energy efficiency, eliminate flicker, and extend the operational life of fluorescent lamps. Commercial and industrial facility managers are adopting these ballasts for retrofits where a full fixture replacement is not yet economically justified. This incremental upgrade technology is rewriting the economic calculus for rip-and-replace decisions, prolonging the viability of existing fluorescent infrastructure.
An expansion of the EU's RoHS directive now restricts most common T5 and T8 linear fluorescent lamps from the market. This regulatory action compels a large-scale transition, dramatically accelerating the shift toward LED tube replacements or entirely new LED fixtures. The commercial and industrial sectors are most impacted, facing mandated lighting system overhauls to ensure compliance across their European facilities.
A shift toward performance-based service contracts is altering how lighting is procured in large-scale commercial real estate. This model moves away from the transactional sale of lamps and fixtures, substituting it with long-term agreements that bundle maintenance, upgrades, and energy management. This trend is most visible in North America and Western Europe, where property owners seek to outsource non-core facility operations.
Fluorescent Lighting Market Segmentation
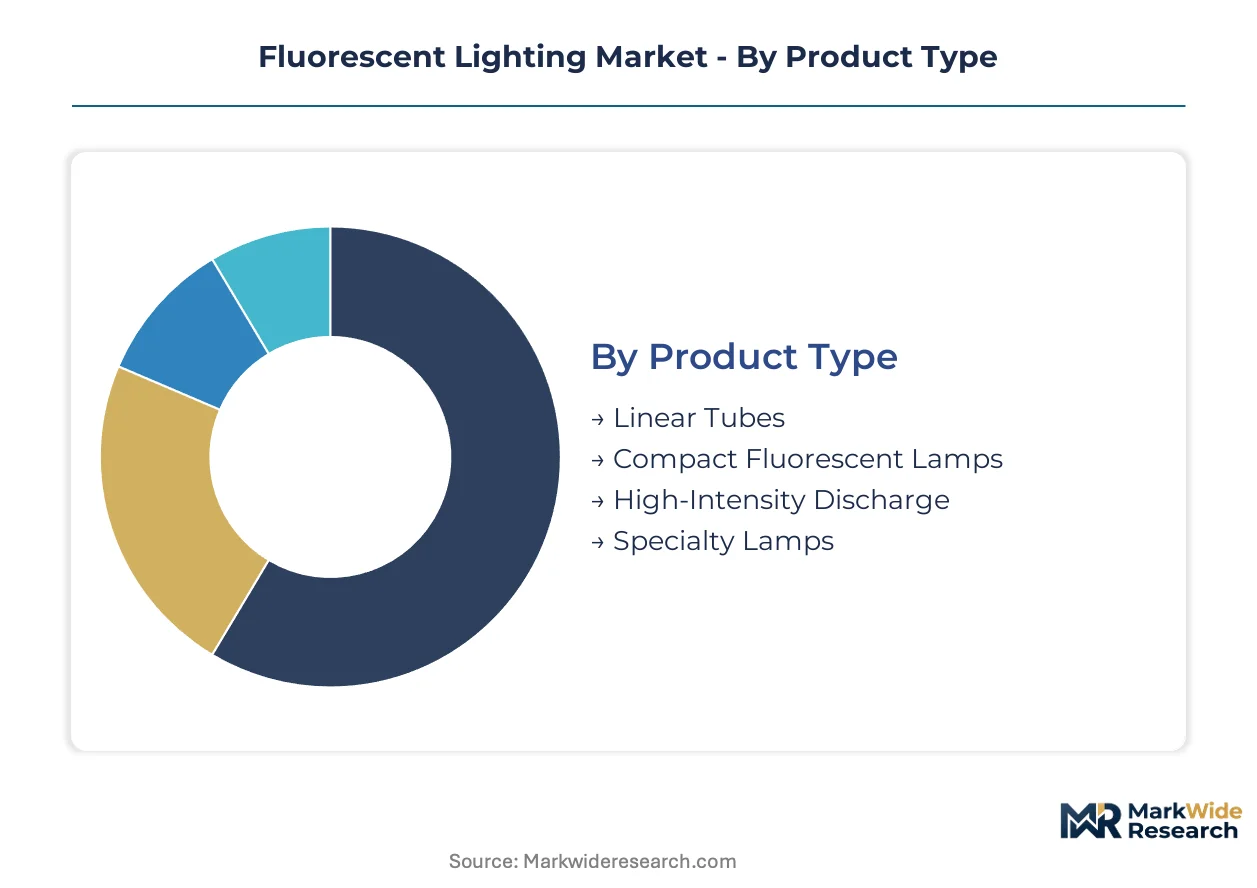
The Fluorescent Lighting Market segmentation highlights how distinct product types and applications drive varied replacement cycles and technology adoption patterns. Understanding these segments allows manufacturers to tailor product development and service strategies amidst evolving regulatory landscapes. This granular view clarifies where sustained demand for fluorescent systems persists.
Product Type:
The product type segmentation reveals how different lamp designs are impacted by ongoing replacement cycles and regulatory phase-outs, dictating their market longevity. Facilities managing extensive legacy infrastructure often prioritize direct lamp-for-lamp replacements to defer full fixture overhauls. This approach sustains demand for specific fluorescent lamp types even as new installations shift towards LED.
- Linear Tubes:These lamps generate visible light by exciting mercury vapor within a glass tube, producing UV light converted by phosphor. They form the largest product segment, driven by replacement demand in commercial spaces and industrial facilities seeking cost-effective area illumination.
- Compact Fluorescent Lamps:CFLs integrate the ballast and lamp into a single unit, designed for screw-in bases. Demand concentrates in specific residential and small commercial replacement applications, particularly where older incandescent fixtures still require compatible lamp forms.
- High-Intensity Discharge:HID lamps provide high light output for large areas, often used in sports arenas and street lighting.
- Specialty Lamps:These include fluorescent lamps for horticulture, medical phototherapy, and UV-C disinfection, serving niche applications with specific spectral requirements.
Linear Tubes sit at the top of the volume ranking, with Specialty Lamps climbing the fastest.
Application:
The application segmentation highlights where fluorescent lighting solutions deliver the most significant value propositions based on illumination requirements and operational scale. Different end-use environments exhibit distinct purchasing patterns and maintenance schedules for their lighting infrastructure. This influences the types and quantities of fluorescent lamps procured for ongoing operations.
- Commercial Spaces:This segment includes offices, retail stores, and public buildings, where linear fluorescent tubes provide efficient, uniform illumination over large areas. Demand is primarily driven by scheduled replacements and energy efficiency upgrades in existing structures across Europe and North America.
- Industrial Facilities:Warehouses, factories, and manufacturing plants utilize robust fluorescent lighting for high-ceiling environments and task-specific illumination. Sustained demand comes from maintaining operational continuity and complying with worker safety standards in India's expanding industrial sector.
- Outdoor Lighting:Fluorescent lamps see limited use in outdoor applications, primarily for specific signage or sheltered public areas.
- Residential Uses:This segment now primarily focuses on replacement compact fluorescent lamps in specific legacy fixtures, facing substantial displacement by LED alternatives.
Commercial Spaces and Industrial Facilities collectively define the primary demand centers for fluorescent lighting solutions.
Technology:
The technology segmentation emphasizes the critical role of ballast types and control mechanisms in optimizing fluorescent lamp performance and energy consumption. Advancements in these components directly impact the lifespan, flicker reduction, and dimming capabilities of fluorescent systems. Facilities prioritize technologies that offer improved energy efficiency and reduced maintenance burdens.
- Ballast Type:Ballasts regulate the current to fluorescent lamps, ensuring stable operation. Electronic ballasts enhance energy efficiency and eliminate flicker, driving retrofits in commercial and industrial facilities not yet ready for full LED conversion.
- Integrated:Integrated fluorescent lamps combine the lamp and ballast into a single unit, simplifying installation for specific replacement scenarios. These are often compact fluorescent lamps designed for direct incandescent fixture replacements.
- Dimmable:Dimmable fluorescent systems allow for adjustable light output, offering energy savings and enhanced user control in office environments.
- Non-Dimmable:These systems provide constant light output, representing the standard configuration for most basic fluorescent installations in industrial and commercial settings.
The evolution of these technologies directly influences operational efficiency and user experience in fluorescent lighting systems.
End User:
The end-user segmentation examines the varied requirements and procurement strategies of different institutional and commercial clients for fluorescent lighting. Each user category possesses unique operational hours, budget constraints, and aesthetic preferences influencing their lighting choices. This segmentation reveals how maintenance contracts and bulk purchasing agreements are structured.
- Retail Chains:These establishments require consistent, high-quality illumination to showcase products and enhance customer experience. Replacement cycles are often driven by store renovation schedules and energy efficiency mandates, particularly across North American retail operations.
- Office Buildings:Offices demand flicker-free, comfortable lighting for prolonged periods, impacting employee productivity and well-being. Facility managers prioritize lamps with extended lifespans and good color rendering, driving demand for compliant linear tubes in European office complexes.
- Manufacturing Units:These facilities require durable, bright, and often specialized lighting for safety and detailed work, sustaining demand for robust linear fluorescent systems.
- Educational Institutions:Schools and universities utilize fluorescent lighting for classrooms and common areas, balancing energy efficiency with budget constraints for replacements.
Each end-user segment presents distinct procurement cycles and maintenance requirements for fluorescent lighting solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's rapid infrastructure development drives significant new demand for fluorescent lighting, contrasting sharply with Europe's market, which is largely shaped by mandatory replacement cycles due to regulatory changes. This dual dynamic highlights the divergent forces influencing regional market trajectories. Each region navigates unique challenges and opportunities in managing its installed base and transitioning to modern lighting solutions.
India
Infrastructure development and large-scale commercial projects in India sustain consistent demand for linear fluorescent lighting due to its cost-effectiveness in illuminating vast areas. The country's energy efficiency standards, supported by initiatives like the PLI scheme, encourage the adoption of more efficient lighting systems for new installations. Major commercial hubs like Mumbai and Delhi continue to drive significant procurement within the construction sector.
Germany
Germany's market is predominantly influenced by the EU's RoHS directive, which mandates the phase-out of certain mercury-containing lamps, creating non-discretionary replacement demand. Facility managers in industrial and commercial sectors prioritize compliant fluorescent or alternative systems for legacy infrastructure maintenance. The industrial regions, such as the Ruhr Valley, face significant system overhauls to ensure regulatory adherence.
United States
The United States experiences sustained demand from its extensive installed base of fluorescent fixtures in commercial buildings and industrial plants. US EPA's disposal guidelines for mercury-containing products increase the total cost of ownership and administrative burdens for end-users. Large metropolitan areas like New York City and Chicago see continuous activity in retrofitting older commercial real estate.
China
China's energy efficiency standards, outlined under its dual carbon goals, influence acceptable performance benchmarks for new fluorescent installations, pushing for higher efficiency. The market is characterized by a strategic tension between servicing legacy systems and managing a transition to alternatives. Commercial and industrial development in the Yangtze River Delta region drives both new installations and replacement demand.
Fluorescent Lighting Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, creating a tiered market structure. The market exhibits a tension between traditional lamp producers and companies integrating lighting into broader building management ecosystems. Strategic archetypes include diversified lighting solution providers, specialized lamp manufacturers, and integrated building automation firms. Dominant competitive moves involve service model innovation and targeted niche application focus.
Diversified lighting solution providers, such as Philips Lighting, leverage extensive distribution networks to serve both new installation and replacement markets across various geographies. Specialists in specific application areas, like Osram, focus on specialty lamps for automotive and industrial uses, carving out distinct market positions. Schneider Electric exemplifies companies that integrate lighting controls within broader building automation and energy management platforms, providing comprehensive solutions for commercial and industrial clients.
| Leading Market Players |
|---|
| Sylvania |
| Narva |
| Philips Lighting |
| Facom |
| Neutral |
| Osram |
| Schneider Electric |
| Orbitec |
| GE Lighting |
| Others |
Cost & Logistics Intelligence
Skilled manufacturing labor concentrations in Asian economies, particularly China, create labor-cost differentials that influence pricing-tier spreads across fluorescent lighting products. This dynamic impacts both lamp production and component sourcing for electronic ballasts.
Pricing Analysis
Capacity additions in Asian manufacturing hubs are reshaping price floors for standard linear fluorescent tubes. The dominant pricing structure for lamps remains per-unit transactional, while service contracts often employ a project-based or long-term agreement model. Price differentiation stems from regulatory compliance, such as RoHS certification, and the inclusion of advanced features like electronic ballasts. Pricing pressure intensifies due to the continuous decline in LED alternative costs. Price-sensitive buyers in developing economies like India and Southeast Asia prioritize upfront cost, while European commercial clients often accept higher prices for compliant, energy-efficient systems.
Supply Chain Analysis
Regulatory certification gating, particularly for mercury content and energy efficiency, significantly shapes the fluorescent lighting supply chain. Geographic supply concentrates heavily in China for lamp manufacturing, with critical raw materials like rare earth elements for phosphors sourced from a few key countries. The supply chain faces structural risk from commodity price volatility, especially for rare earth elements. Downstream distribution runs through established electrical wholesalers, specialized lighting distributors, and direct channels for large commercial and industrial clients, often integrated with maintenance service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, driven by the shift towards higher-value service contracts and niche specialty lamp applications.
For Market Incumbents: To counter accelerating LED substitution, diversified lighting providers must deepen their integration of lighting-as-a-service (LaaS) models, bundling maintenance, and recycling. Reconfiguring production lines to focus on compliant fluorescent lamps for replacement cycles and investing in advanced electronic ballasts will extend relevance. Leveraging existing extensive distribution networks for service delivery represents a critical lever.
For New Entrants and Emerging Players: Technology-first solutions, such as advanced UV-C disinfection lamps or horticulture lighting, offer a defensible wedge into specific market segments. Targeting price-sensitive commercial and public sector projects in developing economies like Africa provides a penetrable entry point. A strong go-to-market angle involves offering bundled energy efficiency upgrades that integrate smart controls with existing fluorescent infrastructure.
For Investors and Strategic Acquirers: Integrated building automation firms are the most active acquirers in this space, seeking to integrate lighting controls into broader energy management platforms. The market maintains long-term viability for the next 5-10 years, sustained by mandatory replacement cycles and niche applications. Acquisition targets should include companies with strong intellectual property in specialty lamps or established service networks for legacy systems. The signal to watch is the pace of new regional mercury bans.
| Strategic Initiative | Industry Significance |
|---|---|
| Service Model Innovation | Secures long-term revenue streams by bundling lamp supply with maintenance and recycling services. |
| Niche Product Development | Creates defensible market segments with specific spectral requirements, less exposed to LED competition. |
| Supply Chain Reconfiguration | Ensures compliance with evolving environmental regulations and mitigates rare earth element supply risks. |
| Geographic Market Entry | Captures demand in developing economies where upfront capital cost remains a primary purchasing criterion. |
| Technology Integration | Enhances energy efficiency and extends the operational life of existing fluorescent infrastructure through electronic ballasts. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and internal databases — were reconciled to construct a comprehensive market view. This involved combining insights from facility managers, lighting engineers, procurement officers, and regulatory experts. Secondary validation drew from industry association reports, government energy efficiency databases, and company financial filings, triangulating data points across various sources.
The analytical framework reconciled historical data with projections across the modeling period, segmenting the market by product type, application, technology, end-user, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, regulatory impact assessments, and technological substitution rates. Key forecast inputs included raw material price forecasts, infrastructure development plans in India, and LED cost curve projections.
The model holds under current regulatory environments and technology adoption rates; deviation in accelerated LED decline or new mercury bans would shift market trajectories. Forecasts reflect these assumptions, acknowledging inherent risk factors. A model refresh is warranted upon material change in global energy efficiency standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Graphene Lighting Market
Lighting
Intelligent Lighting Controls Market
Lighting
Miniature Bulbs Market
Lighting
Art and Museum Lighting Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Connected (Smart) Street Lighting Market
Lighting
Bulb Market
Lighting
Industrial OLED Lighting Market
Lighting
Digital Light Processing Technology Market
Lighting
Smart Lamp Market
Lighting
Specialty Lighting Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Global Work Lights Market
Lighting
Smart Industrial Illumination Market
Lighting
OLED Lightening Panels Market